
 Data Integration Software Market | 2026-2036
Data Integration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Data Integration Software Market Analysis
Enterprise software procurement is tilting toward subscription-based cloud delivery, reshaping how data integration vendors engage Fortune 500 buyers. Microsoft Corporation leverages its Azure ecosystem to embed integration tools within existing enterprise workflows. IBM Corporation anchors its position through hybrid cloud architectures that bridge mainframe systems with modern APIs. Oracle Corporation competes by extending database-native integration capabilities that reduce extract-transform-load latency for large-scale deployments.
Data integration software encompasses tools and platforms that aggregate, transform, and synchronize information across disparate systems using protocols such as RESTful APIs, message queuing, and change data capture at throughput rates exceeding millions of events per second. Its primary purpose is to enable real-time decision-making by establishing consistent, query-ready data pipelines between operational databases, analytics warehouses, and external partner systems. Cloud-based deployment leads in new contract value as organizations retire on-premises middleware, while real-time data processing represents the fastest-expanding use case driven by IoT sensor networks and financial transaction monitoring. API-based integration commands premium pricing due to the engineering intensity of bidirectional schema mapping and protocol translation.
The EU AI Act and GDPR impose strict lineage and consent requirements on automated data flows, compelling vendors to embed audit trails and purpose-limitation controls directly into pipeline orchestration layers. The US Securities and Exchange Commission's climate disclosure rules are forcing finance and manufacturing end users to adopt integration platforms capable of tracing emissions data from operational systems through to regulatory filings. Stakeholders must weigh the trade-off between multi-cloud flexibility and the operational simplicity of single-vendor stacks as data sovereignty requirements fragment across national jurisdictions.
Market Dynamics
Cloud-based data integration platforms are compressing deployment timelines from quarters to weeks, forcing incumbent middleware vendors to rearchitect their delivery models around API-first consumption patterns. This structural shift is redistributing contract value toward real-time streaming capabilities and away from batch-oriented legacy stacks.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making pipelines now require embedded lineage tracking, driving replacement demand for opaque legacy ETL tools across European financial services and healthcare sectors.
- Healthcare interoperability:The 21st Century Cures Act in the United States mandates FHIR-based data exchange, compelling hospital systems to modernize integration infrastructure for patient record unification.
- Edge computing proliferation:Manufacturing and logistics operators are deploying distributed integration nodes to preprocess IoT telemetry before cloud ingestion, reducing bandwidth costs and latency.
Market Restraints
- Specialized engineering talent scarcity:Pipeline architects fluent in both legacy mainframe protocols and modern event streaming command compensation premiums that inflate total cost of ownership.
- Cloud concentration risk:Three hyperscale providers dominate managed integration runtime environments, creating single-point-of-failure exposure for enterprise data flows.
- Schema standardization friction:Industry-specific data models lack universal adoption, forcing expensive custom mapping development for cross-enterprise connectivity.
Strategic Opportunities
- Southeast Asia manufacturing digitization:Indonesia and Vietnam's electronics assembly sectors remain underserved by real-time supply chain integration, presenting greenfield deployment potential.
- Climate disclosure automation:The SEC's emissions reporting rules create demand for platforms that trace carbon data from operational systems through to regulatory filings.
- Convergence of data mesh and AI governance:Federated architectures combined with automated quality scoring enable self-service analytics without centralized IT bottlenecks.
Industry Challenges
- Legacy system entanglement:Decades-old ERP installations with undocumented customizations resist API abstraction, prolonging migration timelines and inflating professional services dependency.
- Cross-border data sovereignty navigation:Fragmented national localization requirements force vendors to maintain redundant infrastructure footprints, complicating multi-tenant platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Integration Software Market |
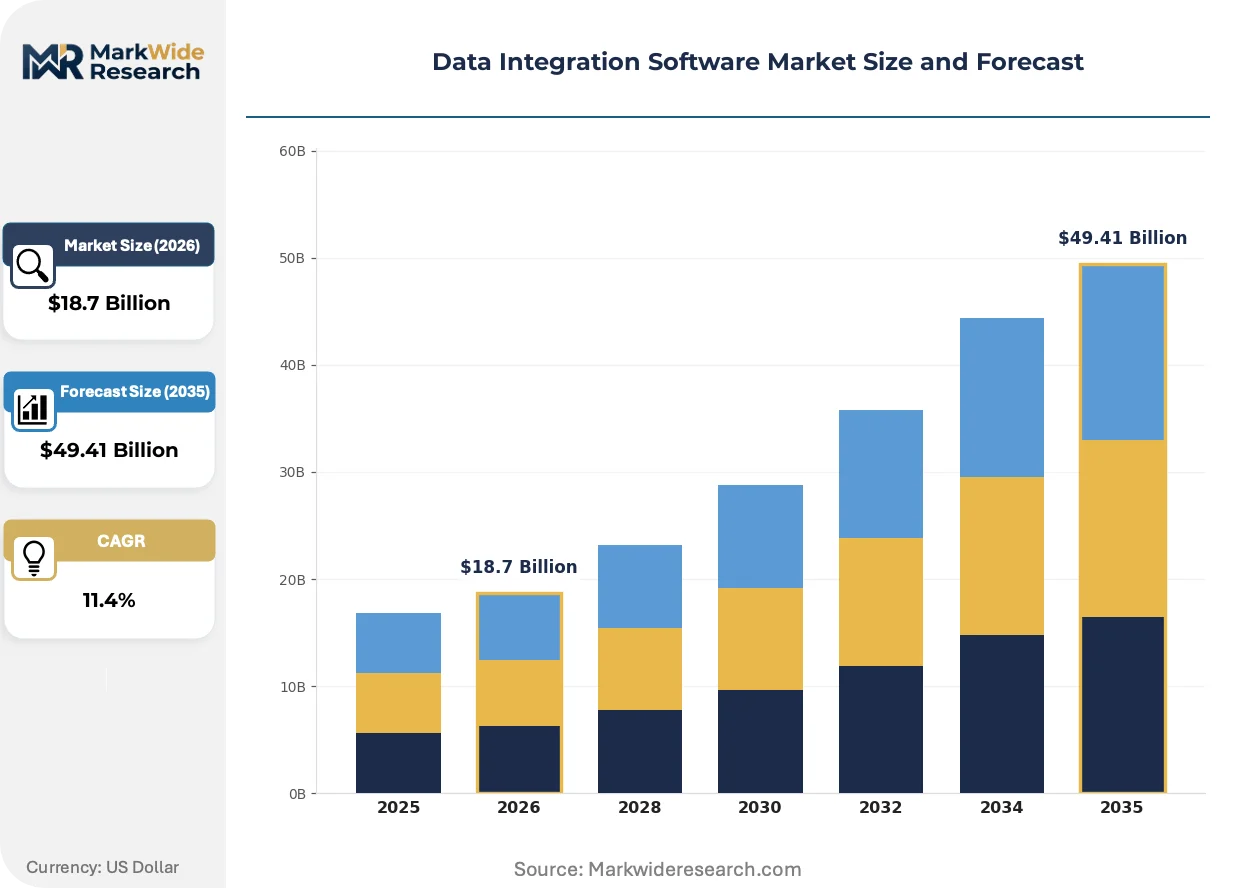
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Use Case: Data Migration, Data Warehousing, ETL, Real-Time Data Processing End User: Healthcare, Retail, Manufacturing, Finance Integration Type: API-Based, Batch Processing, Streaming, Others |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, Informatica, Talend, SAS Institute Inc., TIBCO Software Inc., Salesforce (MuleSoft), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Integration Software Market Emerging Trajectories
Data integration architecture is pivoting from centralized ETL toward distributed event streaming, compressing the latency window between operational capture and analytical availability. This shift is redefining competitive advantage around throughput engineering rather than connector breadth.
Change data capture technology is migrating from database replication utilities toward real-time analytics enablers. Financial institutions now deploy CDC streams to power fraud detection systems with sub-second response requirements. The technology is migrating from passive backup synchronization into active operational intelligence infrastructure, collapsing the traditional boundary between OLTP and OLAP environments.
The EU AI Act's risk classification framework imposes algorithmic auditability requirements on automated data flows. Vendors must now embed purpose-limitation controls and consent propagation directly into pipeline orchestration layers. High-risk AI deployments in credit scoring and medical diagnostics face the steepest compliance engineering burdens, accelerating demand for explainable transformation logic.
Enterprise buyers are consolidating vendor relationships around integrated data platform suites rather than best-of-breed point solutions. Procurement committees now prioritize unified governance consoles over specialized transformation depth. This concentration pattern is most pronounced among Fortune 500 manufacturers modernizing operational technology stacks, where procurement cycles increasingly favor strategic supplier partnerships with multi-year transformation roadmaps.
Data Integration Software Market Segmentation
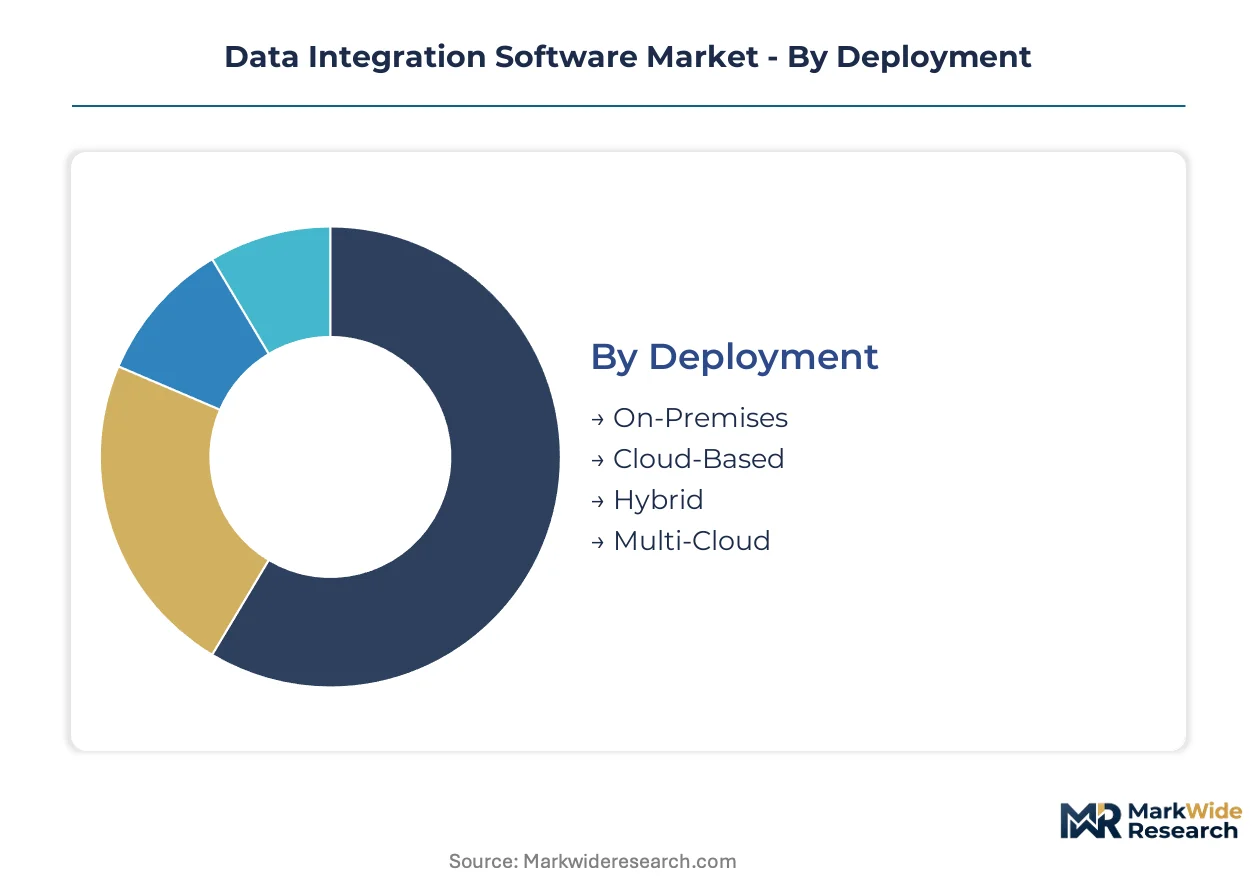
Data integration software vendors must align product architecture with distinct operational constraints across deployment environments, processing paradigms, and industry compliance regimes. Segmentation reveals where engineering investment concentrates versus where standardization prevails.
Deployment:
Mature on-premises installations coexist with emerging multi-cloud orchestration layers as enterprises navigate workload portability requirements.
- On-Premises:Legacy middleware stacks running inside corporate data centers retain dominance in defense, intelligence, and critical infrastructure sectors where air-gapped security mandates persist. Financial services institutions in Germany and Switzerland maintain these deployments to satisfy national banking regulator data localization requirements.
- Cloud-Based:Fully managed integration platform-as-a-service offerings eliminate infrastructure provisioning overhead. Healthcare providers in the United States accelerate migration here to meet HIPAA-compliant patient record exchange under the 21st Century Cures Act.
- Hybrid:Split architectures process sensitive data on-premises while bursting analytics workloads to public cloud. Manufacturing firms deploy this model to keep proprietary process data inside factory networks while feeding aggregated metrics to cloud-based supply chain visibility platforms.
- Multi-Cloud:Orchestration layers abstracting AWS, Azure, and Google Cloud APIs simultaneously. Retail enterprises adopt this approach to avoid vendor lock-in and negotiate competitive pricing across hyperscale providers.
Cloud-Based handles the majority of throughput; Multi-Cloud is expanding most quickly on share as sovereignty requirements fragment.
Use Case:
Cost tier differentiation separates high-touch professional services engagements from self-service subscription offerings.
- Data Migration:One-time bulk transfer projects between legacy and modern systems. ERP consolidation initiatives in manufacturing generate concentrated demand, though project-based revenue lacks recurrence.
- Data Warehousing:Continuous pipeline construction feeding centralized analytics repositories. Finance sector deployments in London and New York dominate here, driven by regulatory reporting automation requirements.
- ETL:Traditional extract-transform-load batch processing for historical analytics. Mature technology with compressed margins; vendors compete on connector breadth rather than transformation sophistication.
- Real-Time Data Processing:Sub-second event streaming enabling operational decision automation. Fraud detection systems at payment processors and IoT telemetry pipelines in automotive manufacturing represent the steepest growth trajectory.
ETL still commands the largest installed base; Real-Time Data Processing shows the steepest expansion trajectory as latency requirements tighten.
End User:
Application-specific compliance burdens reshape feature prioritization across vertical sales motions.
- Healthcare:FHIR-compliant interoperability platforms unifying electronic health records. United States hospital systems drive procurement volume to satisfy interoperability mandates from CMS and ONC.
- Retail:Omnichannel inventory synchronization and customer data platform integration. European fashion retailers concentrate investment here to unify online and in-store transaction streams.
- Manufacturing:Operational technology and IT convergence for predictive maintenance and quality control. German automotive suppliers lead adoption, integrating shop-floor SCADA with cloud-based analytics.
- Finance:Real-time risk calculation and regulatory reporting pipelines. SEC climate disclosure rules and EU CSRD requirements force emissions data traceability from core banking systems through to filings.
Finance generates the highest contract values; Healthcare is climbing fastest as interoperability deadlines approach.
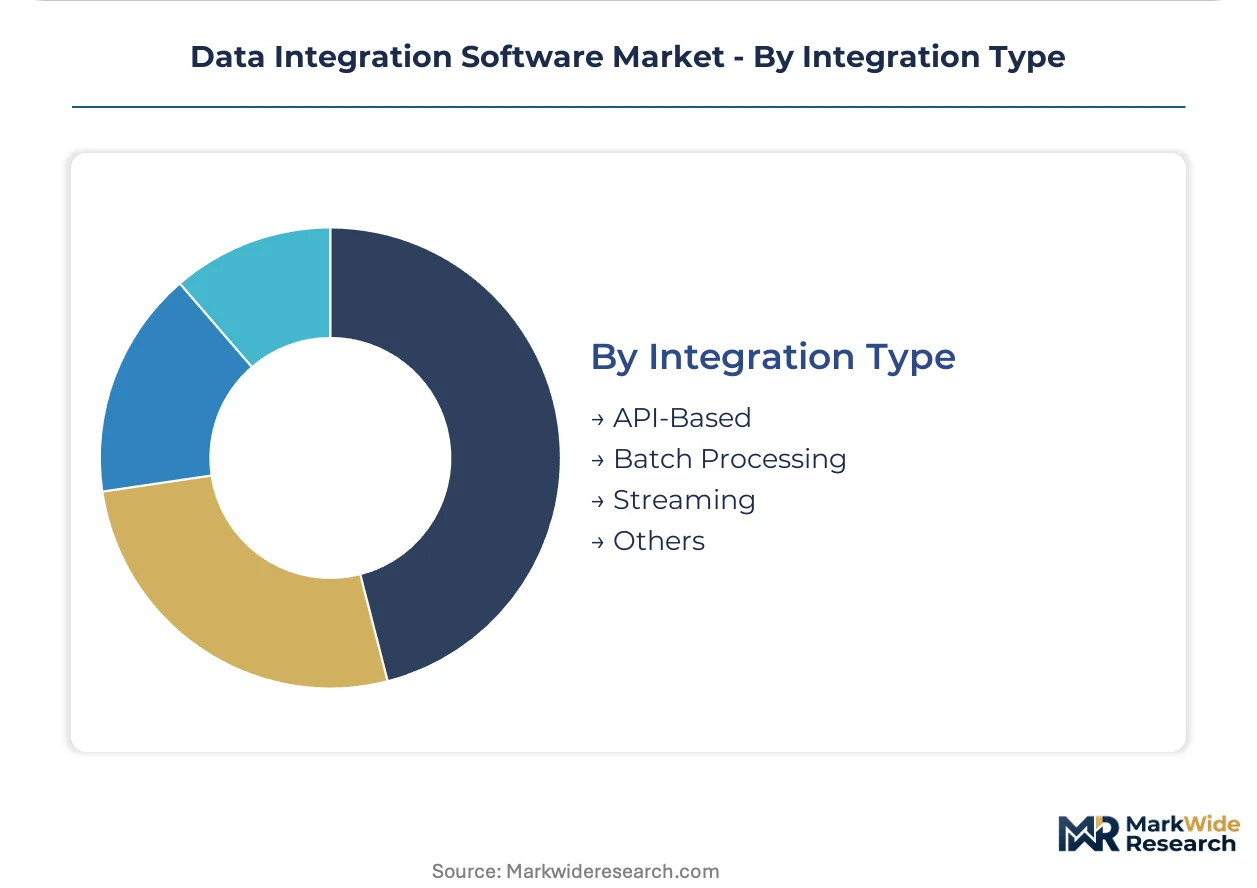
Integration Type:
Customer type stratification separates engineering-intensive custom development from configurable self-service consumption.
- API-Based:Bidirectional REST and GraphQL connectors enabling application composability. Premium pricing reflects schema mapping complexity; demand concentrates among SaaS-native enterprises in technology and professional services.
- Batch Processing:Scheduled bulk data movement optimized for cost over speed. Mature segment serving cost-conscious mid-market buyers with predictable, non-urgent data requirements.
- Streaming:Continuous event ingestion with exactly-once processing guarantees. Apache Kafka and Pulsar ecosystems dominate; financial trading platforms and connected vehicle networks drive capability investment.
- Others:File-based transfer protocols, message queuing systems, and emerging blockchain-based data notarization. Niche applications in cross-border trade finance and pharmaceutical supply chain provenance.
API-Based carries the margin premium; Streaming is gaining share fastest as event-driven architectures displace request-response patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC climate disclosure rules and the 21st Century Cures Act are concentrating procurement velocity in the United States, while EU AI Act lineage mandates reshape European vendor selection criteria.
United States
Hospital systems and financial services institutions dominate demand as HIPAA-compliant cloud migration and real-time fraud detection pipelines accelerate procurement. The 21st Century Cures Act's FHIR interoperability deadlines are forcing electronic health record unification projects across integrated delivery networks. Healthcare clusters in Boston and the Research Triangle are deploying hybrid integration architectures to bridge on-premises clinical systems with cloud analytics.
Germany
Automotive suppliers and precision manufacturers are converging operational technology with enterprise IT for predictive maintenance workflows. The EU AI Act's high-risk system classification imposes audit trail requirements on automated quality control pipelines. Industrial clusters in Stuttgart and Munich are embedding change data capture layers between shop-floor SCADA and cloud-based supply chain visibility platforms.
United Kingdom
London-based financial institutions are modernizing regulatory reporting infrastructure to satisfy FCA and Bank of England data lineage expectations. GDPR purpose-limitation requirements are propagating consent metadata through real-time transaction streams. Fintech concentrations in Canary Wharf and Edinburgh are driving API-first integration platform adoption for open banking compliance.
Japan
Automotive OEMs and electronics manufacturers are deploying edge computing nodes for IoT telemetry preprocessing before cloud ingestion. METI's data free flow with trust initiatives are shaping cross-border data governance architecture decisions. Manufacturing corridors in Aichi Prefecture and Kansai are integrating legacy mainframe production scheduling with modern ERP systems.
India
IT services exporters and domestic banks are building real-time data pipelines to support unified payment interface transaction monitoring. RBI's data localization directives are forcing infrastructure deployment within national boundaries. Technology parks in Bengaluru and Hyderabad are emerging as integration engineering talent hubs for global system integrators.
Data Integration Software Market Vendor Landscape
Hyperscale cloud providers and specialized integration vendors split the market into distinct capability tiers. Consolidation pressure is intensifying as enterprise procurement committees favor unified platform suites over point solutions. Three archetypes dominate: database-native incumbents extending middleware stacks, cloud-native challengers built on event streaming foundations, and legacy ETL vendors rearchitecting for API-first delivery. Dominant competitive moves include strategic partnerships with hyperscale infrastructure providers and vertical integration into industry-specific connector libraries.
Within the database-native tier, Oracle Corporation and IBM Corporation exemplify incumbents leveraging installed base relationships to embed integration capabilities within existing enterprise data architectures. Microsoft Corporation anchors the cloud-native vector through Azure-embedded consumption models. These three entities collectively represent the competitive pressure forcing specialized vendors toward niche vertical positioning or acquisition exits.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Informatica |
| Talend |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Salesforce (MuleSoft) |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud infrastructure concentration in the United States, Ireland, and Singapore concentrates compute cost leverage upstream, pushing margin pools toward specialized API engineering and compliance tooling downstream where differentiation commands premium positioning.
Pricing Analysis
North American enterprise contracts carry 15-25% price premiums over equivalent Asia-Pacific deployments due to stringent HIPAA and SEC compliance engineering requirements. The dominant pricing structure stratifies across premium, standard, and economy tiers based on integration complexity and support SLAs. Price differentiation centers on real-time streaming throughput guarantees versus batch processing latency tolerance. Cost compression in the mid-market tier is intensifying because hyperscale providers bundle basic integration capabilities at marginal cost, forcing specialized vendors to retreat toward high-touch professional services engagements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent edge computing nodes deployed in manufacturing integration scenarios. Engineering talent pools concentrate in India, Poland, and Vietnam, creating geographic dependencies for pipeline architecture and connector development. Component sourcing draws from Taiwan for semiconductor-dependent streaming hardware, Ireland for EU data residency infrastructure, and Singapore for Asia-Pacific latency optimization. Single-source vulnerability persists around Apache Kafka ecosystem maintenance and support. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by hyperscaler marketplace listings for mid-market self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock enterprise buyers into orchestration layers that embed deeply across operational workflows, creating durable incumbent advantages against point-solution challengers.
For Market Incumbents: Insulate core relationships by embedding change data capture agents directly into customer mainframe environments, raising extraction friction for competitors. Extend API connector libraries into industry-specific protocols like FHIR for healthcare and ISO 20022 for finance. Threat vectors include cloud-native challengers built on event streaming foundations and hyperscale providers bundling integration at marginal cost. For New Entrants and Emerging Players: Pursue greenfield deployment opportunities in Southeast Asian manufacturing corridors where real-time supply chain visibility remains underpenetrated. Target mid-market healthcare providers in secondary United States metropolitan areas facing 21st Century Cures Act deadlines without internal engineering capacity. Go-to-market motion should emphasize pre-built FHIR compliance templates and rapid deployment guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward vertical integration specialists with captive connector libraries in regulated industries, where regulatory entrenchment compounds switching cost advantages. Acquisition target archetype: event streaming platforms with exactly-once processing guarantees and established financial services deployments. Signal to monitor: hyperscaler bundling intensity in mid-market segments as inflection indicator for specialized vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding CDC agents into Oracle and IBM mainframe environments raises competitor extraction costs. |
| Acquisition of Specialist Firm | Targeted purchases of FHIR-compliant healthcare interoperability vendors accelerate regulatory deadline capture. |
| Strategic Partnership | Hyperscaler co-sell agreements with AWS and Azure expand mid-market reach without direct sales investment. |
| Product Launch | Real-time emissions traceability modules address SEC climate disclosure compliance requirements. |
| Geographic Expansion | Jakarta and Ho Chi Minh City engineering hubs tap underserved electronics manufacturing digitization demand. |
Methodological Framework
A standing panel of chief technology officers, enterprise integration architects, healthcare IT procurement leads, and financial services data governance officers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, CMS interoperability mandate documentation, and EU AI Act implementation guidance. Bottom-up deployment sizing and top-down vendor revenue triangulation anchored market estimates.
Scenario bracketing around regulatory implementation timelines and cloud migration velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, processing paradigm, vertical compliance regime, organization size tier, and regional adoption pattern. CAGRs were derived from installed base growth rates and new contract value trajectories. Industry-specific inputs incorporated FHIR mandate deadline pacing and EU AI Act risk classification rollout schedules.
Sensitivities concentrate around hyperscaler bundling intensity, regulatory deadline extensions, and legacy system migration acceleration. Forecasts reflect documented assumptions on enterprise cloud adoption curves and compliance engineering cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
E-Clinical Solution Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Global Digital Experience Management Software Market
Software & Services
Global Webinar Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Software Consulting Market
Software & Services
CAD Modeling Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Winery Management Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Servicenow Tech Services Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Telecom IT Services Market
Software & Services
Global Plumbing Software Market