
 Team Collaboration Software Market | 2026-2036
Team Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Team Collaboration Software Market Intelligence
The established direct-to-enterprise sales channel is fragmenting due to the rise of product-led growth strategies. This model allows individual teams to adopt tools before a formal, top-down procurement process begins. Microsoft Teams leverages its deep integration with the Office 365 suite to secure large enterprise accounts. Slack competes by offering a highly customizable user experience and an extensive ecosystem of third-party application integrations, while Asana specializes in sophisticated project and portfolio management for complex organizational needs.
Team collaboration software integrates disparate functions like communication, document sharing, and task management into a unified digital workspace. A key technical characteristic is the use of APIs to connect with other business systems, enabling seamless data flow and workflow automation. The primary commercial purpose is to enhance team productivity and provide a single source of truth for projects, particularly for geographically distributed teams. Cloud-based deployment is the dominant model, and subscription-based pricing has become the industry standard, frequently offered alongside a freemium tier to encourage initial adoption.
Data security and privacy regulations are shaping product architecture and go-to-market strategies. Adherence to Europe's GDPR is a baseline requirement for vendors, while handling protected health information in the United States necessitates compliance with HIPAA. Many enterprise customers also require vendors to hold ISO/IEC 27001 certification as proof of robust information security management systems. Software providers must continuously balance rapid feature development with the complexities of meeting evolving data sovereignty and international compliance obligations.
Market Dynamics
The central dynamic is the market's inversion from top-down, CIO-led procurement to bottom-up, team-driven adoption. This product-led growth model, accelerated by permanent hybrid work structures, shifts competitive emphasis from enterprise sales relationships to user experience and integration ecosystem depth.
Growth Catalysts
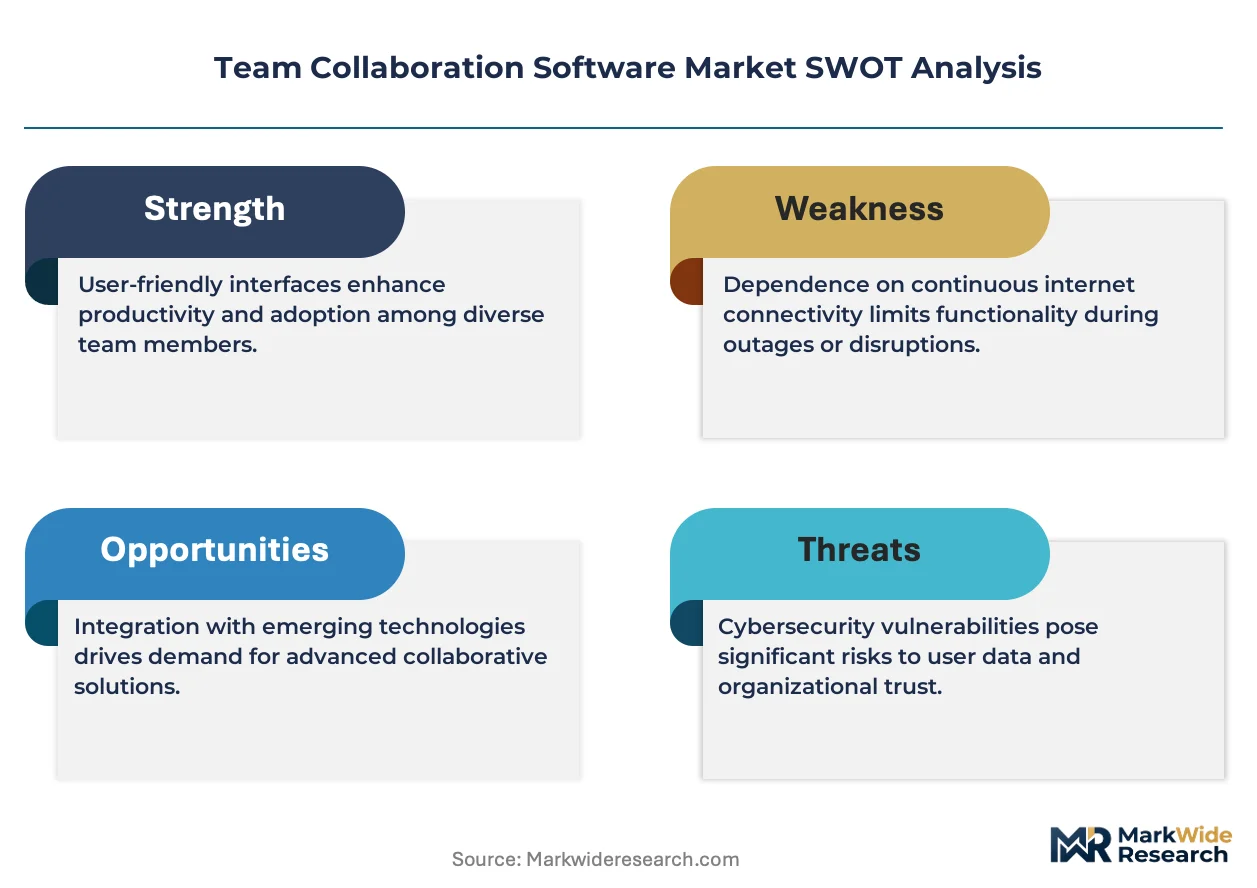
- Hybrid Work Models:Widespread corporate adoption of permanent remote and hybrid work policies necessitates unified digital workspaces to maintain productivity and connectivity for geographically distributed teams.
- Agile Frameworks:The implementation of agile development methodologies within IT and software development departments requires specialized tools for sprint planning, task management, and continuous communication.
- Demand Concentration:Strong demand from high-growth technology and finance sector clusters in the United States, the United Kingdom, and Germany provides a concentrated and sophisticated customer base.
Market Restraints
- Platform Bundling:Standalone collaboration tools face intense competition from bundled offerings within larger productivity suites, which leverage existing enterprise penetration to limit market access for specialized vendors.
- Data Sovereignty Rules:Increasing regulations like Europe's GDPR and other national data localization mandates create significant architectural and operational hurdles for global software providers, slowing expansion.
- Legacy System Integration:The complexity and cost of integrating modern collaboration software with entrenched, legacy enterprise resource planning and customer relationship management systems can delay or stall deployments.
Strategic Opportunities
- Vertical-Specific Solutions:Developing tailored solutions for regulated industries like healthcare and finance, incorporating features that address specific compliance needs such as HIPAA or financial reporting standards.
- AI-Powered Automation:Integrating artificial intelligence to automate routine tasks like meeting summarization, action item tracking, and workflow optimization, creating a higher-value, intelligent workspace.
- Emerging Market Penetration:Expanding into markets across Southeast Asia and Latin America where digital transformation initiatives are accelerating, but adoption of sophisticated collaboration tools remains nascent.
Industry Challenges
- Integration Ecosystem Maintenance:The operational burden of ensuring stability, security, and performance across a vast and constantly changing ecosystem of third-party application APIs presents a significant engineering challenge.
- Compliance Overhead:Vendors face continuous pressure to maintain and update certifications like ISO/IEC 27001 and adapt to evolving data privacy regulations, diverting resources from core product development.
- User Notification Fatigue:A primary challenge is designing interfaces that combat information overload and tool sprawl, which can diminish user productivity and lead to platform abandonment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Team Collaboration Software Market |
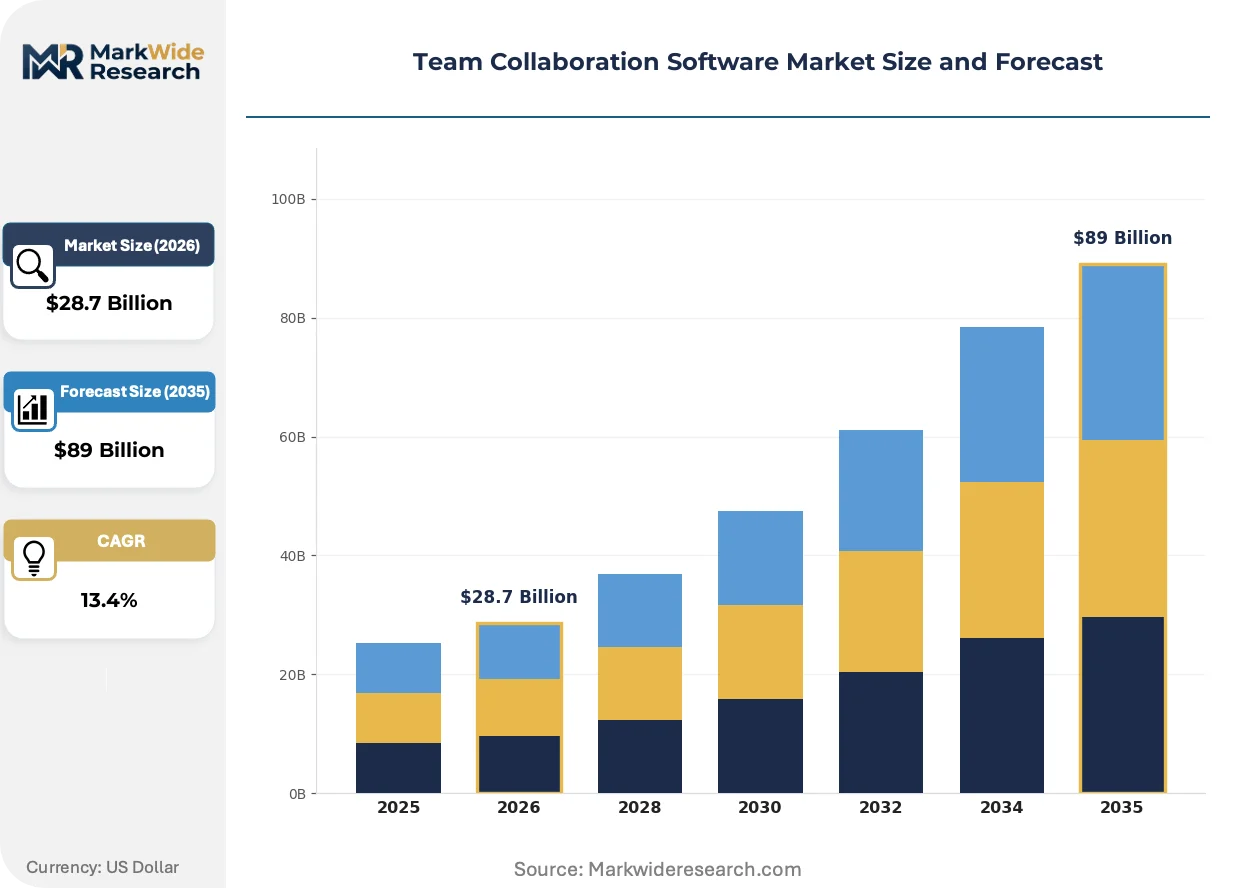
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Managed Application: Project Management, Communication, Document Sharing, Video Conferencing, Workflow Automation End User: IT Departments, Creative Agencies, Educational Institutions, Consulting Firms, Legal Practices Pricing Model: Subscription-Based, Freemium, Perpetual License, Pay-As-You-Go, Usage-Based |
| Companies Covered | Google Workspace, Miro, Microsoft Teams, Notion, Zoom Workplace, Slack, Monday.com, ClickUp, Asana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Team Collaboration Software Market Strategic Shifts & Innovations
The market's evolution is defined by the software's transition from a simple communication channel into an intelligent, central hub for organizational workflows. This shift is propelled by the infusion of artificial intelligence and a demand for a single source of project truth.
AI Integration
Generative AI is being embedded directly into collaboration platforms to perform functions like automated meeting summaries, task generation, and message drafting. Creative agencies and software development teams are notable early adopters, using these features to accelerate project cycles. This integration of AI is virtualizing certain project management and administrative functions by automating routine organizational and documentation tasks.
Data Residency Requirements
Europe's GDPR, along with emerging data sovereignty laws in other nations, imposes strict controls on cross-border data flow and processing. This regulatory pressure compels vendors to build and maintain geographically specific data centers to offer customers data residency options. The finance and public sectors are most affected, frequently making local data hosting a mandatory procurement requirement.
Team-Level Procurement
A clear behavioral shift sees buying power move from centralized IT departments to individual teams and business units. This product-led adoption model bypasses traditional, lengthy procurement cycles, allowing teams to select "best-of-breed" tools that fit their specific workflow needs. This trend is particularly pronounced in the technology sectors of the United States and the United Kingdom.
Team Collaboration Software Market Segmentation
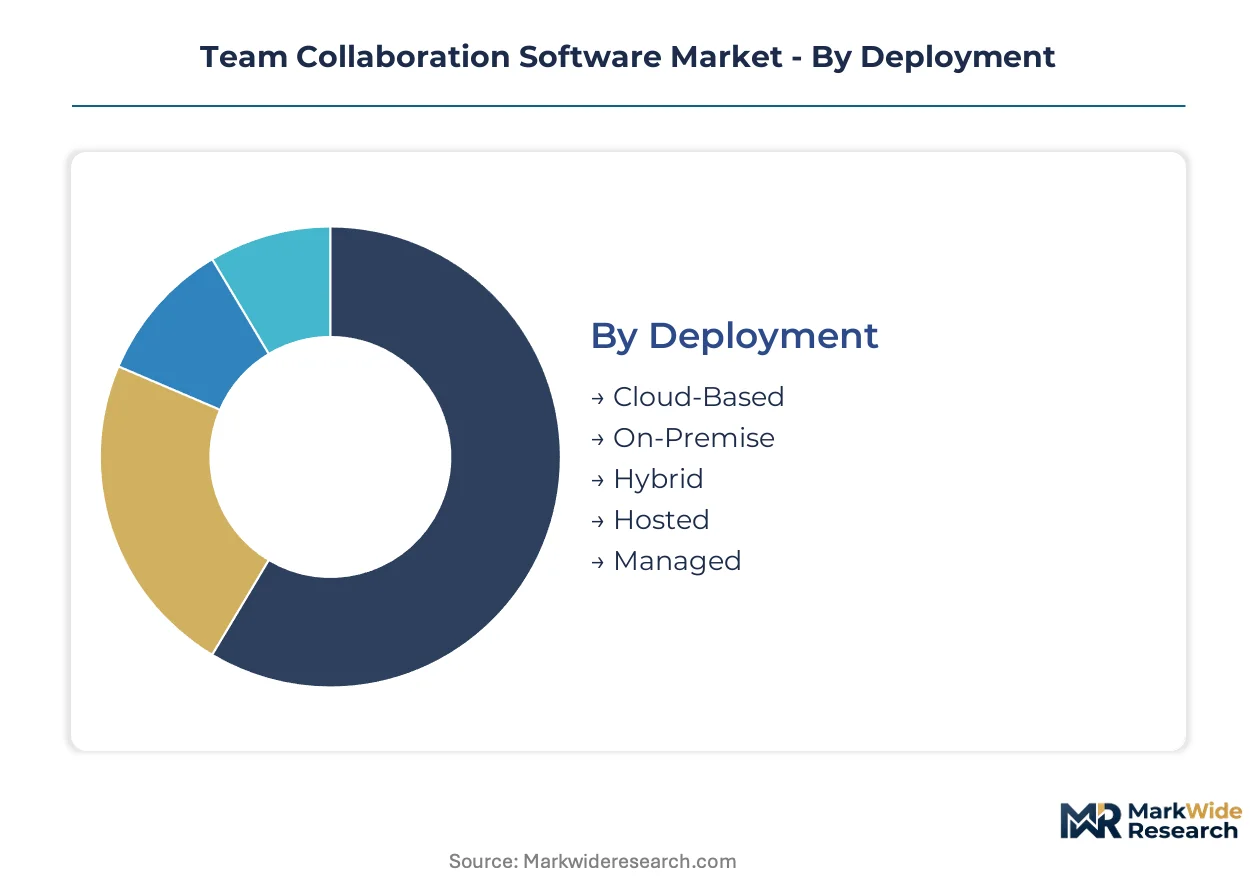
The team collaboration software market segments illuminate varied deployment preferences, functional requirements, and user profiles shaping product development. Understanding these distinctions allows vendors to tailor solutions for specific organizational structures and operational scales. This granular view is essential for identifying concentrated demand clusters and emerging growth opportunities.
Deployment:
The deployment segment reflects a spectrum of maturity, ranging from established on-premise solutions to dynamic cloud-native architectures.
- Cloud-Based:This model delivers software functionality over the internet, hosted by the vendor and accessible via web browsers or mobile applications. Demand concentrates heavily in technology and finance sectors within the United States, driven by scalability requirements and reduced infrastructure overhead.
- Hybrid:Combining elements of both on-premise and cloud deployments, this model allows organizations to store sensitive data locally while leveraging cloud services for flexibility. Corporate adoption of permanent hybrid work models acts as a primary catalyst for this segment's expansion.
- On-Premise:Software is installed on a customer's servers, offering maximum control over data.
- Hosted:A third-party manages software and hardware infrastructure, providing a dedicated environment.
- Managed:Comprehensive oversight by a third-party vendor covers installation, maintenance, and support.
Cloud-Based handles the majority of throughput; Hybrid is the fastest mover on share.
Application:
This category delineates the primary functional purposes for which teams leverage collaboration software, from structured task management to real-time communication.
- Project Management:These tools provide features for planning, tracking, and executing projects, including task assignment, progress monitoring, and deadline management. Creative agencies and IT departments implementing agile development frameworks heavily utilize these sophisticated capabilities.
- Communication:Focusing on real-time and asynchronous messaging, this application type facilitates direct interaction through chat, channels, and direct messages. Geographically distributed teams in the United Kingdom and Germany rely on these functions to maintain connectivity and information flow.
- Document Sharing:This functionality enables secure storage, sharing, and collaborative editing of files.
- Video Conferencing:Platforms offering live video and audio calls support virtual meetings for dispersed workforces.
- Workflow Automation:Tools streamline repetitive tasks and processes, integrating functions for operational efficiency.
Demand for Project Management functionality is expanding most quickly, while Communication maintains foundational utility.
End User:
The end-user segmentation highlights specific organizational types that derive significant value from team collaboration tools, reflecting varied operational needs and compliance requirements.
- IT Departments:These departments utilize collaboration software for agile development, bug tracking, and managing complex software projects. The implementation of agile development methodologies within technology sectors in the United States drives significant adoption.
- Creative Agencies:Agencies leverage these platforms for client communication, campaign management, and collaborative content creation. Growth is pronounced within these agencies due to their need for visual collaboration and rapid iteration cycles.
- Educational Institutions:Schools and universities employ collaboration tools for virtual classrooms and group projects.
- Consulting Firms:Firms use collaboration software for client engagement, project organization, and knowledge sharing.
- Legal Practices:Law firms adopt these tools for secure document management, case collaboration, and client communication.
IT Departments represent the largest customer base, but Creative Agencies exhibit the steepest expansion trajectory.
Pricing Model:
This category distinguishes how vendors structure their charges, influencing accessibility and long-term value perception across different customer segments.
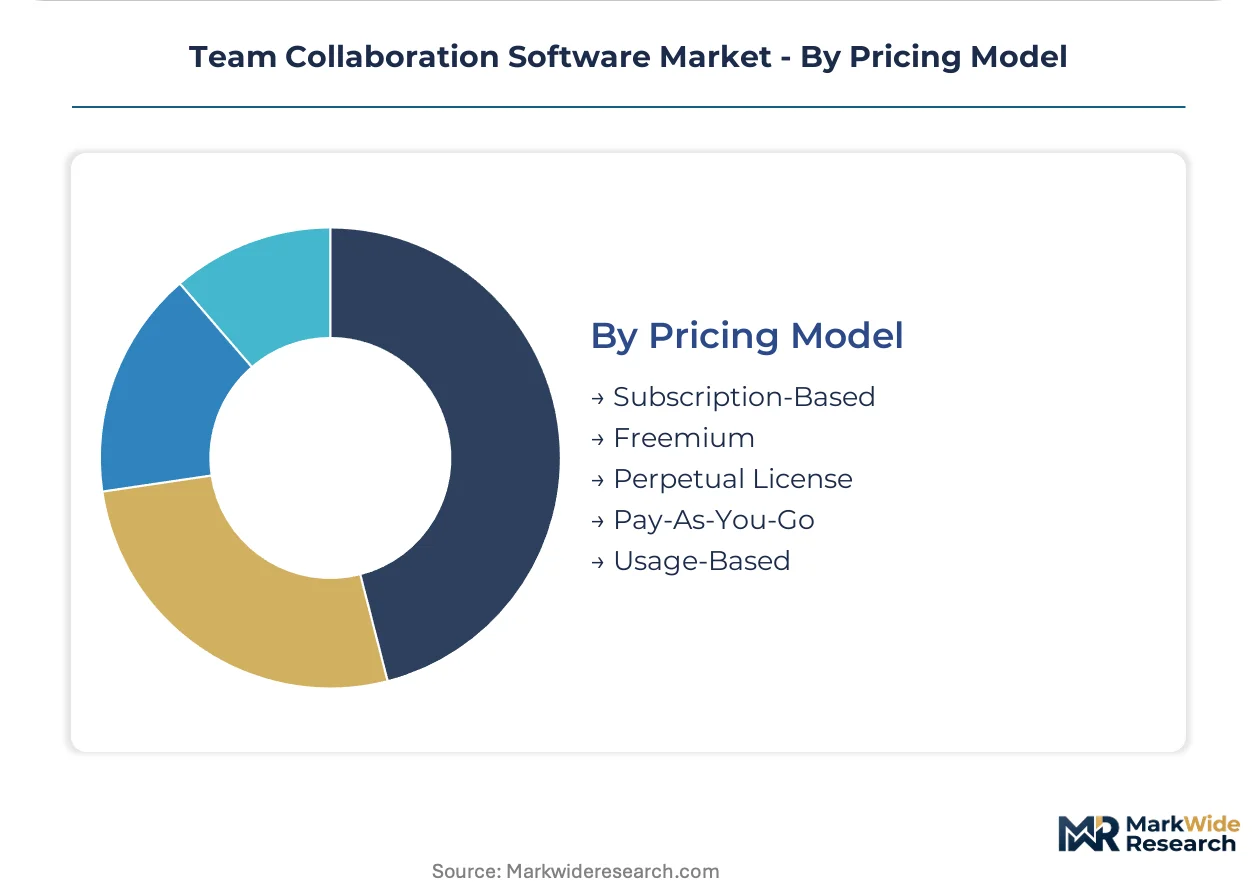
- Subscription-Based:Customers pay a recurring fee, typically monthly or annually, for access to the software and its features. This model has become the industry standard, frequently offered alongside a freemium tier to encourage initial adoption.
- Freemium:A basic version of the software is offered free of charge, with advanced features or increased capacity available through paid subscriptions. This model effectively captures individual teams and small businesses in the United States and the United Kingdom.
- Perpetual License:Users purchase the software once with a one-time fee for indefinite use of that version.
- Pay-As-You-Go:Charges are based on actual usage, such as active users, data storage, or feature consumption.
- Usage-Based:This model bills customers according to consumption metrics, aligning costs directly with value derived.
The Subscription-Based model captures significant market value, with Freemium gaining traction among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting digital transformation and remote work policies are instrumental in shaping the global team collaboration software market. These policies encourage organizations to invest in unified digital workspaces for enhanced productivity and connectivity. Such frameworks provide a fertile ground for market expansion across diverse geographies.
United States
The United States demonstrates robust demand for team collaboration software, particularly within its technology and finance sectors. Compliance with HIPAA regulations is a critical factor for vendors serving healthcare clients. Innovation hubs like Silicon Valley and New York City drive early adoption of advanced collaboration tools and AI-powered features.
United Kingdom
United Kingdom businesses, especially in financial services and creative industries, prioritize team collaboration solutions for distributed teams. Adherence to GDPR mandates data residency options and robust privacy controls for software providers. London's vibrant tech scene actively implements product-led growth strategies for collaboration tool adoption.
Germany
German enterprises in automotive, engineering, and finance seek collaboration tools that ensure stringent data security and privacy. National data localization requirements, alongside GDPR, compel vendors to establish local data centers. Major industrial centers like Munich and Berlin are adopting sophisticated platforms to manage complex projects.
Japan
Japanese companies, particularly in manufacturing and IT, are increasingly adopting team collaboration software to enhance operational efficiency. METI guidelines influence data handling practices, emphasizing secure cloud solutions and data integrity. Tokyo's corporate landscape and Osaka's industrial base are integrating advanced platforms for streamlined project management.
India
India's burgeoning IT services and startup ecosystem fuels significant demand for scalable and cost-effective collaboration software. The upcoming Data Protection Bill is shaping vendor strategies regarding data residency and user privacy. Technology hubs such as Bangalore and Hyderabad are experiencing rapid adoption of cloud-based tools to support remote workforces.
Team Collaboration Software Market Key Industry Players
On the supply side, the industry is characterized by a mix of large platform providers and numerous specialized vendors. This market structure reflects the tension between comprehensive suites and best-of-breed solutions tailored for specific workflows. Key strategic archetypes include ecosystem-driven giants, niche project management specialists, and innovative AI-powered automation providers. Dominant competitive moves involve forming strategic partnerships to expand integration capabilities and diversifying product portfolios to address new end-user needs.
Within the ecosystem-driven platform tier, Microsoft Teams leverages its deep integration with the Office 365 suite to secure large enterprise accounts. Slack, conversely, occupies a position as a highly customizable communication hub, emphasizing its extensive ecosystem of third-party application integrations and user-centric design. Asana exemplifies the specialized project and portfolio management archetype, catering to complex organizational needs with sophisticated workflow capabilities for task assignment and progress monitoring. These players collectively anchor distinct segments of the market, from broad enterprise communication to detailed project execution.
| Leading Market Players |
|---|
| Google Workspace |
| Miro |
| Microsoft Teams |
| Notion |
| Zoom Workplace |
| Slack |
| Monday.com |
| ClickUp |
| Asana |
| Others |
Cost & Logistics Intelligence
Silicon Valley's concentration of software development talent and cloud infrastructure capacity influences the global pricing power for advanced collaboration features. This capacity dynamic shapes the availability and cost of innovative solutions across the market. Pricing structures and supply chain resilience remain critical considerations for vendors.
Pricing Analysis
Compliance certification (ISO/IEC 27001, HIPAA, GDPR) creates the primary spread in enterprise pricing, reflecting the higher assurance requirements for regulated industries. Subscription-based models dominate, often complemented by freemium tiers to facilitate initial adoption by individual teams. Pricing pressure stems from intense competition and the availability of bundled offerings within larger productivity suites. Individual teams and small businesses exhibit the highest price sensitivity, while large enterprises prioritize feature completeness and robust security, making them less sensitive to base subscription costs.
Supply Chain Analysis
Data sovereignty rules pose the most significant structural risk, compelling vendors to establish local data centers in regions like the EU and Japan. The supply chain for team collaboration software primarily sources from skilled software developers in the United States, India, and Eastern Europe. Cloud infrastructure providers represent a critical dependency for service delivery. Distribution runs through direct-to-enterprise sales channels and product-led adoption models, leveraging digital platforms for global reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a fragmentation opportunity as product-led growth strategies empower individual teams to adopt specialized tools. This shift creates distinct niches for focused solutions.
For Market Incumbents: Harden core platform integration with existing productivity suites to leverage established enterprise penetration. This defends against niche AI-powered automation providers that can dislodge specific workflows. Invest heavily in data residency infrastructure and obtain country-specific compliance certifications like ISO/IEC 27001 to meet evolving regulatory demands from finance and public sectors.
For New Entrants and Emerging Players: Vertical-specific solutions for regulated industries like healthcare and finance represent the most penetrable entry point. These segments require tailored compliance features and specialized workflows. A strong freemium model combined with product-led growth strategies provides an effective go-to-market angle, capturing early adopters within technology and creative agencies.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized AI-powered automation providers with strong vertical integrations. These firms offer high-value intellectual property and address specific pain points, ensuring long-term viability as AI capabilities mature. Increased enterprise-wide adoption of AI features beyond early adopters serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Feature Integration | Automates routine tasks and enhances productivity for project teams. |
| Vertical-Specific Solution Development | Addresses compliance needs for regulated industries like healthcare and finance. |
| Global Data Center Expansion | Meets data residency requirements for international enterprise clients. |
| Ecosystem Partnership Building | Expands integration capabilities with diverse third-party applications. |
| Freemium Model Optimization | Captures individual teams and small businesses for product-led growth. |
Research Approach
Desk research of technology news archives, company financial filings, and regulatory body publications preceded structured interviews with CTOs, IT procurement officers, and project managers. This approach ensured a comprehensive understanding of market dynamics. Software developers and compliance officers also provided crucial insights into technical characteristics and regulatory challenges. Bottom-up and top-down triangulation validated market size estimates and growth projections.
Assumptions regarding the sustained adoption of hybrid work models and the continuous integration of AI capabilities were held constant across the analysis window. The quantitative model segmented the market by deployment model, application type, end user, and pricing model, along with regional adoption patterns. Compound annual growth rates were derived from historical data extrapolation and projected market dynamics, factoring in demand concentration and regulatory impacts.
Practitioners should monitor rapid technological shifts and evolving data privacy regulations for early signals that could revise forecasts. Forecasts reflect assumptions about market conditions and competitive landscapes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Employee Advocacy Software Market
Software & Services
Labeling Software Market
Software & Services
Business Productivity Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Software Testing Company Market
Software & Services
Hackathon Management Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Design Engineering Software Market
Software & Services
Legal Practice Management Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Global Quoting Software Market
Software & Services
Observability Platform Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Collaborative Applications Market