
 Digital Workplace Technologies Market | 2026-2036
Digital Workplace Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Workplace Technologies Market Analysis
Buyer concentration is expanding as Fortune 500 enterprises consolidate vendor relationships across hybrid work stacks, reducing supplier fragmentation that characterized early pandemic procurement. IBM anchors its position through deep vertical integration into mainframe-to-cloud middleware that bridges legacy systems with modern collaboration endpoints. Accenture differentiates through outcome-based consulting engagements that bundle deployment services with ongoing platform optimization. Cognizant competes aggressively on cost arbitrage, leveraging its India-based delivery footprint to undercut Western systems integrators on large-scale workplace transformation contracts.
Digital workplace technologies encompass the integrated software, hardware, and service layers that enable distributed employees to communicate, collaborate, access enterprise applications, and execute workflows from any location, typically requiring sub-50 millisecond latency for real-time video and API-level interoperability between identity management and content repositories. Cloud Computing dominates deployment architecture as enterprises retire on-premise Exchange and SharePoint instances, while Artificial Intelligence is the fastest-growing technology segment as vendors embed generative capabilities into document creation and meeting summarization functions. Collaboration Tools command the largest product type revenue pool, though Virtual Desktops represent the highest-margin segment due to complex GPU provisioning requirements and specialized endpoint security protocols.
The EU AI Act imposes risk-classification requirements on automated decision-making features within workplace platforms, forcing vendors to reengineer recommendation engines and analytics dashboards for European deployment. In the United States, HIPAA and SEC record-keeping rules shape data residency and audit trail specifications for healthcare and financial services buyers respectively. Stakeholders must monitor how NIST cybersecurity framework updates and emerging state-level biometric privacy laws will redefine authentication and employee monitoring compliance obligations across multi-jurisdictional deployments.
Market Dynamics
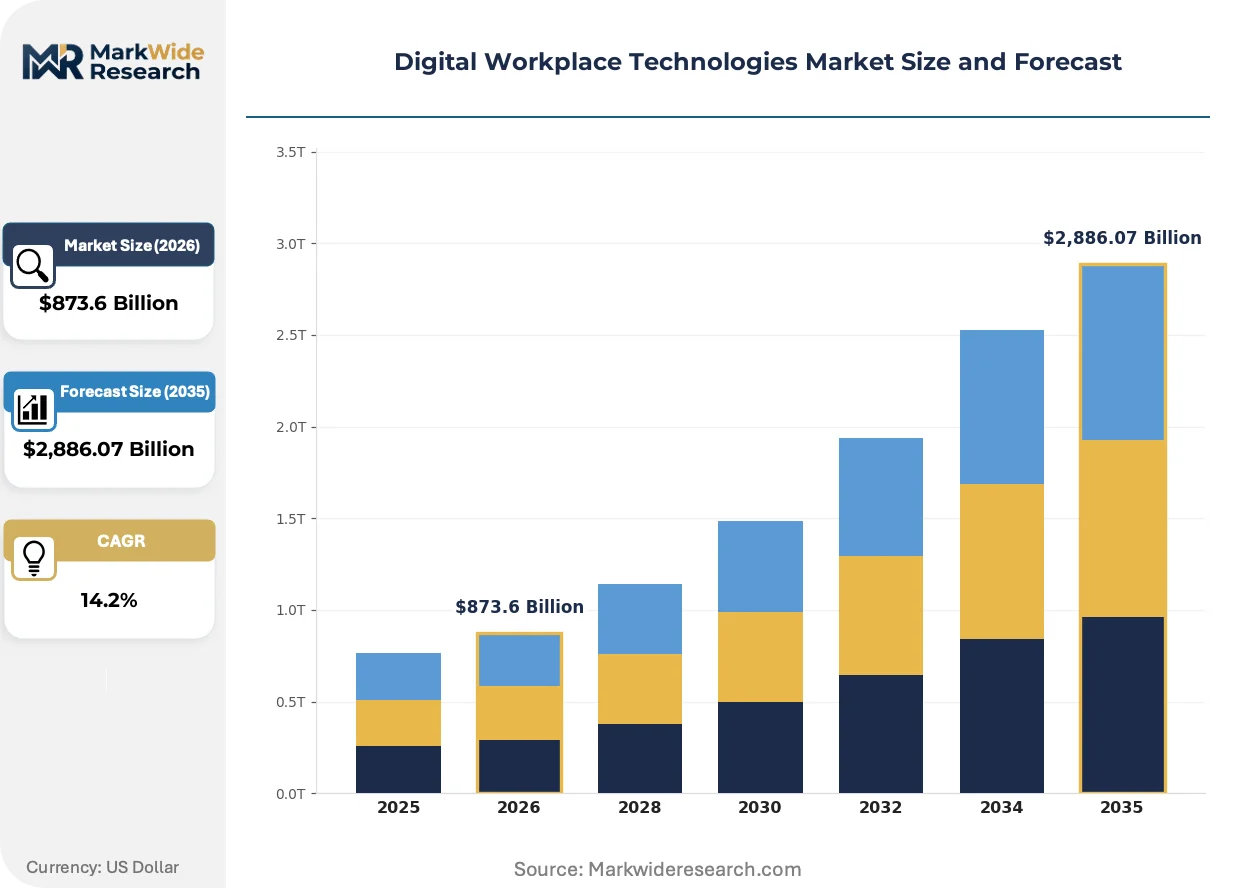
Fortune 500 enterprises are consolidating vendor relationships across hybrid work stacks, compressing supplier fragmentation that characterized early pandemic procurement and privileging integrated platform providers over point solutions.
Growth Catalysts
- EU AI Act risk-classification mandates:European financial services institutions must reengineer automated decision-making features, creating replacement demand for compliant workplace analytics platforms.
- Healthcare HIPAA record-keeping rules:US hospital systems require audit-trail specifications that drive unified digital workplace procurement over fragmented collaboration tools.
- GPU provisioning for virtual desktops:Financial services trading floors demand sub-50 millisecond latency for real-time video, accelerating specialized infrastructure investment.
Market Restraints
- Specialized endpoint security protocols:Virtual desktop infrastructure requires complex GPU provisioning that elevates deployment costs beyond mid-market budgets.
- India-based delivery concentration:Cost arbitrage competitors concentrate implementation capacity in single geography, creating geopolitical exposure for Western buyers.
- Mainframe-to-cloud middleware dependency:Legacy system integration demands captive technical expertise that constrains vendor switching.
Strategic Opportunities
- Biometric privacy law fragmentation:Emerging US state-level regulations create demand for authentication solutions that span multi-jurisdictional compliance requirements.
- Generative AI document creation:Convergence of large language models with meeting summarization functions opens white space in professional services workflows.
- Outcome-based consulting bundles:Deployment services married to ongoing platform optimization represent underpenetrated revenue model in enterprise segment.
Industry Challenges
- API-level interoperability certification:Identity management and content repository integration requires specialized engineering talent in short supply.
- NIST cybersecurity framework updates:Continuous compliance reconfiguration demands capital investment in monitoring infrastructure.
- SEC record-keeping audit timelines:Financial services buyers impose compressed certification cycles that strain vendor delivery capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Workplace Technologies Market |
| Market Size in 2026 | $873.6 Billion |
| Market Size in 2035 | $2,886.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collaboration Tools, Document Management, Virtual Desktops, Video Conferencing Technology: Cloud Computing, Artificial Intelligence, IoT, Mobile Applications End User: Corporates, Small Enterprises, Remote Workers, Educational Institutions Deployment: On-Premise, Hybrid, Private Cloud, Public Cloud |
| Companies Covered | Atos, Cognizant, IBM, Wipro, Tata Consultancy Services, Infosys, Accenture, HCL Technologies, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Workplace Technologies Market Emerging Trajectories
Artificial intelligence capabilities are embedding into core collaboration functions, while regulatory fragmentation across jurisdictions forces architectural redesign of analytics and authentication layers.
Generative AI is converging with document creation and meeting summarization functions. Large employers in professional services and financial services are deploying these capabilities at pilot scale before enterprise-wide rollout. This convergence is compressing the differentiation window for standalone productivity applications.
GDPR data residency specifications are reshaping cloud deployment architectures. European enterprises now require sovereign cloud instances that limit cross-border data flows. Healthcare and financial services verticals in Germany, France, and the Netherlands are responding with hybrid configurations that keep sensitive workloads in-country.
Buyer concentration among Fortune 500 enterprises is consolidating procurement authority into centralized IT governance functions. Regional system integrators and value-added resellers are losing access to large contracts as direct vendor relationships predominate. This pattern is most visible in United States financial services and healthcare systems with mature digital transformation programs.
Digital Workplace Technologies Market Segmentation
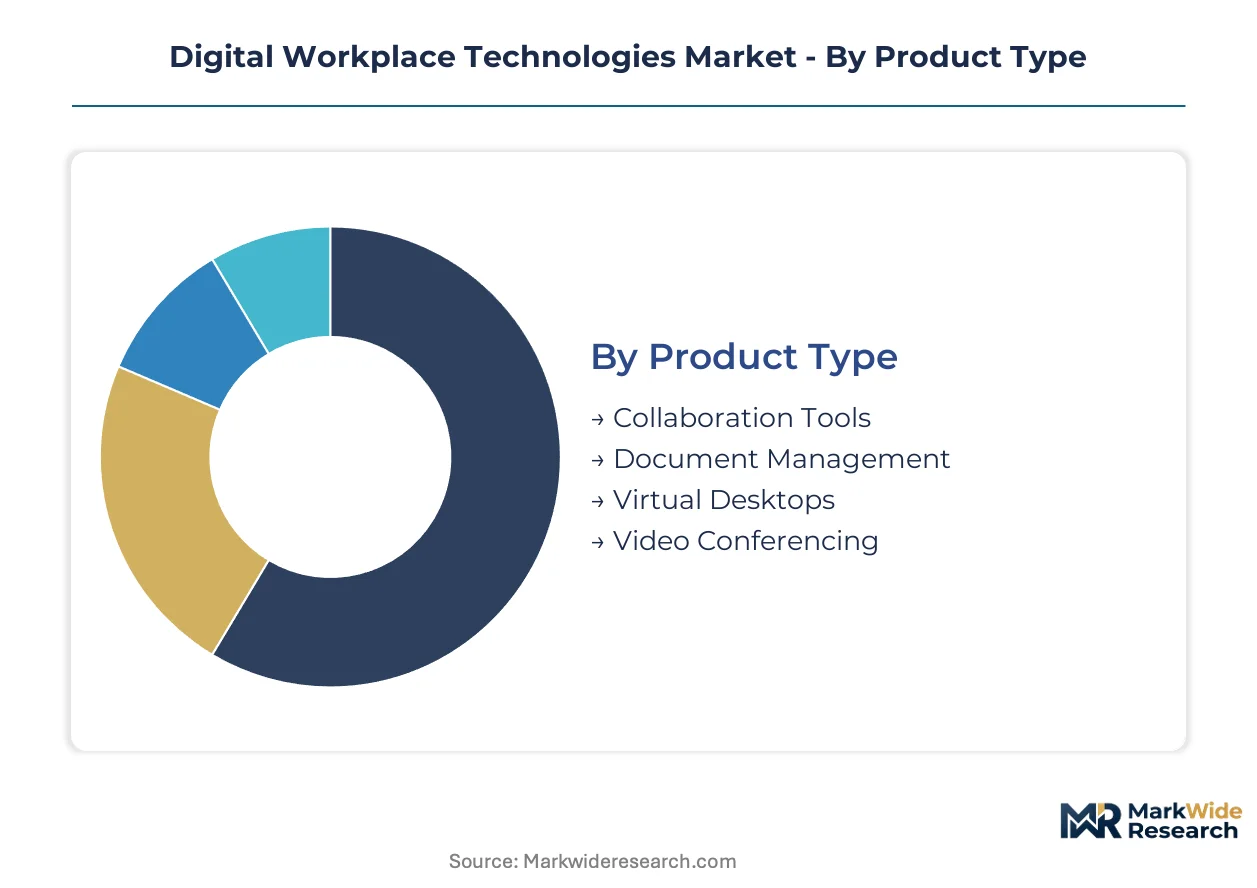
Digital workplace procurement patterns diverge sharply by organizational scale and technical maturity, with Fortune 500 enterprises demanding deeply integrated stacks while mid-market buyers prioritize rapid deployment over customization. Segmentation reveals where vendor consolidation concentrates versus where point solutions retain viability.
Product Type:
Customization intensity spans from configurable SaaS modules to bespoke GPU-provisioned infrastructure, creating distinct margin profiles and implementation timelines across this category.
- Collaboration Tools:Unified messaging, project management, and synchronous communication platforms delivered through browser and mobile endpoints. Demand concentrates among United States financial services institutions consolidating fragmented pandemic-era point solutions into governed enterprise stacks, driven by SEC record-keeping compliance requirements that mandate centralized audit trails.
- Virtual Desktops:GPU-accelerated remote workstation infrastructure requiring sub-50 millisecond latency for real-time video rendering and specialized endpoint security protocols. Financial services trading floors in New York and Chicago anchor demand, constrained by complex provisioning costs that exclude mid-market budgets.
- Document Management:Cloud-native repositories with version control and retention policy automation.
- Video Conferencing:Real-time audio-visual infrastructure with noise cancellation and transcription services.
Most installed capacity flows through Collaboration Tools. Expansion is steepest in Virtual Desktops.
Technology:
Architecture choices here determine interoperability complexity and ongoing compliance burden across multi-jurisdictional deployments.
- Cloud Computing:Dominant deployment architecture as enterprises retire on-premise Exchange and SharePoint instances, migrating to elastic compute and storage. Healthcare systems in Germany, France, and the Netherlands drive sovereign cloud configurations that satisfy GDPR data residency specifications by keeping sensitive workloads in-country.
- Artificial Intelligence:Fastest-growing segment as vendors embed generative capabilities into document creation and meeting summarization functions. Professional services firms in London and New York pilot enterprise-wide rollout after initial proof-of-concept deployments.
- IoT:Sensor networks and edge computing for smart office environmental control and occupancy analytics.
- Mobile Applications:Native and progressive web apps enabling field workforce access to enterprise systems.
Cloud Computing captures the majority of current infrastructure spend. Artificial Intelligence is gaining share fastest as generative capabilities mature.
End User:
Buyer sophistication and procurement authority vary dramatically across organizational scale and sector governance requirements.
- Corporates:Large enterprises with centralized IT governance and multi-year transformation roadmaps. Fortune 500 consolidation of vendor relationships privileges integrated platform providers, compressing supplier fragmentation visible in early pandemic procurement cycles across United States healthcare and financial services verticals.
- Remote Workers:Distributed individual contributors and contractor networks requiring zero-trust access and consumer-grade usability. Demand clusters in technology and professional services sectors with permanently hybrid workforce policies, constrained by emerging state-level biometric privacy laws that complicate authentication deployment.
- Small Enterprises:Organizations under 500 employees with limited dedicated IT staff.
- Educational Institutions:Universities and K-12 systems with seasonal usage patterns and FERPA compliance obligations.
Corporates currently account for the largest contract value concentration. Remote Workers represent the steepest expansion trajectory as hybrid policies institutionalize.
Deployment:
Data sovereignty requirements and legacy system interdependencies shape architectural decisions across regulated industries.
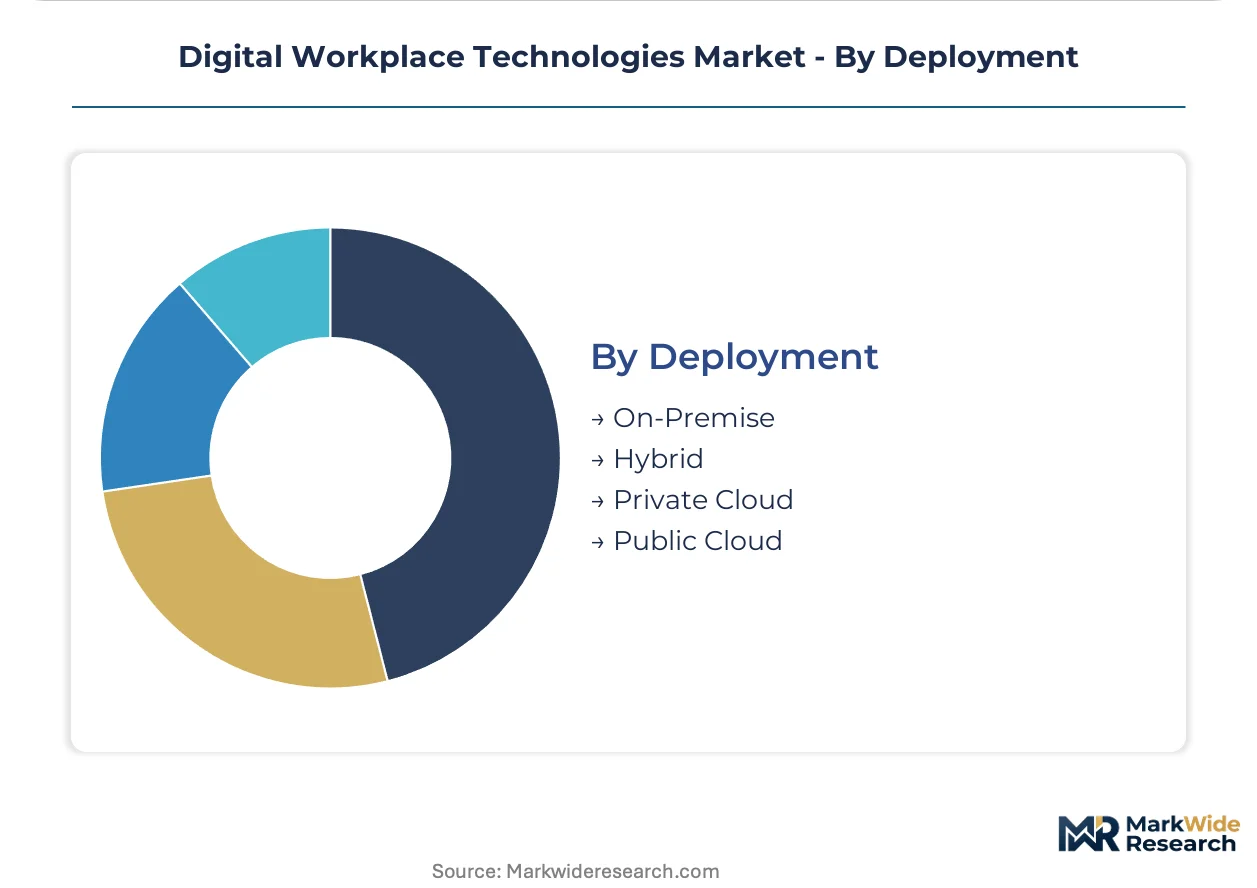
- Hybrid:Workload distribution across on-premise and cloud infrastructure with orchestration layers managing data gravity and latency requirements. European financial services institutions responding to EU AI Act risk-classification mandates favor this model for automated decision-making features that require European-resident processing.
- Public Cloud:Multi-tenant SaaS and IaaS consumption with shared responsibility security models. United States technology and media companies dominate adoption, drawn by consumption-based pricing and rapid scaling without capital commitment.
- On-Premise:Self-managed infrastructure in customer-controlled data centers.
- Private Cloud:Single-tenant cloud environments with dedicated hardware and network isolation.
Hybrid deployments carry the largest current infrastructure commitment. Public Cloud is climbing the fastest as vendor compliance certifications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services talent clusters in New York and London anchor enterprise demand for low-latency virtual desktop infrastructure. Healthcare systems in Germany and the Netherlands drive sovereign cloud procurement. Professional services firms across India and Singapore scale hybrid workforce platforms.
United States
Wall Street trading floors demand sub-50 millisecond latency for real-time video rendering on virtual desktops. SEC record-keeping rules mandate centralized audit trails that compress vendor fragmentation into governed enterprise stacks. New York and Chicago financial services clusters consolidate procurement authority into centralized IT governance functions.
Germany
Automotive and industrial conglomerates in Baden-Württemberg and Bavaria pilot generative AI document creation at enterprise scale. GDPR data residency specifications reshape cloud deployment architectures toward sovereign instances. Frankfurt and Munich healthcare systems deploy hybrid configurations that keep sensitive workloads in-country.
United Kingdom
London professional services firms embed AI meeting summarization into client-facing workflows before enterprise-wide rollout. The Information Commissioner's Office enforces biometric privacy constraints on authentication deployment. The City of London financial cluster replaces fragmented pandemic-era point solutions with unified digital workplace stacks.
India
Bangalore and Hyderabad technology campuses institutionalize permanently hybrid workforce policies at scale. The country's central bank guidelines shape data localization requirements for financial services cloud adoption. Mumbai financial services institutions leverage India-based delivery footprints for cost arbitrage on large-scale transformation contracts.
Singapore
Regional headquarters of multinational corporations demand API-level interoperability between identity management and content repositories. The Monetary Authority of Singapore imposes cybersecurity framework compliance on financial services workplace platforms. The Marina Bay financial district concentrates procurement of GPU-accelerated remote workstation infrastructure.
Digital Workplace Technologies Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across implementation and platform layers. The vendor base stratifies into three tiers: global systems integrators with captive delivery footprints, technology specialists with deep vertical integration into legacy middleware, and regional consultancies bundling deployment with optimization services. Dominant competitive moves include outcome-based consulting engagements and geographic delivery concentration for cost positioning.
Within the systems integrator tier, IBM anchors a position through mainframe-to-cloud middleware bridging legacy systems with modern endpoints. Accenture exemplifies outcome-based bundling of deployment services with ongoing platform optimization. Cognizant occupies a cost-arbitrage position leveraging India-based delivery capacity to undercut Western competitors on large-scale contracts.
| Leading Market Players |
|---|
| Atos |
| Cognizant |
| IBM |
| Wipro |
| Tata Consultancy Services |
| Infosys |
| Accenture |
| HCL Technologies |
| Capgemini |
| Others |
Supply Flow & Price Mechanics
Fortune 500 procurement consolidation into governed enterprise stacks is compressing vendor fragmentation and forcing suppliers to absorb integration costs, compressing margins on large-scale workplace transformation contracts while elevating pricing power for GPU-accelerated virtual desktop infrastructure with sub-50 millisecond latency guarantees.
Pricing Analysis
Capacity additions in India are reshaping price floors for implementation services as Cognizant, Wipro, and Tata Consultancy Services leverage Bangalore and Hyderabad delivery footprints to undercut Western systems integrators on cost. Three-tier pricing structure across premium GPU-provisioned virtual desktops, standard cloud collaboration suites, and economy SaaS modules reflects latency performance and compliance certification tiers. Pricing pressure stems from mid-market budget constraints excluding complex virtual desktop deployments. Healthcare systems in Germany and the Netherlands exhibit lowest price sensitivity due to GDPR-mandated sovereign cloud requirements.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts vendor participation in financial services procurement, concentrating qualified supply among IBM, Accenture, and India-based delivery networks. Supply concentrates in the United States for cloud infrastructure, India for implementation services, and Ireland and Singapore for EU and Asia-Pacific data residency compliance. Raw material dependencies span specialized GPU hardware from NVIDIA and AMD, enterprise identity management software from Okta and Microsoft, and fiber connectivity for latency-sensitive trading floor deployments. Single-source vulnerability in GPU provisioning elevates risk for virtual desktop infrastructure. Distribution runs through direct vendor relationships with centralized IT governance functions at Fortune 500 enterprises, displacing regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Workplace Technologies Market functions as a stable compounder anchored by regulatory mandates that perpetually refresh replacement demand across compliance-driven verticals.
For Market Incumbents: Cement platform stickiness through deep mainframe-to-cloud middleware integration that bridges legacy systems with modern collaboration endpoints, raising switching costs for financial services institutions. Capture biometric authentication certification investments ahead of emerging US state-level privacy laws. Defend against cost arbitrage competitors by embedding outcome-based consulting bundles that tie deployment services to ongoing platform optimization revenue. For New Entrants and Emerging Players: Generative AI meeting summarization capabilities offer a technology-first wedge into professional services workflows in London and New York before enterprise-wide rollout. Target mid-market healthcare systems in the United States seeking HIPAA-compliant unified stacks without Fortune 500 integration complexity. Pursue channel partnerships with sovereign cloud providers in Germany and the Netherlands to bypass direct competition with established systems integrators. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing captive GPU provisioning expertise and financial services compliance certifications. Long-term viability hinges on recurring platform optimization revenue rather than one-time deployment fees. Monitor SEC record-keeping rule enforcement intensity as an inflection indicator for replacement demand velocity in United States financial services.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | IBM's mainframe-to-cloud middleware bridges legacy systems with modern collaboration endpoints for financial services retention. |
| Geographic Expansion | Accenture's outcome-based consulting bundles in Germany and the Netherlands capture GDPR-mandated sovereign cloud demand. |
| Acquisition of Specialist Firm | GPU provisioning expertise from niche virtual desktop vendors secures sub-50 millisecond latency guarantees for trading floors. |
| Strategic Partnership | Channel alliances with biometric authentication providers span emerging US state-level privacy compliance requirements. |
| Product Launch | Generative AI document creation capabilities target professional services pilot programs in London and New York. |
Methodological Framework
Bottom-up corporate procurement modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across financial services and healthcare verticals were validated against secondary sources including SEC filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and hospital procurement databases. Top-down triangulation against vendor-reported implementation capacity in India and sovereign cloud deployments in Europe ensures coverage completeness.
Input-output matrices map deployment model, organization size, vertical integration complexity, and regional adoption pattern to derive segment-level growth trajectories across the projection horizon. CAGRs were computed from modeled annual spend flows rather than extrapolated point estimates. Forecast inputs incorporate EU AI Act risk-classification compliance timelines and NIST cybersecurity framework update cycles as demand drivers.
The model holds under stable regulatory enforcement intensity; deviation in SEC audit timeline compression or EU AI Act penalty severity would shift replacement demand velocity. A model refresh is warranted upon material change in biometric privacy law adoption rates across US states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Global E-Visa Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Inventory Management Market
Digital Solutions
Location As a Service Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Cloud Based Manufacturing Market