
 Smart Recording Pen Market | 2026-2036
Smart Recording Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Recording Pen Market Insights
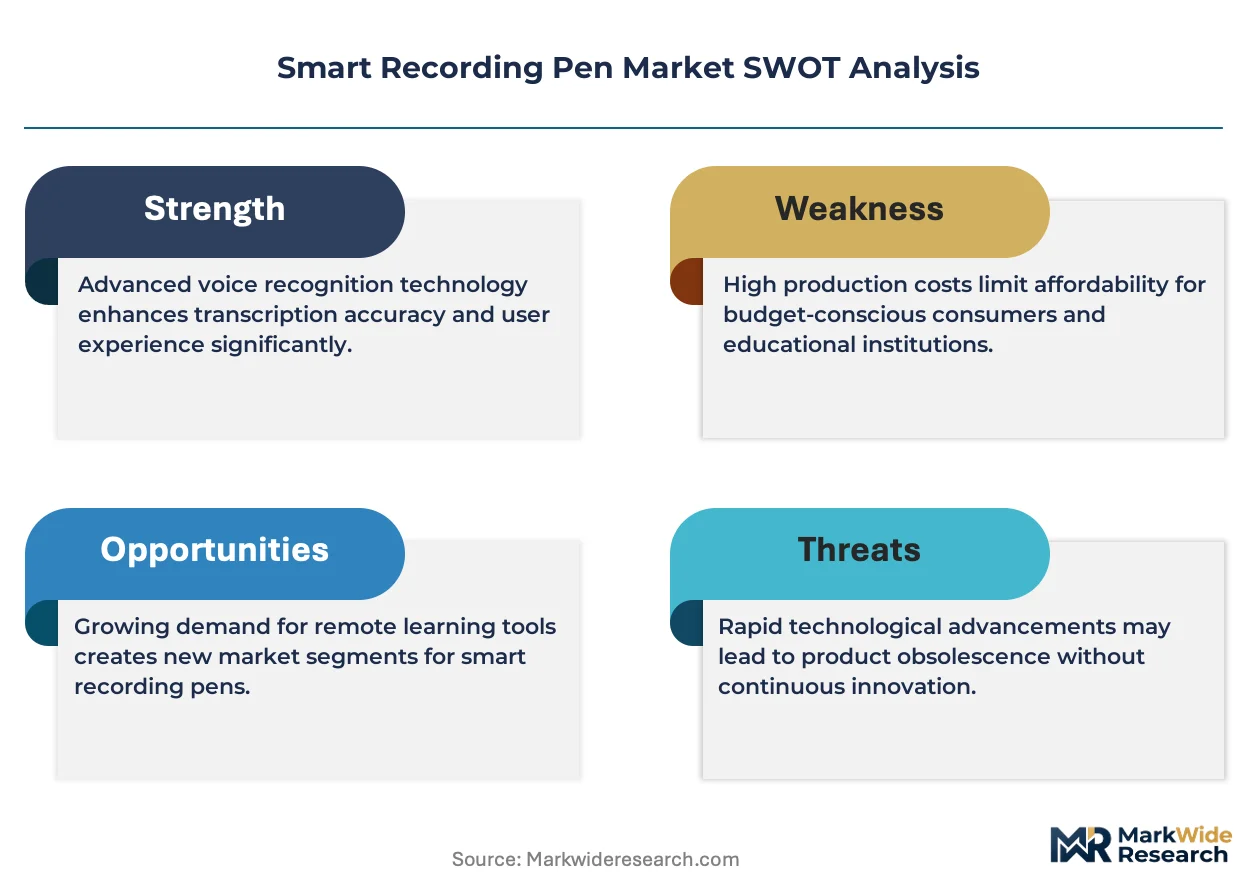
A capital-intensity divergence between established electronics conglomerates and emerging specialists is reorganizing competitive dynamics across the smart recording pen landscape. Sony leverages integrated sensor manufacturing and semiconductor design to sustain cost advantages in high-fidelity audio capture. Livescribe anchors its position through proprietary dot-pattern paper ecosystems that lock in recurring consumable revenue. Neo Smartpen competes aggressively on price while focusing narrowly on optical recognition algorithms for East Asian character sets.
A smart recording pen is a handheld digital input device combining ballpoint or stylus writing instrumentation with embedded microphones, Bluetooth or Wi-Fi transceivers, and onboard storage or cloud synchronization capability, typically capturing synchronized audio and handwritten vector data for later retrieval and transcription. The device serves commercial and educational users who require verbatim documentation of meetings, lectures, interviews, or clinical encounters without manual note reconciliation. Digital pens currently command the largest installed base among product type segments, though voice recorders with integrated AI transcription are expanding fastest as professionals abandon manual note-taking workflows. Bluetooth technology dominates connectivity implementations due to universal smartphone compatibility, while optical recognition systems retain niche dominance in markets where stylus-based character input remains culturally preferred.
The Federal Communications Commission governs wireless transmission standards for connected devices in the United States, while the EU AI Act imposes algorithmic transparency obligations on transcription software processing personal data across European markets. Japan's Ministry of Economy, Trade and Industry oversees JIS standards for electromagnetic compatibility that constrain hardware design choices for manufacturers targeting corporate procurement channels. Stakeholders must monitor evolving cross-border data residency requirements that threaten cloud-dependent transcription architectures and evaluate localized edge-processing alternatives before regulatory fragmentation hardens.
Market Dynamics
The EU AI Act's transparency mandates for automated transcription systems are forcing hardware manufacturers to redesign certification pathways and restructure software architectures before commercial deployment.
Growth Catalysts
- Voice-to-text transcription tools:Enterprise professionals in legal and healthcare sectors are abandoning manual note-taking workflows. This technology pull accelerates replacement cycles for legacy recording devices.
- Corporate digitization programs:Germany's precision manufacturing culture drives premium device uptake through procurement channels that prioritize integrated documentation systems.
- Cloud synchronization capability:Bluetooth-enabled seamless audio transfer to enterprise knowledge management platforms reduces friction in clinical encounter documentation and meeting archival.
Market Restraints
- Semiconductor supply concentration:Integrated sensor manufacturing for high-fidelity audio capture depends on concentrated East Asian foundry capacity, exposing hardware vendors to input volatility.
- Data residency fragmentation:Cross-border cloud storage restrictions threaten transcription architectures that rely on centralized processing infrastructure.
- Dot-pattern paper dependency:Proprietary consumable ecosystems lock users into recurring supply costs that standard ballpoint alternatives circumvent.
Strategic Opportunities
- Edge-processing architectures:Localized transcription computation bypasses cloud-dependent regulatory constraints while reducing latency for real-time clinical documentation.
- East Asian character recognition:Optical recognition algorithms optimized for complex script inputs address underpenetrated professional segments in Japan and South Korea.
- Wi-Fi direct connectivity:Enterprise IT departments are mandating air-gapped synchronization protocols that bypass smartphone intermediaries in sensitive legal environments.
Industry Challenges
- Algorithmic audit trails:EU AI Act compliance requires explainable transcription outputs that current black-box neural architectures cannot readily produce.
- Electromagnetic compatibility certification:JIS standards for corporate procurement channels impose lengthy hardware validation timelines that delay product launches.
- Legacy system integration:Electronic health record platforms and legal practice management software demand bespoke API development for synchronized audio-vector data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Recording Pen Market |
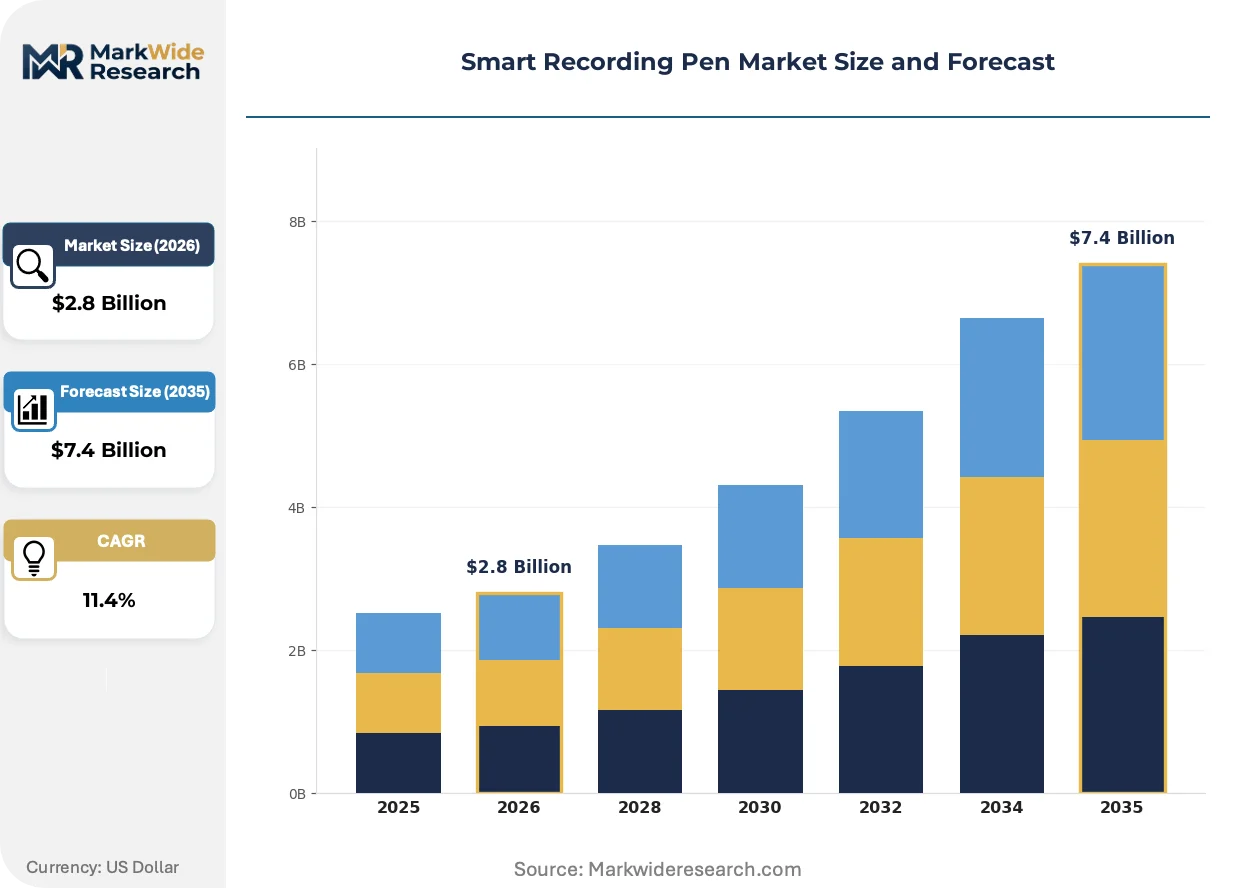
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Pens, Voice Recorders, Smart Notebooks, Accessories Technology: Bluetooth, Wi-Fi, NFC, Optical End User: Students, Professionals, Journalists, Researchers Distribution Channel: Online Retail, Offline Retail, Direct Sales, Resellers |
| Companies Covered | Livescribe, Sony, UMEVO, Rocketbook, Moleskine, Flowtica, Neo Smartpen, Yuan, Plaud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Recording Pen Market Trends and Innovations
Transcription accuracy thresholds and connectivity protocols are shifting competitive advantage from hardware fidelity toward software intelligence and seamless enterprise workflow integration.
On-device neural processing engines are supplanting cloud-dependent transcription pipelines. Legal professionals handling privileged client communications are adopting edge-computing pens that process speech locally. This architectural shift is compressing vendor margins on recurring SaaS transcription revenue while elevating upfront hardware specification requirements.
Algorithmic transparency obligations under the EU AI Act are mandating auditable decision trails for automated speech recognition systems. Hardware manufacturers must now embed logging capabilities that expose model inference steps to regulatory inspection. Medical transcription devices targeting European healthcare procurement channels are responding with open-weight local models that sacrifice marginal accuracy for inspectability.
Enterprise procurement departments are consolidating vendor relationships around integrated documentation platforms rather than discrete hardware purchases. Value-added resellers and specialized IT distributors are displacing consumer electronics retail as the primary channel for professional-grade recording pens. Germany's corporate digitization programs exhibit this pattern most acutely, with centralized IT procurement mandating fleet management and standardized security protocols.
Smart Recording Pen Market Segmentation
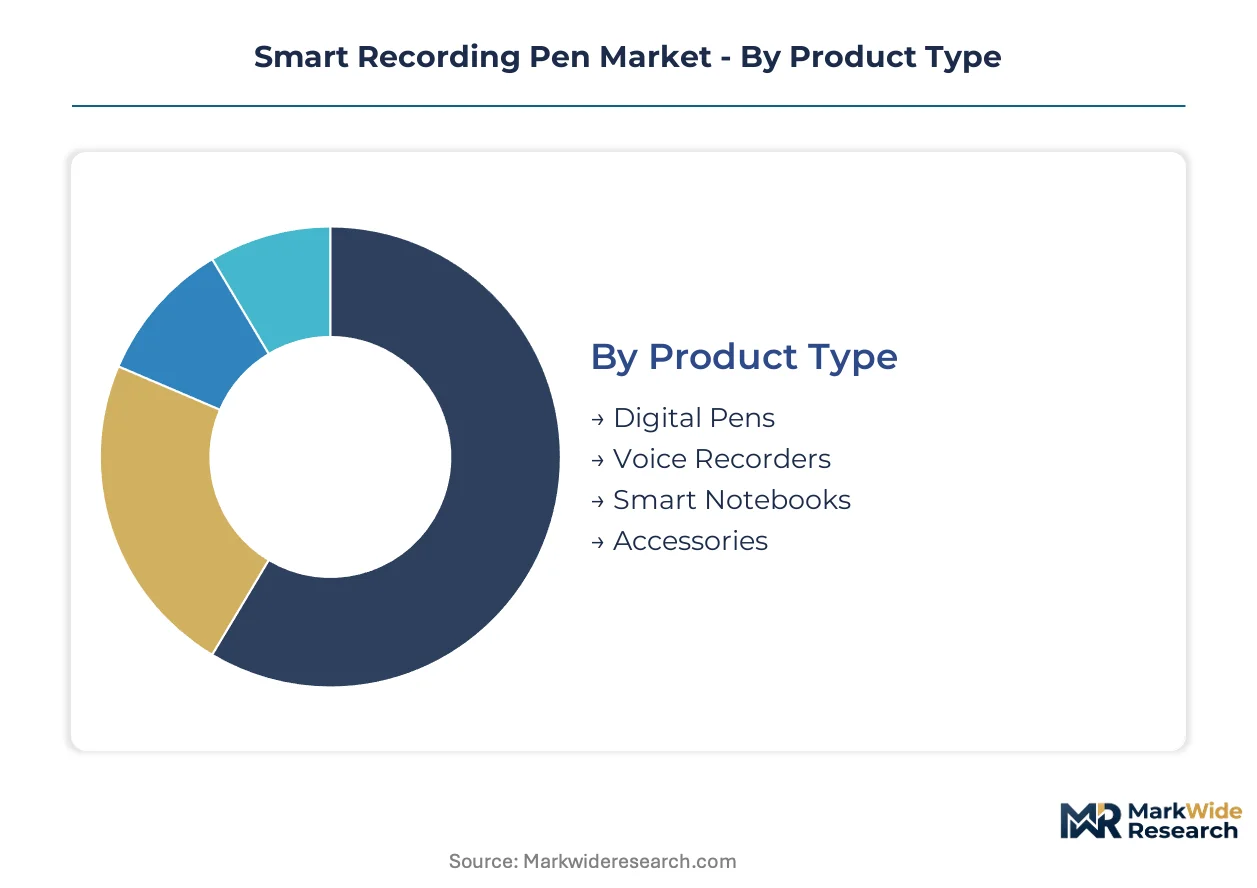
Segmentation in the smart recording pen market reveals divergent vulnerability to substitution from smartphone apps and cloud-based transcription services. Hardware categories face distinct competitive pressures based on their integration depth with enterprise workflows and consumable dependencies.
Product Type:
Digital pens confront the most acute substitution threat from stylus-enabled tablets and native handwriting recognition apps, while voice recorders with embedded AI transcription defend position through specialized audio fidelity that consumer devices cannot replicate.
- Digital Pens:These devices combine ballpoint or stylus instrumentation with embedded microphones and optical sensors to capture synchronized handwritten vector data and audio streams. Demand concentrates in German corporate procurement channels where precision documentation culture and fleet management standardization override consumer-grade alternatives. Dot-pattern paper ecosystems lock in recurring consumable revenue but expose users to supply chain concentration risks.
- Voice Recorders:Dedicated hardware with integrated neural processing engines for local transcription bypasses cloud-dependent regulatory constraints under the EU AI Act. Legal professionals handling privileged communications in the United States drive uptake through HIPAA-aligned edge-computing architectures that smartphones cannot replicate.
- Smart Notebooks:Bound paper systems with embedded sensor arrays bridge analog writing habits with digital capture workflows.
- Accessories:Replacement cartridges, charging docks, and proprietary paper refills generate recurring revenue streams.
Digital pens anchor the volume base while voice recorders gain share at the steepest rate as enterprise professionals abandon manual note-taking workflows.
Technology:
Connectivity protocols segment by enterprise IT security mandates and latency requirements, with cost tiers separating consumer convenience from professional compliance.
- Bluetooth:Universal smartphone compatibility drives the largest installed base among connectivity implementations, though enterprise IT departments increasingly restrict Bluetooth-enabled devices in sensitive legal environments due to interception vulnerabilities.
- Wi-Fi:Direct synchronization protocols bypass smartphone intermediaries and satisfy air-gapped requirements in corporate and clinical settings. German precision manufacturing procurement channels prioritize Wi-Fi direct for integrated documentation systems.
- NFC:Near-field pairing enables rapid device authentication and localized data transfer without persistent network connections.
- Optical:Pattern recognition systems retain dominance in East Asian markets where stylus-based character input remains culturally preferred.
Bluetooth sustains the broadest compatibility footprint while Wi-Fi direct climbs the fastest as enterprise security protocols harden.
End User:
Professional application intensity determines margin capture, with volume concentration in education segments and value concentration in regulated industries.
- Students:Price-sensitive demand favors basic digital pens with cloud synchronization for lecture capture. Japanese university procurement channels under METI oversight drive standardization around electromagnetic compatibility certification.
- Professionals:Legal and healthcare practitioners in Germany and the United States command premium pricing for edge-processing transcription devices that satisfy EU AI Act transparency mandates and HIPAA privacy requirements.
- Journalists:Field reporting applications prioritize ruggedized hardware with extended battery life and offline operation.
- Researchers:Academic interview documentation requires verbatim accuracy and multilingual transcription support.
Students anchor the volume base while professionals generate the steepest value expansion as regulatory compliance premiums harden.
Distribution Channel:
Channel structure reflects the shift from consumer electronics retail toward enterprise procurement integration, with margin concentration in direct relationships and volume concentration in scaled platforms.
- Online Retail:E-commerce platforms capture student and individual professional demand through price transparency and review aggregation. German corporate digitization programs are displacing this channel for fleet purchases.
- Offline Retail:Consumer electronics stores and office supply chains serve impulse purchases and gift markets.
- Direct Sales:Vendor relationships with enterprise IT departments enable customized security protocols and API integration for electronic health record platforms. Value-added resellers in the United States legal sector consolidate around integrated documentation platforms.
- Resellers:Specialized IT distributors displace retail for professional-grade deployments with standardized fleet management.
Online retail anchors the volume base while direct sales expands most quickly as enterprise procurement consolidates around integrated vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's precision manufacturing corridors while volume manufacturing gravitates toward East Asian electronics clusters. This asymmetry creates divergent margin structures across procurement channels. Regulatory fragmentation around data residency and algorithmic transparency is hardening competitive moats in European markets.
Germany
Corporate digitization programs and fleet management standardization drive premium device uptake through centralized IT procurement. The EU AI Act mandates algorithmic audit trails for transcription software processing personal data. Bavaria's precision manufacturing culture anchors demand for integrated documentation systems in automotive and industrial engineering headquarters.
United States
Legal professionals handling privileged client communications and HIPAA-aligned healthcare documentation expand edge-computing adoption. The FCC governs wireless transmission standards for Bluetooth and Wi-Fi implementations in connected devices. Greater Boston's healthcare technology cluster and Silicon Valley's enterprise software corridors concentrate procurement for transcription-integrated workflows.
Japan
University procurement channels and corporate documentation culture sustain demand for stylus-based optical recognition systems. METI oversees JIS standards for electromagnetic compatibility that constrain hardware design for corporate buyers. Tokyo-Osaka corridor electronics distributors prioritize devices with localized edge-processing to satisfy data sovereignty expectations.
South Korea
Enterprise professionals in technology and financial services sectors adopt voice-to-text tools for meeting documentation. National data residency requirements pressure vendors to deploy localized transcription infrastructure. Seoul Capital Area conglomerates mandate air-gapped synchronization protocols that bypass cloud intermediaries in sensitive environments.
China
Domestic electronics manufacturing ecosystems and university research documentation drive volume demand for cost-optimized digital pens. MIIT oversees GB standards for wireless transmission and electromagnetic compatibility. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate optical sensor and microphone component supply for regional brands.
Smart Recording Pen Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that leverage integrated sensor manufacturing and semiconductor design capabilities. The vendor base spans three tiers: established technology multinationals with captive component supply, specialized digital stationery firms with proprietary consumable ecosystems, and emerging hardware startups focused on edge AI transcription. Strategic moves center on backward integration into sensor fabrication and technology licensing partnerships for optical recognition algorithms.
Among diversified technology conglomerates, Sony exemplifies the integrated manufacturing archetype through captive semiconductor and sensor operations. Livescribe and Neo Smartpen occupy positions within the specialized digital stationery tier, with the former anchoring proprietary consumable revenue models and the latter representing aggressive price positioning on optical recognition specialization. These three companies illustrate the competitive divergence between scale-driven component integration and niche algorithmic focus.
| Leading Market Players |
|---|
| Livescribe |
| Sony |
| UMEVO |
| Rocketbook |
| Moleskine |
| Flowtica |
| Neo Smartpen |
| Yuan |
| Plaud |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with East Asian foundries lock in semiconductor access and stabilize component pricing for hardware manufacturers navigating volatile sensor markets. These arrangements bind transcription device vendors to minimum volume commitments while insulating them from spot-market spikes in microphone MEMS and optical sensor inputs.
Pricing Analysis
The customization-premium spread separates standard Bluetooth-enabled digital pens from configured-to-order edge-processing devices with local neural engines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and integration depth, with EU AI Act-compliant transcription systems commanding substantial premiums. Cost compression in the economy tier intensifies as smartphone substitution erodes basic voice recorder positioning. Students exhibit the highest price sensitivity, while German corporate procurement channels prioritize fleet standardization over unit cost.
Supply Chain Analysis
Taiwan Strait transit routes underpin concentrated semiconductor fabrication for audio DSP chips and neural processing units. Manufacturing gravity centers on China for optical sensor assembly, South Korea for memory components, and Japan for precision microphone elements. Single-source vulnerability in dot-pattern paper substrates exposes Livescribe-compatible vendors to proprietary supply constraints. Distribution runs through enterprise IT resellers and specialized stationery distributors rather than consumer electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcription accuracy subscriptions and fleet management services are expanding faster than hardware unit sales, converting one-time device purchases into recurring revenue architectures. This service-attach dynamic rewards vendors who embed software layers deeply into enterprise documentation workflows.
For Market Incumbents: Fortify proprietary consumable ecosystems through backward integration into dot-pattern paper manufacturing, neutralizing supply disruption risks from sole-source dependencies. Sony should extend captive sensor fabrication into edge-AI chip design, preempting emerging entrants from matching hardware-software integration depth.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships accelerates European market access before EU AI Act audit trail requirements harden. White-space concentration sits in South Korean financial services procurement, where air-gapped Wi-Fi direct protocols remain underpenetrated by established brands.
For Investors and Strategic Acquirers: Capital is best deployed toward optical recognition specialists with East Asian character set expertise and localized edge-processing capabilities. The signal to watch is German corporate IT procurement consolidation around integrated documentation platforms with mandatory fleet management.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Integration | Local transcription processing satisfies EU AI Act transparency mandates without cloud dependency. |
| Optical Recognition Licensing | East Asian character algorithm partnerships unlock Japan and South Korea corporate procurement channels. |
| Proprietary Paper Backward Integration | Captive dot-pattern substrate production secures recurring consumable margins against supply disruption. |
| Enterprise Reseller Consolidation | Value-added IT distributors displace retail for professional-grade fleet deployments with standardized security. |
| Wi-Fi Direct Certification | Air-gapped synchronization protocols meet HIPAA-aligned healthcare documentation requirements in legal environments. |
Research Methodology
Initial hypotheses were tested against primary input from enterprise IT procurement officers, legal practice technology directors, healthcare clinical documentation leads, and optical recognition R&D engineers and refined through secondary validation. Primary fieldwork combined structured interviews with transcription device vendors and enterprise deployment case studies. Secondary sources encompassed FCC equipment authorization databases, EU AI Act regulatory filings, METI JIS certification records, and corporate procurement platform disclosures. Bottom-up unit economics triangulated against top-down market sizing across hardware categories and service attach rates.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and technology substitution effects. Segmentation modeling spans product type, connectivity protocol, end-user vertical, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves calibrated to replacement cycle acceleration and enterprise adoption inflection patterns. Forecast inputs incorporate semiconductor foundry capacity expansion timelines and cloud-to-edge architectural migration rates.
The analysis sits within stated boundaries; outcomes outside sustained enterprise digitization investment and stable cross-border data flow regimes would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and component supply normalization. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and East Asian foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
System Integrator Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Kazakhstan ICT Market