
 Ad Network Software Market | 2026-2036
Ad Network Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ad Network Software Market Outlook
The shift from single-source ad serving to multi-source programmatic stacks is realigning how publishers monetize inventory. Google AdMob leverages its SDK penetration across mobile app ecosystems to sustain developer loyalty. Media.net competes through contextual targeting specialization that reduces reliance on third-party identifiers. PropellerAds anchors its position in emerging market traffic arbitrage where fill-rate optimization commands premium pricing.
Ad network software constitutes a technology layer that automates the matching, auctioning, and delivery of digital advertising impressions between supply-side publishers and demand-side buyers, operating through real-time bidding protocols with sub-100-millisecond latency requirements. Its primary commercial purpose is to maximize yield per impression while reducing manual insertion-order workflows. Cloud-based deployment models now dominate enterprise adoption because elastic infrastructure costs align with campaign volatility. Mobile advertising represents the fastest-expanding solution type as in-app programmatic budgets displace mobile web spending. API-based integration is maturing fastest among mid-market publishers seeking direct demand-path optimization without engineering overhead.
The Federal Trade Commission scrutinizes data broker practices that underpin audience extension products, while the EU's Digital Markets Act imposes interoperability mandates on gatekeeper platforms that control ad tech stacks. These frameworks elevate compliance costs for cross-border campaigns but create market access for independent verification vendors. Stakeholders must monitor regulatory fragmentation between Washington and Brussels as divergent privacy enforcement timelines fragment addressable audience pools.
Market Dynamics
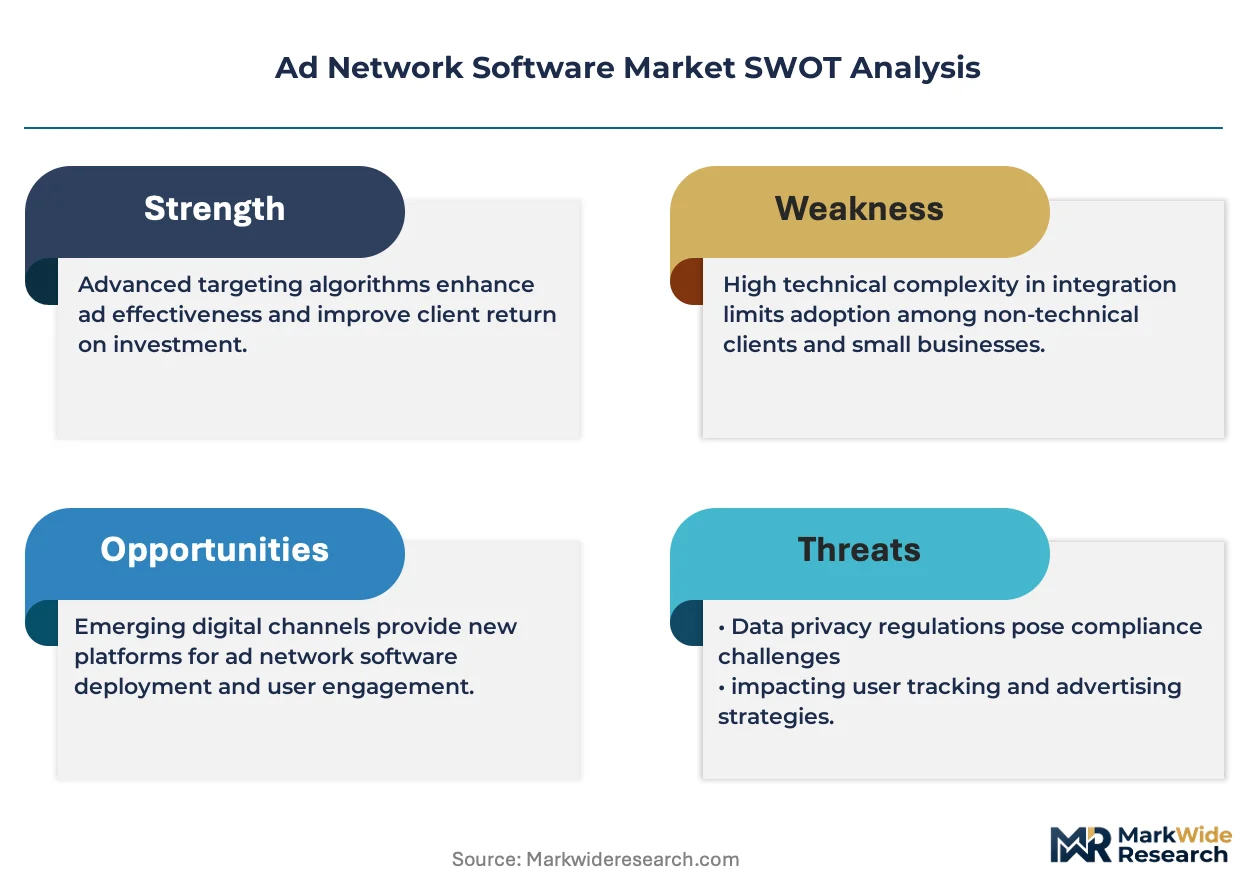
The deprecation of third-party cookies across Chrome, Safari, and Firefox is forcing ad network software vendors to rebuild attribution engines around first-party data graphs and contextual signals. This structural rupture is redistributing competitive advantage toward publishers with authenticated user bases and retail media networks with closed-loop transaction data.
Growth Catalysts
- Retail media networks:Walmart, Target, and Kroger are licensing their first-party purchase data to brand advertisers, creating closed attribution loops that bypass cookie-dependent measurement. This inventory category commands CPM premiums and attracts FMCG budgets previously allocated to open-web programmatic.
- Privacy Sandbox APIs:Google's Topics API and Attribution Reporting API provide privacy-preserving alternatives to cross-site tracking, enabling continued behavioral targeting without device-level identifiers. Early adopters among publisher networks are rebuilding yield optimization around these signals.
- Connected TV (CTV) inventory expansion:Streaming platforms are opening ad slots to programmatic demand through private marketplace deals. Ad network software vendors are integrating SSAI (server-side ad insertion) protocols to capture CTV budgets migrating from linear television.
Market Restraints
- Cloud infrastructure cost concentration:AWS, Google Cloud, and Microsoft Azure control the elastic compute layers underlying real-time bidding infrastructure. Bid processing latency requirements below 100 milliseconds prevent meaningful multi-cloud redundancy, creating vendor lock-in risk.
- Identity fragmentation:The absence of a unified post-cookie identifier across Safari, Chrome, and Firefox forces advertisers to maintain parallel targeting stacks. This technical limitation inflates campaign management overhead and depresses addressable audience scale.
- FTC data broker scrutiny:The Federal Trade Commission's enforcement actions against audience extension products are elevating legal review costs for data onboarding partnerships. Cross-border campaigns face divergent consent requirements that complicate unified targeting.
Strategic Opportunities
- Commerce media in Latin America:Mercado Libre and regional grocery chains are underpenetrated by specialized ad network infrastructure. Vendors with localized payment integration and Spanish/Portuguese language support can capture retail media budgets before global platforms establish dominance.
- AI-driven creative optimization:Generative models for dynamic creative assembly are converging with real-time bidding protocols. Networks that integrate Midjourney-style image generation and copy variation engines can offer performance guarantees that static creative cannot match.
- EU Digital Markets Act interoperability:Gatekeeper platforms must open advertising interfaces to third-party verification. Independent ad tech vendors can wedge into measurement and attribution workflows previously controlled by vertically integrated platforms.
Industry Challenges
- Data engineering talent scarcity:Real-time bidding infrastructure requires specialized expertise in distributed systems and low-latency databases. Recruitment competition from fintech and gaming sectors inflates compensation costs for platform engineering teams.
- Legacy SSP integration complexity:Publisher clients operate heterogeneous technology stacks accumulated through years of vendor switching. API standardization remains incomplete, forcing custom engineering work for each major supply-side platform connection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ad Network Software Market |
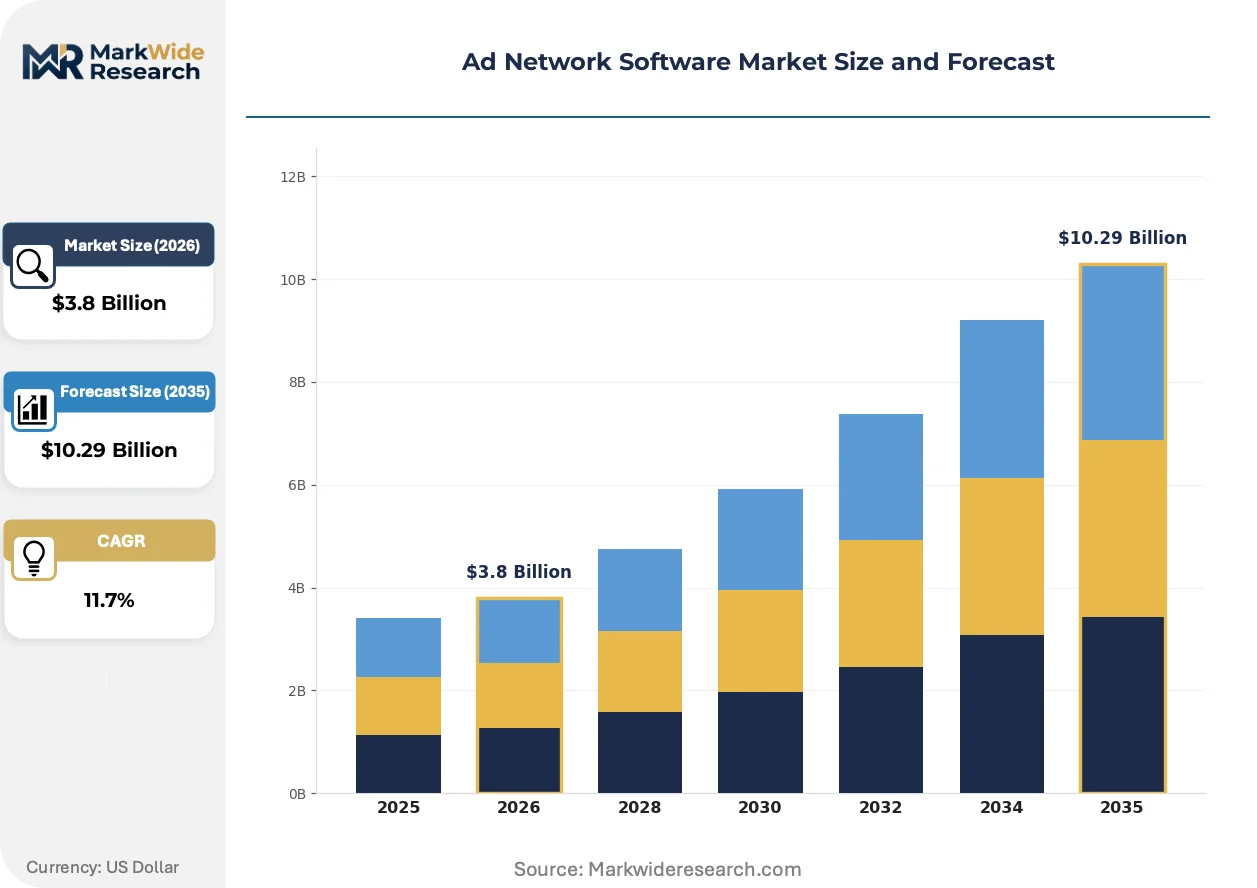
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Programmatic Ad Buying, Mobile Advertising, Video Advertising, Display Advertising Deployment Model: Cloud-Based, On-Premise, Hybrid Model, Multi-Channel User Type: Advertisers, Agencies, Publishers, Marketers Integration Type: API-Based, SDK Integration, Plug-in, Custom Integration |
| Companies Covered | Google AdMob, Google AdSense, Media.net, AdMaven, PropellerAds, RevX, EvaDav, Admixer.Network, SmartyAds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ad Network Software Market Strategic Shifts
Programmatic infrastructure is fragmenting into specialized layers as privacy constraints and channel expansion force architectural redesign. Three concurrent developments are reshaping how demand and supply connect.
Server-side header bidding is expanding into mobile in-app environments as developers reject SDK bloat that degrades user experience. Gaming publishers with sub-50MB app size constraints are adopting server-to-server auction protocols that consolidate demand sources without client-side latency. This compression of the mediation layer is enabling mid-size publishers to access demand path optimization previously requiring dedicated engineering teams.
REACH chemical safety regulations and the EU AI Act are imposing algorithmic transparency requirements on automated decision-making in ad targeting. The European Chemicals Agency's extension of substance restrictions to digital infrastructure components is affecting data center hardware procurement. Ad tech vendors with EU-domiciled processing infrastructure are responding by localizing bid processing to satisfy data residency mandates.
Brand safety verification has unbundled from media buying as procurement teams separate verification budgets from working media. Advertisers in CPG and financial services are mandating third-party impression validation through MRC-accredited vendors. This pattern is most visible in the United States, where ANA membership surveys document consistent growth in dedicated verification line items.
Ad Network Software Market Segmentation
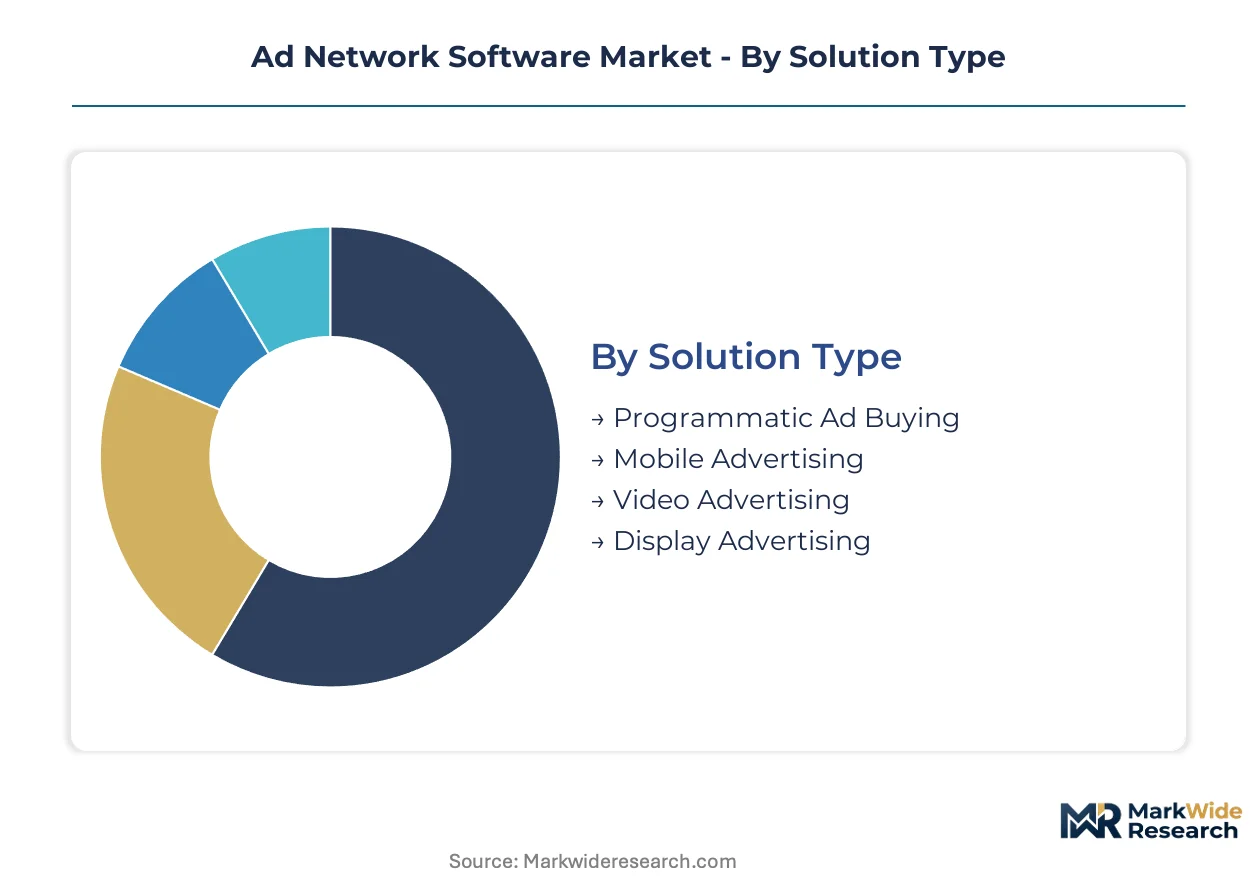
Ad network software architectures diverge sharply across deployment models and integration pathways, with capital requirements and latency constraints determining viable configurations for publishers and advertisers. Segmentation reveals how infrastructure choices lock in operational capabilities and compliance postures.
Solution Type:
Capital intensity peaks in video infrastructure, where server-side ad insertion and transcoding pipelines demand sustained engineering investment.
- Programmatic Ad Buying:Real-time bidding engines process auction decisions within 100-millisecond windows, requiring distributed compute clusters and low-latency data centers. Demand concentrates among mid-market publishers in the United States seeking demand-path optimization without building proprietary stacks.
- Mobile Advertising:In-app mediation layers manage SDK bloat constraints while consolidating demand from multiple networks. Gaming publishers with sub-50MB app size limits are driving server-to-server protocol adoption to reduce client-side overhead.
- Video Advertising:SSAI protocols and transcoding pipelines require substantial upfront infrastructure investment.
- Display Advertising:Header bidding wrappers and native ad formats dominate publisher monetization strategies.
Programmatic ad buying absorbs the bulk of installed capacity; mobile advertising is expanding most quickly.
Deployment Model:
Operational cost structures vary by elasticity requirements, with campaign volatility favoring variable-cost architectures.
- Cloud-Based:Elastic infrastructure aligns bid processing capacity with traffic spikes, eliminating stranded capital during low-volume periods. AWS, Google Cloud, and Microsoft Azure control this layer, creating vendor lock-in risk for sub-100-millisecond latency requirements.
- On-Premise:Dedicated hardware satisfies data residency mandates from EU regulators and financial services advertisers. Fixed capital commitments suit publishers with predictable traffic baselines and stringent latency requirements.
- Hybrid Model:Burst capacity to cloud during peak events while maintaining core processing on-premises.
- Multi-Channel:Unified orchestration across CTV, mobile, and desktop inventory pools.
Cloud-based deployments capture the majority of new installations; hybrid models are climbing the fastest as compliance requirements harden.
User Type:
Technical sophistication and integration budgets segment the buyer base across the advertising value chain.
- Advertisers:Direct brand teams with first-party data assets seek self-serve platforms for audience activation. CPG and retail media networks in the United States are building in-house programmatic capabilities to reduce agency fees.
- Agencies:Trading desks demand API flexibility and unified reporting across client portfolios. Consolidation pressure is forcing technology stack standardization to maintain margin.
- Publishers:Inventory owners prioritize yield optimization and header bidding management.
- Marketers:Performance-focused buyers emphasize attribution and closed-loop measurement.
Agencies retain the largest installed base; advertisers are gaining share fastest as brand teams internalize programmatic expertise.
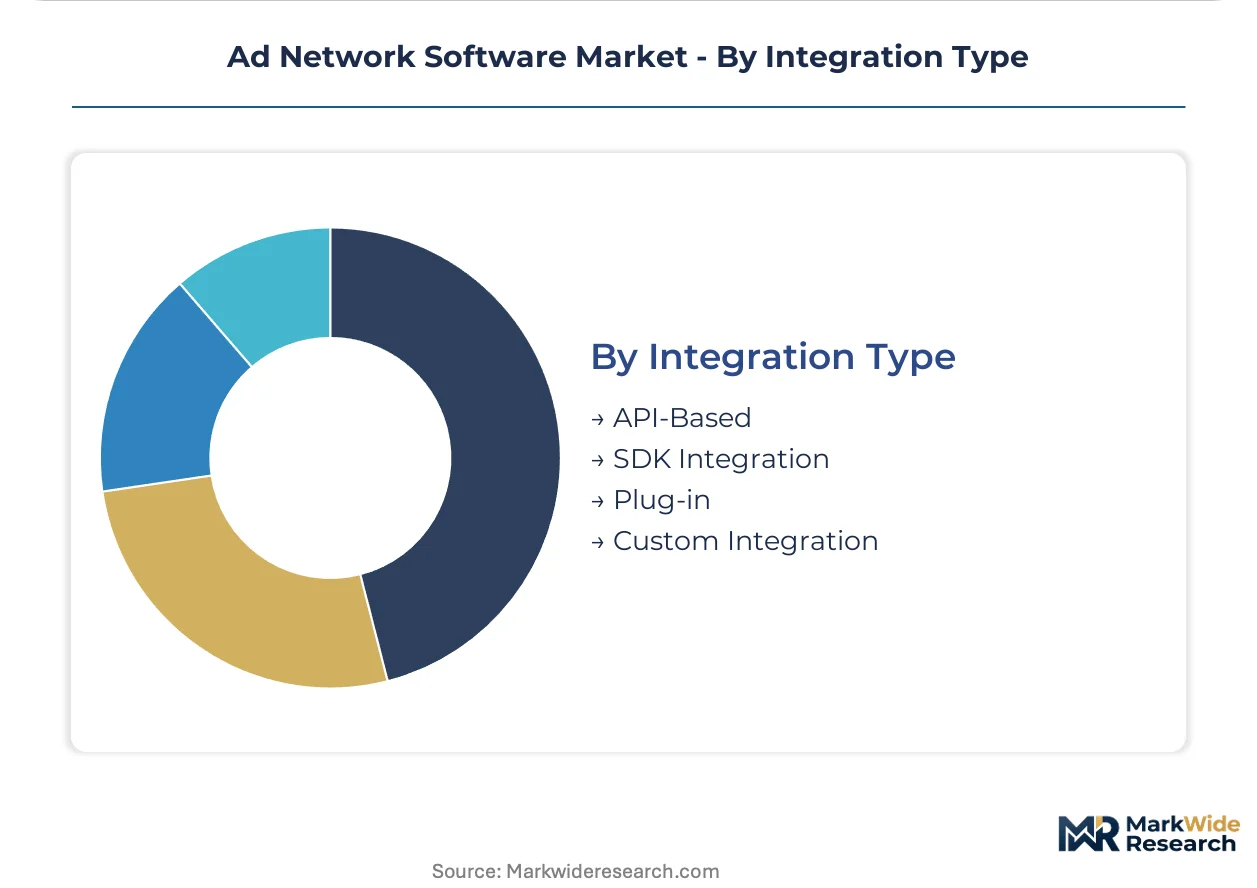
Integration Type:
Engineering resource constraints determine viable connection methods for publishers with heterogeneous technology stacks.
- API-Based:REST and gRPC interfaces enable direct demand-path optimization without SDK bloat. Mid-market publishers with limited engineering headcount are adopting API-first platforms to bypass custom integration complexity.
- SDK Integration:Native mobile libraries provide deep device-level signals for targeting and attribution. Gaming and app developers prioritize lightweight SDKs that preserve user experience metrics.
- Plug-in:Pre-built connectors for major content management and ad serving platforms.
- Custom Integration:Bespoke engineering for publishers with legacy SSP stacks accumulated through years of vendor switching.
SDK integration holds the dominant installed footprint; API-based connections are expanding most rapidly among resource-constrained publishers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center clusters in Northern Virginia and Frankfurt anchor the infrastructure layer for real-time bidding operations, while Singapore and Mumbai process emerging market traffic. Cloud region density determines latency performance for sub-100-millisecond auction requirements.
United States
Connected TV inventory expansion and retail media network adoption drive enterprise software procurement. The FTC scrutinizes data broker practices under Section 5 enforcement, elevating compliance costs for cross-border campaigns. Northern Virginia's data center corridor hosts the majority of programmatic infrastructure for North American traffic.
Germany
Automotive and industrial advertisers demand privacy-compliant attribution tools as first-party data strategies replace cookie-dependent targeting. The EU Digital Markets Act imposes interoperability mandates on gatekeeper platforms controlling ad tech stacks. Frankfurt's financial services cluster generates specialized demand for on-premise deployment models satisfying data residency requirements.
United Kingdom
Agency trading desks and publisher networks prioritize API-based integration to reduce engineering overhead. The Information Commissioner's Office enforces GDPR consent requirements that fragment addressable audience pools. London's advertising technology cluster concentrates vendor headquarters and venture capital for ad tech startups.
Japan
Mobile gaming publishers with sub-50MB app size constraints drive server-to-server protocol adoption for in-app mediation. METI guidelines on data governance influence enterprise procurement standards for cloud-based deployments. Tokyo's digital entertainment district hosts specialized vendors serving the mobile advertising segment.
Brazil
Commerce media opportunities in regional grocery chains remain underpenetrated by specialized ad network infrastructure. ANVISA regulations on health-related advertising impose content verification requirements for pharmaceutical campaigns. São Paulo's e-commerce corridor attracts platform investment for Latin American market expansion.
Ad Network Software Market Competitive Environment
Global majors compete with regional champions across infrastructure scale and localization depth. The vendor base clusters around three strategic tiers: cloud-native platforms with elastic compute advantages, contextual targeting specialists reducing third-party identifier dependence, and emerging market arbitrage networks optimizing fill rates. M&A activity concentrates on first-party data assets and SSAI technology capabilities. Strategic partnerships between publishers and retail media networks bypass traditional ad tech intermediaries.
Within the contextual specialization tier, Media.net exemplifies publisher-centric targeting approaches that reduce reliance on cross-site tracking. PropellerAds occupies a position among traffic arbitrage specialists serving emerging market inventory pools. Google AdMob and Google AdSense represent the scale-driven infrastructure tier, leveraging SDK penetration across mobile ecosystems to sustain developer platform loyalty. These three archetypes illustrate how competitive positioning fragments across technical specialization, geographic focus, and vertical integration depth.
| Leading Market Players |
|---|
| Google AdMob |
| Google AdSense |
| Media.net |
| AdMaven |
| PropellerAds |
| RevX |
| EvaDav |
| Admixer.Network |
| SmartyAds |
| Others |
Value Chain & Pricing Dynamics
Server-side ad insertion protocols are compressing infrastructure cost curves while concentrating supply-side bargaining power among cloud hyperscalers. This technical transition simultaneously elevates capital barriers for new entrants and locks incumbent platforms into elastic compute contracts that reshape margin structures.
Pricing Analysis
Warranty and service bundling separates premium ad network vendors from economy-tier competitors, with SLA guarantees and dedicated support engineering commanding substantial premiums. Pricing stratifies across premium, standard, and economy tiers based on latency performance guarantees and data residency certifications. Cost compression in the economy tier is intensifying because AWS, Google Cloud, and Microsoft Azure dominate underlying compute costs. Mid-market publishers with limited engineering headcount exhibit highest price sensitivity, while enterprise retail media networks prioritize compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements for bid processing infrastructure mandate multi-cloud qualification among publishers with sub-100-millisecond latency mandates. Supply concentrates in the United States, Ireland, and Singapore where hyperscaler data center density anchors real-time bidding operations. Raw material dependencies center on specialized silicon for AI inference acceleration, high-bandwidth networking equipment, and EU-compliant server hardware. Single-source vulnerability pervades the cloud infrastructure layer where AWS, Google Cloud, and Microsoft Azure control elastic compute. Distribution runs through direct enterprise sales teams and channel partners serving mid-market publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-party data graphs are displacing cookie-dependent attribution engines, forcing stakeholders to rebuild technology stacks around authenticated user bases and contextual signals.
For Market Incumbents: Acquire specialized server-side ad insertion technology capabilities to defend against streaming platform vertical integration. Consolidate first-party data assets through strategic partnerships with retail media networks before Walmart and Target lock exclusive attribution loops. Invest in EU-domiciled processing infrastructure to satisfy Digital Markets Act interoperability mandates and data residency requirements.
For New Entrants and Emerging Players: The price-point gap between premium latency-optimized platforms and economy-tier self-serve tools creates white-space opportunity in Latin American commerce media. Target Mercado Libre and regional grocery chains with localized payment integration and Spanish/Portuguese language support before global platforms establish dominance. Pursue API-first go-to-market positioning that bypasses SDK bloat constraints for gaming publishers with sub-50MB app size limits.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking first-party data assets and SSAI technology capabilities. Long-term viability hinges on privacy-compliant attribution infrastructure that survives regulatory fragmentation between Washington and Brussels. Monitor Digital Markets Act enforcement timelines as the critical inflection signal for independent verification vendor market access.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Asset Acquisition | Retail media networks like Walmart and Target are licensing purchase data to brand advertisers, creating closed attribution loops. |
| SSAI Technology Integration | Streaming platforms opening ad slots to programmatic demand require server-side ad insertion protocols for CTV budget capture. |
| EU Infrastructure Localization | Frankfurt data centers satisfy Digital Markets Act interoperability mandates and data residency requirements for financial services advertisers. |
| API-First Platform Development | Mid-market publishers with limited engineering headcount seek direct demand-path optimization without SDK bloat. |
| Privacy Sandbox API Adoption | Google's Topics API and Attribution Reporting API enable continued behavioral targeting without device-level identifiers. |
Study Parameters
Independent corroboration across programmatic platform executives, publisher monetization leads, and ad tech engineering directors underwrites the qualitative findings. Primary interviews with supply-side platform operators, demand-side trading desk managers, and retail media network technology officers combined with secondary validation from SEC filings, App Annie mobile intelligence data, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model adoption rates and top-down validation against cloud infrastructure spending patterns anchored the market sizing.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include deployment model elasticity, integration complexity tiers, and regional regulatory cluster variations. CAGRs derived from elasticity-adjusted spend trajectories incorporate real-time bidding volume growth, retail media network expansion rates, and privacy-compliant attribution tool replacement cycles.
Underlying measurement precision varies by segment; cloud-based deployment models carry tighter precision than on-premise installations where data residency mandates fragment reporting. Forecasts reflect assumptions about Chrome third-party cookie deprecation timelines and Digital Markets Act enforcement intensity. Deviation in Privacy Sandbox API adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Enterprise Mobility in Manufacturing Market