
 Application Performance Management Market | 2026-2036
Application Performance Management Market Size, Share, and Industry Trends Forecast 2026-2036
Application Performance Management Market Analysis
Enterprise-grade observability with sub-second latency thresholds is redrawing competitive boundaries in application performance management. Datadog leverages its cloud-native architecture to dominate multi-environment monitoring. Splunk APM anchors its position through deep log analytics integration. Dynatrace sustains technology leadership via autonomous AI-driven root cause analysis.
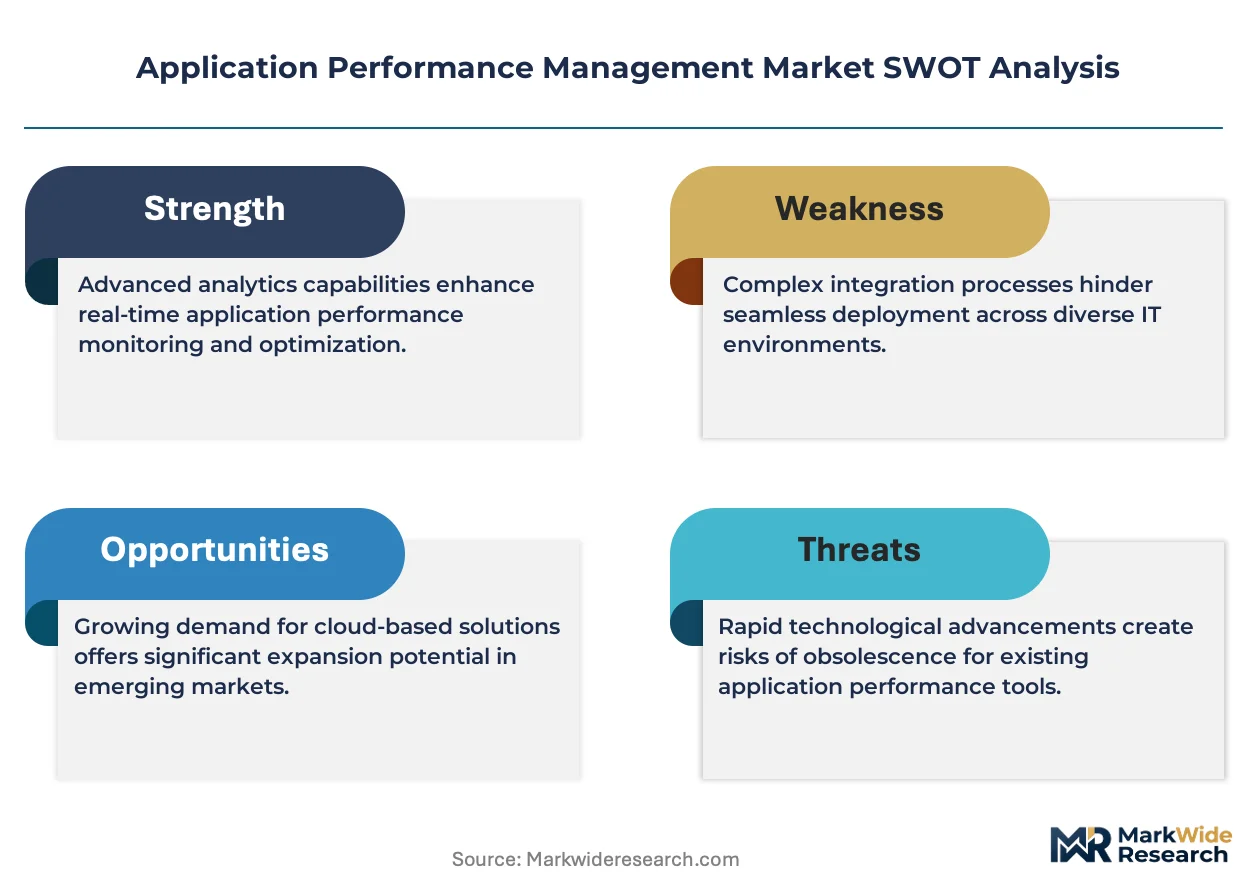
Application performance management encompasses software systems that measure, monitor, and optimize application responsiveness, throughput, and error rates through distributed tracing, code-level diagnostics, and infrastructure correlation. These platforms ingest telemetry from servers, containers, databases, and networks to maintain service-level objectives in complex IT estates. The solution dimension shows monitoring tools commanding the largest installed base while analytics platforms capture expanding margin pools as enterprises prioritize predictive insight over reactive alerting. Hybrid cloud deployment presents the steepest growth trajectory as organizations balance elasticity requirements with data residency constraints.
FCC guidelines on telecommunications reliability, SEC disclosure requirements for financial system uptime, and HIPAA safeguards for healthcare data integrity collectively elevate APM from operational convenience to regulatory necessity. ISO 27001 and SOC 2 frameworks further harden procurement criteria, channeling enterprise budgets toward certified vendors. Stakeholders must weigh the pace of AI-infused automation against persistent skills shortages in distributed systems engineering.
Market Dynamics
Container orchestration and microservices architecture are compressing observability requirements into sub-second latency thresholds, forcing enterprises to rebuild monitoring stacks around distributed tracing and infrastructure correlation rather than traditional server-centric dashboards.
Growth Catalysts
- FCC telecommunications reliability guidelines:Mandates for real-time transaction visibility in financial networks are accelerating APM procurement across banking infrastructure.
- Healthcare data integrity requirements:HIPAA safeguards for patient record systems elevate continuous monitoring from operational preference to compliance necessity.
- Cloud-native enterprise transformation:Hybrid deployment architectures in United States data centers are driving demand for cross-environment telemetry platforms.
Market Restraints
- Distributed systems engineering talent scarcity:Skills shortages in Kubernetes observability and OpenTelemetry instrumentation constrain implementation velocity.
- Data sovereignty compliance costs:Multi-region deployment requirements fragment vendor architectures and inflate operational overhead.
- Legacy monitoring sunk investment:Existing agent-based infrastructure creates switching friction that delays cloud-native migration timelines.
Strategic Opportunities
- AI-infused autonomous operations:Convergence of generative AI with causal analysis engines opens predictive remediation capabilities beyond reactive alerting.
- Edge computing observability:IoT and 5G distributed workloads create greenfield demand for lightweight telemetry agents.
- SEC disclosure mandates:Uptime reporting requirements for financial system availability create procurement tailwinds for certified APM vendors.
Industry Challenges
- OpenTelemetry standardization gaps:Incomplete instrumentation specifications force vendors to maintain proprietary agent layers alongside open-source collectors.
- Cross-functional observability silos:Fragmented ownership between DevOps, SRE, and platform engineering teams complicates unified dashboard deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Performance Management Market |
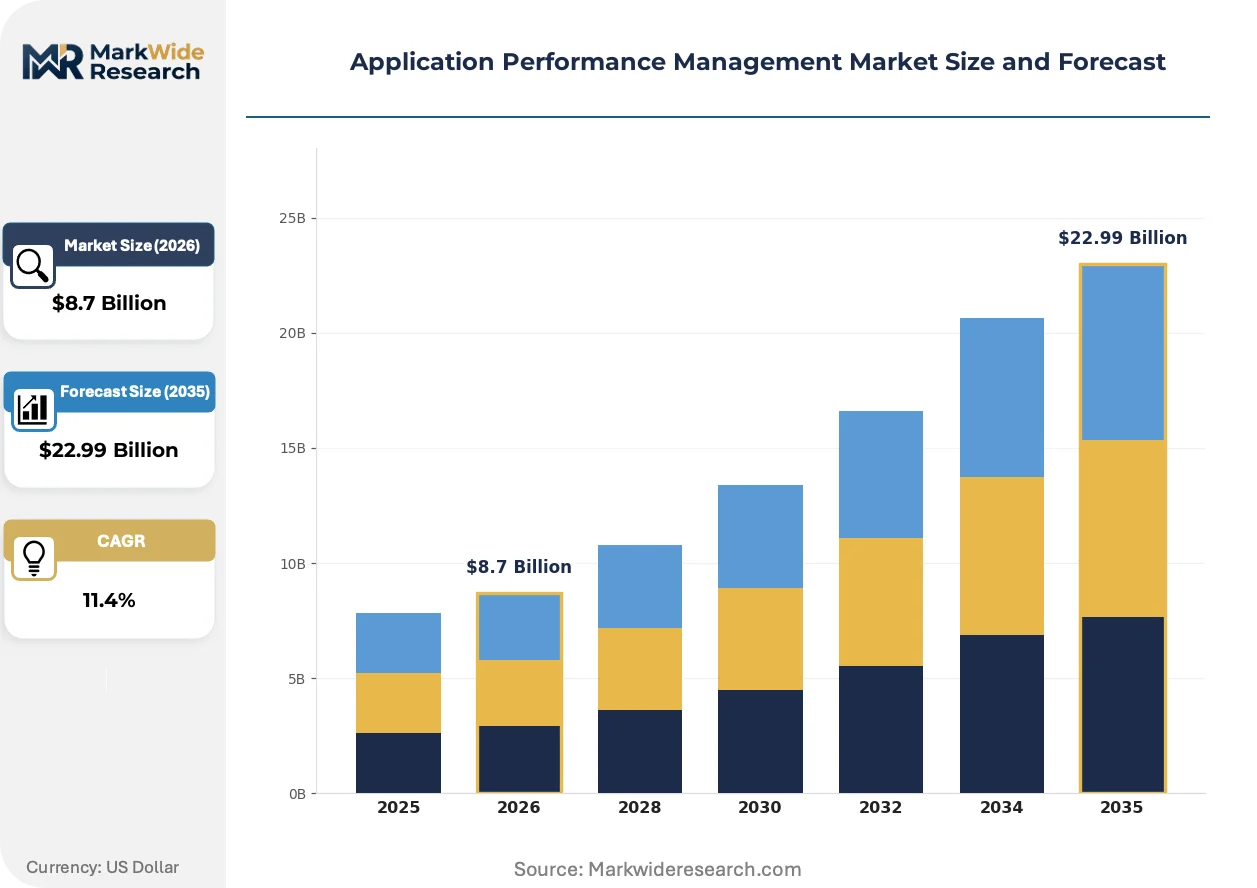
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: IT Enterprises, Telecom, Healthcare, E-Commerce Solution: Monitoring Tools, Analytics Platforms, Testing Solutions, Orchestration Software Technology: Artificial Intelligence, Machine Learning, Big Data, Microservices |
| Companies Covered | Datadog, Splunk APM, New Relic, AppDynamics, Elastic APM, Dynatrace, CubeAPM, SolarWinds, Splunk AppDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Performance Management Market Emerging Trajectories
Telemetry pipeline architectures are fragmenting into specialized layers for ingestion, processing, and visualization, with vendors racing to own the control plane while commoditizing data collection.
OpenTelemetry is bifurcating the instrumentation layer from proprietary agent ecosystems. Cloud-native enterprises in financial services and digital commerce are standardizing on vendor-neutral SDKs for custom application tracing. This shift is compressing margins for legacy agent-based pricing models while expanding addressable market for processing-layer platforms.
EU AI Act transparency requirements are mandating explainability trails for automated decision systems. Financial institutions deploying algorithmic trading and credit scoring must now maintain continuous performance audit logs. The compliance burden falls heaviest on model-serving infrastructure, where latency and drift monitoring must integrate with traditional application metrics.
Enterprise buyers are unbundling monitoring from analytics procurement, selecting best-of-breed visualization tools independent of data collection infrastructure. Managed service providers and systems integrators are capturing implementation value that previously accrued to platform vendors. This pattern is most pronounced in Germany and France, where multi-cloud strategies resist single-vendor consolidation.
Application Performance Management Market Segmentation
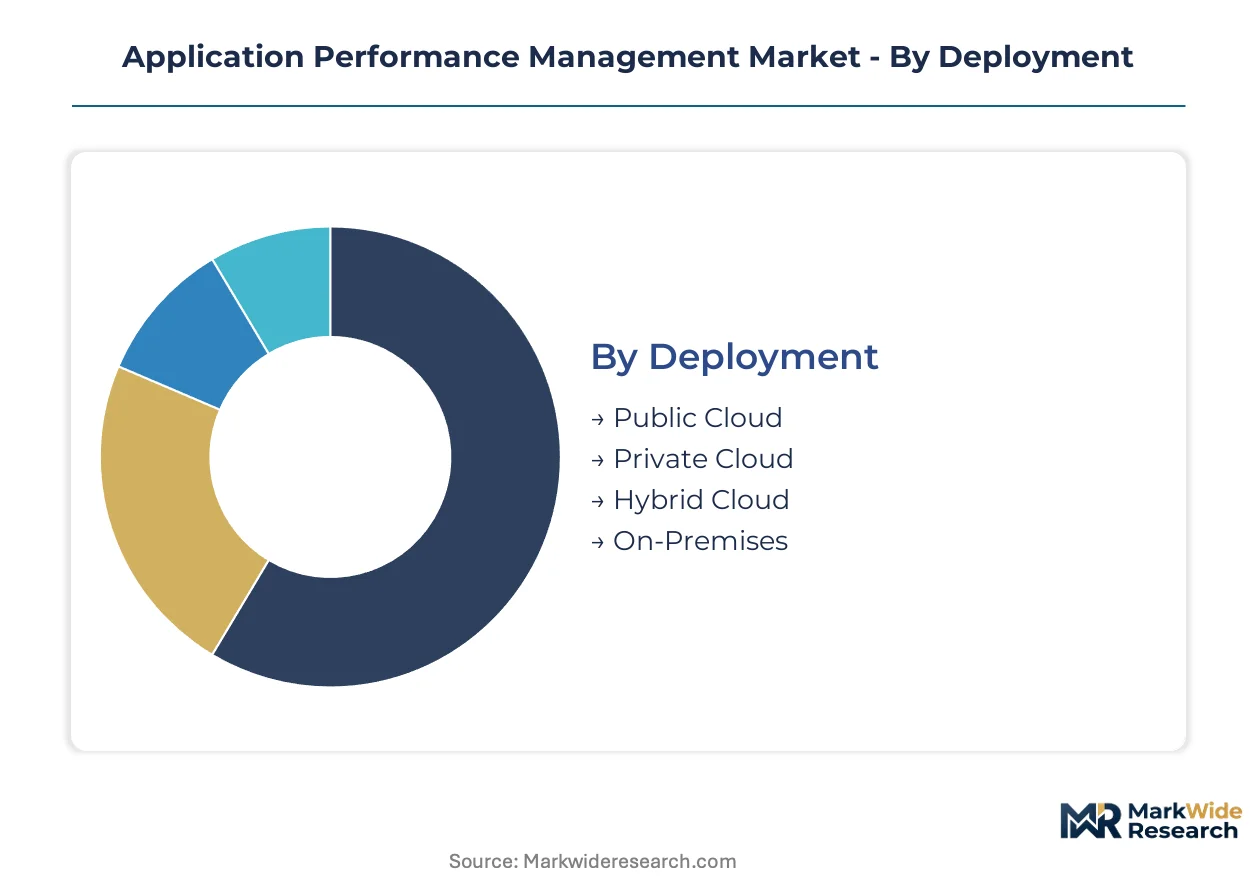
Application performance management procurement patterns diverge sharply across deployment architectures and organizational maturity. Segmentation reveals how cloud-native telemetry requirements reshape vendor selection criteria and channel economics.
Deployment:
Public cloud deployments flow through hyperscaler marketplaces and direct vendor channels, while on-premises sales cycle through systems integrators with certified implementation practices.
- Public Cloud:Multi-tenant SaaS architectures deliver elastic telemetry ingestion without infrastructure overhead. Financial services firms in the United States dominate procurement, driven by SEC uptime disclosure mandates and real-time transaction visibility requirements.
- Hybrid Cloud:Cross-environment orchestration platforms bridge sovereign data residency with burst capacity. German automotive manufacturers and French retail conglomerates anchor European demand, constrained by GDPR cross-border transfer protocols and operational sovereignty requirements.
- Private Cloud:Dedicated tenant isolation serves defense contractors and national healthcare systems with classified workload requirements.
- On-Premises:Air-gapped instrumentation persists in critical infrastructure operators with NERC CIP compliance obligations.
By volume, public cloud leads. By growth pace, hybrid cloud is expanding most quickly.
End User:
Cost tier stratification separates enterprise-grade observability budgets from mid-market self-service adoption, with telecom carriers representing the highest per-seat expenditure.
- IT Enterprises:Platform engineering teams consolidate DevOps and SRE tooling under unified FinOps governance. United States technology conglomerates drive standardization around OpenTelemetry collectors, displacing proprietary agent architectures.
- Telecom:5G core network slicing demands sub-millisecond latency telemetry at carrier scale. FCC reliability guidelines and ITU-T performance standards compel real-time infrastructure investment.
- Healthcare:HIPAA audit trails for patient-facing applications elevate continuous monitoring to compliance necessity.
- E-Commerce:Peak-load elasticity requirements favor consumption-based pricing models over perpetual licenses.
IT enterprises command the largest aggregate spend. Telecom exhibits the steepest expansion trajectory.
Solution:
Margin concentration shifts from data collection infrastructure toward predictive analytics layers as enterprises unbundle procurement.
- Monitoring Tools:Infrastructure and application metric collection forms the foundational telemetry layer. Container orchestration environments in United States cloud-native enterprises standardize on vendor-neutral instrumentation.
- Analytics Platforms:Causal analysis engines and anomaly detection algorithms capture expanding value pools. Financial services compliance teams in London and Singapore require explainable AI audit trails for algorithmic trading infrastructure.
- Testing Solutions:Synthetic transaction simulation validates service-level objectives pre-deployment.
- Orchestration Software:Automated remediation workflows integrate with ITSM platforms for closed-loop operations.
Monitoring tools retain the widest installed base. Analytics platforms are gaining share fastest.
Technology:
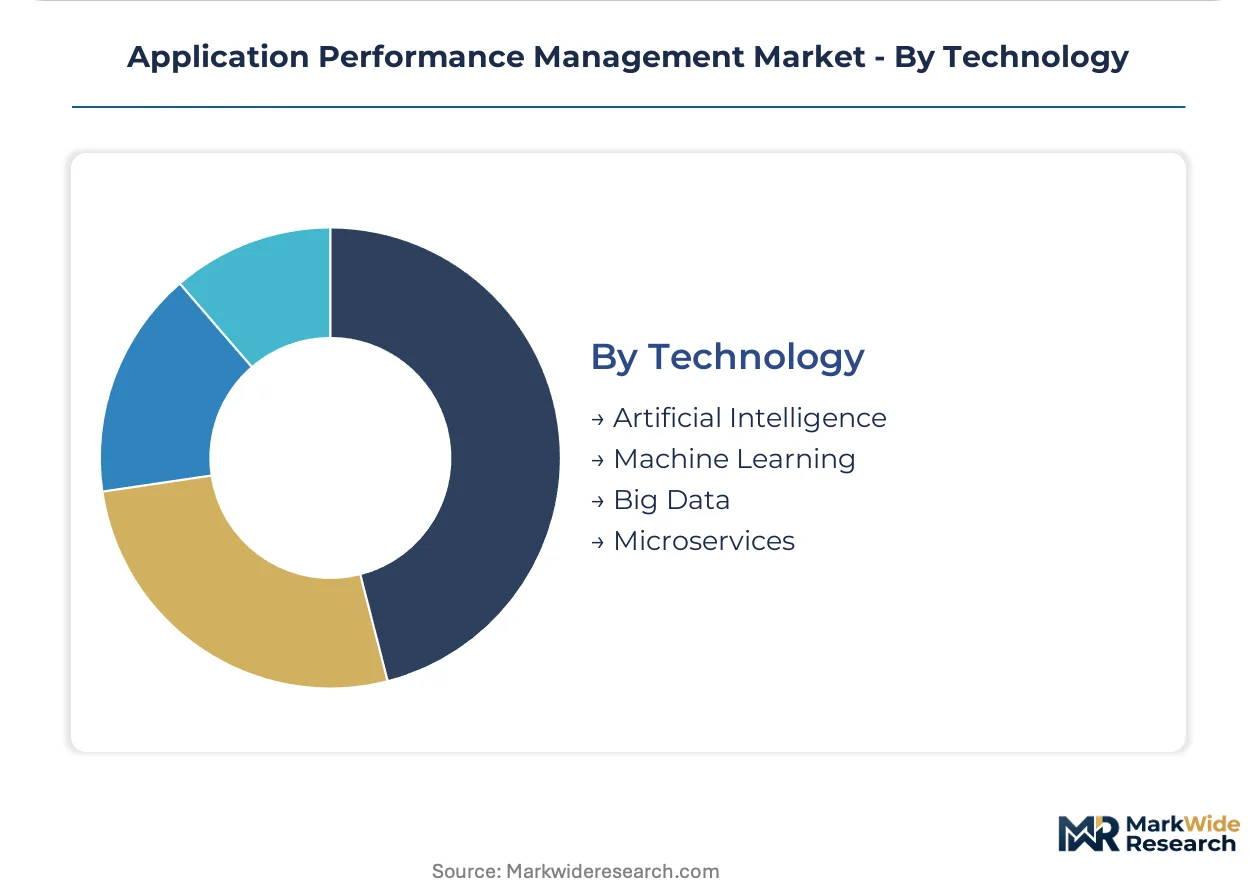
Application maturity separates production-grade AI implementations from experimental deployments, with microservices architecture reaching saturation in cloud-native enterprises.
- Artificial Intelligence:Generative models for root cause analysis and natural language incident summarization reshape operator workflows. EU AI Act transparency requirements mandate explainability trails for automated decision systems in credit scoring and trading infrastructure.
- Machine Learning:Baseline behavioral models detect performance drift in seasonally variable workloads.
- Big Data:Petabyte-scale telemetry lakes enable retrospective pattern analysis across extended retention windows.
- Microservices:Distributed tracing standards mature as service mesh adoption plateaus in enterprise Kubernetes environments.
Microservices instrumentation leads by deployment volume. Artificial intelligence represents the fastest-climbing investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native enterprise transformation concentrates APM procurement in the United States, while data sovereignty mandates fragment vendor architectures across European and Asian markets. Financial services compliance requirements and telecommunications reliability standards reshape regional deployment patterns. Each geography exhibits distinct procurement rhythms tied to sector-specific regulatory enforcement.
United States
SEC disclosure mandates for financial system uptime and FCC telecommunications reliability guidelines accelerate real-time transaction visibility investments. HIPAA safeguards for healthcare data integrity elevate continuous monitoring to compliance necessity. Silicon Valley technology conglomerates and New York financial services firms standardize on OpenTelemetry collectors, displacing proprietary agent architectures.
Germany
Automotive manufacturers and industrial conglomerates anchor European demand for hybrid cloud observability platforms. GDPR cross-border transfer protocols and operational sovereignty requirements constrain multi-region deployment architectures. Bavaria-based automotive OEMs and Baden-Württemberg machinery producers prioritize sovereign data residency with burst capacity integration.
United Kingdom
Financial services compliance teams in London require explainable AI audit trails for algorithmic trading infrastructure. The Prudential Regulation Authority and Financial Conduct Authority mandate system resilience documentation for critical banking operations. The City of London and Canary Wharf fintech clusters drive procurement of causal analysis engines with natural language incident summarization.
Japan
Manufacturing conglomerates and telecommunications carriers demand sub-millisecond latency telemetry at enterprise scale. METI industrial standards and NTT reliability benchmarks compel real-time infrastructure investment. Tokyo and Osaka metropolitan technology clusters standardize on vendor-neutral SDKs for custom application tracing in container orchestration environments.
Singapore
Monetary Authority of Singapore operational resilience guidelines and ASEAN cross-border data flow protocols shape procurement criteria for financial institutions. The central business district banking cluster and one-north technology precinct drive demand for predictive analytics platforms with automated remediation workflows.
Application Performance Management Market Vendor Landscape
Concentration sits with cloud-native SaaS platforms and legacy infrastructure monitoring incumbents competing across distinct deployment archetypes. The vendor landscape exhibits tiered segmentation between hyperscaler-aligned observability suites, specialized APM pure-plays, and diversified IT operations portfolios. Strategic archetypes include autonomous AI-driven root cause analysis specialists, log analytics-integrated platforms, and container-native telemetry providers. Competitive moves center on OpenTelemetry standardization alignment and hybrid cloud orchestration capability expansion.
Within the cloud-native tier, Datadog exemplifies multi-environment monitoring dominance through elastic telemetry ingestion architectures. Splunk APM occupies a position anchoring deep log analytics integration for enterprise security operations centers. Dynatrace represents autonomous operations leadership via causal analysis engines and natural language incident workflows. These three vendors collectively illustrate the strategic bifurcation between data collection infrastructure commoditization and predictive analytics layer value capture.
| Leading Market Players |
|---|
| Datadog |
| Splunk APM |
| New Relic |
| AppDynamics |
| Elastic APM |
| Dynatrace |
| CubeAPM |
| SolarWinds |
| Splunk AppDynamics |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center utilization rates above 80% in United States cloud regions compress marginal compute costs for telemetry ingestion, concentrating supply-side power among vendors operating multi-tenant SaaS architectures and establishing price floors that exclude smaller operators lacking comparable scale economies.
Pricing Analysis
SEC disclosure mandates for financial system uptime dictate the pricing tier structure across the Application Performance Management landscape. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade autonomous AI platforms from mid-market SaaS offerings and open-source instrumentation tiers. Price differentiation rests on certification level (ISO 27001, SOC 2 Type II) and cross-environment orchestration capability. Cost compression in the standard tier is intensifying because OpenTelemetry standardization commoditizes data collection infrastructure. Mid-market e-commerce platforms exhibit highest price sensitivity; defense contractors with air-gapped requirements show lowest.
Supply Chain Analysis
Trans-Pacific container availability constraints and port congestion at Los Angeles-Long Beach inflate inbound logistics costs for on-premises appliance deployments. Geographic supply concentration centers on United States hyperscaler regions, Ireland for EU data residency, and Singapore for ASEAN financial services. Component dependencies include GPU accelerators for AI inference, high-throughput network interface cards, and encrypted storage arrays. Single-source vulnerability in specialized telemetry processor chips creates procurement risk. Distribution runs through hyperscaler marketplaces, systems integrator channels, and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application Performance Management sits in early-cycle expansion as cloud-native enterprise transformation accelerates telemetry procurement beyond traditional monitoring replacement rates.
For Market Incumbents: Secure OpenTelemetry collector dominance before standardization completes, locking in processing-layer control as instrumentation commoditizes. Invest in sovereign cloud certifications for German and French data residency requirements. Defensive consolidation around causal AI engines counters emerging generative-native entrants. For New Entrants and Emerging Players: Differentiate on edge computing observability for IoT and 5G distributed workloads where incumbent architectures carry excess overhead. Target healthcare mid-market with HIPAA-compliant lightweight agents as the most penetrable segment. Pursue managed service provider channel partnerships to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid cloud orchestration platforms with multi-year FinOps governance contracts. Long-term viability favors vendors with autonomous remediation capabilities reducing human-in-the-loop dependency. Watch OpenTelemetry instrumentation penetration rates as inflection signal for processing-layer margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| OpenTelemetry Collector Integration | Commoditizes instrumentation layer while capturing processing-layer value pools. |
| Sovereign Cloud Certification | Unlocks German automotive and French retail procurement constrained by GDPR protocols. |
| Autonomous Remediation Engine | Reduces MTTR below SEC-mandated thresholds for financial services uptime disclosure. |
| Edge Telemetry Agent Development | Addresses 5G network slicing latency requirements for Japanese telecommunications carriers. |
| Healthcare Compliance Specialization | Captures HIPAA-driven procurement elevation from operational preference to necessity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases. Platform engineering directors, SRE team leads, IT procurement officers, and compliance auditors at financial services and healthcare enterprises provided operational perspective. Bottom-up telemetry deployment estimates triangulated against top-down vendor revenue segmentation.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves across the projection horizon. Forecast inputs include Kubernetes cluster growth rates and OpenTelemetry instrumentation penetration by enterprise maturity segment.
The analysis sits within stated boundaries; outcomes outside sustained cloud-native transformation velocity or OpenTelemetry standardization completion would require recalibration. Forecasts reflect assumptions around skills shortage persistence and data sovereignty enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Social Computing Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market