
 IoT Data Governance Market | 2026-2036
IoT Data Governance Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Data Governance Market Foresight
Buyer concentration among healthcare providers is expanding as hospital networks consolidate IoT device fleets and demand unified governance platforms. IBM leverages its hybrid cloud architecture to anchor enterprise contracts across multi-site health systems. Collibra specializes in metadata automation for clinical data lakes, competing with Informatica's AI-powered data quality engines. Tata Consultancy Services extends its managed services footprint by integrating governance tools into existing hospital IT estates.
IoT Data Governance encompasses the policies, technical controls, and operational workflows that ensure sensor-generated data remains accurate, secure, and compliant across distributed edge-to-cloud pipelines, typically enforcing lineage tracking, access policies, and retention rules through automated policy engines. The practice serves to mitigate regulatory exposure while enabling analytics-ready datasets from high-velocity machine telemetry. Cloud-based deployment models are capturing the fastest expansion as manufacturers and retailers seek elastic scalability for seasonal data surges. Data Privacy and Compliance Management solution types command premium pricing due to the complexity of cross-jurisdictional regulatory mapping, while Integration services within the service type category dominate current vendor revenue as enterprises retrofit legacy operational technology stacks.
The EU AI Act, GDPR, and ISO/IEC 27001 standards collectively shape product roadmaps by mandating explainable automated decisions and documented data provenance for high-risk IoT applications. FDA guidance on connected medical device cybersecurity further tightens validation requirements for healthcare-facing governance modules. Stakeholders must monitor how NIS2 implementation across EU member states alters liability allocation between IoT platform operators and their enterprise customers.
Market Dynamics
Cross-border data localization mandates are fragmenting cloud architectures and forcing vendors to engineer region-specific governance stacks rather than unified global platforms. Healthcare networks in Germany and industrial manufacturers in Japan now demand sovereign data residency as a contractual prerequisite.
Growth Catalysts
- EU AI Act enforcement:High-risk IoT applications must maintain auditable data provenance chains, compelling hospitals and automotive suppliers to deploy automated lineage tracking systems.
- Edge-to-cloud telemetry volumes:Shop-floor sensor networks generate petabyte-scale streams requiring real-time policy enforcement at the network edge.
- Japan METI data trust framework:Industrial consortiums adopt standardized governance protocols for cross-enterprise data sharing in smart factory ecosystems.
Market Restraints
- Skilled architect scarcity:Enterprises face 18-month hiring cycles for engineers proficient in both ISO/IEC 27001 compliance and distributed systems design.
- Input cost concentration:Specialized hardware security modules for edge nodes rely on Taiwanese semiconductor fabrication capacity.
- Regulatory friction:Divergent FDA and EMA guidance on connected medical device data retention creates validation duplication costs.
Strategic Opportunities
- India BIS standards convergence:Domestic manufacturing incentives under PLI schemes attract governance vendors to localize cloud infrastructure for industrial IoT deployments.
- Digital twin integration:Convergence of physics-based simulation with live sensor governance creates new subscription revenue pools in predictive maintenance.
- API-first distribution:Embedded governance modules sold through cloud marketplaces bypass traditional enterprise sales cycles.
Industry Challenges
- Retrofit complexity:Brownfield operational technology stacks lack standardized APIs, forcing custom integration engineering for each legacy deployment.
- Certification timeline compression:ISO/IEC 27001 and SOC 2 audit queues extend to nine months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Data Governance Market |
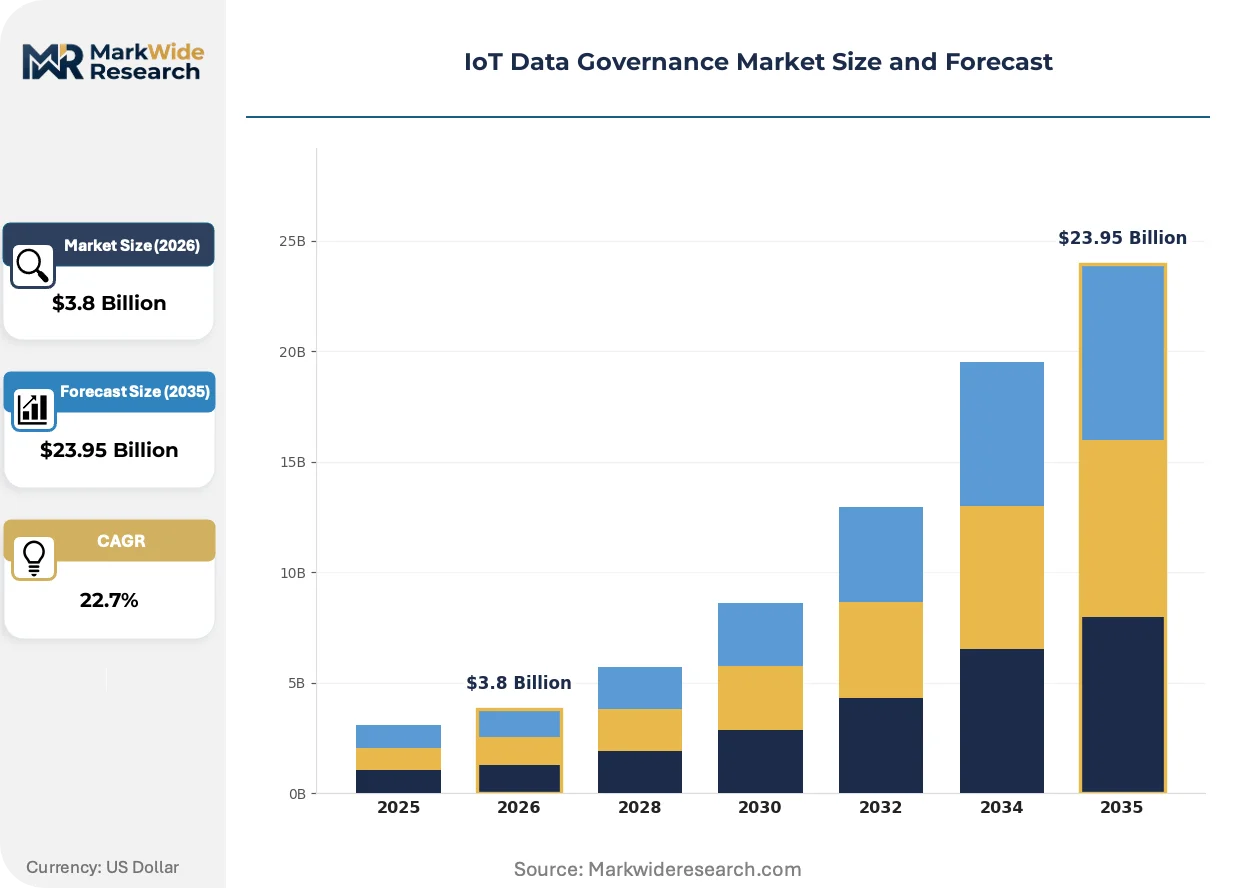
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Manufacturing, Healthcare, Retail, Transportation Solution Type: Data Security, Compliance Management, Data Quality, Data Privacy Service Type: Consulting, Integration, Support & Maintenance, Managed Services |
| Companies Covered | Atlan, Alation, Collibra, Tata Consultancy Services, EPAM Systems, Informatica, IBM, Wipro, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Data Governance Market Shifts & Advancements
Federated governance architectures are displacing centralized control planes as data sovereignty requirements harden across jurisdictions. Vendors now engineer mesh policy engines that synchronize compliance states without consolidating raw telemetry.
Confidential computing enclaves are electrifying edge deployment security by enabling encrypted processing of sensitive sensor streams without exposing cleartext to host infrastructure. Automotive tier-1 suppliers in Germany adopt these modules for autonomous vehicle telemetry. The technology is electrifying competitive differentiation as privacy-preserving analytics become a procurement gate.
EU AI Act risk classification tiers are forcing governance vendors to map automated decision pathways for high-risk IoT applications. Healthcare providers must document data provenance for diagnostic algorithms. French hospital networks under CNIL oversight lead implementation, with EMA cross-referencing these submissions for medical device approvals.
Consolidated procurement by multi-site health systems is compressing vendor evaluation cycles and favoring platforms with pre-certified compliance modules. Group purchasing organizations now mandate unified governance across acquired hospital networks. This pattern concentrates most visibly in German hospital federations integrating rural clinics into metropolitan data lakes.
IoT Data Governance Market Segmentation
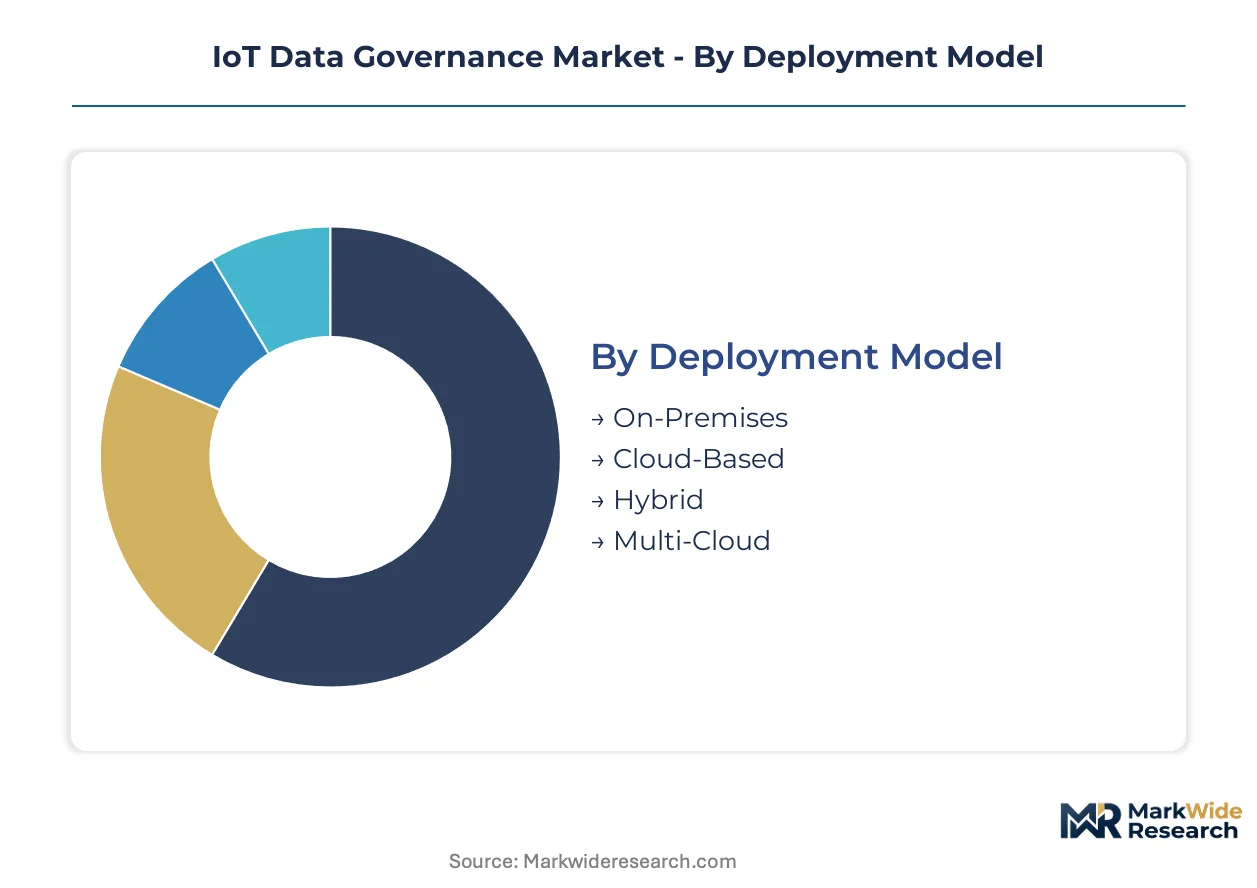
Segmentation in IoT data governance reveals distinct capital requirements and regulatory exposure profiles across deployment architectures, end-use verticals, and service delivery models. Understanding these partitions helps vendors align R&D spend with buyer procurement patterns and compliance mandates.
Deployment Model:
Capital intensity varies sharply across deployment architectures, with on-premises installations demanding substantial upfront infrastructure investment while cloud models shift expenditure to operational budgets.
- On-Premises:Dedicated hardware stacks within enterprise data centers enforce governance policies through localized policy engines. German automotive manufacturers and Japanese industrial conglomerates favor this model to satisfy sovereign data residency requirements under METI frameworks and EU AI Act risk classifications.
- Cloud-Based:Elastic compute resources provisioned through hyperscale providers enable rapid scaling for seasonal telemetry surges. Retail chains in France and healthcare networks in Spain deploy these architectures to avoid capital-heavy infrastructure builds while maintaining GDPR-compliant data localization through region-specific availability zones.
- Hybrid:Split architectures process sensitive telemetry on-premises while archiving analytics-ready datasets to cloud repositories.
- Multi-Cloud:Distributed governance control planes spanning AWS, Azure, and GCP environments mitigate vendor lock-in risks.
On-Premises deployments absorb the bulk of installed capacity in regulated industrial sectors; Cloud-Based configurations are expanding most quickly among mid-market enterprises seeking elastic scalability.
End User:
Application context determines governance complexity, with healthcare and manufacturing presenting divergent technical requirements around latency tolerance and audit granularity.
- Healthcare:Connected medical device telemetry demands sub-second policy enforcement for patient safety-critical data streams. Hospital networks in Germany and diagnostic imaging centers in France drive procurement under FDA and EMA cybersecurity guidance, with CNIL oversight mandating documented data provenance for diagnostic algorithms.
- Manufacturing:Shop-floor sensor networks generate high-velocity machine telemetry requiring real-time lineage tracking. German industrial manufacturers digitizing production lines under Industry 4.0 initiatives represent concentrated demand, with METI-standardized governance protocols gaining traction in Japanese smart factory ecosystems.
- Retail:Point-of-sale and inventory sensor data governance focuses on consumer privacy protection and cross-border transaction compliance.
- Transportation:Fleet telematics and autonomous vehicle data streams require edge-resident policy enforcement for latency-sensitive safety systems.
Healthcare captures the steepest expansion trajectory as hospital consolidation accelerates unified governance platform procurement; Manufacturing retains the largest installed base among industrial IoT deployments.
Solution Type:
Margin profiles diverge across solution categories, with compliance and privacy modules commanding premium pricing due to regulatory complexity while data quality tools compete on automation efficiency.
- Data Privacy:Cross-jurisdictional regulatory mapping engines automate consent management and right-to-erasure workflows. French hospital networks under CNIL jurisdiction and German healthcare federations integrate these modules to satisfy GDPR and EU AI Act documentation requirements for high-risk automated decision systems.
- Compliance Management:Audit trail generation and certification documentation tools streamline ISO/IEC 27001 and SOC 2 validation processes. Healthcare providers in Switzerland and medical device manufacturers in Germany prioritize these solutions to compress nine-month audit timelines.
- Data Security:Encryption key management and access control frameworks protect telemetry in transit and at rest.
- Data Quality:Automated profiling and cleansing engines ensure sensor data accuracy for downstream analytics.
Compliance Management solutions absorb the bulk of enterprise software budgets in regulated sectors; Data Privacy modules are gaining share fastest as EU AI Act enforcement tightens provenance documentation mandates.
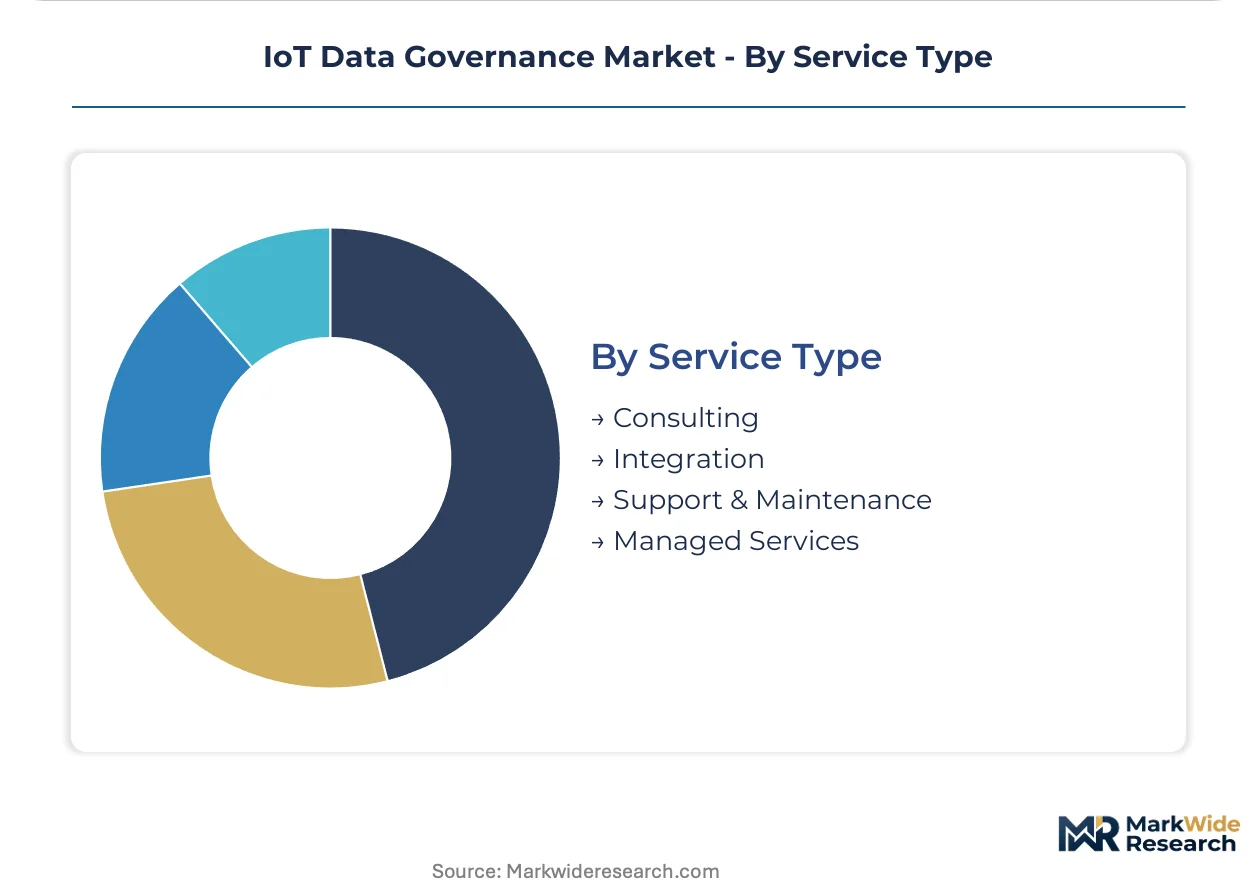
Service Type:
Revenue concentration favors integration services as enterprises retrofit brownfield operational technology stacks lacking standardized APIs.
- Integration:Custom engineering connects legacy industrial control systems with modern governance platforms. German automotive suppliers and Japanese electronics manufacturers drive sustained demand as each deployment requires bespoke adapter development for proprietary sensor protocols.
- Managed Services:Outsourced policy administration and continuous compliance monitoring transfer operational burden to vendor specialists. Healthcare networks in Spain and industrial consortiums in Italy adopt these arrangements to address 18-month hiring cycles for scarce governance architect talent.
- Consulting:Advisory engagements map regulatory requirements to technical control implementations.
- Support & Maintenance:Ongoing patch management and policy engine updates ensure continued certification validity.
Integration services command the largest revenue share among professional services categories; Managed Services are climbing the fastest as skills scarcity pushes enterprises toward outsourced governance operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network consolidation in Germany and industrial digitization across Japanese manufacturing hubs concentrate procurement volume for governance platforms. Sovereign data residency mandates fragment cloud architectures, compelling vendors to engineer jurisdiction-specific stacks rather than unified global deployments.
Germany
Automotive tier-1 suppliers and industrial manufacturers digitizing shop-floor sensor networks under Industry 4.0 initiatives drive concentrated demand. KBA oversight intersects with EU AI Act risk classifications for autonomous vehicle telemetry. Bavaria's automotive cluster and Baden-Württemberg's machine tool ecosystem anchor sovereign cloud deployments for cross-border data flows.
United States
FDA cybersecurity guidance on connected medical devices tightens validation requirements for healthcare-facing governance modules. Hospital networks consolidating IoT device fleets demand unified platforms with pre-certified compliance engines. The Greater Boston medical technology corridor and Pacific Northwest cloud infrastructure hubs concentrate vendor engineering resources.
Japan
METI data trust frameworks standardize governance protocols for cross-enterprise data sharing in smart factory ecosystems. Industrial consortiums adopt federated architectures to satisfy data sovereignty requirements without consolidating raw telemetry. The Chubu region around Nagoya anchors automotive supplier governance deployments for edge-resident policy enforcement.
France
CNIL oversight mandates documented data provenance for diagnostic algorithms in hospital networks under EU AI Act enforcement. French healthcare providers lead implementation of automated lineage tracking for high-risk automated decision systems. The Île-de-France region concentrates procurement for metropolitan data lake integration with rural clinic federations.
India
BIS standards convergence under PLI manufacturing incentives attracts governance vendors to localize cloud infrastructure for industrial IoT deployments. Domestic manufacturers retrofit brownfield operational technology stacks with modern policy engines. Karnataka's technology corridor and Gujarat's industrial zones anchor initial sovereign data center deployments.
IoT Data Governance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-first distribution through cloud marketplaces. The vendor base stratifies across three maturity tiers: legacy systems integrators with managed services footprints, pure-play metadata specialists, and hyperscale cloud natives embedding governance modules. Strategic archetypes include hybrid cloud architects, clinical data lake specialists, and edge-to-cloud pipeline engineers. Consolidation pressures favor platforms with pre-certified compliance modules as group purchasing organizations mandate unified governance across acquired networks.
Within the enterprise systems tier, IBM anchors multi-site health system contracts through hybrid cloud architectures, while Collibra exemplifies metadata automation specialists competing for clinical data lake deployments. Tata Consultancy Services occupies a position among IT services conglomerates extending managed services integration into existing hospital estates. These three represent distinct competitive vectors: platform-centric, specialization-focused, and services-led respectively.
| Leading Market Players |
|---|
| Atlan |
| Alation |
| Collibra |
| Tata Consultancy Services |
| EPAM Systems |
| Informatica |
| IBM |
| Wipro |
| Databricks |
| Others |
Supply & Pricing Matrix
Healthcare network consolidation in Germany and industrial manufacturer digitization in Japan concentrate procurement volume among multi-site systems seeking unified governance platforms, anchoring subscription-based SaaS pricing with tiered feature access scaled to device fleet size and compliance module depth.
Pricing Analysis
Volume-driven cloud deployments capture margin compression from hyperscale infrastructure efficiencies while on-premises sovereign stacks retain premium pricing through hardware security module bundling and ISO/IEC 27001 certification engineering. Price differentiation hinges on EU AI Act risk classification tier and edge node count scale, with high-risk diagnostic algorithm governance commanding substantial premiums over standard telemetry management. Cost compression in mid-market cloud tiers is intensifying because hyperscale marketplace distribution bypasses traditional enterprise sales overhead. Hospital group purchasing organizations exhibit acute price sensitivity, whereas German automotive tier-1 suppliers prioritize sovereign data residency over cost optimization.
Supply Chain Analysis
ISO/IEC 27001 and SOC 2 certification gating concentrates qualified hardware security module supply among Taiwan, South Korea, and USA fabrication facilities, with audit queue backlogs extending vendor qualification timelines. Edge node processors and specialized encryption chipsets draw from Taiwanese semiconductor foundries, German precision sensor manufacturers, and Japanese industrial control component suppliers. Single-source vulnerability in hardware security module fabrication creates systemic exposure to geopolitical trade restriction shocks. Distribution runs through direct enterprise sales teams for large healthcare networks, while cloud marketplace channels serve mid-market manufacturing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into confidential computing enclave hardware and federated governance mesh software stacks constitutes the dominant competitive race, with control over edge-resident policy engines emerging as the critical downstream lever.
For Market Incumbents: To counter API-first cloud marketplace entrants, anchor multi-year enterprise contracts through pre-certified compliance module bundling and deepen in-house production of hardware security modules for sovereign data center deployments. Prioritize ISO/IEC 27001 audit acceleration partnerships to compress nine-month certification queues. For New Entrants and Emerging Players: Confidential computing enclaves for automotive telemetry offer a technology-first wedge into German KBA-regulated autonomous vehicle supplier networks. Target brownfield manufacturing integration services in India's Gujarat industrial zones under PLI scheme incentives, deploying API-first distribution through hyperscale marketplaces to bypass traditional sales cycles. For Investors and Strategic Acquirers: The window for entry favors clinical data lake specialists with automated lineage tracking capabilities and pre-existing CNIL audit relationships. Monitor EU AI Act enforcement variance across member states as the inflection indicator for governance platform consolidation velocity. Long-term viability rests on federated architecture IP and healthcare compliance certification density.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Enclave Development | Edge-resident encryption processing satisfies German automotive KBA telemetry requirements without cleartext exposure. |
| Federated Governance Mesh Architecture | Decentralized policy synchronization enables Japanese METI cross-enterprise data sharing without raw telemetry consolidation. |
| Pre-Certified Compliance Module Bundling | ISO/IEC 27001 and EU AI Act documentation accelerates hospital procurement under French CNIL oversight. |
| API-First Cloud Marketplace Distribution | Embedded governance modules bypass eighteen-month enterprise sales cycles for mid-market manufacturing. |
| Hardware Security Module Vertical Integration | Taiwanese semiconductor sourcing control mitigates single-fabrication risk for sovereign data center deployments. |
Research Methodology
Independent corroboration across governance platform engineering directors, hospital procurement committee leads, and industrial IoT integration specialists underwrites the qualitative findings. Secondary validation draws from EU AI Act implementation guidance, FDA connected device cybersecurity documentation, METI data trust framework protocols, and hyperscale cloud marketplace transaction disclosures. Bottom-up device fleet sizing triangulates against top-down enterprise software spend estimates across German, Japanese, and US healthcare networks.
Rate-of-change decomposition separates cloud deployment elasticity coefficients from on-premises infrastructure replacement cycles across the analysis window. Segmentation dimensions span deployment architecture, end-use vertical, solution type, and service delivery model, with regional regulatory cluster intensity as an industry-specific overlay. CAGRs derive from telemetry volume growth curves, compliance mandate enforcement timelines, and vendor revenue recognition patterns. Forecast inputs incorporate hospital consolidation velocity and industrial digitization capex commitments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIS2 liability allocation shifts and Taiwan semiconductor supply disruption scenarios. Model assumptions reflect current EU AI Act risk classification guidance and ISO/IEC 27001 audit capacity constraints. A model refresh is warranted upon material change in cross-border data localization mandate enforcement or hardware security module fabrication capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Private Narrowband IoT Market