
 Real Time Store Monitoring Platform Market | 2026-2036
Real Time Store Monitoring Platform Market Size, Share, and Industry Trends Forecast 2026-2036
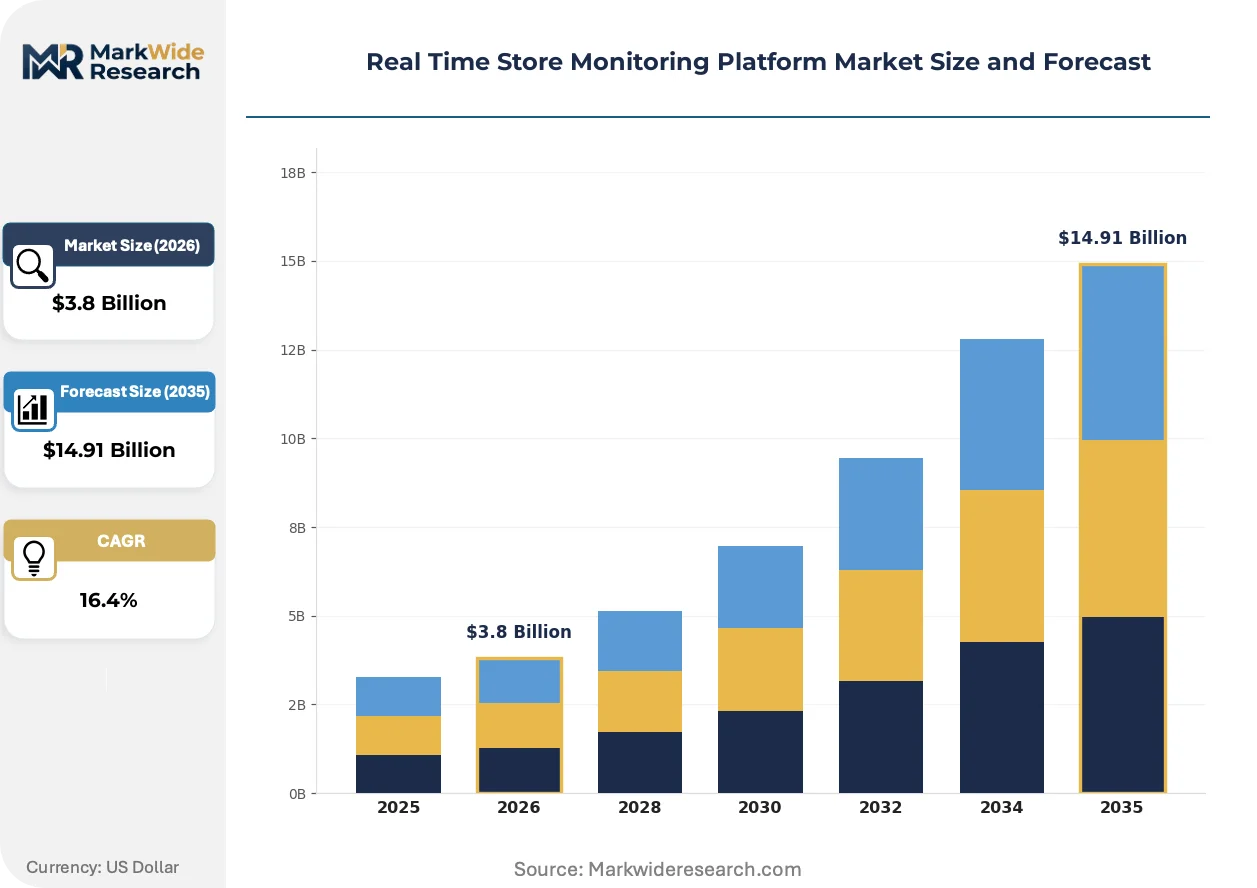
Real Time Store Monitoring Platform Market Outlook
Mid-market retail chains are bifurcating from enterprise buyers as the fastest-growing adoption segment for real-time store monitoring platforms. SAP SE leverages deep ERP integration to anchor its position in enterprise grocery deployments. Zebra Technologies sustains hardware-software bundling advantages across North American convenience store networks. Cisco Systems competes through edge networking infrastructure that underpins distributed video analytics architectures.
A real-time store monitoring platform integrates IoT sensors, video analytics engines, and cloud-native dashboards to track shelf conditions, foot traffic patterns, and inventory states with sub-minute latency. Cloud-based solutions now dominate new deployments for their elasticity, while on-premises configurations retain share among retailers with strict data residency requirements. Video analytics technology leads platform differentiation by enabling automated planogram compliance, whereas RFID deployments concentrate in apparel and electronics verticals where item-level tracking justifies tag costs.
The EU GDPR and the EU AI Act constrain cross-border video data flows and algorithmic decision-making in European retail deployments, compelling vendors to localize processing at the edge. The US Federal Trade Commission scrutinizes biometric data collection in retail analytics, shaping consent frameworks and platform feature sets. Stakeholders must weigh edge computing investments against evolving patchworks of privacy enforcement to sustain deployment velocity without regulatory exposure.
Market Dynamics
Edge computing architectures are compressing latency thresholds for video analytics pipelines, forcing platform vendors to re-architect around localized inference rather than cloud-only processing.
Growth Catalysts
- GDPR-aligned data governance frameworks:European retailers are accelerating platform deployment to satisfy localization mandates for biometric and video data processing.
- Convenience store network expansion:Operators across the United States are consolidating vendor relationships around integrated IoT-video stacks to reduce stockout rates.
- Computer vision inference at the edge:Shelf-monitoring accuracy improvements are driving replacement cycles for legacy camera-only surveillance systems.
Market Restraints
- GPU and NPU silicon concentration:Edge AI accelerator supply depends on Taiwan-based foundry capacity, creating input cost volatility for hardware-software bundles.
- Biometric data consent friction:FTC scrutiny of facial recognition analytics in US retail environments is lengthening sales cycles and constraining feature deployment.
- RFID tag cost economics:Item-level tracking remains prohibitive for low-margin grocery categories, limiting technology penetration outside apparel and electronics verticals.
Strategic Opportunities
- EU AI Act compliance services:Algorithmic audit and explainability tooling represent an emerging revenue layer for European deployments.
- Mid-market retail chain penetration:Buyers in this segment are bifurcating from enterprise procurement patterns, creating whitespace for modular platform offerings.
- Cloud-native dashboard elasticity:Subscription pricing models are unlocking adoption among retailers with seasonal demand volatility.
Industry Challenges
- Planogram compliance algorithm training:Computer vision models require extensive SKU-specific datasets, creating data engineering bottlenecks for new retail categories.
- Legacy POS integration complexity:Real-time inventory synchronization demands API connectivity with decades-old transactional systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Time Store Monitoring Platform Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Solutions, Hybrid Solutions, Mobile Applications End User: Retail Chains, Supermarkets, Convenience Stores, E-commerce Platforms Technology: IoT Sensors, Video Analytics, RFID, Data Analytics Tools Deployment: Edge Computing, Centralized Systems, Distributed Systems, Remote Monitoring |
| Companies Covered | SAP SE, Zebra Technologies, Cisco Systems, Sensormatic Solutions, RetailNext, Microsoft Corporation, Oracle Corporation, Trax Retail, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Time Store Monitoring Platform Market Strategic Shifts
Platform architectures are pivoting from centralized cloud processing toward distributed edge inference, reshaping hardware procurement patterns and vendor competitive positioning.
Edge-native video analytics is supplanting cloud-reliant processing pipelines in retail deployments. Convenience store operators are adopting localized inference engines to achieve sub-second shelf-state detection. This compression of decision latency is enabling automated replenishment triggers that bypass human verification steps.
The EU AI Act is imposing algorithmic transparency requirements on automated decision-making in European retail environments. Vendors must now document training data provenance and model performance metrics for shelf-monitoring systems. German and French retailers are responding by demanding edge-localized processing to limit cross-border data exposure.
Buyer procurement patterns are compressing vendor consolidation timelines around integrated technology stacks. Mid-market retail chains are abandoning point-solution purchasing in favor of unified IoT-video-cloud contracts. This preference shift is most visible in the United States, where major chains are reducing supplier counts to simplify interoperability management.
Real Time Store Monitoring Platform Market Segmentation
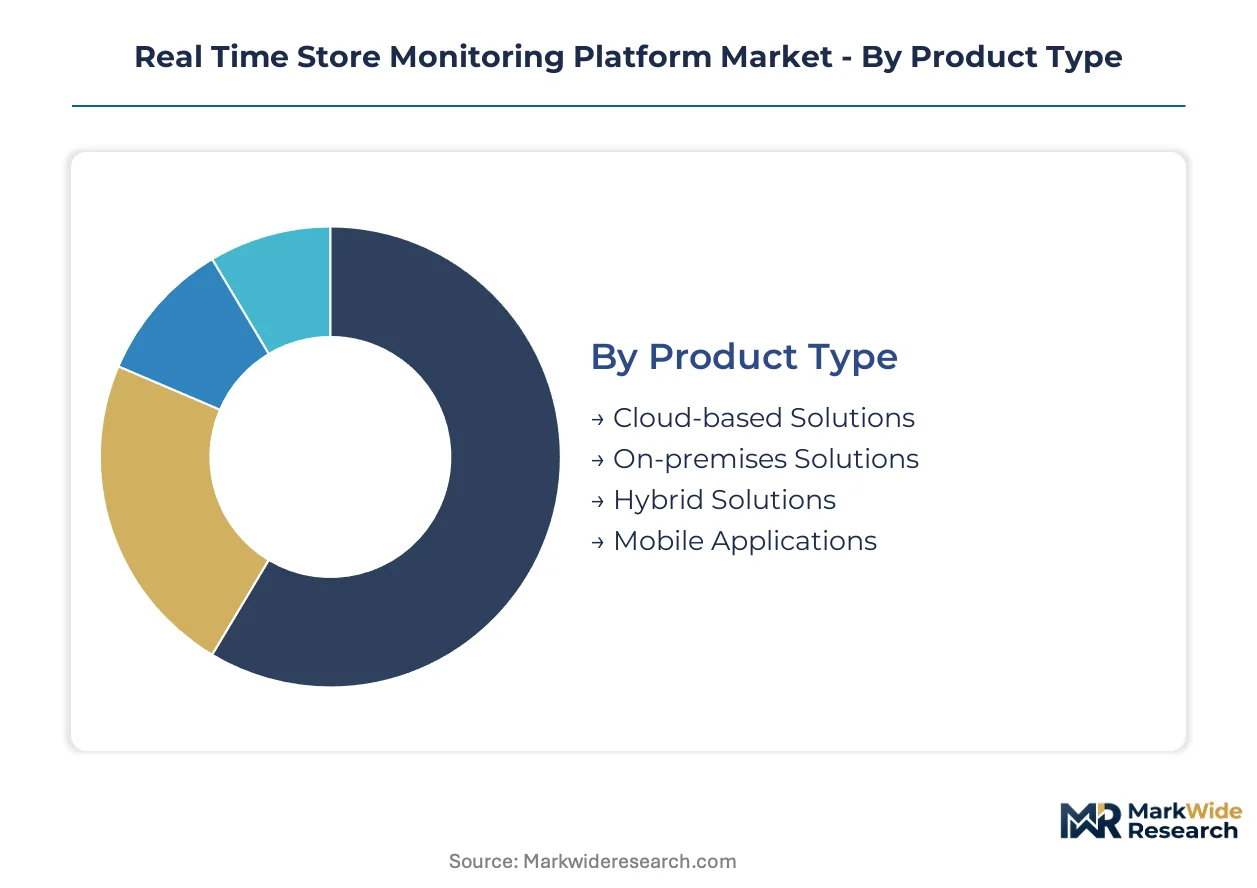
Platform architectures fragment across deployment topologies, data processing locations, and integration depths. Buyers select configurations based on SKU velocity, privacy jurisdiction, and legacy system constraints.
Product Type:
GDPR localization mandates and FTC biometric scrutiny are bifurcating procurement between residency-compliant on-premises stacks and elastic cloud-native alternatives.
- Cloud-based Solutions:Elastic compute resources enable seasonal scaling for retailers with demand volatility. United States supermarket chains concentrate procurement here, driven by subscription pricing flexibility and rapid feature deployment cycles.
- On-premises Solutions:Localized data processing satisfies strict residency requirements in German and French retail environments. Convenience store operators with limited IT staffing avoid these due to maintenance overhead.
- Hybrid Solutions:Split processing architectures process sensitive biometric data at the edge while pushing analytics to cloud dashboards.
- Mobile Applications:Manager-facing alert systems deliver shelf-state notifications to field personnel.
Cloud-based Solutions handle the majority of throughput; Hybrid Solutions are gaining share fastest as edge-cloud orchestration matures.
End User:
Foot traffic density and inventory turnover rates determine technology stack sophistication across buyer categories.
- Retail Chains:Enterprise-grade deployments integrate ERP systems with video analytics for chain-wide planogram compliance. United States mid-market chains are consolidating vendor relationships around unified IoT-video contracts.
- Supermarkets:High-SKU environments demand computer vision pipelines trained on extensive grocery datasets. German retailers lead European adoption due to labor cost pressures.
- Convenience Stores:Compact footprints favor edge-native inference engines with sub-second latency. United States operators are replacing camera-only surveillance with automated replenishment triggers.
- E-commerce Platforms:Dark store and micro-fulfillment center applications track picker productivity and inventory location accuracy.
Retail Chains command the largest deployment base; Convenience Stores are expanding most quickly as edge hardware costs decline.
Technology:
Sensor modality selection hinges on item-level tracking economics versus shelf-state inference accuracy.
- IoT Sensors:Weight-sensing shelves and environmental monitors feed real-time inventory dashboards. United States grocery chains deploy these for high-velocity categories where stockout costs exceed sensor capex.
- Video Analytics:Computer vision engines detect planogram deviations and shopper dwell patterns. French retailers are localizing these at the edge to limit GDPR exposure.
- RFID:Item-level tracking concentrates in apparel and electronics verticals where tag costs align with product margins.
- Data Analytics Tools:Predictive demand models synthesize sensor feeds with historical POS data.
Video Analytics dominates new deployment value; IoT Sensors are climbing the fastest as sensor fusion architectures proliferate.
Deployment:
Latency requirements and cross-border data restrictions are compressing decision-making toward store-level processing.
- Edge Computing:Localized GPU and NPU inference achieves sub-minute shelf-state detection without cloud round-trips. EU AI Act compliance is accelerating German and French retailer adoption.
- Centralized Systems:Legacy architectures persist among retailers with established data center investments and lower real-time requirements.
- Distributed Systems:Regional processing nodes balance latency and scale for multi-banner retail groups.
- Remote Monitoring:Cloud-reliant oversight suits smaller operators without on-site technical capabilities.
Edge Computing anchors forward deployment plans; Distributed Systems are seeing steepest expansion trajectory among multi-national retail groups managing jurisdictional complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German platform vendors export integrated edge-cloud stacks to United States convenience store operators seeking GDPR-compliant architecture templates. Cross-border technology flows concentrate between these two markets as regulatory frameworks diverge.
United States
Mid-market retail chains consolidate vendor relationships around unified IoT-video contracts. FTC scrutiny of biometric data collection lengthens sales cycles for facial recognition features. Dallas-Fort Worth operators deploy automated replenishment triggers across convenience store networks.
Germany
Supermarket operators drive demand for computer vision pipelines trained on high-SKU grocery datasets. The EU AI Act mandates algorithmic transparency documentation for automated shelf-monitoring decisions. Munich retailers localize processing at the edge to satisfy cross-border data restrictions.
France
Retailers prioritize edge-localized video analytics to limit GDPR exposure from biometric data flows. CNIL enforcement actions shape consent framework requirements for in-store customer tracking. Paris-based deployment clusters concentrate planogram compliance innovation.
United Kingdom
Post-Brexit data governance divergence creates procurement complexity for multi-national retail groups. UK Information Commissioner's Office guidelines constrain automated decision-making in customer analytics. London operators balance EU-aligned practices with distinct national regulatory interpretations.
Japan
Labor cost pressures in convenience store operations accelerate edge-native inference adoption. METI standards for IoT security influence platform procurement specifications. Tokyo-Kanto retail clusters integrate real-time monitoring with existing ERP infrastructure.
Real Time Store Monitoring Platform Market Competitive Environment
Listed leaders compete with private specialists across integrated technology stack depth. The vendor base concentrates around three strategic tiers: enterprise software incumbents with ERP integration advantages, hardware-software bundlers with sensor network scale, and cloud-native specialists with analytics velocity. Competitive moves center on M&A for computer vision capabilities and strategic partnerships for edge hardware supply.
Within the enterprise software tier, SAP SE and Oracle Corporation anchor positions through deep ERP integration in grocery deployments. Zebra Technologies exemplifies hardware-software bundling advantages across North American convenience store networks. Cisco Systems occupies a position in edge networking infrastructure that underpins distributed video analytics architectures.
| Leading Market Players |
|---|
| SAP SE |
| Zebra Technologies |
| Cisco Systems |
| Sensormatic Solutions |
| RetailNext |
| Microsoft Corporation |
| Oracle Corporation |
| Trax Retail |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Subscription-based SaaS contracts with tiered feature entitlements lock in multi-year supply access for edge hardware while capping price volatility for United States mid-market retail chains navigating FTC compliance costs.
Pricing Analysis
Next-generation edge-native inference engines command 40-60% subscription premiums over prior-generation cloud-reliant architectures. Three-tier pricing structure across premium, standard, and economy levels segments by SKU velocity, integration depth, and GDPR compliance certification. Cost compression in economy tiers is intensifying because Taiwanese GPU foundry capacity constraints inflate hardware-software bundle input costs. Convenience store operators exhibit highest price sensitivity due to limited IT staffing budgets, while enterprise grocery chains absorb premium tiers for ERP-integrated deployments.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing hubs through Los Angeles and Long Beach port complexes create 15-25 day hardware delivery windows for North American deployments. GPU and NPU silicon production concentrates in Taiwan, South Korea, and China, with edge server assembly drawing from Mexico and Vietnam facilities. Single-source vulnerability rests on TSMC advanced node capacity for AI accelerators. Distribution runs through OEM-direct channels for enterprise accounts and value-added resellers serving mid-market retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in retail monitoring are approaching an interoperability inflection as vendor consolidation around unified IoT-video-cloud stacks displaces point-solution purchasing patterns.
For Market Incumbents: Shield ERP integration advantages through accelerated edge-cloud orchestration patent filings. Deepen backward integration into NPU silicon sourcing to offset Taiwan foundry concentration risk. Defend against modular cloud-native specialists by embedding algorithmic audit tooling for EU AI Act compliance.
For New Entrants and Emerging Players: Anchor in mid-market retail chain whitespace where procurement patterns are bifurcating from enterprise vendor consolidation. Target United States convenience store networks replacing camera-only surveillance with automated replenishment triggers. Pursue white-label edge hardware partnerships to bypass direct silicon procurement exposure.
For Investors and Strategic Acquirers: Capital is best deployed toward computer vision specialists with SKU-specific training datasets and established API connectivity to legacy POS systems. Long-term viability favors platforms with demonstrated GDPR localization architecture and edge inference latency below one second. Monitor FTC consent framework enforcement intensity as signal for facial recognition feature deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Orchestration Platform | Enables sub-second shelf-state detection for United States convenience store operators. |
| EU AI Act Compliance Tooling | Creates algorithmic audit revenue layer for German and French retail deployments. |
| Legacy POS API Integration | Unlocks real-time inventory synchronization with decades-old transactional systems. |
| Computer Vision Specialist Acquisition | Accelerates SKU-specific model training for high-velocity grocery categories. |
| Mid-Market Channel Partnership | Captures bifurcating procurement patterns away from enterprise vendor consolidation. |
Study Parameters
Cross-validation between executive interviews with retail technology procurement officers and secondary validation through SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory filings anchors the qualitative findings. Primary fieldwork encompassed platform engineering leads at edge hardware vendors, IT directors at United States supermarket chains, compliance officers navigating GDPR and EU AI Act requirements, and channel partners distributing IoT-video bundles. Bottom-up deployment sizing triangulates against top-down market aggregation across cloud-native dashboard subscriptions and on-premises license flows.
Sensitivity analysis around edge hardware cost trajectories and regulatory enforcement intensity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, data processing location, integration depth with ERP systems, and retail vertical adoption patterns. CAGRs derive from installed base expansion rates and replacement cycle compression for legacy surveillance infrastructure. SKU velocity thresholds and labor cost pressures in convenience store operations constitute industry-specific forecast inputs.
Underlying assumptions cover sustained Taiwan foundry capacity allocation to edge AI accelerators and stable FTC consent framework interpretation, with deviation risk concentrated in geopolitical supply disruptions and biometric data enforcement escalations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Service Fulfillment Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Inventory Management Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Core Graphics Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Social Computing Market
Digital Solutions
Cloud Based Manufacturing Market