
 Condition Monitoring Software Market | 2026-2036
Condition Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Condition Monitoring Software Market Outlook
Power generation is pivoting toward continuous remote diagnostics as grid operators face pressure to minimize unplanned downtime across aging infrastructure. Siemens AG leverages its digital twin portfolio to anchor condition monitoring within utility control rooms. SKF Group specializes in bearing-centric vibration analytics for rotating machinery across thermal and wind assets. Emerson Electric Co. competes through its Plantweb ecosystem, integrating wireless sensors with predictive algorithms for turbine fleets.
Condition monitoring software encompasses digital platforms that acquire, process, and interpret sensor data from industrial equipment to detect anomalies before functional failure occurs. These systems typically process vibration spectra in the 0.5 Hz to 20 kHz range, temperature differentials, and acoustic signatures through edge gateways or centralized servers to trigger maintenance workflows. Vibration monitoring retains the largest installed base due to its maturity in rotating equipment applications, while thermal imaging is gaining share in electrical infrastructure and refractory monitoring where contact sensors prove impractical. Cloud-based deployment is expanding fastest among mid-sized manufacturers seeking to avoid capital-intensive server farms, though on-premises installations persist in oil & gas and defense environments with stringent data sovereignty requirements.
FERC reliability standards and OSHA mechanical integrity rules in the United States compel covered facilities to document equipment health surveillance, directly expanding software procurement for compliance logging and audit trails. The EU Machinery Directive and CE marking requirements for safety-related control systems push European OEMs to embed condition monitoring as a standard feature rather than aftermarket add-on. Stakeholders must weigh the trade-off between cloud analytics scalability and edge latency as machine learning models migrate closer to physical assets.
Market Dynamics
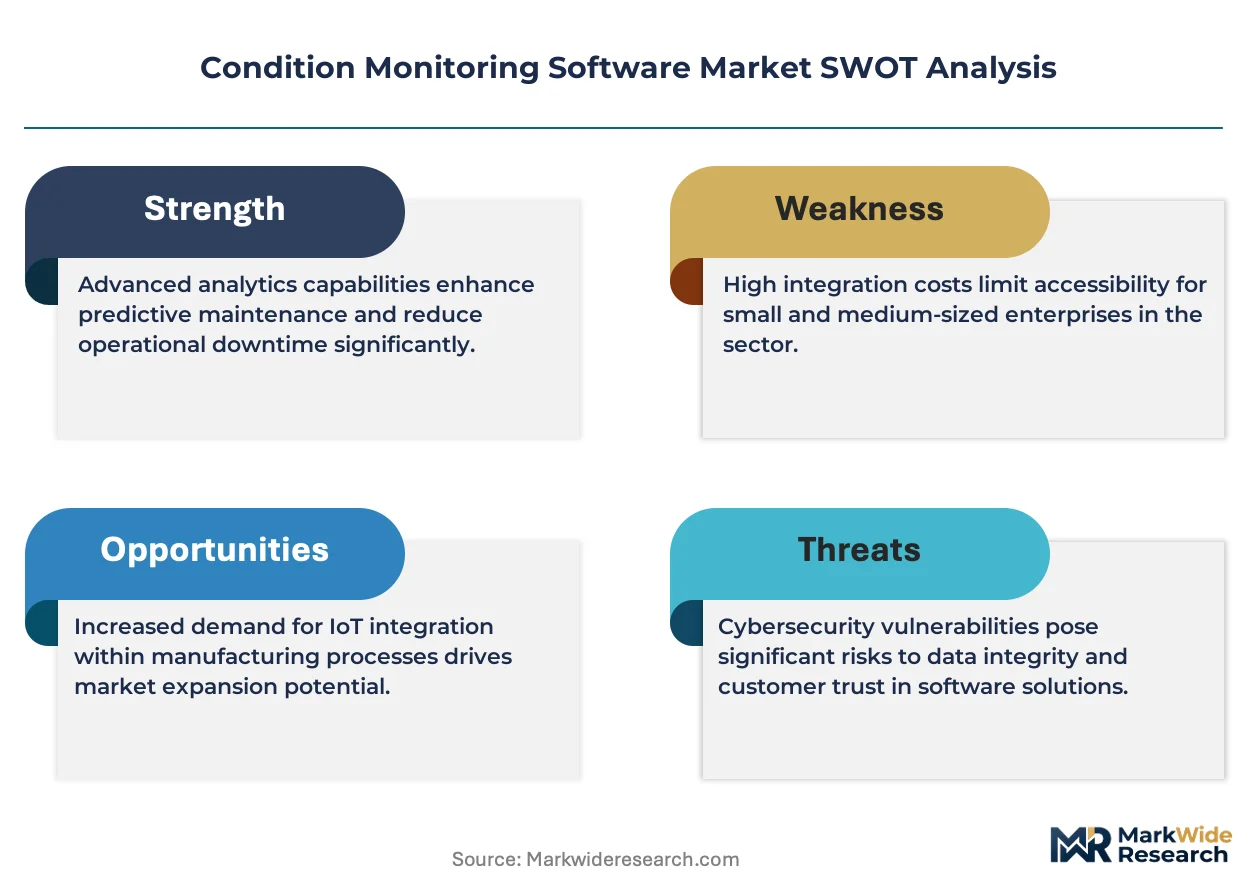
Power utilities and heavy manufacturing are consolidating sensor networks into unified digital platforms, forcing software vendors to absorb edge analytics capabilities that were previously standalone hardware functions.
Growth Catalysts
- OSHA mechanical integrity mandates:US refineries and chemical plants must document continuous equipment surveillance, creating mandatory procurement of audit-trail software for compliance logging.
- Wind turbine fleet expansion:Offshore installations in the North Sea and Baltic require predictive algorithms capable of processing blade pitch and drivetrain vibration data across geographically dispersed assets.
- Edge computing architectures:Real-time inference at the asset level reduces latency for critical rotating machinery, enabling sub-second anomaly detection in thermal power generation.
Market Restraints
- Semiconductor supply concentration:Specialized ADC chips for high-frequency vibration acquisition face lead times extending from Taiwan and South Korea foundries, constraining hardware-software bundle rollouts.
- Data sovereignty requirements:Oil and gas operators in the Middle East and defense contractors in the US mandate on-premises server deployment, blocking cloud-native subscription models.
- Interoperability fragmentation:Proprietary protocols from legacy DCS vendors create integration friction when connecting third-party condition monitoring platforms to existing control systems.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for capital goods and electronics are attracting greenfield automotive and machinery plants requiring integrated condition monitoring from commissioning.
- EU CSRD disclosure requirements:Mandatory sustainability reporting is pushing industrial asset owners to deploy energy-efficiency monitoring modules that correlate equipment health with carbon intensity metrics.
- Digital twin convergence:Physics-based modeling fused with operational sensor streams enables remaining useful life prediction for high-value turbomachinery, opening premium software tiers.
Industry Challenges
- Vibration analyst skill scarcity:Interpretation of frequency spectra and envelope demodulation requires specialized training that outpaces workforce development in maintenance departments.
- Legacy SCADA integration:Decades-old control systems in established power plants lack standardized APIs, forcing costly middleware development for data extraction.
- Cybersecurity certification delays:IEC 62443 compliance timelines for industrial software extend deployment cycles by six to twelve months in critical infrastructure sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condition Monitoring Software Market |
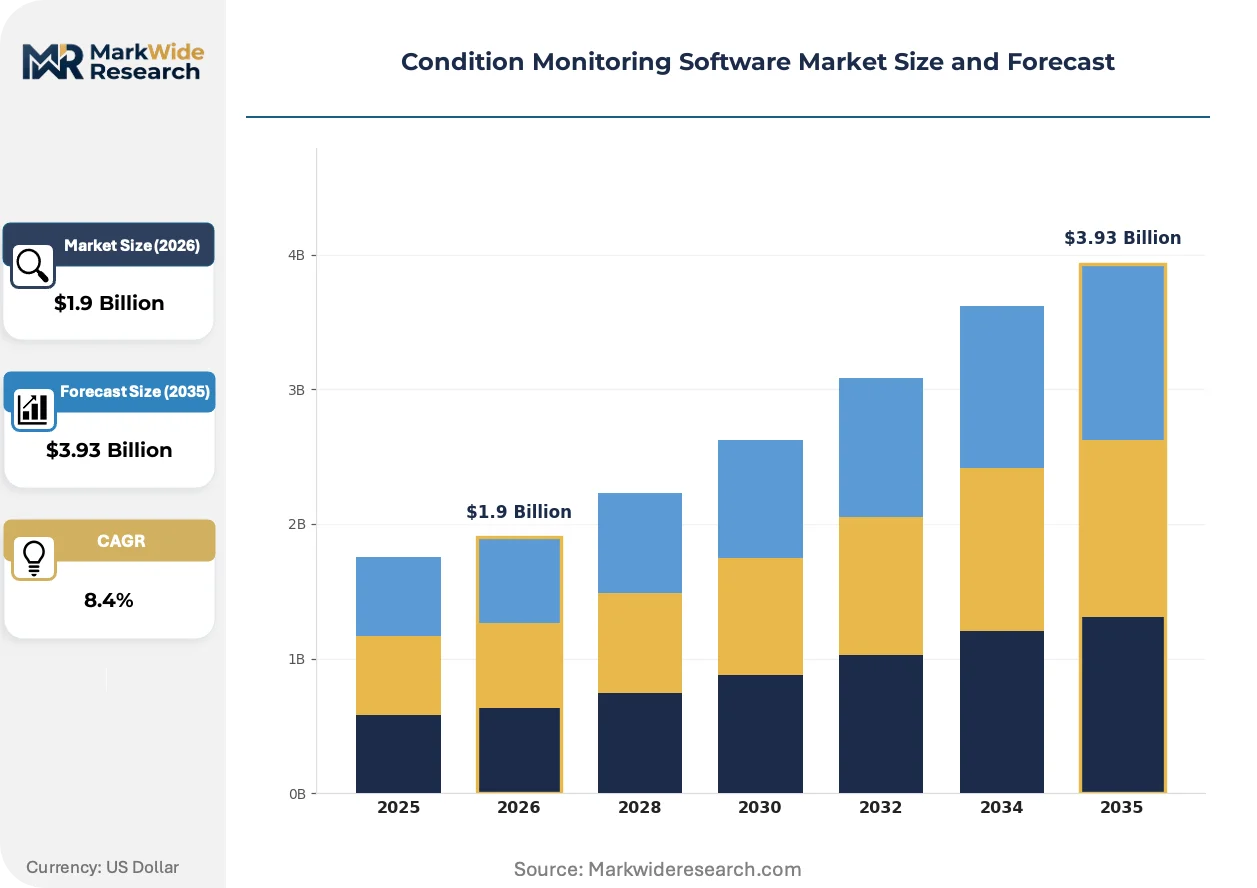
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Monitoring, Thermal Imaging, Acoustic Emission, Ultrasonic Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Oil & Gas, Transportation, Power Generation Technology: IoT Solutions, Big Data Analytics, Machine Learning, Wireless Sensors |
| Companies Covered | Emerson Electric Co., SKF Group, Honeywell International Inc., Siemens AG, ABB Ltd., General Electric, Schneider Electric SE, Rockwell Automation Inc., National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condition Monitoring Software Market Strategic Shifts
Machine learning inference is migrating from cloud data centers to ruggedized edge devices, compressing response times for critical asset protection while fragmenting software architecture decisions.
Embedded GPU accelerators in vibration data collectors are integrating neural network execution directly at the sensor node. Wind farm operators in Denmark and Germany are deploying these units across drivetrain monitoring points. The shift is integrating predictive capability into hardware that previously streamed raw data to centralized servers.
The EU AI Act's risk classification framework is compelling software vendors to document algorithmic decision pathways for safety-critical industrial applications. High-risk systems in chemical processing and nuclear auxiliary equipment face mandatory conformity assessments. German machinery OEMs are restructuring development pipelines to embed explainability features from initial design stages.
Mid-sized manufacturers are unbundling condition monitoring from long-term service contracts and procuring software subscriptions directly. Industrial distributors in the US Midwest are losing attach-rate margins as buyers source cloud platforms through vendor direct sales. The pattern is most pronounced among automotive tier-two suppliers seeking operational technology autonomy from OEM-mandated maintenance programs.
Condition Monitoring Software Market Segmentation
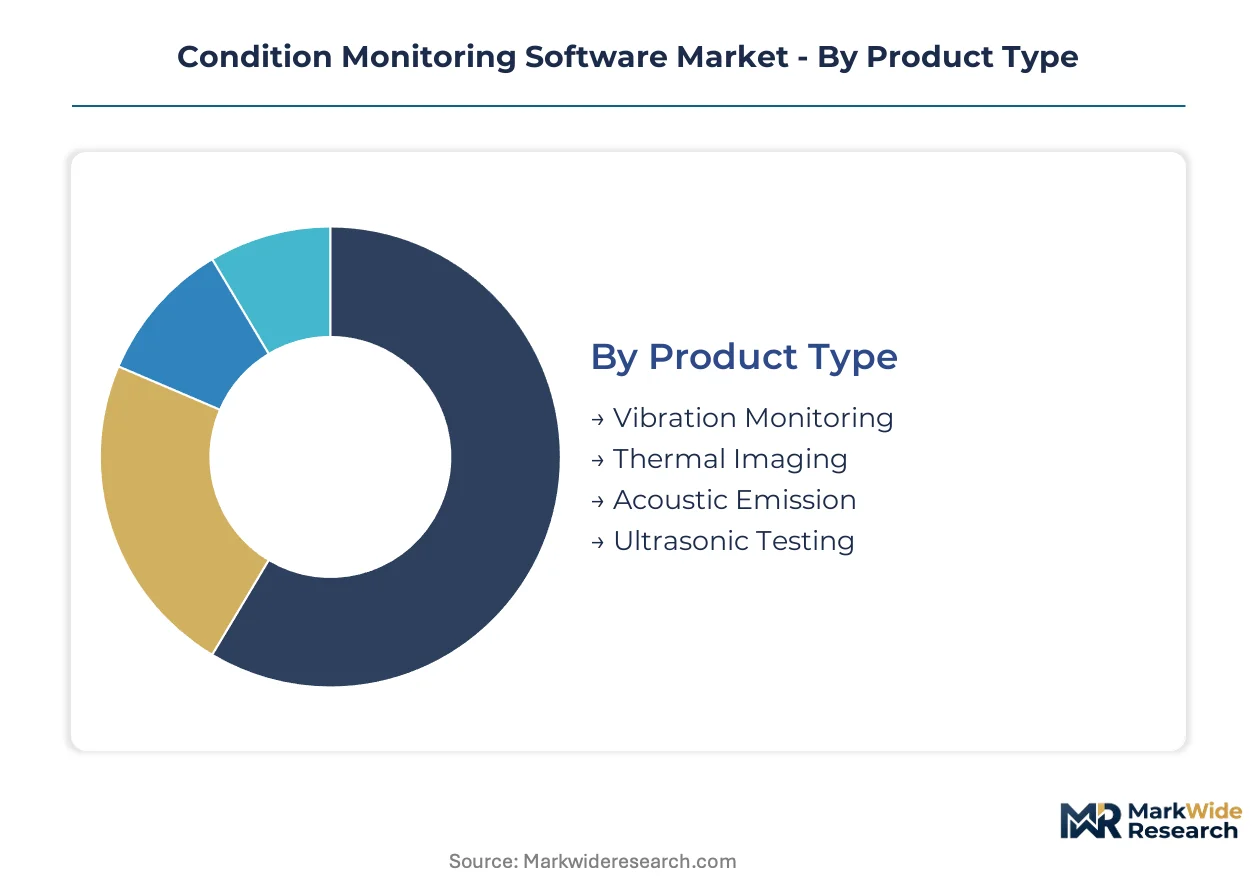
Segmentation in condition monitoring software reveals how technology specialization aligns with distinct operational constraints across industrial verticals. Deployment choices reflect trade-offs between data sovereignty, latency requirements, and capital intensity that vary sharply by end-use environment.
Product Type:
Vibration spectrum analysis dominates rotating equipment applications through established frequency-domain techniques.
- Vibration Monitoring:Processes acceleration signals from 0.5 Hz to 20 kHz using piezoelectric accelerometers mounted on bearings, gearboxes, and turbine shafts. Power generation utilities in Germany mandate continuous vibration surveillance for steam turbine fleets under grid stability protocols.
- Thermal Imaging:Captures infrared radiation across electrical switchgear, refractory linings, and transformer bushings without contact sensors. Offshore wind operators in the North Sea deploy drone-mounted thermal systems for blade leading-edge inspection where physical access is hazardous.
- Acoustic Emission:Detects stress-wave emissions from crack propagation and friction events in pressure vessels and storage tanks.
- Ultrasonic Testing:Employs high-frequency sound pulses for thickness gauging and weld integrity verification in pipeline networks.
Mature deployment sits with vibration monitoring. Newer deployment is concentrated in thermal imaging.
Deployment Model:
Architecture decisions hinge on latency tolerance, data volume, and regulatory jurisdiction over stored telemetry.
- On-Premises:Maintains sensor data within facility-controlled server infrastructure behind air-gapped networks. Middle Eastern oil operators and US defense contractors specify on-premises deployment to satisfy national data localization statutes.
- Cloud-Based:Streams processed metrics to vendor-managed data centers with elastic compute scaling. Automotive tier-two suppliers in the US Midwest favor subscription access to avoid capital-intensive server procurement.
- Hybrid:Retains critical alerts at the edge while archiving historical trends in cloud repositories.
- Edge Computing:Executes inference algorithms on ruggedized gateways co-located with physical assets.
Cloud-based subscriptions are climbing the fastest among mid-sized manufacturers seeking operational technology autonomy.
End User:
Vertical-specific failure modes dictate sensor modality selection and algorithm training priorities.
- Manufacturing:Monitors CNC spindle bearings, conveyor systems, and robotic actuators for unplanned downtime prevention. German automotive OEMs embed condition monitoring as standard equipment under CE marking requirements for machinery safety.
- Oil & Gas:Surveils centrifugal compressors, pumps, and subsea production systems in hazardous area classifications. FERC reliability standards compel US pipeline operators to document continuous equipment health surveillance.
- Transportation:Tracks rail wheelsets, marine propulsion systems, and fleet vehicle powertrain degradation.
- Power Generation:Protects gas turbines, hydroelectric generators, and wind drivetrains from catastrophic failure.
Power generation commands the highest software spend per megawatt of installed capacity.
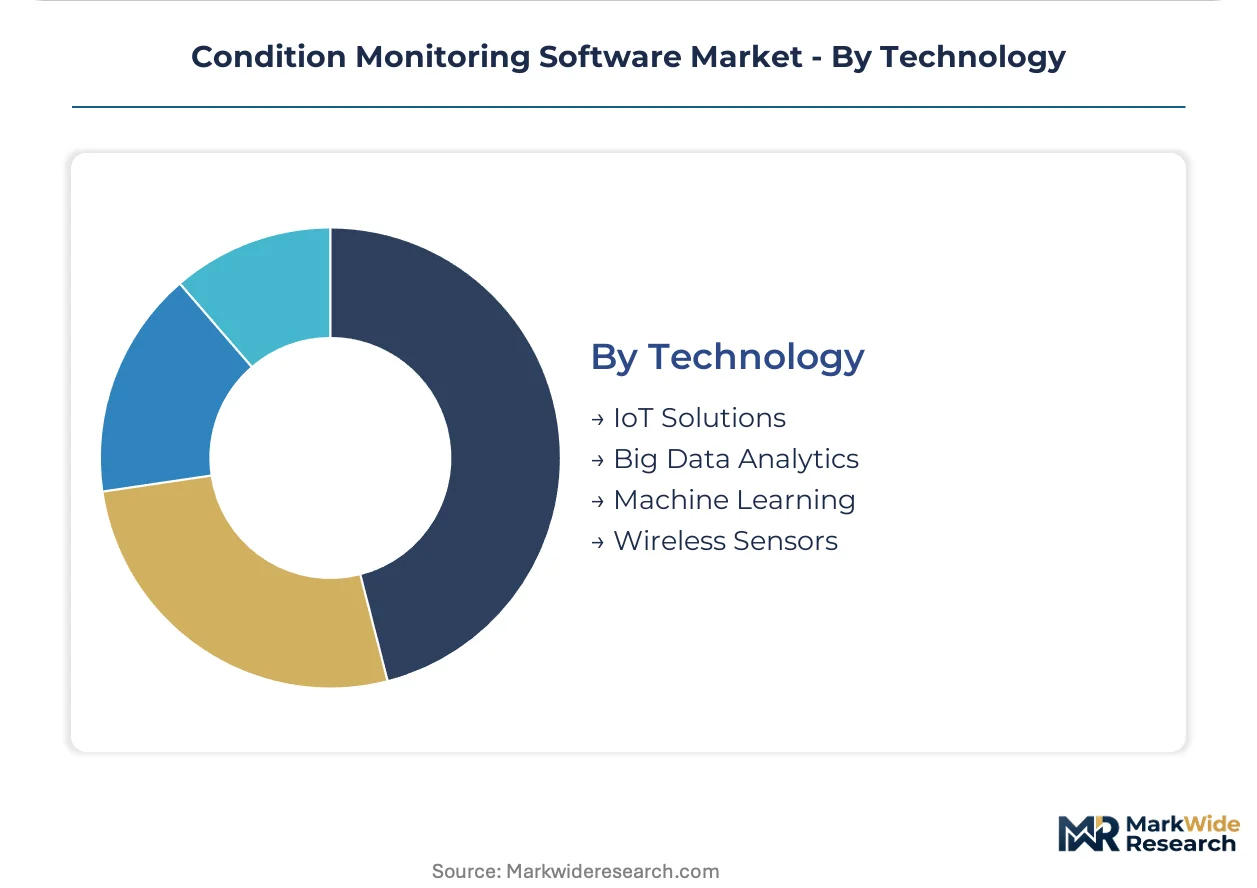
Technology:
Underlying technology stacks determine interoperability, model sophistication, and hardware integration complexity.
- IoT Solutions:Connects distributed sensor nodes through industrial protocols including MQTT and OPC-UA. Wind farm operators in Denmark deploy LoRaWAN mesh networks across geographically dispersed turbine clusters.
- Big Data Analytics:Processes terabyte-scale historical archives to establish baseline degradation signatures. Thermal power stations in India apply pattern recognition across decades of operational data for remaining useful life estimation.
- Machine Learning:Automates anomaly classification through neural networks trained on labeled failure examples.
- Wireless Sensors:Eliminates cabling costs in retrofit applications and hazardous environments.
Wireless sensors are gaining share fastest in brownfield installations where conduit routing is prohibitively expensive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for capital goods and electronics manufacturing is concentrating greenfield plant construction in industrial corridors. Special economic zones in Gujarat and Tamil Nadu offer accelerated depreciation for condition monitoring infrastructure.
United States
FERC reliability standards and OSHA mechanical integrity mandates compel power utilities and refineries to document continuous equipment surveillance. Pipeline operators in Texas and Louisiana procure audit-trail software to satisfy federal compliance logging requirements. The Gulf Coast petrochemical corridor anchors demand for vibration monitoring in centrifugal compressor fleets.
Germany
Automotive OEMs and machinery builders embed condition monitoring as standard equipment under CE marking requirements for machinery safety. The EU Machinery Directive pushes continuous uptime guarantees into supplier contracts. Industrial clusters in Baden-Württemberg and Bavaria mandate predictive maintenance integration for export certification.
India
Automotive tier-one suppliers and capital goods manufacturers deploy condition monitoring from plant commissioning under PLI scheme incentives. The Central Electricity Authority mandates generator health surveillance for grid-connected assets above 100 MW. Manufacturing investments in Pune and Chennai industrial belts prioritize integrated predictive maintenance platforms.
China
Wind turbine OEMs and thermal power operators scale edge computing architectures for real-time drivetrain analytics under dual carbon emission reduction targets. MIIT industrial internet standards accelerate sensor network deployment in smart factories. Yangtze River Delta manufacturing hubs integrate vibration monitoring into digital twin implementations for export competitiveness.
Saudi Arabia
National data localization statutes mandate on-premises server deployment for oil and gas operators, blocking cloud-native subscription models. The country's national petroleum regulator requires documented mechanical integrity surveillance for subsea production systems. Eastern Province energy clusters procure hybrid edge-cloud architectures to satisfy sovereignty requirements while enabling fleet-scale analytics.
Condition Monitoring Software Market Competitive Environment
Top-tier vendors anchor the integrated platform tier, while specialized sensor analytics providers occupy mid-market positions. The vendor structure concentrates around industrial conglomerates with embedded software divisions and independent condition monitoring specialists. Three archetypes dominate: diversified automation conglomerates, bearing-centric vibration specialists, and industrial software pure-plays. Competitive moves center on absorbing edge analytics capabilities and converging condition monitoring with digital twin platforms.
Within the diversified industrial tier, Siemens AG and Emerson Electric Co. exemplify platform consolidation strategies, while SKF Group occupies a position as a bearing-centric analytics specialist. These three entities represent contrasting approaches to market positioning—Siemens anchoring utility control room integration, Emerson competing through wireless sensor ecosystems, and SKF concentrating rotating machinery expertise.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SKF Group |
| Honeywell International Inc. |
| Siemens AG |
| ABB Ltd. |
| General Electric |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| National Instruments Corporation |
| Others |
Value Chain & Pricing Dynamics
German automotive OEMs and machinery builders concentrate procurement authority for condition monitoring platforms, anchoring contract-based licensing with multi-year predictive maintenance service bundles as the dominant pricing structure. Their mandate for continuous uptime guarantees under CE marking requirements transfers pricing power toward vendors with integrated digital twin capabilities.
Pricing Analysis
Premium pricing attaches to edge computing deployments with sub-second latency guarantees for critical rotating machinery, while spot-access cloud subscriptions trade at discounts for mid-sized manufacturers with tolerance for batch-processed analytics. Three-tier pricing structure across premium, standard, and economy levels separates digital twin-integrated platforms from standalone vibration modules and basic threshold-alert systems. Cost compression in the standard tier intensifies as industrial distributors lose attach-rate margins to vendor direct sales. Automotive tier-two suppliers exhibit highest price sensitivity, seeking operational technology autonomy from OEM-mandated maintenance programs.
Supply Chain Analysis
Specialized ADC chips for high-frequency vibration acquisition rest on Taiwan and South Korea foundries, with analog front-end components drawing from Japanese precision sensor manufacturers. Edge gateway hardware sources ruggedized enclosures from German industrial enclosure specialists and GPU accelerators from US semiconductor designers. Single-source vulnerability concentrates in vibration-grade piezoelectric elements where two European suppliers anchor global capacity. Distribution runs through industrial automation distributors in the US Midwest and direct vendor relationships with German machinery OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Condition monitoring software is becoming a vertical-integration race where control over edge hardware determines algorithm deployment speed and data sovereignty compliance. Incumbents and challengers alike are pursuing backward integration into sensor manufacturing to secure supply continuity.
For Market Incumbents: Anticipate margin pressure from unbundled software subscriptions by embedding predictive algorithms directly into bearing and sensor hardware at the point of manufacture. Secure exclusive supply agreements with Taiwan-based ADC foundries before lead time extensions constrain hardware-software bundle rollouts. Prioritize IEC 62443 cybersecurity certification to defend against mid-market pure-plays targeting compliance-delayed deployment cycles.
For New Entrants and Emerging Players: Industrial distributors in the US Midwest represent the most penetrable channel partner type, having lost attach-rate margins as buyers source cloud platforms through vendor direct sales. Target automotive tier-two suppliers seeking operational technology autonomy from OEM-mandated maintenance programs. White-space sits in drone-mounted thermal inspection systems for offshore wind blade monitoring where physical access remains hazardous.
For Investors and Strategic Acquirers: The window for entry favors edge analytics specialists with proven neural network execution on ruggedized gateways. Long-term viability hinges on convergence with physics-based digital twin platforms for remaining useful life prediction in high-value turbomachinery. Watch for FERC reliability standard amendments as the signal to monitor for accelerated procurement timelines in US power generation.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Integration | Embedded GPU accelerators from NVIDIA enable neural network execution directly at Danish wind farm sensor nodes. |
| Digital Twin Convergence | Physics-based modeling fused with operational sensor streams opens premium software tiers for Siemens utility customers. |
| Cybersecurity Certification | IEC 62443 compliance timelines extend deployment cycles, creating defensive moats for pre-certified vendors. |
| Direct Cloud Subscription | Vendor-direct SaaS procurement displaces industrial distributor margins across US Midwest manufacturing belts. |
| Regulatory Compliance Module | EU CSRD disclosure requirements push asset owners toward energy-efficiency monitoring with carbon intensity correlation. |
Study Parameters
SEC filings from Emerson Electric and SKF Group, FERC reliability standard documentation, and EU Machinery Directive regulatory texts formed the secondary backbone for market sizing and competitive positioning. Primary interviews with maintenance directors at German automotive OEMs, plant engineers at US Gulf Coast refineries, and aftermarket service heads at industrial distributors validated deployment trends and procurement timelines. Bottom-up triangulation across sensor modality adoption rates and top-down validation against predictive maintenance software spending disclosed in utility capital expenditure reports anchored volume estimates.
Historical trendline analysis of vibration monitoring software adoption across power generation utilities established baseline growth patterns extrapolated across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-use vertical, sensor modality, and organization size tier. CAGRs derived from fitted growth curves applied to disclosed platform subscription revenues and hardware-software bundle attach rates. Forecast inputs incorporated wind turbine fleet expansion timelines in the North Sea and PLI scheme incentive trajectories for Indian manufacturing capacity.
Caveats apply where semiconductor supply concentration or data sovereignty statute amendments could materially shift the outlook. Forecasts reflect assumptions regarding edge computing cost trajectories and interoperability standardization timelines. A small set of named triggers—Taiwan foundry capacity allocation, FERC mandate expansion, EU AI Act enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Asia-Pacific Data Monetization Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Global DDI Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Smart Card in Government Market