
 Big Data As a Service (Bdaas) Market | 2026-2036
Big Data As a Service (Bdaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data As a Service (Bdaas) Market Intelligence
Healthcare and life sciences is realigning toward predictive patient analytics and population health management, pulling substantial BDaaS consumption toward HIPAA-compliant cloud environments. Amazon Web Services anchors this vertical through FedRAMP-authorized health data lakes. Microsoft Azure competes with specialized FHIR interoperability layers. Google Cloud differentiates via Vertex AI integrations for genomics workloads.
Big Data As a Service denotes the outsourced delivery of distributed data processing, storage, and analytics capabilities via cloud subscription models, typically leveraging Apache Spark, Presto, or proprietary query engines across elastic compute clusters. Its primary commercial purpose is eliminating capital expenditure on on-premise data infrastructure while enabling elastic scaling for variable analytical workloads. Public cloud deployment captures the dominant revenue share as enterprises prioritize OpEx flexibility, though hybrid cloud configurations are expanding fastest among regulated industries requiring data residency controls. Data analytics and data governance solution offerings concentrate margin pools, with predictive maintenance and fraud detection use cases driving the steepest growth trajectories in manufacturing and financial services end-user industries.
HIPAA in the United States, GDPR in Europe, and India's DPDP Act are tightening data localization and cross-border transfer rules, compelling providers to certify region-specific infrastructure and encryption standards. The EU AI Act adds algorithmic accountability requirements for automated decision systems built on BDaaS platforms. Stakeholders must monitor evolving certification burdens against the operational flexibility that multi-cloud orchestration promises.
Market Dynamics
Cloud data sovereignty mandates are fragmenting procurement patterns across the Big Data As a Service ecosystem, compelling providers to replicate infrastructure stacks across jurisdictional boundaries rather than optimizing for centralized scale economies.
Growth Catalysts
- FHIR Interoperability Mandates:Healthcare systems in the United States face HIPAA-aligned data exchange requirements that accelerate migration from on-premise Hadoop clusters to managed cloud-native architectures.
- EU AI Act Algorithmic Accountability:Automated decision systems deployed on BDaaS platforms must now maintain audit trails, creating sustained demand for governance-embedded analytics stacks.
- Real-Time Risk Analytics:Financial services firms in India and Germany are expanding consumption of streaming data platforms for fraud detection and regulatory reporting workloads.
Market Restraints
- Cross-Border Data Transfer Friction:GDPR adequacy decisions and India's DPDP Act data localization rules fragment global workloads into region-isolated deployments.
- Specialized Talent Scarcity:Shortage of Apache Spark optimization engineers and cloud-native security architects constrains enterprise migration velocity.
- Hybrid Cloud Complexity Premium:Regulated industries requiring data residency controls face 15-40% operational overhead versus pure public cloud configurations.
Strategic Opportunities
- Genomics Workload Expansion:Vertex AI integrations for population-scale genomic analysis represent underpenetrated white space in life sciences BDaaS consumption.
- Predictive Maintenance Convergence:Manufacturing sectors in Germany are combining IoT sensor streams with machine learning pipelines for asset optimization.
- FedRAMP-Authorized Health Data Lakes:Federal healthcare agencies in the United States create procurement preference for pre-certified cloud infrastructure.
Industry Challenges
- Legacy System Integration:Mainframe data warehouses and COBOL-based transaction systems resist seamless API connectivity to modern analytics platforms.
- Multi-Cloud Orchestration Talent:Kubernetes-native data engineering skills remain concentrated among hyperscaler-certified professionals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data As a Service (Bdaas) Market |
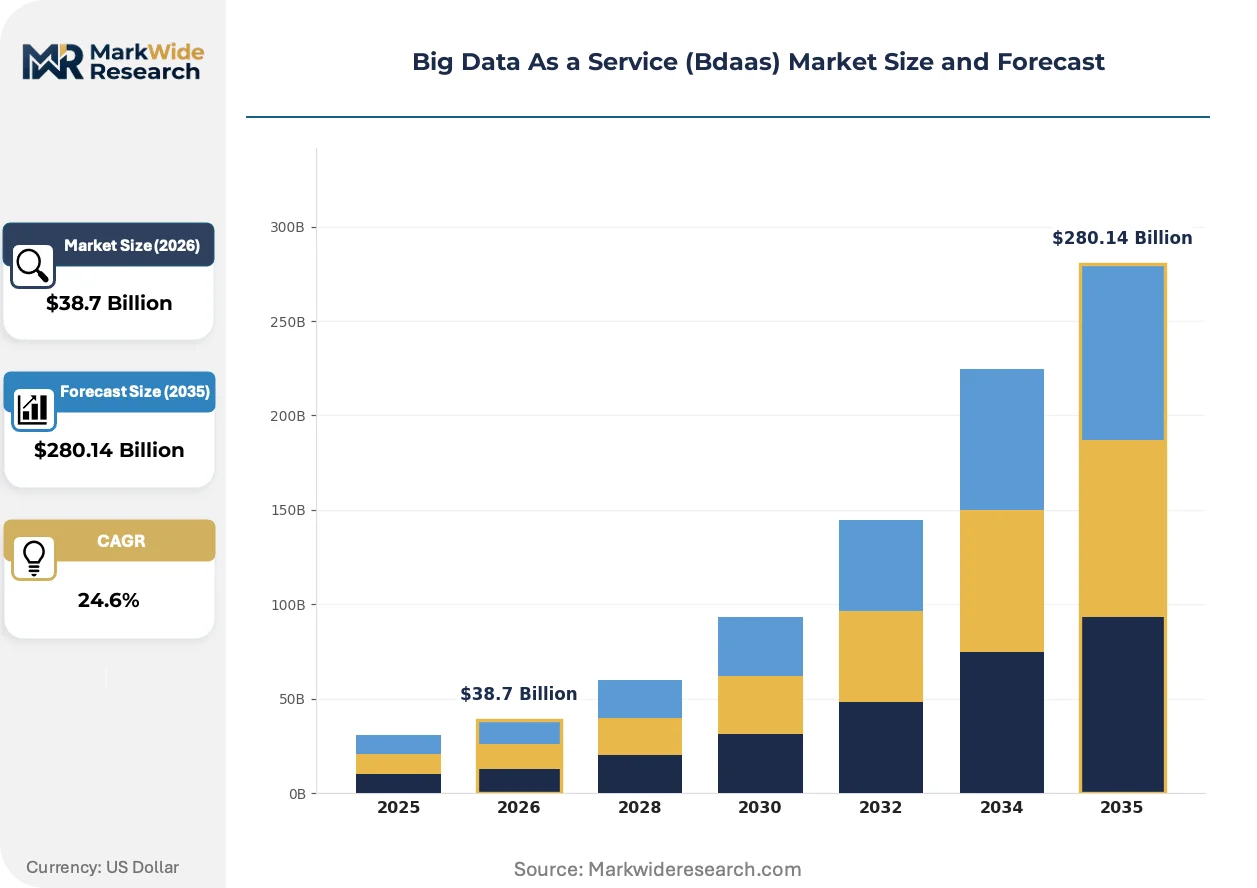
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Data Integration, Data Storage, Data Analytics, Data Visualization, Data Governance Use Case: Customer Insights, Risk Management, Predictive Maintenance, Fraud Detection, Supply Chain Optimization End User Industry: Telecommunications, Manufacturing, Energy & Utilities, Media & Entertainment, Transportation |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Corporation, Oracle Corporation, SAP SE, Hewlett Packard Enterprise, Accenture, Cloudera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data As a Service (Bdaas) Market Strategic Shifts & Innovations
Generative AI is compressing the analytics development lifecycle, shifting competitive advantage from infrastructure scale to model-serving latency and vector database performance.
Apache Iceberg and Delta Lake table formats are automating schema evolution and time-travel queries across petabyte-scale data lakes. Financial services firms in the United States are adopting these open protocols fastest, replacing proprietary warehouse engines. This standardization is automating vendor lock-in reduction and enabling workload portability across cloud providers.
The EU AI Act imposes conformity assessment requirements for high-risk automated decision systems, compelling BDaaS providers to embed algorithmic impact documentation and human oversight interfaces. Healthcare and credit scoring applications face the steepest compliance burden. German enterprises are responding by pre-certifying entire analytics pipelines rather than individual models.
Consumption-based pricing is displacing reserved capacity contracts as the dominant procurement model for variable analytical workloads. Mid-market enterprises in India prefer this flexibility over multi-year commitments. Manufacturing verticals show the fastest behavioral shift, correlating analytics spend directly with production volume fluctuations rather than fixed IT budgets.
Big Data As a Service (Bdaas) Market Segmentation
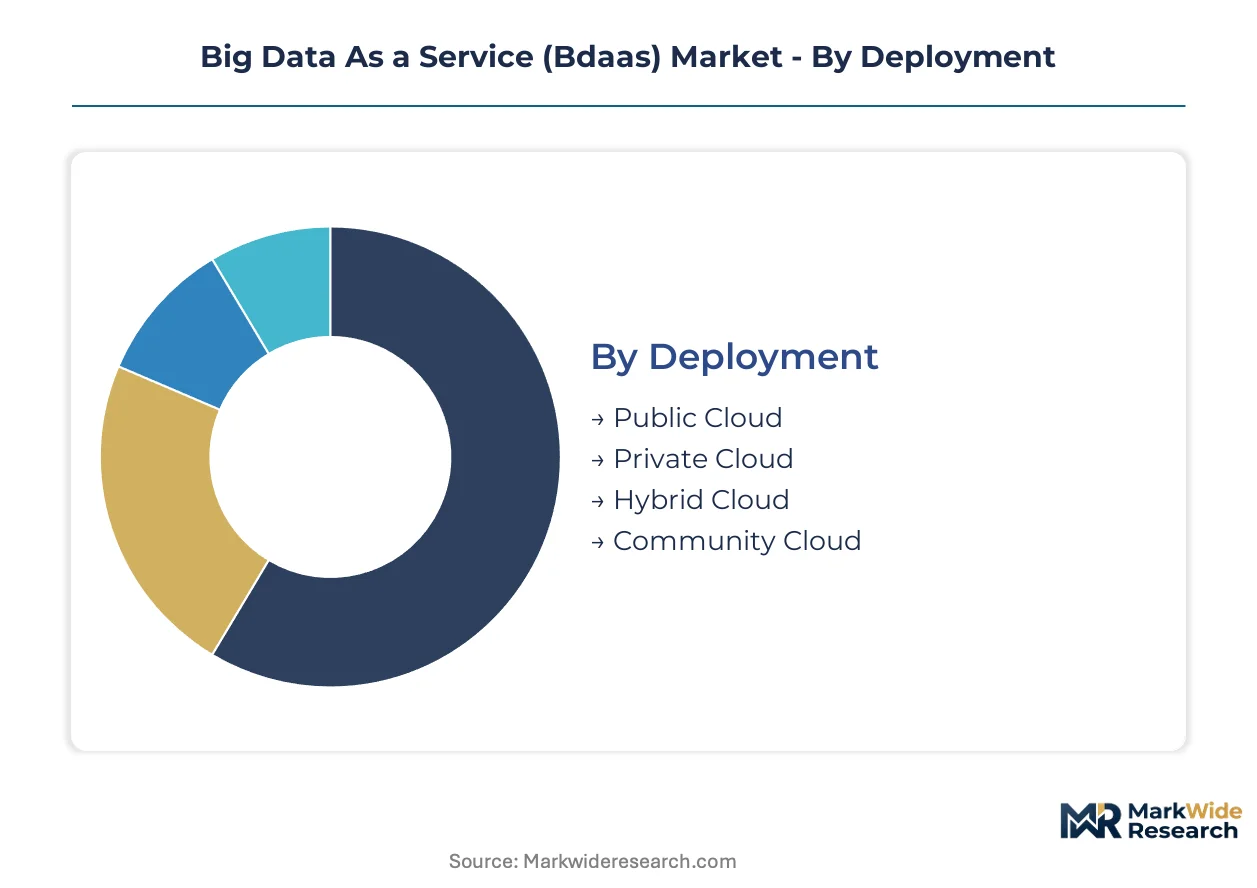
BDaaS procurement patterns diverge sharply across deployment architectures and solution layers, with regulatory pressure and workload volatility determining where enterprises concentrate spending. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Deployment:
Supply concentration in hyperscaler infrastructure is fragmenting as data sovereignty mandates force regional replication of compute stacks.
- Public Cloud:Elastic compute clusters operated by hyperscalers deliver Apache Spark and Presto query engines via subscription models. Financial services firms in Germany and India are migrating risk analytics workloads here for OpEx flexibility, though GDPR adequacy decisions constrain cross-border data flows.
- Hybrid Cloud:Split architectures partition sensitive data on-premise while bursting analytical workloads to public infrastructure. Manufacturing sectors in Germany absorb 15-40% operational overhead for this configuration to satisfy data residency controls while preserving scalability.
- Private Cloud:Dedicated infrastructure stacks deployed within enterprise firewalls or single-tenant hosted environments.
- Community Cloud:Shared infrastructure serving specific industry consortia or regulatory-bound stakeholder groups.
Public Cloud absorbs the bulk of installed capacity; Hybrid Cloud is expanding most quickly.
Solution Offering:
Margin concentration follows the analytics value chain upstream from raw storage toward governance-embedded intelligence.
- Data Analytics:Distributed processing engines enabling predictive modeling, streaming analytics, and machine learning pipeline execution. Healthcare systems in the United States are pulling consumption toward HIPAA-compliant environments for population health management.
- Data Governance:Policy enforcement, lineage tracking, and compliance automation layers. The EU AI Act is accelerating procurement here as German enterprises pre-certify entire analytics pipelines for algorithmic accountability.
- Data Integration:ETL/ELT pipelines and real-time streaming ingestion frameworks.
- Data Storage:Object stores, data lakes, and lakehouse architectures using Iceberg or Delta Lake formats.
- Data Visualization:Dashboard and reporting interfaces consuming curated analytical outputs.
Data Analytics captures the dominant revenue share; Data Governance is climbing the fastest.
Use Case:
Application intensity varies by sectoral digital maturity and regulatory exposure to automated decision systems.
- Fraud Detection:Real-time pattern recognition across transaction streams for financial crime prevention. Indian banks are expanding streaming platform consumption here under RBI supervision, correlating analytics spend directly with transaction volume fluctuations.
- Predictive Maintenance:IoT sensor fusion with machine learning for asset degradation forecasting. German manufacturing combines this with digital twin architectures for production line optimization.
- Customer Insights:Behavioral segmentation and personalization engines.
- Risk Management:Credit scoring, market risk simulation, and regulatory capital calculation.
- Supply Chain Optimization:Demand forecasting and logistics orchestration across distributed networks.
Fraud Detection concentrates current procurement volume; Predictive Maintenance is gaining share fastest.
End User Industry:
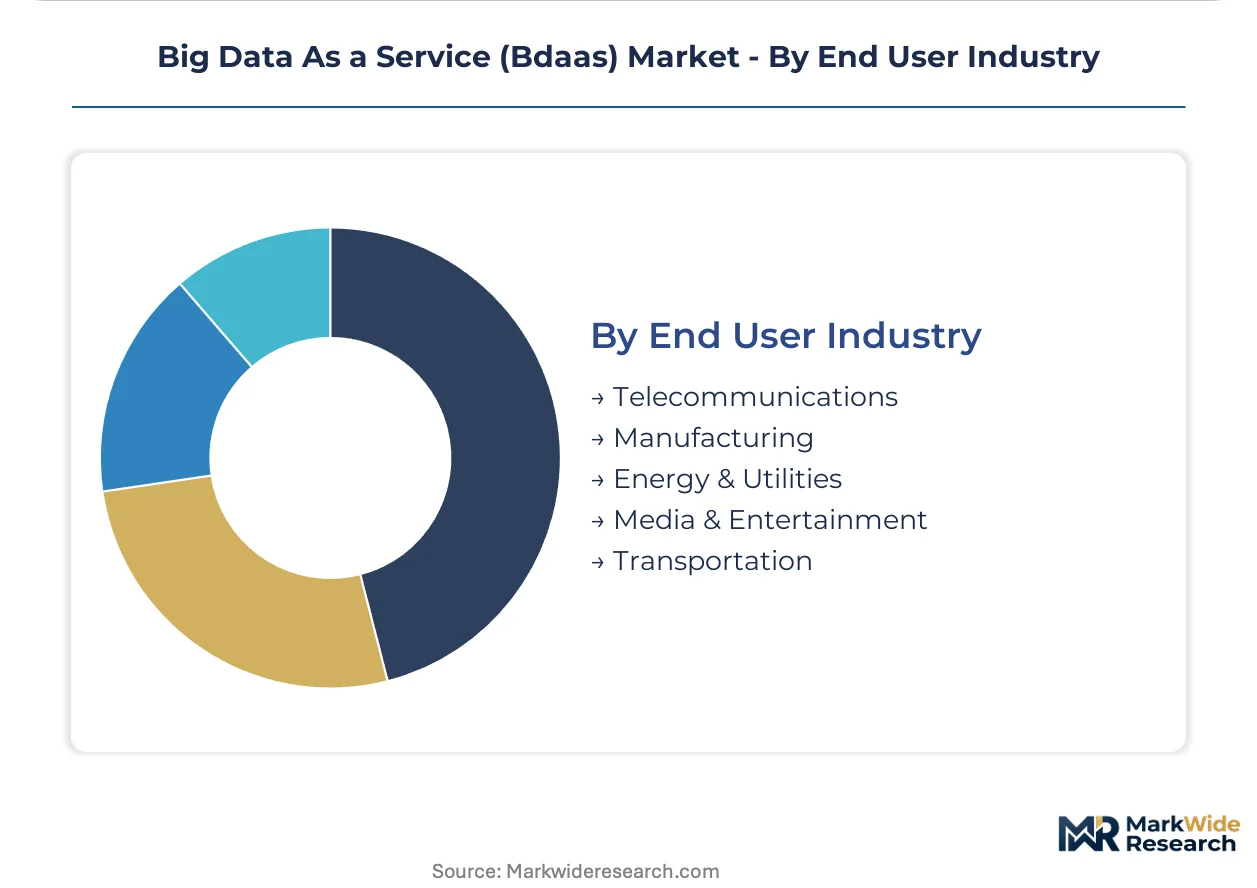
Sectoral adoption velocity reflects regulatory data localization requirements and legacy system replacement cycles.
- Manufacturing:Industrial IoT integration and quality analytics driving BDaaS consumption. German automotive and machinery producers are converging sensor streams with Vertex AI pipelines for asset optimization.
- Telecommunications:Network performance analytics and subscriber behavior modeling at massive scale.
- Energy & Utilities:Grid optimization and predictive infrastructure maintenance.
- Media & Entertainment:Content recommendation and audience analytics.
- Transportation:Fleet optimization and autonomous system development.
Manufacturing anchors sectoral demand; Telecommunications is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BDaaS infrastructure production clusters in the United States, Germany, and India while consumption spreads across regulated industries demanding data sovereignty compliance. Cloud providers replicate compute stacks across jurisdictional boundaries rather than optimizing for centralized scale. Procurement patterns fragment as GDPR adequacy decisions and sectoral privacy laws reshape deployment architectures.
United States
Federal healthcare agencies and financial services firms drive demand for FedRAMP-authorized health data lakes and real-time risk analytics platforms. HIPAA mandates accelerate migration from on-premise Hadoop clusters to managed cloud-native architectures. The Greater Boston biotech corridor and New York financial district concentrate consumption of predictive patient analytics and fraud detection workloads.
Germany
Automotive and machinery producers in Baden-Württemberg converge IoT sensor streams with machine learning pipelines for asset optimization. The EU AI Act imposes algorithmic accountability requirements that compel enterprises to pre-certify entire analytics pipelines. Manufacturing verticals absorb 15-40% operational overhead for hybrid cloud configurations to satisfy data residency controls.
India
Banks under RBI supervision expand streaming platform consumption for fraud detection and regulatory reporting workloads. The DPDP Act data localization rules fragment global workloads into region-isolated deployments. Bangalore and Hyderabad anchor hyperscaler infrastructure expansion as mid-market enterprises prefer consumption-based pricing over multi-year commitments.
United Kingdom
Financial services firms in London migrate credit scoring and market risk simulation workloads to compliant cloud environments. GDPR adequacy decisions constrain cross-border data flows while creating procurement preference for UK-sovereign infrastructure. The Cambridge life sciences cluster pulls BDaaS consumption toward HIPAA-aligned data exchange architectures.
Japan
Manufacturing conglomerates in the Chubu region deploy predictive maintenance solutions combining digital twin architectures with Vertex AI integrations. METI industrial digitization programs subsidize cloud migration for quality analytics and supply chain optimization. Tokyo anchors regional demand for network performance analytics at telecommunications scale.
Big Data As a Service (Bdaas) Market Key Industry Players
Top-tier vendors anchor hyperscale infrastructure tiers, while specialized platform providers and systems integrators occupy differentiated positions. The market structure concentrates around cloud-native compute stacks with governance-embedded analytics layers. Three archetypes dominate: hyperscaler infrastructure operators, enterprise software incumbents with data governance portfolios, and vertical specialists in regulated industry compliance. Competitive moves center on multi-cloud orchestration capabilities and region-specific certification attainment.
Within the hyperscaler tier, Amazon Web Services, Microsoft Azure, and Google Cloud represent the dominant infrastructure anchors. These entities exemplify scale-driven competitive positioning through elastic compute clusters and proprietary query engines delivered via subscription models. Each occupies a distinct vertical specialization vector—health data lakes, FHIR interoperability layers, and genomics workload integrations respectively—while competing for manufacturing and financial services consumption in Germany and India.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Hewlett Packard Enterprise |
| Accenture |
| Cloudera |
| Others |
Cost & Logistics Intelligence
FedRAMP-authorized procurement preferences in United States federal healthcare agencies are compelling hyperscalers to replicate certified infrastructure stacks across multiple availability zones, fragmenting scale economies and elevating operational overhead into subscription pricing. German automotive manufacturers' demand for data-resident hybrid configurations absorbs 15-40% cost premiums versus pure public cloud deployments, compressing margin pools for providers unable to certify region-specific encryption standards.
Pricing Analysis
Short lead-time provisioning for streaming analytics workloads commands premium subscription tiers, while reserved capacity contracts for batch processing offer discounted rates. Consumption-based pricing stratifies across premium, standard, and economy tiers differentiated by SLAs and support responsiveness. Pricing pressure stems from mid-market enterprises in India preferring pay-as-you-go flexibility over multi-year commitments. Financial services firms in Germany exhibit lowest price sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Specialized GPU clusters for genomics workloads rest on Taiwanese semiconductor foundries and South Korean memory fabricators. Apache Spark optimization talent concentrates in United States and Indian technology corridors. Supply chain risk centers on single-source vulnerability for advanced AI accelerators constrained by export control classifications. Distribution runs through hyperscaler direct sales organizations and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apache Spark optimization engineer scarcity constrains enterprise migration velocity, propping pricing power for providers with certified training pipelines and managed service capabilities.
For Market Incumbents: Lock in healthcare and financial services verticals through pre-certified FedRAMP and HIPAA-compliant infrastructure stacks before EU AI Act algorithmic accountability requirements harden procurement criteria. Defend against emerging vertical specialists by embedding governance automation layers directly into analytics pipelines. Prioritize capacity expansion in Bangalore and Hyderabad to capture Indian mid-market consumption-based demand. For New Entrants and Emerging Players: Enter via genomics workload specialization in life sciences, where Vertex AI integration gaps create white space underserved by generalized hyperscaler offerings. Target German manufacturing predictive maintenance segments combining IoT sensor fusion with digital twin architectures. Lead with consumption-based pricing models correlating analytics spend directly with production volume fluctuations. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with embedded compliance automation for EU AI Act algorithmic accountability requirements. Long-term viability hinges on governance-embedded analytics capabilities rather than raw infrastructure scale. Watch for consolidation triggers when hyperscaler certification backlogs exceed twelve-month provisioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Certification Acceleration | Pre-certified health data lakes capture United States federal procurement preference before competitors complete authorization timelines. |
| FHIR Interoperability Layer Development | Specialized data exchange protocols differentiate Microsoft Azure against Amazon Web Services in HIPAA-aligned healthcare migrations. |
| Vertex AI Genomics Integration | Population-scale genomic analysis capabilities open underpenetrated life sciences consumption white space for Google Cloud. |
| Hybrid Cloud Operational Streamlining | Reducing 15-40% overhead premium for data-resident configurations expands addressable market among German automotive manufacturers. |
| Consumption-Based Pricing Infrastructure | Variable workload correlation with production volume fluctuations captures Indian mid-market enterprises abandoning fixed IT commitments. |
Research Approach
Document review covered hyperscaler capex disclosures, SEC 10-K filings, and regulatory certification databases, complemented by interviews with cloud platform engineers, healthcare IT procurement officers, financial services risk analytics directors, and data governance consultants. Secondary sources included GDPR adequacy decision records, EU AI Act implementation guidance, and RBI supervisory circulars on data localization. Bottom-up segment sizing triangulated against top-down infrastructure capacity estimates.
Historical deployment velocity cross-referenced against panel input from enterprise architects and channel partners informed projection trajectories across the analysis window. Segmentation modeled deployment architecture, solution offering tier, use case intensity, and end-user industry regulatory exposure. CAGRs derived from elasticity-adjusted adoption curves incorporating compliance mandate effective dates and legacy system replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt export control expansions affecting AI accelerator availability or accelerated EU AI Act enforcement timelines. A small set of named triggers warrants ongoing watch: hyperscaler certification backlog durations, DPDP Act implementation strictness in India, and FHIR mandate expansion beyond United States federal agencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
United States ICT Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
IT Service Management Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Global Freelance Platforms Market