
 Artificial Intelligence Based Personalization Market | 2026-2036
Artificial Intelligence Based Personalization Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence Based Personalization Market Analysis
The EU AI Act is realigning the cost-of-entry calculus for AI personalization vendors serving European enterprises. Amazon leverages its proprietary recommendation infrastructure to sustain dominance in e-commerce personalization. Google anchors its competitive position through deep integration of machine learning across advertising and content delivery platforms. Microsoft differentiates by embedding AI personalization tools within enterprise cloud suites that span customer relationship management and productivity workflows.
Artificial intelligence based personalization encompasses algorithmic systems that analyze behavioral signals, demographic attributes, and contextual data to generate individualized content, product suggestions, or service configurations in real time. These systems typically operate through supervised learning pipelines, reinforcement learning feedback loops, or transformer architectures processing multimodal inputs, with latency requirements often below 100 milliseconds for real-time deployment. Their primary commercial purpose centers on improving conversion rates, extending customer lifetime value, and reducing churn across digital touchpoints. Machine learning and natural language processing together constitute the technology backbone where margin pools concentrate, given the computational intensity and specialized talent required. Cloud-based deployment leads in adoption velocity among retailers and media companies, while on-premises and hybrid configurations persist among financial service providers and healthcare systems governed by strict data residency requirements.
The US Federal Trade Commission scrutinizes AI-driven personalization for discriminatory outcomes in credit, housing, and employment decisions, elevating compliance costs for domestic operators. China's SAMR and MEE enforce algorithmic recommendation transparency rules and data localization standards that fragment technical architectures for multinationals. ISO and IEC develop interoperable standards for AI system trustworthiness that shape procurement criteria across regulated industries. Stakeholders must monitor how divergent regulatory timelines for algorithmic auditing and explainability mandates reshape competitive moats and geographic market access.
Market Dynamics
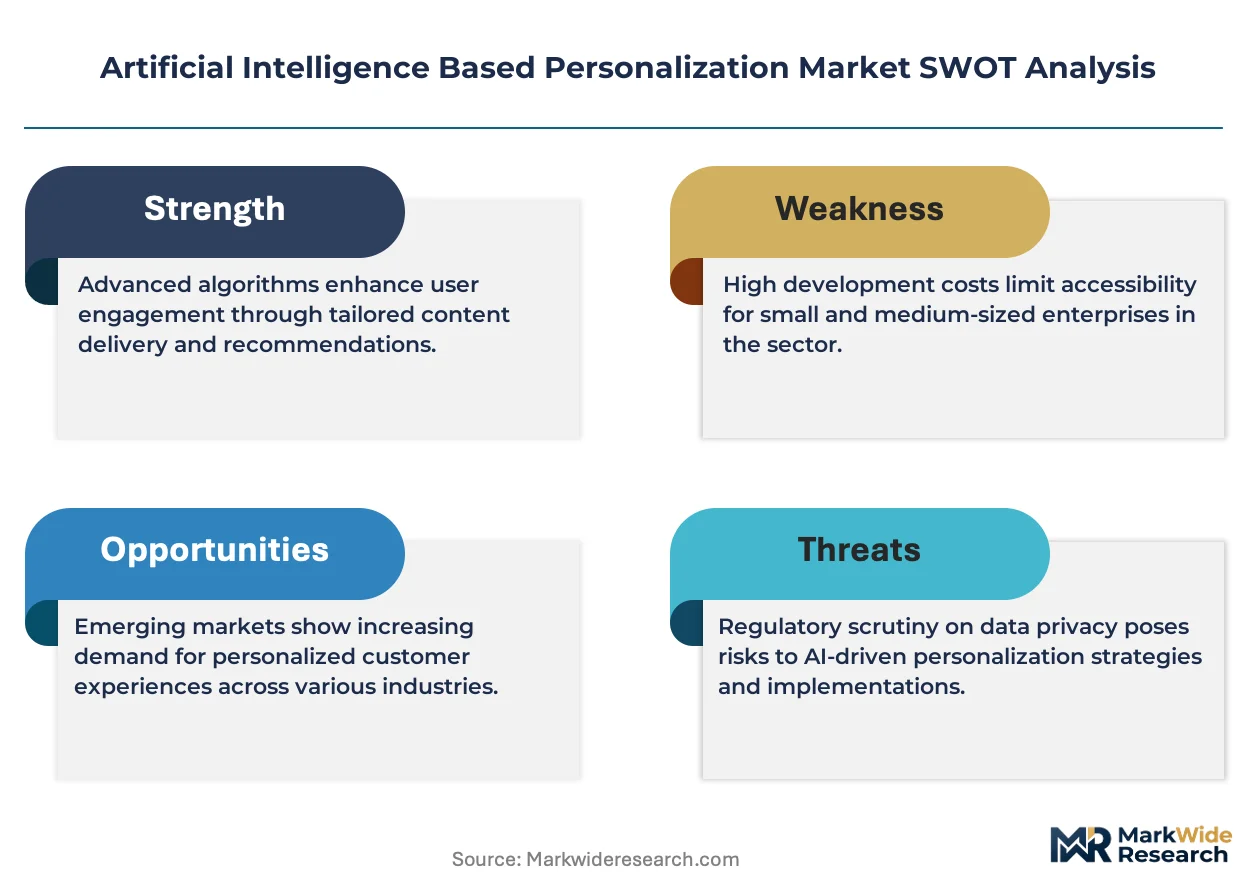
The EU AI Act's algorithmic transparency mandates are forcing personalization vendors to rearchitect inference pipelines, splitting real-time recommendation engines from explainability layers and elevating compliance engineering to a core competency.
Growth Catalysts
- Transformer architectures:Foundation models trained on multimodal behavioral data enable zero-shot personalization without historical user profiles, opening addressable markets in privacy-sensitive jurisdictions.
- GDPR Article 22 clarifications:Recent regulatory guidance on automated decision-making creates legal certainty for consent-based personalization, accelerating enterprise procurement cycles in European financial services.
- Edge inference hardware:Dedicated AI accelerators in smartphones and retail kiosks reduce latency below 50 milliseconds, enabling real-time dynamic pricing at physical point-of-sale terminals.
Market Restraints
- GPU supply concentration:Foundry capacity for high-bandwidth memory chips concentrates in Taiwan and South Korea, creating input cost volatility for training-intensive personalization models.
- SAMR algorithmic filing requirements:China's mandatory registration of recommendation algorithms imposes 60-90 day approval delays, fragmenting technical architectures for multinationals.
- Differential privacy overhead:Mathematical guarantees against re-identification require 15-40% additional compute per inference, compressing margins for real-time deployment at scale.
Strategic Opportunities
- Healthcare patient engagement:HIPAA-compliant personalization for medication adherence and care navigation remains underpenetrated, with health systems seeking vendor-managed infrastructure to limit liability exposure.
- CSRD sustainability reporting:Mandatory disclosure of customer segmentation methodologies creates demand for personalization platforms with built-in audit trails and bias documentation.
- Federated learning architectures:Convergence of edge computing and secure multi-party computation enables personalization without centralizing sensitive behavioral data, addressing data residency requirements in Germany and France.
Industry Challenges
- MLOps talent scarcity:Production-grade personalization requires engineers fluent in both distributed systems and fairness metrics, with compensation premiums exceeding 40% above standard data science roles.
- ISO/IEC 42001 certification timelines:First-party conformity assessments for AI management systems demand 8-14 months, delaying procurement eligibility for regulated industries.
- Legacy CRM integration:Enterprise customer data platforms built on decade-old schemas require expensive middleware development to feed real-time feature stores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence Based Personalization Market |
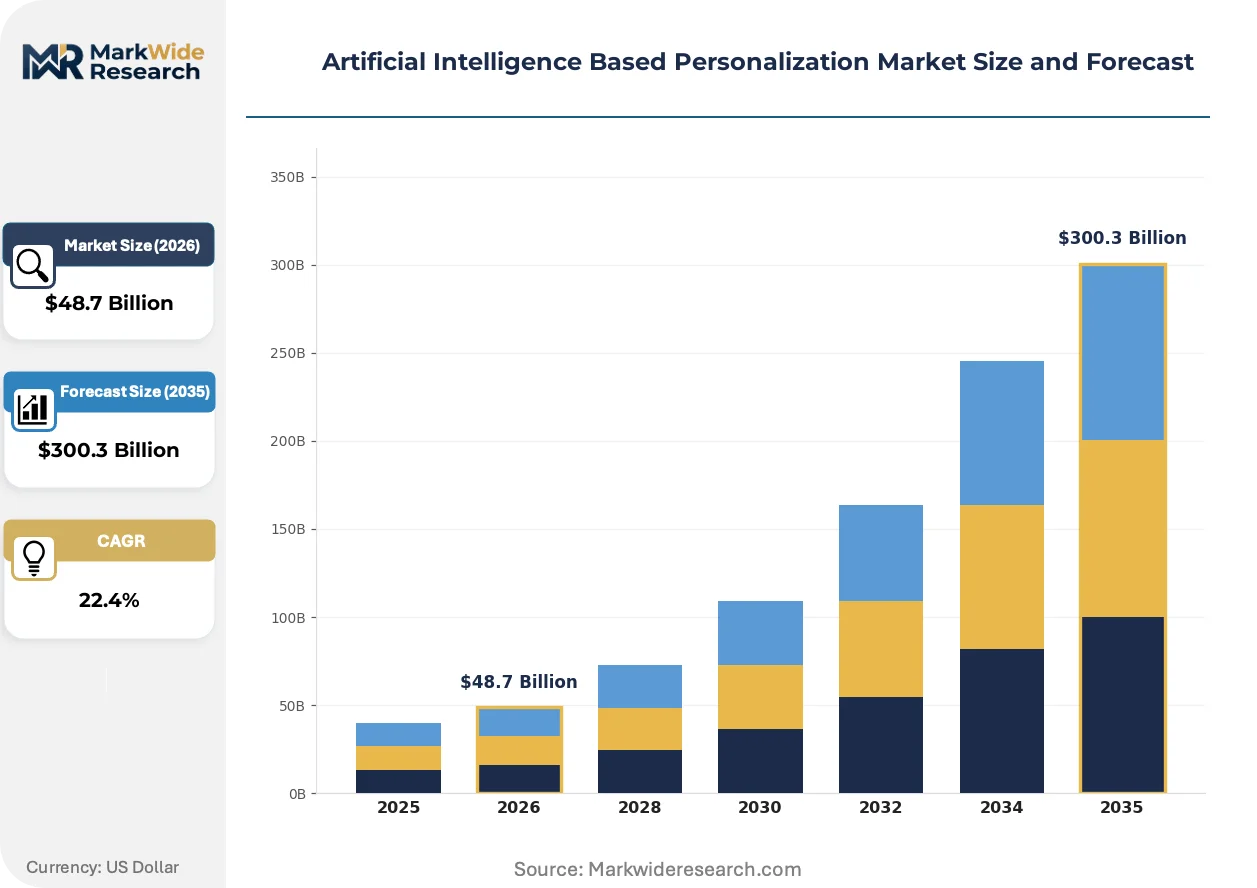
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $300.3 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Application: E-commerce, Marketing Automation, Customer Support, Content Recommendation End User: Retailers, Brands, Service Providers, Media Companies Deployment: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | Amazon, Google, Microsoft, IBM, Salesforce, Adobe, Oracle, SAP, Zeta Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence Based Personalization Market Emerging Trajectories
Foundation models are compressing the traditional feature engineering pipeline, enabling personalization systems to infer intent from sparse signals rather than relying on exhaustive behavioral histories. This shift is redistributing competitive advantage toward compute scale and prompting a wave of infrastructure consolidation.
Retrieval-augmented generation is overtaking static embedding-based recommendation, allowing systems to ground suggestions in fresh inventory data and contractual terms without full model retraining. Retailers with volatile SKU catalogs are adopting this hybrid architecture fastest, compressing the gap between merchandising decisions and customer-facing recommendations from days to minutes.
The EU AI Act's risk classification framework is segmenting the vendor landscape, with high-risk applications—credit scoring, employment matching, insurance pricing—now requiring conformity assessments before deployment. Financial services procurement teams in Frankfurt and Paris are rewriting RFP criteria to prioritize vendors with established notified body relationships, creating first-mover advantages for early certifiers.
First-party data activation is displacing third-party cookie dependency as the dominant targeting paradigm, with publishers and retailers building authenticated identity graphs through loyalty programs and subscription walls. This shift is most visible in the United States, where media companies are vertically integrating into commerce recommendation to monetize logged-in user bases directly.
Artificial Intelligence Based Personalization Market Segmentation
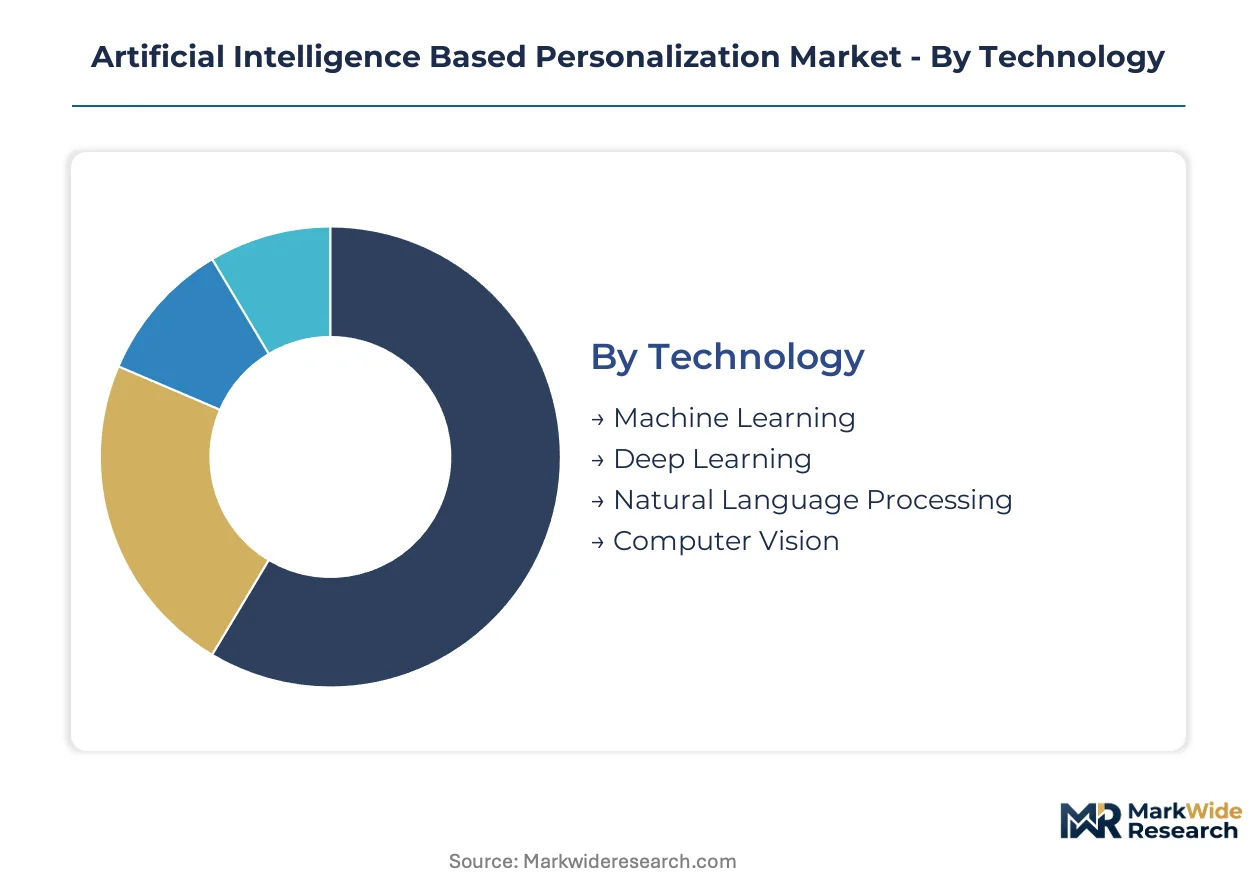
Segmentation in AI personalization reveals how technical architecture, commercial use case, and infrastructure choices partition margin pools. Vendors competing across these boundaries face fundamentally different talent requirements, compliance burdens, and customer procurement cycles.
Technology:
Machine learning and deep learning architectures differentiate on computational intensity, interpretability, and latency tolerance for real-time inference.
- Machine Learning:Supervised learning pipelines on structured behavioral data dominate retail recommendation engines. Scalable feature engineering and well-documented fairness metrics satisfy procurement requirements from Frankfurt financial services firms facing EU AI Act scrutiny.
- Deep Learning:Neural architectures process high-dimensional embeddings for visual and sequential pattern recognition. Demand concentrates in media streaming platforms across the United States, where GPU clusters support billion-parameter models for content matching.
- Natural Language Processing:Transformer-based intent classification powers conversational interfaces and search personalization. German automotive brands deploy these systems for multilingual customer service automation.
- Computer Vision:Convolutional networks analyze visual preferences from browsing behavior and in-store cameras. French luxury retailers use edge-deployed models for real-time styling recommendations.
Machine Learning leads on scale; Deep Learning leads on momentum.
Application:
Commercial deployment contexts determine data pipeline complexity, integration touchpoints, and regulatory exposure for personalization vendors.
- E-commerce:Real-time product matching across volatile SKU catalogs demands sub-100 millisecond inference latency. United States-based marketplaces invest heavily in retrieval-augmented architectures that synchronize inventory updates with customer-facing recommendations.
- Marketing Automation:Cross-channel orchestration of email, push, and display personalization requires identity resolution at scale. European consumer brands prioritize GDPR-compliant consent management embedded directly into campaign workflows.
- Customer Support:Intent classification and agent routing reduce resolution times in high-volume service environments. Indian IT service providers bundle these capabilities into outsourced contact center offerings.
- Content Recommendation:Sequential modeling of engagement signals maximizes dwell time and subscription retention. Japanese publishers and South Korean streaming platforms compete on proprietary algorithms for local language content.
E-commerce commands the largest revenue pool; Marketing Automation is climbing the fastest as B2B procurement accelerates.
End User:
Customer organizational type shapes deployment complexity, data governance requirements, and vendor pricing power.
- Retailers:Omnichannel merchants unify online and in-store behavioral signals for consistent personalization. Walmart and Carrefour-scale operators demand dedicated infrastructure teams and custom model retraining cycles.
- Brands:Consumer packaged goods companies with limited first-party data rely on retail media networks and co-op data partnerships. Procter & Gamble and Unilever procurement teams negotiate algorithmic transparency as a standard contract term.
- Service Providers:Banks, insurers, and telcos embed personalization into core product workflows with strict audit trail requirements. Singaporean and Swiss private banks lead on compliance-engineered procurement specifications.
- Media Companies:Publishers and broadcasters monetize authenticated user bases through subscription and advertising optimization. New York Times and Axel Springer verticals demonstrate the revenue potential of logged-in identity graphs.
Retailers anchor volume demand; Service Providers offer the steepest expansion trajectory as regulated industries digitize.
Deployment:
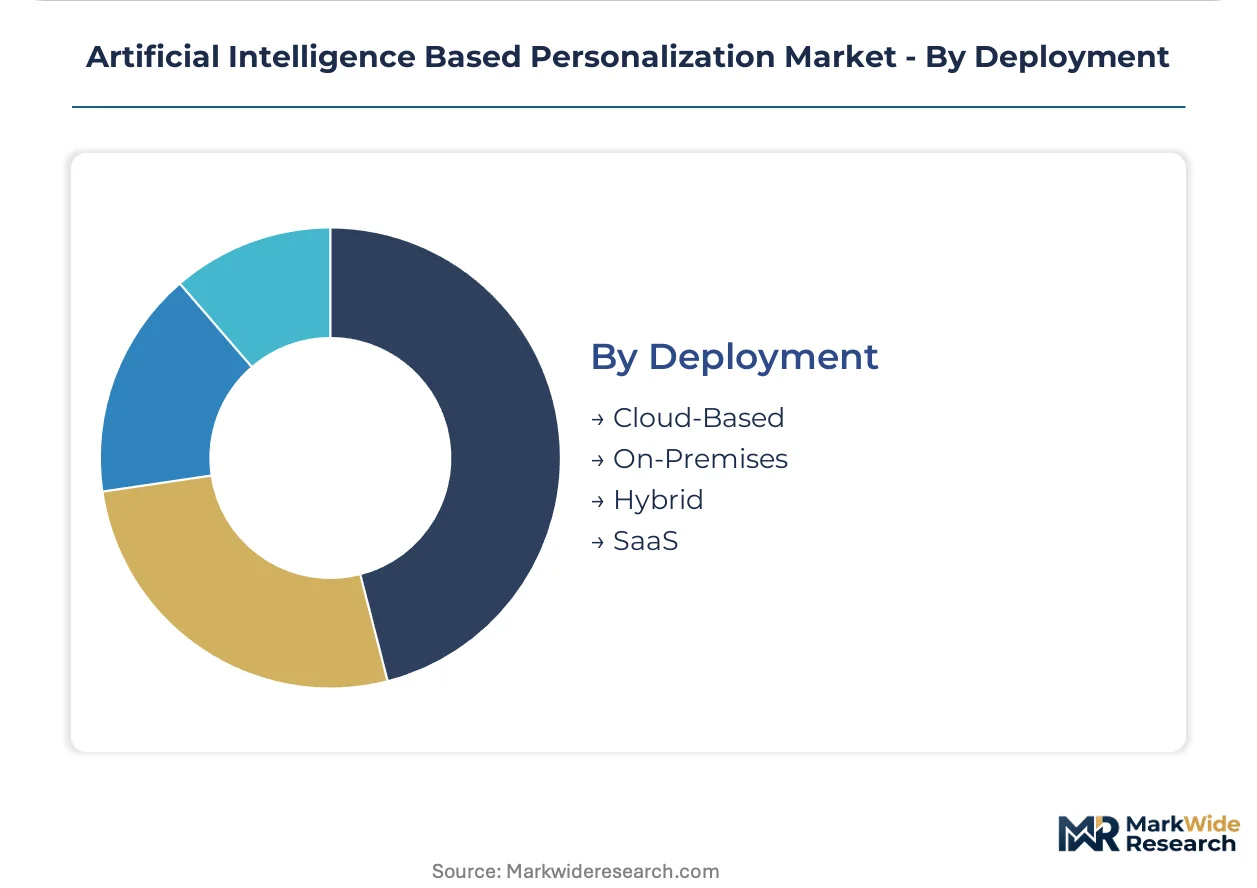
Infrastructure configuration trades operational flexibility against data residency, latency, and total cost of ownership.
- Cloud-Based:Hyperscaler-managed infrastructure enables elastic scaling for traffic spikes and model retraining. United States retailers and media companies default to this mode for speed-to-market.
- On-Premises:Dedicated hardware satisfies data localization mandates in China and sector-specific requirements from Germany's Bundesbank. Capital intensity limits adoption to largest enterprises with captive infrastructure teams.
- Hybrid:Sensitive data processing on-premises combines with cloud-based model development and benchmarking. French healthcare systems and Canadian provincial health authorities favor this architecture for patient engagement personalization.
- SaaS:Pre-configured personalization modules reduce time-to-value for mid-market customers with limited data science resources. Australian and Brazilian e-commerce platforms represent growing adoption clusters.
Cloud-Based dominates current deployment; Hybrid configurations are gaining share fastest as data sovereignty regulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers and MLOps specialists concentrate in Seattle, San Francisco, and Boston, anchoring North American innovation capacity. Cloud infrastructure spending and digital advertising budgets sustain enterprise adoption clusters across these metropolitan hubs.
United States
Retail media networks and streaming platforms drive demand for real-time recommendation engines. The FTC scrutinizes algorithmic decision-making in credit and housing, elevating compliance engineering requirements. Seattle-based hyperscalers dominate cloud-hosted personalization infrastructure.
Germany
Automotive OEMs and industrial manufacturers deploy multilingual customer service automation. The EU AI Act mandates conformity assessments for high-risk personalization applications. Frankfurt financial services firms prioritize vendors with established notified body relationships.
China
E-commerce platforms and short-video applications process billion-scale user interactions. SAMR enforces 60-90 day algorithmic registration delays for recommendation systems. Shenzhen hardware manufacturers supply edge AI accelerators for retail kiosk deployments.
United Kingdom
Publisher subscription optimization and fintech customer engagement sustain vendor demand. GDPR Article 22 guidance on automated decision-making clarifies consent frameworks. London-based media companies vertically integrate into commerce recommendation engines.
France
Luxury retailers and healthcare systems pursue HIPAA-equivalent patient engagement personalization. CNIL enforces strict purpose limitation on behavioral data processing. Parisian banking consortiums federate learning architectures to satisfy data residency requirements.
Artificial Intelligence Based Personalization Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and compliance sophistication tiers. The vendor base stratifies between hyperscale cloud operators, enterprise software incumbents, and vertical-specific personalization engines. Three archetypes dominate: infrastructure-anchored platforms, CRM-embedded modules, and retail-native recommendation systems. Competitive moves concentrate on M&A for identity resolution capabilities and strategic partnerships with edge hardware manufacturers.
Within the infrastructure-anchored tier, Amazon, Google, and Microsoft occupy positions defined by proprietary training clusters and global data center footprints. These hyperscalers exemplify scale-driven competitive moats where inference latency and model refresh cadence separate market tiers.
| Leading Market Players |
|---|
| Amazon |
| Microsoft |
| IBM |
| Salesforce |
| Adobe |
| Oracle |
| SAP |
| Zeta Global |
| Others |
Supply Flow & Price Mechanics
Frankfurt financial services procurement teams concentrate demand for EU AI Act-compliant personalization engines, anchoring a subscription-SaaS pricing model where certification tier determines contract value. Compliance engineering costs flow downstream as vendors split inference pipelines from explainability layers, reshaping how buyers evaluate total cost of ownership.
Pricing Analysis
Bundled platform subscriptions dominate enterprise procurement, while unbundled per-inference pricing serves mid-market retailers with volatile traffic patterns. Three-tier pricing structure across premium, standard, and economy levels separates vendors with notified body relationships from uncertified competitors. Pricing pressure stems from GPU supply concentration in Taiwan and South Korea elevating training costs for foundation model operators. Mid-market e-commerce platforms exhibit highest price sensitivity, while Singaporean private banks accept premium tiers for audit trail guarantees.
Supply Chain Analysis
High-bandwidth memory chip supply rests on TSMC foundry capacity in Taiwan and Samsung HBM3E production in South Korea, with NVIDIA design centers in the United States completing the silicon triad. Cloud hyperscalers draw from these concentrated sources for training clusters, while edge AI accelerator demand feeds from Shenzhen hardware manufacturers. Single-source vulnerability in advanced packaging creates procurement risk for real-time inference deployments. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with system integrators handling legacy CRM integration middleware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement teams in regulated industries prioritize conformity-assessed vendors over lowest-cost alternatives. Foundation model capabilities are concentrating demand toward certified platforms with documented bias audit trails.
For Market Incumbents: Deploy compliance-engineering differentiation by embedding EU AI Act conformity assessments into standard product tiers before competitors complete notified body relationships. Establish captive GPU allocation agreements with foundry partners to secure training capacity against emerging cloud-native challengers. Vertically integrate into edge hardware partnerships to control latency-critical retail kiosk deployments. For New Entrants and Emerging Players: Capture HIPAA-equivalent patient engagement personalization in French and Canadian healthcare systems where incumbent platforms carry liability exposure. Target federated learning architectures for German and French data residency requirements as multinational vendors fragment technical stacks. Lead with vendor-managed infrastructure positioning to limit health system operational burden. For Investors and Strategic Acquirers: Cloud hyperscalers are the most active acquirer in this space, seeking identity resolution capabilities to complete authenticated user graphs. Long-term viability favors vendors with established notified body relationships and proprietary training data moats. Watch for SAMR algorithmic filing delays triggering multinational technical architecture fragmentation as an inflection signal for geographic market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EU AI Act conformity assessments create procurement eligibility barriers for uncertified competitors in Frankfurt and Paris. |
| Retrieval-Augmented Generation Deployment | Hybrid architectures synchronize volatile SKU catalogs with customer-facing recommendations for United States retailers. |
| Federated Learning Architecture Development | Secure multi-party computation addresses data residency requirements in Germany and France without centralizing behavioral data. |
| Edge AI Accelerator Partnership | Shenzhen hardware integration enables sub-50 millisecond inference for physical point-of-sale dynamic pricing. |
| First-Party Data Platform Acquisition | Authenticated identity graphs displace third-party cookie dependency for New York Times and Axel Springer verticals. |
Methodological Framework
Multiple input streams — primary interviews with MLOps engineers and procurement officers at Frankfurt financial services firms, regulatory affairs leads at notified bodies, and cloud infrastructure specialists at Seattle hyperscalers — were reconciled against secondary validation from SEC hyperscaler capex disclosures, EU AI Act implementation guidance, and SAMR algorithmic filing databases. Bottom-up feature store deployment estimates and top-down cloud infrastructure spending patterns were triangulated to anchor market sizing.
Historical foundation model training cost curves were cross-referenced against expert panel inputs on inference latency requirements and compliance engineering timelines. Segmentation modeling spanned technology architecture, application context, deployment mode, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure capacity expansion trajectories. GPU supply concentration and differential privacy compute overhead were incorporated as margin compression inputs.
Regulatory timeline acceleration, foundry capacity constraints, and foundation model capability breakthroughs are the dominant revision risks to the forecast framework. Forecasts reflect documented assumptions on procurement cycle durations and certification pipeline bottlenecks. A small set of named triggers — SAMR filing delays, EU AI Act enforcement actions, and HBM3E supply disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Conversational AI Market