
 Cloud Logistics Software Market | 2026-2036
Cloud Logistics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Logistics Software Market Insights
Mid-market freight brokers is collapsing the traditional buyer hierarchy that large enterprises once dominated in cloud logistics procurement. Oracle Corporation leverages extensive database infrastructure to anchor enterprise-grade supply chain deployments across North America. SAP SE sustains deep ERP integration capabilities that dominate European manufacturing logistics workflows. Manhattan Associates specializes in warehouse execution systems that compete directly with broader platform providers in retail distribution.
Cloud logistics software denotes browser-accessible applications that orchestrate freight movement, inventory positioning, and order fulfillment through API-connected data layers, typically processing real-time telemetry from GPS, RFID, and warehouse sensors to optimize routing and stock allocation. Transportation management systems lead current revenue contribution due to fuel cost volatility and carrier capacity constraints, while AI-driven analytics represents the fastest-expanding technology segment as shippers deploy predictive models for demand sensing and exception management. Warehouse management retains mature margin pools in cold chain and pharmaceutical verticals where regulatory traceability commands premium pricing.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape European vendor certification and cross-border data routing architectures. The US Federal Motor Carrier Safety Administration and Food and Drug Administration enforce electronic logging, temperature monitoring, and chain-of-custody documentation that drive cloud platform substitution for paper-based compliance systems. Stakeholders must monitor how divergent AI governance frameworks between Brussels and Washington fragment platform development roadmaps and inflate compliance engineering costs.
Market Dynamics
Mid-market freight brokers are collapsing the traditional buyer hierarchy that large enterprises once dominated in cloud logistics procurement, compressing deployment timelines and forcing vendors to rearchitect pricing and onboarding workflows for smaller, nimbler customers.
Growth Catalysts
- E-commerce fulfillment networks:Direct-to-consumer order volumes are forcing retailers to deploy real-time inventory orchestration platforms that synchronize warehouse, carrier, and last-mile data layers.
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated routing and demand forecasting are accelerating certified platform upgrades across European logistics operations.
- Fuel cost volatility:Transportation management systems with dynamic carrier selection and route optimization are capturing procurement budgets as shippers seek immediate freight spend reduction.
Market Restraints
- Data residency architectures:Cross-border data routing restrictions under GDPR and emerging national data localization laws are inflating cloud infrastructure costs for multi-country deployments.
- Legacy ERP integration complexity:Proprietary data formats in incumbent warehouse and transportation systems extend implementation timelines and require costly middleware development.
- Carrier API standardization gaps:Inconsistent electronic data interchange protocols across regional freight networks limit real-time visibility coverage and require redundant connectivity investments.
Strategic Opportunities
- Cold chain pharmaceutical verticals:Temperature monitoring and chain-of-custody documentation requirements under FDA and EMA rules are creating premium subscription tiers for compliance-automated platforms.
- Predictive demand sensing convergence:Machine learning models fused with IoT sensor streams are opening new revenue pools in inventory positioning and automated replenishment services.
- Small-freight-broker channel innovation:Self-service onboarding and usage-based pricing models are penetrating the long tail of regional freight intermediaries previously excluded from enterprise platform economics.
Industry Challenges
- API integration engineering talent scarcity:Shortages of developers skilled in legacy system connectivity and real-time data pipeline architecture are throttling implementation capacity at scaling vendors.
- Algorithmic audit certification timelines:EU AI Act conformity assessments and GDPR algorithmic impact reviews are extending sales cycles and requiring dedicated compliance product teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Logistics Software Market |
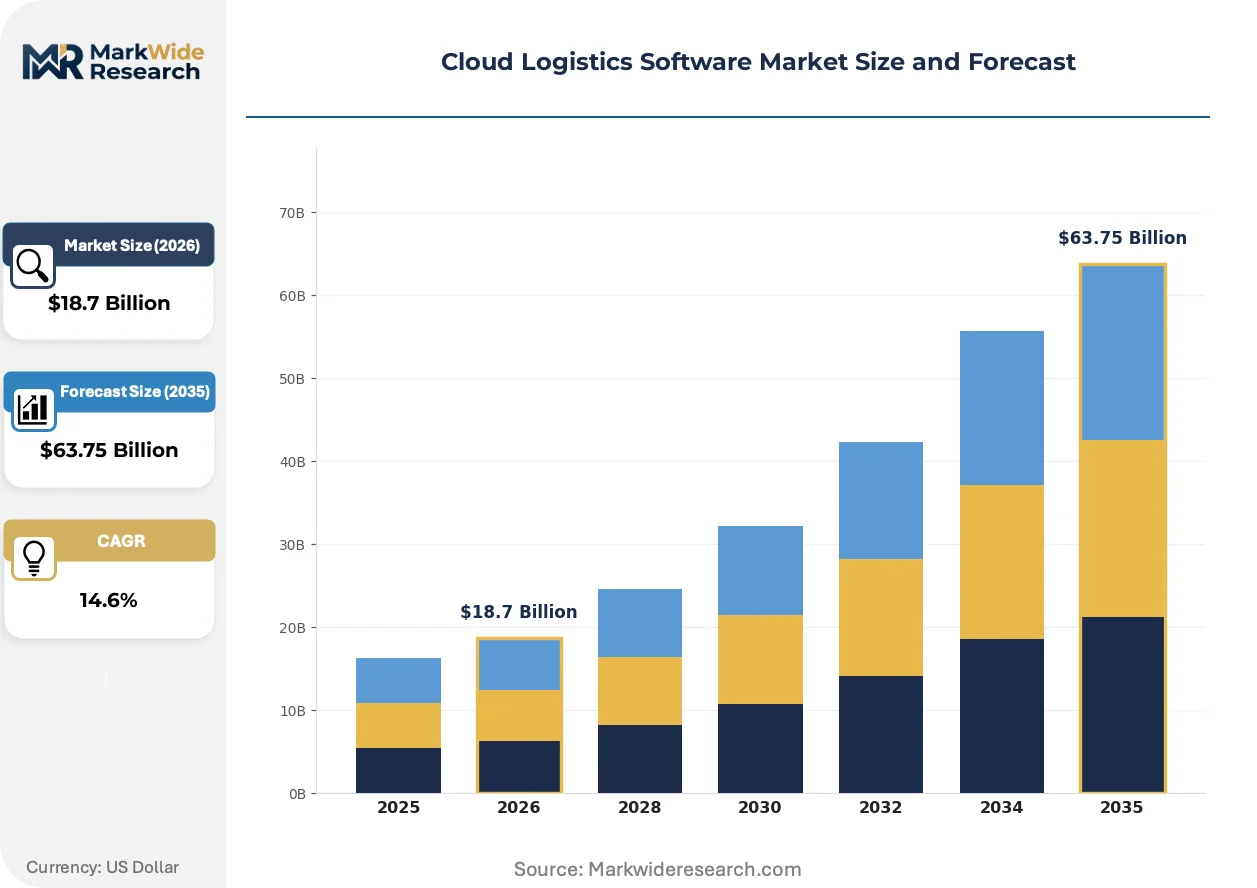
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Product Type: Warehouse Management, Transportation Management, Yard Management, Order Management End User: Retailers, Manufacturers, Third-Party Logistics, E-commerce Technology: AI-Driven Analytics, IoT Integration, Automation Solutions, Blockchain |
| Companies Covered | Oracle Corporation, SAP SE, IBM Corporation, Microsoft Corporation, Manhattan Associates, The Descartes Systems Group Inc., Trimble Inc., Magaya Corporation, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Logistics Software Market Trends and Innovations
Real-time telemetry from GPS, RFID, and warehouse sensors is compressing decision latency across freight movement and inventory positioning, forcing platform architectures toward edge-computing deployments and sub-second API response standards.
AI-driven predictive analytics is fragmenting the traditional transportation management system market by enabling standalone demand forecasting and exception management modules that shippers deploy without full platform replacement. Retailers and automotive manufacturers are adopting these point solutions fastest, compressing the addressable market for integrated suites while expanding total spend on specialized analytics tools. The structural consequence is a bifurcation between best-of-breed AI vendors and full-stack platform providers competing for overlapping procurement budgets.
The EU AI Act and GDPR are imposing algorithmic transparency and data residency requirements that reshape European vendor certification standards and cross-border data routing architectures. Logistics platforms serving EU member states must now document automated decision logic and maintain localized data processing nodes, inflating compliance engineering costs and favoring vendors with existing European cloud infrastructure. German automotive and industrial logistics clusters are driving the strictest interpretation of these mandates, creating a certification benchmark that other EU markets are adopting.
Freight procurement is compressing from annual carrier contracts to continuous dynamic booking as fuel volatility and capacity constraints reward agility over price certainty. Large shippers are unbundling transportation management from execution, selecting specialized platforms for spot-market bidding while retaining legacy systems for contracted lanes. This behavioral shift is most visible in North American over-the-road freight, where mid-market brokers now represent the fastest-growing customer segment for API-first booking platforms.
Cloud Logistics Software Market Segmentation
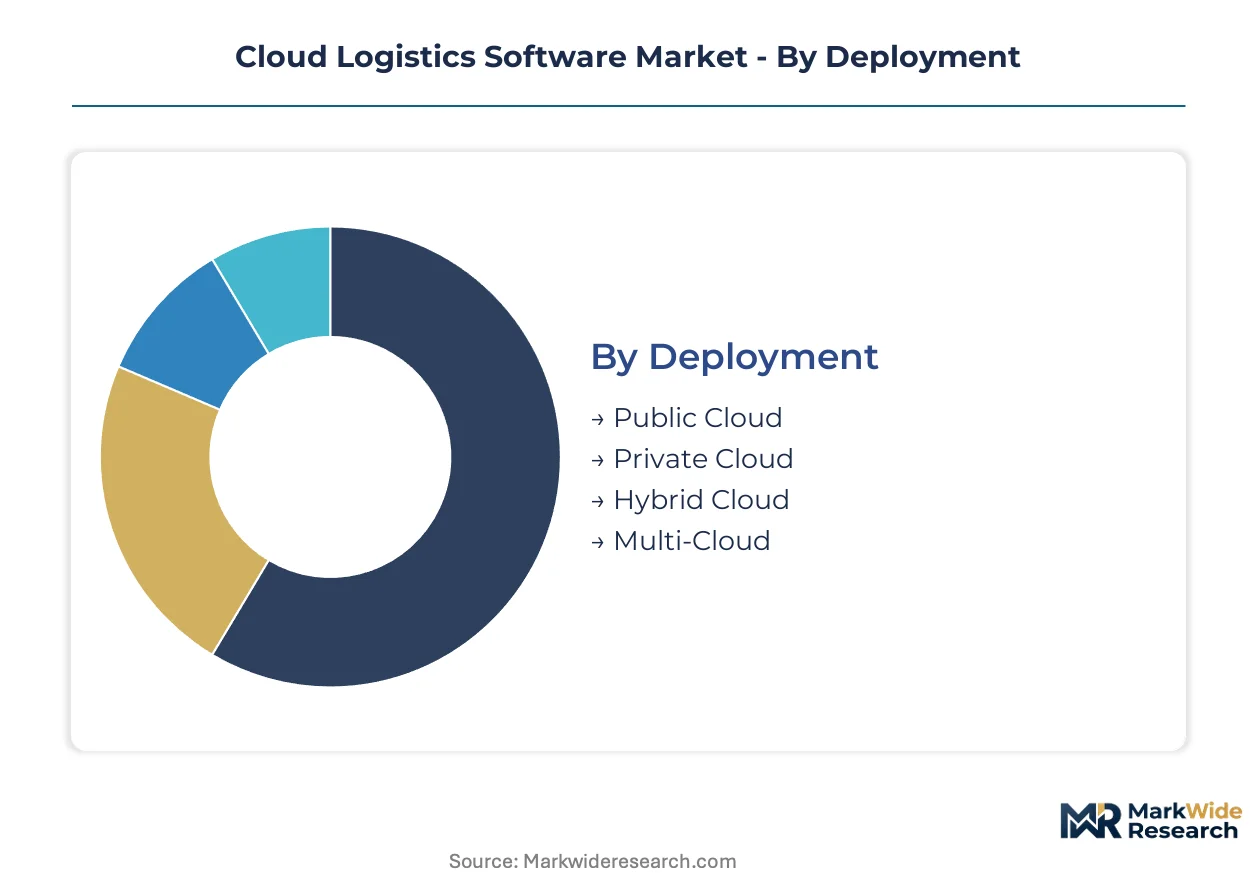
Cloud logistics software procurement splits across four distinct dimensions that reshape vendor go-to-market strategies. Deployment architecture determines infrastructure cost structures and compliance postures. Product type alignment governs which workflow layers shippers prioritize for cloud migration.
Deployment:
Margin pools concentrate in configurations that balance scalability against data sovereignty mandates from EU and Asian regulators.
- Public Cloud:Shared infrastructure delivers elastic compute for seasonal freight volume spikes without capital commitment. Retailers and e-commerce platforms in the United States and India favor this model for rapid warehouse management system deployment during peak cycles.
- Private Cloud:Dedicated tenant environments isolate sensitive routing algorithms and carrier rate data. German automotive logistics clusters mandate private deployments to satisfy GDPR algorithmic audit requirements and KBA data residency interpretations.
- Hybrid Cloud:Blends core transaction processing on-premises with burst capacity in public nodes. Third-party logistics providers leverage this architecture to maintain legacy ERP connectivity while modernizing customer-facing visibility layers.
- Multi-Cloud:Distributes workloads across AWS, Azure, and Google Cloud to mitigate vendor lock-in and optimize regional latency. Cold chain pharmaceutical operators deploy multi-cloud strategies to satisfy divergent FDA and EMA data localization rules without single-provider dependency.
The dominant share belongs to Public Cloud, while Multi-Cloud is climbing the fastest as cross-border operators fragment infrastructure across jurisdictions.
Product Type:
Application maturity varies sharply, with established modules commanding recurring revenue and emerging categories capturing expansion budgets.
- Warehouse Management:Orchestrates inventory positioning, labor allocation, and equipment routing across distribution nodes. Cold chain and pharmaceutical verticals in Switzerland and France pay premium subscription tiers for Swissmedic and ANSM compliance automation.
- Transportation Management:Dynamic carrier selection and route optimization respond to fuel cost volatility and capacity constraints. North American over-the-road freight brokers represent the fastest-expanding customer cohort for API-first booking platforms.
- Yard Management:Coordinates trailer positioning, gate scheduling, and dock door allocation to compress dwell times. Port-centric logistics clusters in the Netherlands and Belgium deploy yard systems to manage container flow volatility.
- Order Management:Synchronizes omnichannel inventory visibility and promise management across warehouse and drop-ship networks. Direct-to-consumer retailers in the United Kingdom integrate order management with last-mile execution platforms.
Warehouse Management retains the largest installed base, though Transportation Management is gaining share fastest among mid-market freight intermediaries.
End User:
Buyer sophistication and procurement cycle length diverge significantly across organizational types and vertical integration levels.
- Retailers:Omnichannel fulfillment networks require real-time inventory orchestration across warehouse, carrier, and last-mile data layers. Grocery and fashion retailers in France and Italy prioritize order management modules with predictive demand sensing.
- Manufacturers:ERP-integrated supply chain visibility dominates procurement criteria for production-linked logistics. German and Japanese automotive manufacturers sustain deep SAP and Oracle deployments for inbound material flow coordination.
- Third-Party Logistics:Asset-light intermediaries demand white-label platform capabilities and rapid customer onboarding. Regional freight brokers in the United States and Brazil adopt self-service pricing models previously exclusive to enterprise buyers.
- E-commerce:Pure-play digital merchants prioritize speed-to-deploy over customization depth. Marketplace sellers in India and Southeast Asia leverage public cloud warehouse management for seasonal capacity scaling.
Manufacturers contribute the highest average contract value, while Third-Party Logistics is expanding most quickly as the mid-market broker channel digitizes.
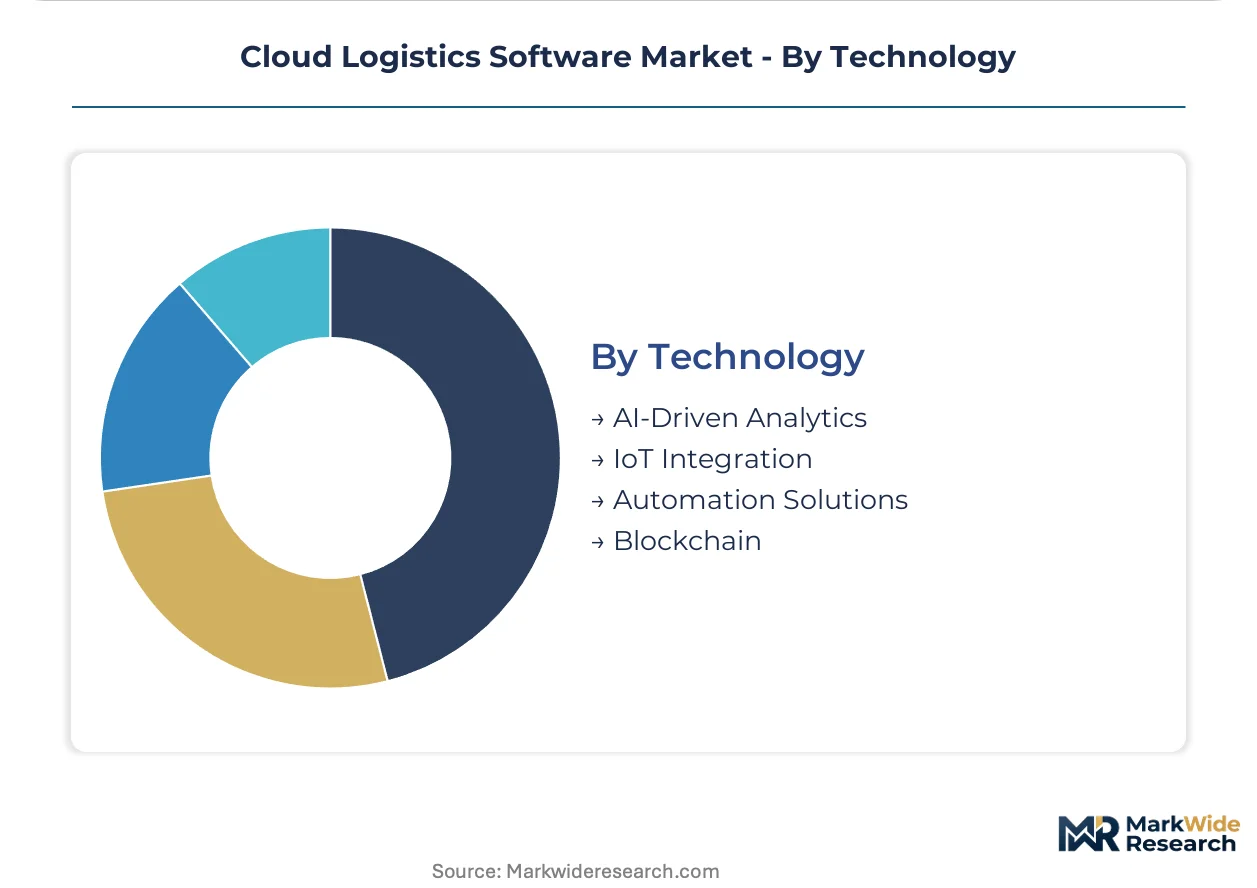
Technology:
Investment intensity clusters around capabilities that compress decision latency or automate compliance documentation.
- AI-Driven Analytics:Machine learning models for demand sensing and exception management deploy as standalone modules or integrated platform features. Retailers and automotive manufacturers in Germany and the United States adopt these tools fastest, fragmenting procurement from full-suite replacements.
- IoT Integration:Real-time telemetry from GPS, RFID, and warehouse sensors feeds optimization engines with sub-second latency requirements. Cold chain operators in the United States and European Union mandate IoT-enabled temperature monitoring for FDA and EMA chain-of-custody compliance.
- Automation Solutions:Robotic process automation and autonomous mobile robot orchestration layers extend warehouse management functionality. Fulfillment centers in the Netherlands and Japan deploy automation modules to compress labor cost inflation.
- Blockchain:Distributed ledger documentation for multi-party shipment verification and smart contract settlement. Pharmaceutical and high-value cargo shippers in Switzerland and Singapore pilot blockchain for tamper-evident custody records.
AI-Driven Analytics commands the steepest expansion trajectory, while IoT Integration anchors the largest current revenue base among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision automotive components to assembly plants across Mexico and the United States, driving cross-border logistics orchestration demand that cloud platforms must synchronize across three regulatory jurisdictions.
United States
Mid-market freight brokers in Chicago and Dallas-Fort Worth are collapsing traditional enterprise procurement hierarchies, compressing deployment timelines for API-first booking platforms. The Federal Motor Carrier Safety Administration mandates electronic logging device integration for interstate carriers. Pharmaceutical distributors in the Philadelphia-Camden corridor deploy temperature-monitoring cloud stacks to satisfy FDA chain-of-custody documentation.
Germany
Automotive and industrial logistics clusters in Stuttgart and Munich anchor European demand for private cloud deployments with algorithmic audit capabilities. The KBA interprets GDPR data residency requirements strictly, forcing localized processing nodes for automated routing decisions. SAP-integrated supply chain visibility dominates procurement criteria for inbound material flow coordination at Volkswagen and BMW supplier parks.
India
E-commerce marketplace sellers in Bangalore and Mumbai leverage public cloud warehouse management for seasonal capacity scaling during festival demand surges. The Digital Personal Data Protection Act imposes emerging data localization obligations on cross-border telemetry flows. Third-party logistics providers in the Delhi-Mumbai Industrial Corridor adopt self-service pricing models previously exclusive to enterprise buyers.
Netherlands
Port-centric logistics clusters in Rotterdam and Amsterdam deploy yard management systems to manage container flow volatility from Asia-Europe trade lanes. The EU AI Act mandates algorithmic transparency for automated gate scheduling and dock door allocation. Cold chain operators serving Schiphol Pharma Hub maintain multi-cloud architectures to satisfy divergent EMA and FDA data localization rules.
Japan
Automotive manufacturers in Toyota City and Yokohama sustain deep ERP-integrated supply chain visibility for just-in-sequence production logistics. METI promotes smart logistics infrastructure standards that accelerate IoT sensor deployment across warehouse networks. Fulfillment centers in the Kanto region deploy automation modules to compress labor cost inflation in high-wage environments.
Cloud Logistics Software Market Competitive Landscape
Listed leaders compete with private specialists across deployment architecture and vertical integration depth, creating a tiered structure where scale advantages clash with sector-specific customization capabilities. The vendor base clusters around three strategic archetypes: database infrastructure incumbents anchoring enterprise deployments, ERP-native platforms dominating manufacturing workflows, and warehouse execution specialists competing in retail distribution. M&A activity concentrates on API connectivity assets and cold chain compliance modules, while geographic expansion targets mid-market broker channels in North America and industrial logistics clusters in Germany.
Within the enterprise infrastructure tier, Oracle Corporation and SAP SE exemplify divergent geographic strengths, with the former anchoring North American supply chain deployments and the latter sustaining European manufacturing dominance through deep ERP integration. Manhattan Associates occupies a position as a warehouse execution specialist competing directly against broader platform providers in retail distribution verticals. These three entities represent the competitive tension between full-stack suites and best-of-breed point solutions reshaping procurement patterns.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Microsoft Corporation |
| Manhattan Associates |
| The Descartes Systems Group Inc. |
| Trimble Inc. |
| Magaya Corporation |
| Infor |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with hyperscale cloud providers lock in compute access and cost visibility for logistics platforms operating under EU AI Act compliance timelines. These multi-year commitments anchor infrastructure spending while exposing vendors to stranded cost risk if data localization requirements shift processing geography.
Pricing Analysis
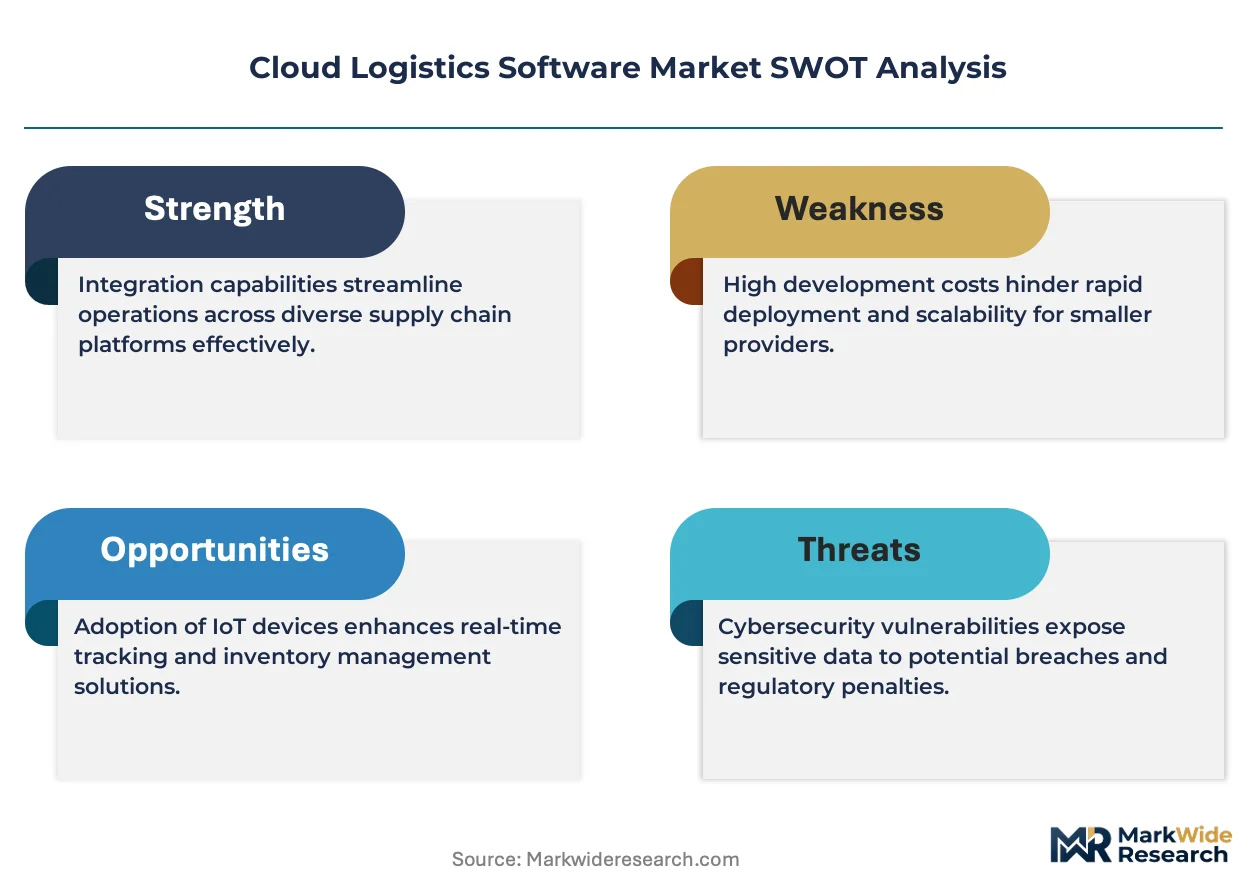
Next-generation AI-orchestrated platforms command 40-60% subscription premiums over legacy TMS deployments lacking predictive analytics modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by API call volume, compliance certification tier, and edge-computing latency guarantees. Cost compression in the economy tier intensifies because mid-market freight brokers negotiate usage-based models that erode per-seat margins. Third-party logistics providers exhibit highest price sensitivity due to thin intermediary margins, while cold chain pharmaceutical operators accept premium tiers for FDA and EMA audit automation.
Supply Chain Analysis
API integration engineering talent scarcity in India, Poland, and Vietnam constrains platform implementation velocity for vendors scaling mid-market broker channels. Cloud infrastructure draws from AWS, Azure, and Google Cloud data centers concentrated in Frankfurt, Dublin, and Singapore. Single-source vulnerability in legacy ERP middleware extends implementation timelines and inflates professional services costs. Distribution runs through direct enterprise sales teams for manufacturers, self-service portals for e-commerce merchants, and channel partners for regional freight intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud logistics software functions as a service-attach opportunity where AI-driven predictive analytics subscriptions expand faster than core platform licensing. Compliance-automated modules for cold chain documentation and algorithmic audit trails capture recurring revenue premiums that hardware-centric deployments cannot match.
For Market Incumbents: Fortify data residency architectures across German, Dutch, and Indian processing nodes to preempt regulatory fragmentation under divergent GDPR and Digital Personal Data Protection Act interpretations. Deepen vertical integration into IoT sensor hardware and edge-computing infrastructure to capture margin pools that API-dependent competitors cannot access. Channel control through certified implementation partners defends against API-first entrants collapsing deployment timelines. For New Entrants and Emerging Players: Lead with self-service onboarding workflows and usage-based pricing models targeting the long tail of North American mid-market freight brokers excluded from enterprise platform economics. White-label yard management modules for port-centric logistics clusters in the Netherlands and Belgium exploit underpenetrated container flow optimization demand. Geographic expansion into India's e-commerce fulfillment corridor leverages public cloud elasticity for seasonal capacity scaling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with AI-driven analytics modules embedded in pharmaceutical and automotive verticals. Long-term viability hinges on compliance engineering capabilities that extend sales cycles but deepen customer switching costs. Acquisition targets with EU AI Act conformity assessment pre-certification and multi-cloud deployment architectures signal defensible positioning. Watch API standardization momentum at the Federal Motor Carrier Safety Administration as inflection indicator for real-time visibility market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-native connectivity with SAP and Oracle anchors manufacturing procurement decisions in Germany. |
| Acquisition of Specialist Firm | Cold chain compliance modules from FDA-certified vendors command premium subscription tiers. |
| Geographic Expansion | Mid-market broker channels in Chicago and Dallas-Fort Worth compress traditional enterprise hierarchies. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure satisfy divergent EMA and FDA data localization rules. |
| Product Launch | Standalone demand forecasting modules fragment procurement from full transportation management replacements. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings for compliance-driven procurement patterns. Primary fieldwork with logistics technology officers, freight broker operations directors, pharmaceutical supply chain managers, and cloud platform engineers informed deployment architecture preferences. Secondary sources include SEC 10-K infrastructure disclosures, EU AI Act implementation guidance, FDA supply chain security filings, and hyperscaler regional capex announcements. Bottom-up sizing of API transaction volumes and top-down triangulation against enterprise software spending benchmarks constrain estimate variance.
Sensitivity analysis across deployment model adoption curves, compliance timeline scenarios, and carrier API penetration rates stress-tests projection robustness. Segmentation dimensions span public-private-hybrid-multi-cloud configurations, product type modules, end-user verticals, and technology integration layers. CAGRs derive from logistic curve fitting of platform subscription growth and professional services attach rates. Forecast inputs incorporate EU AI Act conformity assessment timelines and FMCSA electronic logging mandate enforcement phases.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth and cross-border data flow stability would require recalibration. Forecasts reflect assumptions regarding carrier API standardization velocity and pharmaceutical regulatory harmonization between FDA and EMA jurisdictions. Practitioners should keep alternative scenarios live as algorithmic audit certification timelines and data localization law divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
UX Services Market
Digital Solutions
Dating Services Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Chile ICT Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Service Mesh Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Global Ad Tech Software Market