
 China Digital Twin Market | 2026-2036
China Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Twin Market Insights
Project finance for industrial IoT infrastructure is rewriting competitive dynamics in China's digital twin sector. Siemens AG leverages its automation heritage to anchor large-scale manufacturing deployments across eastern provinces. Huawei Technologies sustains domestic cloud-edge integration capabilities that compete with foreign platform providers. PTC Inc. specializes in industrial AR overlays that extend digital twin visualization into field operations.
A digital twin constitutes a virtual representation of a physical asset, system, or process, continuously updated through real-time sensor telemetry and simulation algorithms operating at millisecond synchronization intervals. Its primary purpose is to enable predictive intervention, optimize operational parameters, and reduce unplanned downtime across capital-intensive industries. Software platforms occupy the dominant margin pool given recurring licensing and update revenue, while IoT-enabled deployments represent the fastest-growing technology layer as edge computing costs decline. Smart cities applications concentrate demand in municipal infrastructure, though manufacturing end users currently generate the largest absolute spend on process optimization and asset management modules.
MIIT's GB standards for industrial internet platforms, NMPA's guidance on computational modeling for medical device approval, and SAMR's data security requirements for critical information infrastructure collectively shape product architecture and market access conditions. The country's dual carbon goals from MEE further compel energy and utility operators to adopt process optimization twins for emissions monitoring. Stakeholders must evaluate whether domestic cloud providers or international software vendors offer more sustainable compliance pathways as data localization rules tighten.
Market Dynamics
MIIT's GB standards for industrial internet platforms are compressing vendor compliance timelines while accelerating domestic platform consolidation. State-backed smart city mandates in Shanghai and Shenzhen are pulling digital twin deployments into municipal infrastructure at scale previously reserved for heavy manufacturing.
Growth Catalysts
- Dual carbon monitoring mandates:MEE's emissions tracking requirements compel energy operators to deploy process optimization twins for real-time carbon accounting across power generation and industrial facilities.
- Smart city infrastructure waves:Municipal governments in the Yangtze River Delta are bundling digital twin modules into integrated command centers for traffic, utilities, and emergency response systems.
- Edge computing cost curves:Declining sensor and edge hardware prices are enabling millisecond-synchronized telemetry deployments in mid-sized manufacturing facilities previously priced out of twin adoption.
Market Restraints
- Data localization compliance costs:SAMR's critical information infrastructure rules require domestic cloud storage, fragmenting architecture for multinational operators with cross-border data flows.
- High-fidelity modeling talent scarcity:The shortage of simulation engineers with combined physics and software expertise constrains deployment velocity in automotive and aerospace verticals.
- Legacy system integration friction:Brownfield manufacturing sites with decades-old SCADA architectures face prohibitive retrofit costs to achieve real-time twin synchronization.
Strategic Opportunities
- Medical device simulation pathways:NMPA's computational modeling guidance for device approval creates a regulated entry point for patient-specific organ twins in surgical planning applications.
- Pearl River Delta manufacturing clusters:Electronics and battery producers in Guangdong province are piloting supply chain twins linking upstream material flows to downstream assembly lines.
- AI-augmented predictive maintenance:Convergence of machine learning inference at the edge with physics-based simulation is opening subscription revenue models for equipment uptime guarantees.
Industry Challenges
- Cross-functional deployment teams:Successful twin implementations require rare coordination between OT engineers, data scientists, and domain specialists, stretching organizational capabilities.
- GB standard certification timelines:MIIT's evolving platform interoperability requirements delay product launches as vendors iterate through compliance testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Twin Market |
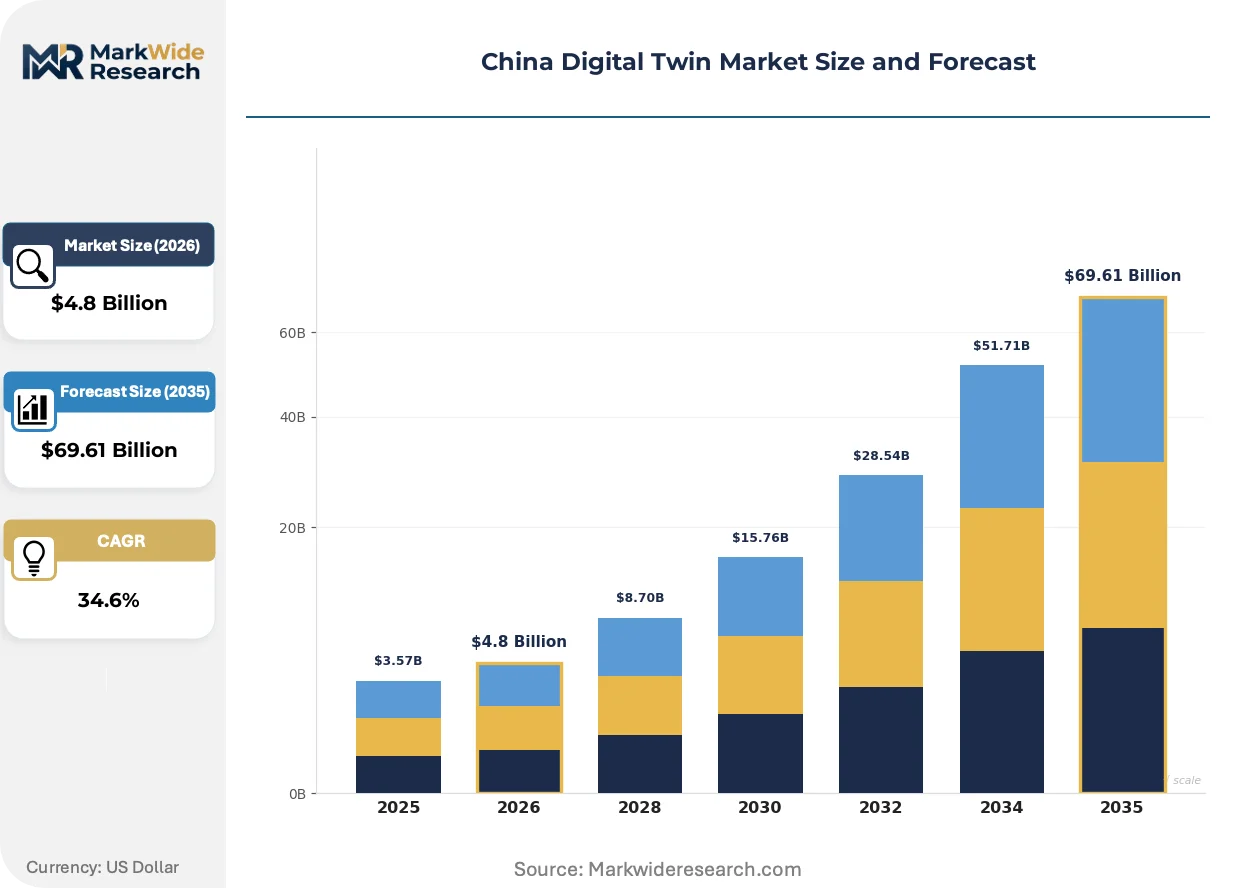
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $69.61 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Middleware, Services End User: Manufacturing, Healthcare, Automotive, Smart Cities Technology: Cloud-based, AI-driven, IoT-enabled, Blockchain Application: Predictive Maintenance, Process Optimization, Asset Management, Urban Planning |
| Companies Covered | Siemens AG, Dassault Systèmes, Microsoft Corporation, IBM Corporation, Autodesk Inc., PTC Inc., Huawei Technologies, GE Vernova, ANSYS Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Twin Market Trends and Innovations
Real-time rendering engines originally built for gaming are migrating into industrial visualization stacks, compressing the fidelity gap between design-phase simulation and operational twins. This migration is redistributing competitive advantage toward software vendors with consumer-grade graphics expertise.
Cloud-native twin architectures are collapsing the traditional separation between design, simulation, and operational data layers. Automotive OEMs in the Yangtze River Delta are deploying unified platforms where vehicle design models evolve continuously from prototype through fleet operation. This compression eliminates manual data translation steps that previously introduced weeks of latency between engineering changes and production line updates.
MIIT's GB/T 23011-2022 standard for industrial digital twin reference architecture is mandating interoperability protocols across state-owned enterprise procurement. Equipment suppliers must now expose standardized API surfaces to qualify for SOE contracts, forcing proprietary platform vendors to open previously closed data models. Heavy machinery producers in Shandong province are responding by pre-certifying twin modules against the standard to accelerate sales cycles.
Asset-as-a-service contracting is displacing perpetual license purchases in municipal infrastructure deployments. Smart city operators in Shenzhen are negotiating performance-based agreements where twin platform vendors bear uptime risk and earn revenue against operational efficiency gains. This shift concentrates vendor selection criteria on proven integration track records rather than feature checklists, favoring incumbent automation suppliers with existing municipal relationships.
China Digital Twin Market Segmentation
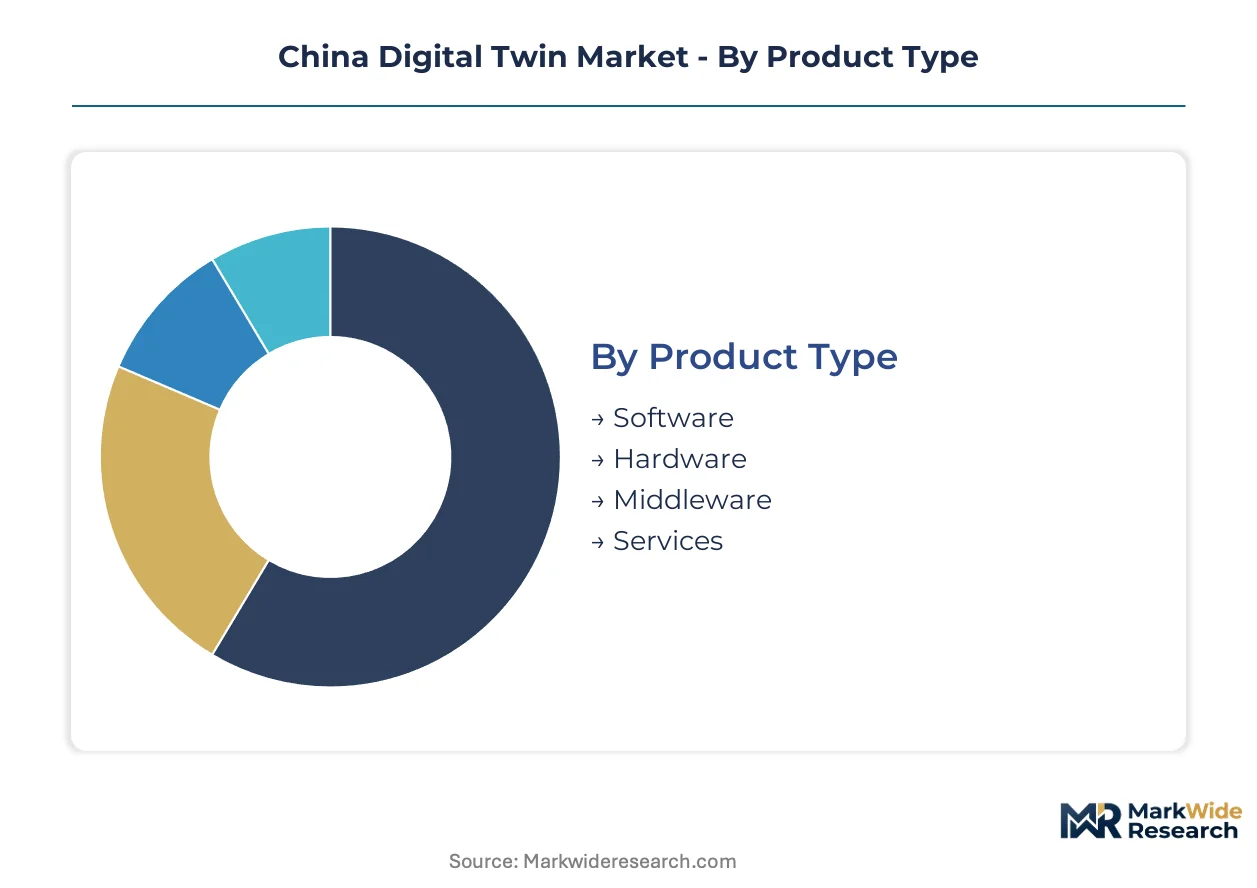
Segmentation in China's digital twin market reveals how technology stacks, deployment models, and application domains fragment procurement decisions. Vendors must align capabilities against distinct buyer priorities across software platforms, industry verticals, and infrastructure layers.
Product Type:
Use-case spectrum spans lightweight visualization tools for municipal dashboards to physics-intensive simulation engines for aerospace suppliers.
- Software:Licensing platforms for model authoring, real-time synchronization, and predictive analytics command recurring revenue streams. Shanghai's smart city operators prioritize subscription-based deployment tools that reduce upfront capital burdens for municipal budgets.
- Hardware:Edge servers, sensor arrays, and GPU clusters enable millisecond-latency telemetry pipelines. Pearl River Delta electronics manufacturers drive demand for compact edge devices that retrofit existing production lines without SCADA overhauls.
- Middleware:Integration layers bridge proprietary OT protocols with cloud-native data fabrics.
- Services:System integration and managed operations support brownfield deployments.
The dominant share belongs to Software, while Hardware is closing the gap fastest as edge computing costs decline.
End User:
Customer type determines procurement authority, with state-backed infrastructure projects following distinct tender processes from private manufacturing contracts.
- Manufacturing:Process optimization twins for asset-intensive production lines dominate absolute spend. Yangtze River Delta automotive suppliers deploy unified platforms linking design models through fleet operation, eliminating manual translation steps.
- Smart Cities:Municipal command centers bundle traffic, utilities, and emergency response modules. Shenzhen's integrated urban operations platforms set procurement templates for delta-region cities.
- Healthcare:Patient-specific organ twins for surgical planning gain traction under NMPA computational modeling guidance.
- Automotive:Battery producers pilot supply chain twins linking upstream material flows to downstream assembly.
Manufacturing retains the largest deployment base, though Smart Cities demonstrates the steepest expansion trajectory as municipal mandates accelerate.
Technology:
Margin structure varies sharply across deployment architectures, with cloud-native stacks capturing recurring revenue and edge-heavy configurations requiring capital-intensive hardware sales.
- IoT-enabled:Sensor-to-twin telemetry pipelines represent the fastest-climbing technology layer as hardware costs fall. Mid-sized Shandong machinery producers now deploy synchronized monitoring previously restricted to large SOEs.
- AI-driven:Machine learning inference at the edge converges with physics simulation for predictive maintenance subscriptions. Equipment uptime guarantees reshape vendor revenue models toward performance-based contracting.
- Cloud-based:Domestic providers compete with international platforms under tightening SAMR data localization rules.
- Blockchain:Immutable audit trails for supply chain twins attract compliance-focused procurement.
IoT-enabled deployments command the deepest buyer commitment, while AI-driven layers are gaining share fastest through subscription revenue innovation.
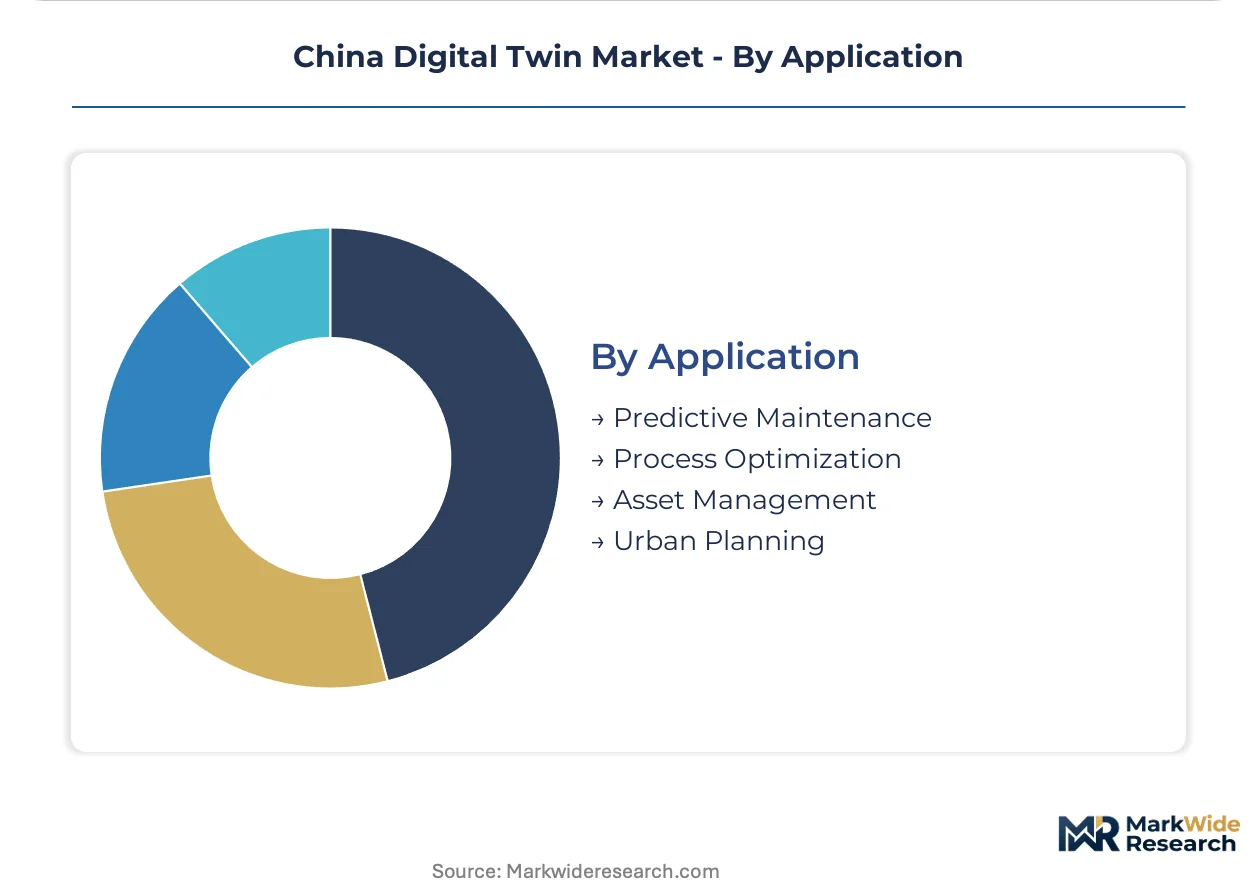
Application:
Functional purpose dictates integration complexity, with operational twins requiring live SCADA connections and planning tools operating on historical datasets.
- Predictive Maintenance:AI-augmented failure forecasting reduces unplanned downtime in capital-intensive facilities. Power generation operators under MEE dual carbon mandates deploy process twins for emissions-linked equipment optimization.
- Process Optimization:Real-time parameter tuning for energy efficiency and yield improvement dominates manufacturing ROI calculations. Carbon accounting modules now feature in procurement specifications for state-owned energy assets.
- Asset Management:Lifecycle tracking from commissioning through decommissioning supports capital planning.
- Urban Planning:Static and dynamic city models inform infrastructure investment decisions.
Predictive Maintenance holds the dominant deployment share, while Process Optimization is climbing fastest as carbon monitoring mandates expand compliance-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's digital infrastructure mandates and dual carbon targets from MEE are redirecting investment flows toward provincial clusters with pre-certified industrial internet capabilities. Provincial governments compete for central funding by accelerating smart city procurement timelines.
Yangtze River Delta
Automotive OEMs and battery producers in Shanghai and Jiangsu province deploy unified design-to-operation platforms. MIIT's GB/T 23011-2022 standard mandates interoperability protocols for state-owned enterprise procurement. Nanjing's integrated command centers bundle traffic, utilities, and emergency response modules for municipal operators.
Pearl River Delta
Electronics manufacturers in Shenzhen and Guangzhou pilot supply chain twins linking upstream material flows to downstream assembly. SAMR's data localization rules fragment architecture for cross-border operators. Dongguan's machinery producers pre-certify twin modules against national standards to accelerate sales cycles.
Beijing-Tianjin-Hebei
State-owned energy operators deploy process optimization twins for emissions monitoring under MEE mandates. NMPA's computational modeling guidance creates regulated entry points for medical device simulation. Tianjin's port infrastructure operators negotiate performance-based twin contracts with automation suppliers.
Shandong Peninsula
Heavy machinery producers adopt synchronized monitoring previously restricted to large SOEs as edge computing costs decline. SAMR's critical information infrastructure rules require domestic cloud storage for mid-sized facilities. Qingdao's manufacturing clusters retrofit existing production lines with compact edge devices.
Sichuan-Chongqing
Power generation operators under dual carbon mandates deploy process twins for real-time carbon accounting. MIIT's evolving platform interoperability requirements delay product launches through compliance testing cycles. Chengdu's smart city operators prioritize subscription-based deployment tools to reduce upfront capital burdens.
China Digital Twin Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement authority in municipal and industrial deployments. The vendor base organizes into three tiers: automation incumbents with existing municipal relationships, domestic cloud providers with edge integration capabilities, and international software vendors with physics simulation heritage. Strategic moves concentrate on GB standard pre-certification for SOE qualification and asset-as-a-service contracting to displace perpetual licenses.
Within the automation incumbent tier, Siemens AG anchors large-scale manufacturing deployments across eastern provinces. Huawei Technologies occupies a position among domestic cloud-edge integrators competing under tightening data localization rules. PTC Inc. exemplifies the visualization specialist archetype extending digital twin interfaces into field operations through industrial AR overlays.
| Leading Market Players |
|---|
| Siemens AG |
| Dassault Systèmes |
| Microsoft Corporation |
| IBM Corporation |
| Autodesk Inc. |
| PTC Inc. |
| Huawei Technologies |
| GE Vernova |
| ANSYS Inc. |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo freight corridor's container cost dynamics compress margins for edge hardware suppliers while amplifying price spreads between certified and uncertified software platforms. Domestic cloud providers exploit this logistics concentration to bundle storage with twin deployment tools, forcing international vendors toward premium positioning or local partnership structures.
Pricing Analysis
Certification level under MIIT's GB/T 23011-2022 standard creates the primary spread between qualified and unqualified platform vendors. Three-tier pricing structure across SOE-certified, enterprise-standard, and mid-market economy levels dominates procurement, with after-sales service bundling adding further differentiation. Pricing pressure stems from Huawei's aggressive cloud-edge bundling in municipal tenders. State-owned energy operators show least price sensitivity given dual carbon compliance mandates, while mid-sized Shandong machinery producers drive hardest bargain on hardware costs.
Supply Chain Analysis
Foxconn and BYD Electronics contract manufacturing concentration in Shenzhen and Dongguan governs edge device availability for twin deployments. Supply draws from China, Taiwan, and South Korea for GPU accelerators, industrial sensors, and proprietary simulation chipsets. Single-source vulnerability runs through NVIDIA's datacenter GPU allocation to domestic cloud providers. Distribution runs through state-owned enterprise procurement portals and municipal tender platforms rather than open channel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's digital twin market sits in early-cycle expansion as MIIT's GB standard mandates force SOE procurement waves that outpace private manufacturing adoption curves.
For Market Incumbents: Harden platform interoperability against evolving MIIT certification requirements by pre-integrating with domestic cloud stacks. Acquire edge hardware specialists in the Pearl River Delta to neutralize Huawei's cloud-edge bundling threat. Prioritize SOE relationship depth over feature velocity given asset-as-a-service contracting displacement of perpetual licenses.
For New Entrants and Emerging Players: Pursue medical device simulation under NMPA's computational modeling guidance as the most penetrable regulated entry point. Target patient-specific organ twin applications where physics simulation heritage creates defensible differentiation. Lead with surgical planning workflow integration rather than platform breadth to bypass incumbent automation relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial software divisions of Western automation conglomerates seeking China market exits under data localization pressure. Long-term viability hinges on domestic cloud partnership structures rather than standalone platform plays. Watch SAMR enforcement intensity against cross-border data flows as the critical inflection signal for international vendor repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Pre-Certification | MIIT's GB/T 23011-2022 qualification opens SOE procurement channels previously closed to unverified platforms. |
| Cloud-Edge Integration Partnership | Domestic cloud alliances neutralize SAMR data localization risks for international software vendors. |
| Asset-as-a-Service Contracting | Performance-based municipal agreements shift vendor selection toward proven integration track records. |
| Medical Device Simulation Pathway | NMPA guidance creates regulated entry point for patient-specific organ twins in surgical planning. |
| Supply Chain Twin Pilot Programs | Pearl River Delta electronics manufacturers link upstream material flows to downstream assembly optimization. |
Research Methodology
A standing panel of smart city operations directors, industrial IoT platform engineers, SOE procurement managers, and medical device simulation specialists provided ongoing calibration throughout data collection. Primary interview findings combined with secondary validation against MIIT policy releases, SAMR regulatory filings, municipal tender databases, and industrial internet platform disclosure documents. Bottom-up deployment counts triangulated against top-down software licensing revenue estimates across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths without year-specific milestones. Segmentation dimensions modeled include product type, end user vertical, technology layer, and application function alongside regional cluster adoption patterns. CAGRs derived from deployment velocity curves weighted by procurement authority concentration in state-backed infrastructure versus private manufacturing. Edge computing cost decline trajectories and GB standard compliance timeline assumptions shaped forward estimates.
Sensitivities concentrate around MIIT certification timeline acceleration, SAMR data localization enforcement intensity, and dual carbon mandate expansion beyond power generation into industrial facilities. Forecasts reflect documented assumptions about state-backed procurement continuity and domestic cloud provider competitive positioning. Quarterly review of municipal tender award patterns and SOE pilot program conversions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Transport Management System Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Smart Signage Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Global Tracking As a Service Market