
 Cloud-Based Repository Services Market | 2026-2036
Cloud-Based Repository Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Repository Services Market Analysis
ISO 27001 certification is collapsing the vendor qualification window for enterprise procurement teams evaluating cloud repository providers. Amazon Web Services dominates infrastructure scale across North American and European zones. Microsoft Azure anchors government and healthcare verticals through FedRAMP and HITRUST accreditations. Google Cloud Platform differentiates on AI-integrated analytics tiers for unstructured data workloads.
Cloud-based repository services deliver centralized digital storage with automated versioning, redundancy protocols, and API-driven access controls for structured and unstructured enterprise data. Organizations deploy these systems to replace on-premises tape libraries and disk arrays with elastic capacity that scales to petabyte volumes without capital hardware cycles. Backup services command the largest revenue pool among service types as ransomware recovery mandates harden retention requirements. Hybrid cloud deployments are expanding fastest among deployment models as regulated industries seek air-gapped copies alongside operational accessibility. Large enterprises sustain the deepest per-account spend within end users, though SMEs represent the fastest onboarding velocity.
FedRAMP in the United States and GDPR in Europe enforce encryption standards and data residency rules that determine which providers qualify for public-sector and regulated-industry contracts. HIPAA business associate agreements and SEC recordkeeping rules extend compliance obligations to financial services and healthcare sub-verticals across American jurisdictions. Stakeholders must monitor evolving AI Act documentation requirements in Europe and emerging state-level privacy statutes in the United States before committing to multi-year repository architectures.

Market Dynamics
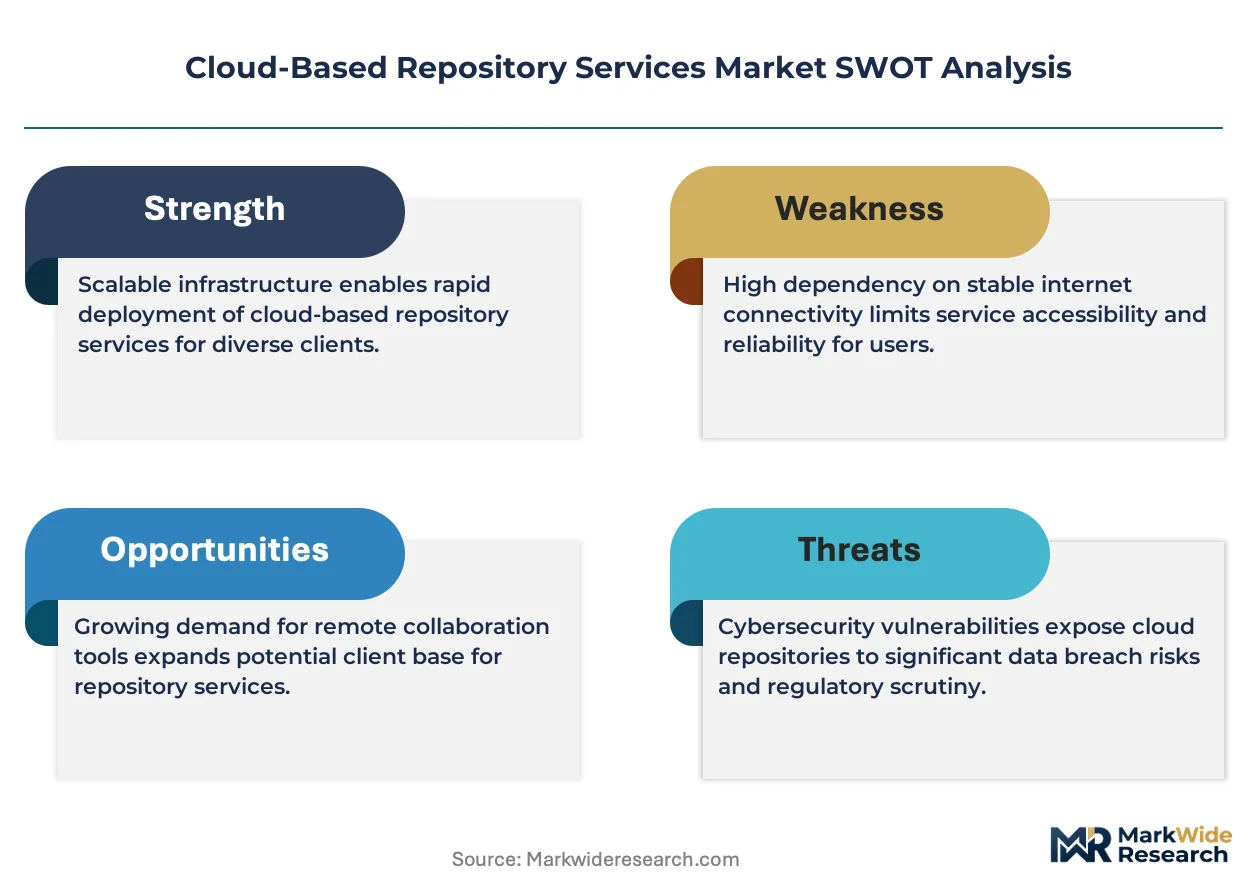
Enterprise migration from tape-based archives to elastic cloud storage is compressing procurement cycles and forcing vendors to bundle compliance certifications into standard service tiers rather than premium add-ons.
Growth Catalysts
- Ransomware Recovery Mandates:Financial regulators in the United States through SEC recordkeeping rules and the European Banking Authority are hardening data retention requirements, compelling institutions to maintain immutable cloud copies with multi-year retention.
- EU AI Act Documentation:Healthcare providers deploying diagnostic AI must maintain auditable training-data repositories, creating qualified demand for GDPR-compliant cloud storage with lineage tracking capabilities.
- India PLI Scheme:Domestic data center infrastructure incentives are attracting hyperscaler investment into Mumbai and Hyderabad zones, reducing latency for South Asian enterprise workloads.
Market Restraints
- Data Residency Friction:Russia's data localization requirements and China's Cybersecurity Law block cross-border repository architectures, fragmenting vendor operational scale.
- Encryption Key Escrow Risks:Government access mandates in Australia and the United Kingdom create jurisdictional conflicts with enterprise zero-knowledge encryption policies.
- Tape Archive Inertia:Cold storage economics of LTO-9 cartridges in air-gapped configurations retain cost advantages for petabyte-scale retention beyond seven years.
Strategic Opportunities
- Brazil ANVISA Medical Imaging:Underpenetrated healthcare digitization in São Paulo and Rio de Janeiro creates first-mover positioning for HIPAA-equivalent repository services.
- AI-Integrated Analytics Convergence:Merging vector database capabilities with object storage architectures enables real-time unstructured data querying for pharmaceutical research workloads.
- FinOps Channel Innovation:Cloud cost optimization platforms are emerging as new distribution intermediaries, bundling repository procurement with spend governance tools.
Industry Challenges
- FedRAMP Authorization Timelines:The 12-18 month certification window for US federal contracts delays revenue recognition and strains vendor compliance engineering capacity.
- Legacy Mainframe Integration:COBOL-based financial core systems require costly middleware development for API-driven cloud repository connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Repository Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup, Archiving, Disaster Recovery, File Sharing Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: Encryption, AI Integration, Data Analytics, API Management |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Corporation, Oracle Corporation, HCL Technologies, Fujitsu Ltd., Cisco Systems, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Repository Services Market Emerging Trajectories
Immutable object storage with cryptographic verification is displacing traditional backup architectures as the default enterprise data protection posture, while regulatory documentation requirements are embedding compliance automation into storage layer operations.
Object-lock immutability with WORM (Write Once Read Many) enforcement is displacing incremental backup schemes in financial services and healthcare. Tier-one banks in Germany and the United States are mandating 30-day minimum immutable retention for all production data. This architecture compresses recovery point objectives from 24 hours to near-zero while eliminating ransomware encryption pathways.
GDPR Article 30 record-of-processing obligations are forcing repository vendors to embed automated data mapping and retention scheduling into storage management planes. Healthcare providers in France and the Netherlands must demonstrate purpose-limitation compliance for patient imaging archives. Vendors are responding with metadata-driven policy engines that tag objects at ingestion and enforce geographic restriction rules.
Enterprise buying committees are consolidating storage procurement under FinOps governance models that tie repository selection to unit-cost-per-gigabyte targets. Manufacturing firms in Japan and automotive suppliers in Germany are unbundling storage from bundled managed service contracts. This shift favors consumption-based pricing with transparent egress fee structures over committed-use discount schemes.
Cloud-Based Repository Services Market Segmentation
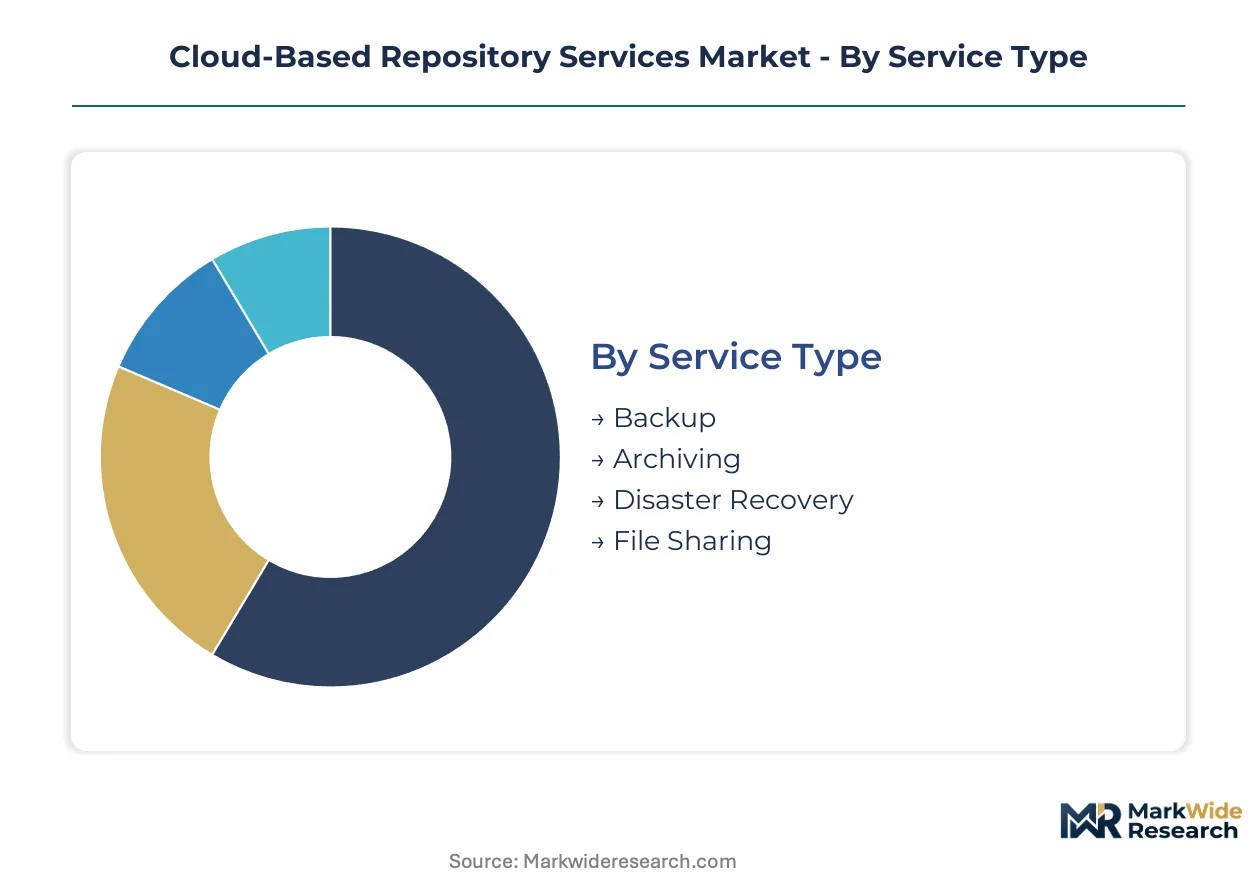
Cloud repository procurement committees segment requirements across four dimensions: service functionality, infrastructure control, organizational scale, and embedded technology. Each dimension carries distinct compliance obligations and cost structures that determine vendor qualification.
Service Type:
Regulatory frameworks distinguish backup from archiving through retention mandates and immutability requirements. SEC recordkeeping rules and EU AI Act documentation obligations create tiered compliance burdens across service categories.
- Backup:Automated snapshot replication with point-in-time recovery capabilities. Financial institutions in Germany and the United States deploy immutable backup tiers to satisfy ransomware recovery mandates from banking regulators.
- Archiving:Long-term retention with WORM enforcement and cryptographic verification. Healthcare providers in France and the Netherlands maintain patient imaging archives under GDPR Article 30 record-of-processing obligations.
- Disaster Recovery:Cross-zone replication with sub-hour recovery objectives.
- File Sharing:Collaborative access controls with version history and audit logging.
Established volume favors Backup; emerging adoption favors Archiving.
Deployment Model:
Cost tier differentiation separates operational workloads from compliance-mandated air-gapped copies. Hybrid architectures command premium pricing due to dual-environment orchestration complexity.
- Public Cloud:Shared infrastructure with elastic capacity scaling. SMEs in India leverage Mumbai and Hyderabad zones under PLI scheme incentives for cost-sensitive primary storage.
- Hybrid Cloud:Operational data in public tiers with immutable copies in private environments. German automotive suppliers and Japanese manufacturing firms deploy this model to satisfy GDPR and METI data sovereignty requirements.
- Private Cloud:Dedicated infrastructure with single-tenant isolation.
- Multi-Cloud:Workload distribution across provider ecosystems to mitigate vendor concentration risk.
Deployment gravity centers on Hybrid Cloud for regulated industries; SME onboarding concentrates in Public Cloud tiers.
End User:
Customer type determines contract structure, with government procurement requiring FedRAMP authorization timelines that extend 12-18 months.
- Large Enterprises:Petabyte-scale deployments with custom SLA negotiations. Tier-one banks in the United States sustain deepest per-account spend through multi-year immutable retention mandates.
- SMEs:Rapid onboarding via self-service portals with consumption-based pricing. Indian and Brazilian mid-market firms represent steepest expansion trajectory as legacy tape migration accelerates.
- Government:FedRAMP and GDPR-compliant sovereign cloud requirements.
- Educational Institutions:Research data management with grant-funded storage allocations.
Revenue concentration sits with Large Enterprises; account velocity peaks among SMEs.
Technology:
Application-specific capabilities differentiate commodity storage from value-added repository services. AI-integrated analytics command pricing premiums in pharmaceutical research segments.
- AI Integration:Vector database capabilities enabling real-time unstructured data querying. Pharmaceutical researchers in Switzerland and the United States deploy these tiers for training-data lineage tracking under FDA documentation guidelines.
- Encryption:Zero-knowledge architectures with customer-managed keys. German enterprises and Australian government agencies specify this layer to satisfy jurisdictional access restrictions.
- Data Analytics:Metadata-driven policy engines for automated compliance enforcement.
- API Management:Programmatic access controls for DevOps integration and legacy mainframe connectivity.
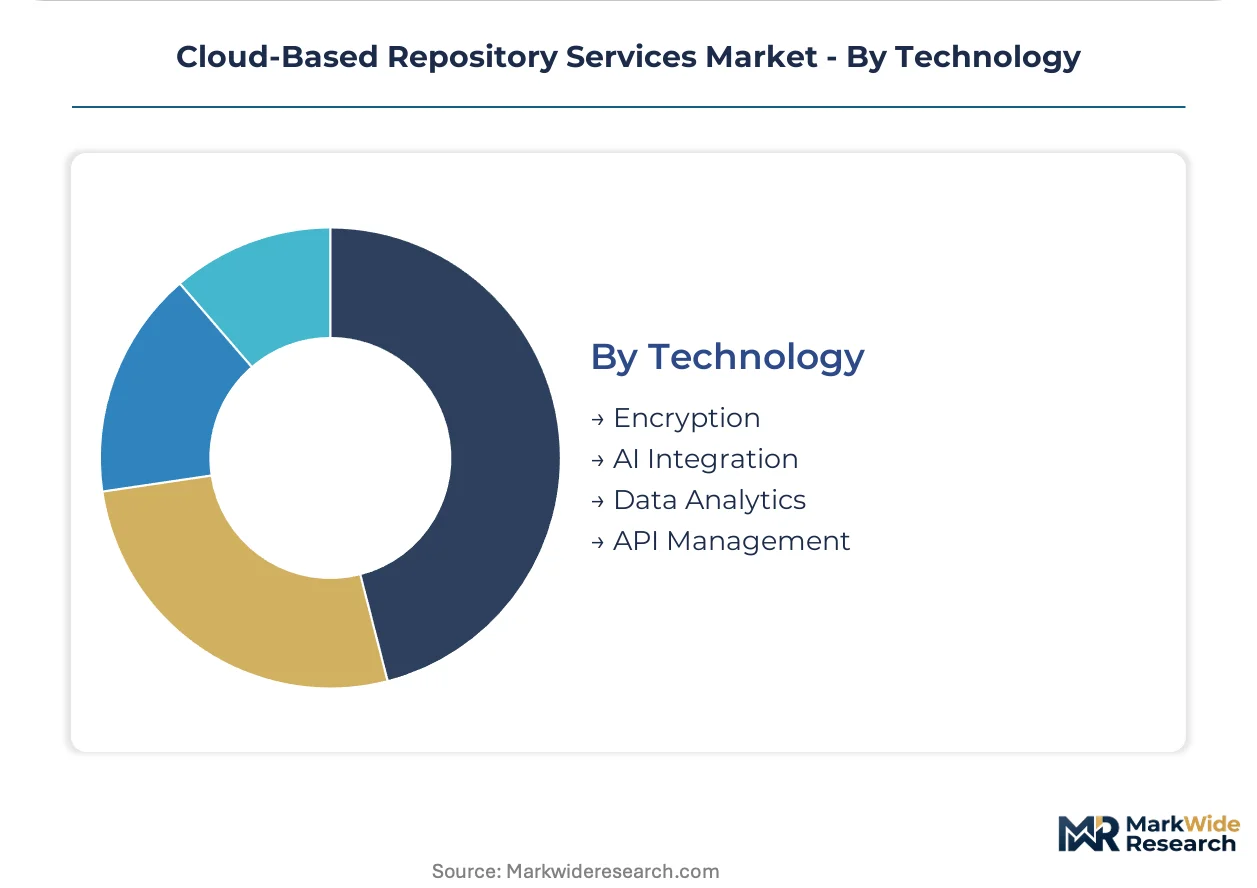
Capability investment clusters in AI Integration; baseline procurement requires Encryption certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government cloud-first mandates and data localization incentives are concentrating procurement authority in national capitals and designated technology corridors. Sovereign cloud requirements in Europe, Asia-Pacific, and North America are fragmenting vendor operational scale while accelerating domestic infrastructure buildouts.
United States
FedRAMP authorization timelines stretching 12-18 months dominate federal procurement cycles, compressing vendor qualification windows. SEC recordkeeping rules and HIPAA business associate agreements extend compliance burdens to financial services and healthcare sub-verticals. Northern Virginia data center clusters and Dallas-Fort Worth zones anchor hyperscaler infrastructure expansion for enterprise workloads.
Germany
GDPR Article 30 record-of-processing obligations and EU AI Act documentation requirements reshape healthcare provider procurement criteria. The country's national data protection regulator enforces purpose-limitation compliance for patient imaging archives. Frankfurt and Berlin technology corridors concentrate sovereign cloud investments from automotive suppliers and pharmaceutical researchers.
India
PLI scheme incentives for domestic data center infrastructure attract hyperscaler investment into Mumbai and Hyderabad zones, reducing latency for South Asian enterprise workloads. RBI and SEBI data localization guidelines compel financial institutions to maintain in-country repositories. Bangalore and Chennai enterprise clusters accelerate tape-to-cloud migration among mid-market manufacturers.
Japan
METI data sovereignty requirements and pharmaceutical research documentation guidelines drive demand for AI-integrated analytics tiers. The country's national data protection framework enforces geographic restriction rules for sensitive workloads. Tokyo and Osaka metropolitan areas concentrate FinOps governance model adoption among automotive and electronics manufacturers.
Brazil
ANVISA medical imaging digitization mandates create qualified demand for HIPAA-equivalent repository services in underpenetrated healthcare markets. The country's national health surveillance agency enforces audit trail requirements for diagnostic data archives. São Paulo and Rio de Janeiro hospital networks anchor first-mover positioning for compliance-certified cloud storage providers.
Cloud-Based Repository Services Market Vendor Landscape
Player mix skews toward hyperscale infrastructure providers with sovereign cloud specializations and compliance-engineering depth. Market structure concentrates around three strategic tiers: infrastructure-scale operators with zone dominance, vertical-accredited specialists with FedRAMP and HITRUST portfolios, and AI-integrated analytics platforms with vector database capabilities. Dominant competitive moves include bundling compliance certifications into standard service tiers and embedding automated policy engines into storage management planes.
Among infrastructure-scale operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the three dominant competitive archetypes. Amazon Web Services anchors zone dominance across North American and European corridors through elastic capacity scaling. Microsoft Azure occupies the vertical-accredited position through FedRAMP and HITRUST specializations in government and healthcare segments. Google Cloud Platform represents the AI-integrated analytics tier with vector database capabilities for unstructured pharmaceutical research workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Corporation |
| Oracle Corporation |
| HCL Technologies |
| Fujitsu Ltd. |
| Cisco Systems |
| NetApp |
| Others |
Supply Flow & Price Mechanics
FedRAMP authorization timelines stretching 12-18 months compress vendor qualification windows while simultaneously gating price premiums, as only accredited providers can bid for federal contracts that sustain above-market rates. This certification bottleneck concentrates pricing power among incumbent hyperscalers with compliance engineering depth, forcing mid-tier vendors into cost-competitive public cloud tiers or specialized healthcare verticals.
Pricing Analysis
Certification level creates the primary spread between service tiers, with FedRAMP-authorized and HITRUST-certified offerings commanding 40-60% premiums over baseline storage. Consumption-based pricing with transparent egress structures dominates enterprise procurement, displacing committed-use discount schemes as FinOps governance tightens unit-cost-per-gigabyte targets. Pricing pressure stems from hyperscaler capacity expansion in Mumbai and Hyderabad zones under India's PLI scheme, compressing margins for regional providers. SMEs in Brazil and India exhibit highest price sensitivity, while tier-one banks in Germany and the United States absorb premium immutable retention tiers without elasticity.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for data center hardware components, extending server deployment timelines for cloud infrastructure buildouts. Supply concentrates in Taiwan for advanced semiconductors, China for server assembly and networking equipment, and the United States for specialized storage controllers and encryption hardware. Raw material dependencies span rare earth elements for magnetic storage substrates, high-purity silicon for solid-state controllers, and copper for data center power distribution. Single-source vulnerability in Taiwan semiconductor fabrication poses structural risk to capacity expansion timelines. Distribution runs through hyperscaler direct procurement channels and regional systems integrators serving government and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise tape-to-cloud migration cycles are entering a recovery phase as ransomware recovery mandates harden retention requirements and compress procurement decision timelines. This cyclical upturn favors vendors with pre-positioned compliance certifications and sovereign cloud infrastructure.
For Market Incumbents: Shield market position by accelerating FedRAMP and EU sovereign cloud certifications ahead of 12-18 month authorization windows, locking out mid-tier competitors from federal and German automotive supplier contracts. Prioritize vertical integration into encryption hardware manufacturing to reduce Taiwan semiconductor exposure and capture zero-knowledge architecture premiums demanded by German enterprises and Australian government agencies. For New Entrants and Emerging Players: SME self-service onboarding gaps in Brazilian healthcare and Indian manufacturing represent the most penetrable white-space, as hyperscalers under-serve mid-market firms with complex compliance needs and limited procurement bandwidth. Target ANVISA-equivalent repository services for São Paulo hospital networks, leveraging HIPAA documentation frameworks as regulatory shorthand. Pursue FinOps channel partnerships to bundle repository procurement with spend governance tools, reducing customer acquisition costs versus direct enterprise sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-integrated analytics tiers as vector database capabilities commoditize, shifting value capture toward compliance-automation software layers. Long-term viability over the next decade hinges on embedded policy engines that automate GDPR Article 30 and EU AI Act documentation. Acquisition targets should exhibit FedRAMP authorization in-process or HITRUST certification with healthcare provider reference accounts. Monitor hyperscaler capex disclosures for Mumbai and Hyderabad zone expansion as inflection signal for South Asian competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Bundling | Embedding FedRAMP and HITRUST into standard tiers accelerates procurement velocity for federal and healthcare buyers. |
| Sovereign Cloud Infrastructure Buildout | Frankfurt and Berlin zone expansion satisfies GDPR data residency requirements for German automotive suppliers. |
| AI-Integrated Analytics Platform Launch | Vector database capabilities enable real-time pharmaceutical research querying under FDA documentation guidelines. |
| FinOps Channel Partnership | Bundling repository procurement with spend governance tools reduces SME customer acquisition costs in India. |
| Zero-Knowledge Encryption Tier Introduction | Customer-managed key architectures capture premiums from German enterprises and Australian government agencies. |
Methodological Framework
Desk research of hyperscaler capex disclosures, regulatory filing databases, and cloud infrastructure trade publications preceded structured interviews with enterprise IT procurement officers, compliance engineering directors, healthcare CIOs, financial services risk managers, and channel partner executives. Primary fieldwork captured procurement committee decision criteria, certification timeline experiences, and migration project economics across German automotive, US banking, Indian manufacturing, and Brazilian healthcare verticals. Secondary validation drew from SEC 10-K infrastructure segments, EU regulatory impact assessments, and RBI data localization guidance documents. Bottom-up account-level spend analysis triangulated against top-down market sizing from infrastructure capacity announcements.
Variance decomposition across service type, deployment model, end-user scale, and embedded technology dimensions anchored the analytical framework throughout the projection horizon. Segmentation modeling incorporated backup versus archiving functionality splits, hybrid versus public cloud deployment gravity, SME versus large enterprise contract structures, and AI integration versus baseline encryption capability tiers. CAGRs derived from elasticity-adjusted adoption curves and compliance mandate implementation schedules, with tape retirement timelines and ransomware recovery regulation enforcement as cloud-specific forecast inputs.
Forecasts assume regulatory continuity in FedRAMP authorization standards, GDPR Article 30 enforcement patterns, and EU AI Act documentation requirements; material policy shifts would require re-modeling adoption trajectories and vendor qualification criteria. Specific risks include encryption key escrow mandate expansions in Australia and the United Kingdom, Russia data localization enforcement fragmentation, and LTO-9 cold storage cost competitiveness beyond seven-year retention horizons. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Cloud Services Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Cloud Banking Solutions Market