
 Product As a Service Market | 2026-2036
Product As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Product As a Service Market Outlook
Asset-light project finance and operational leasing is rewriting competitive entry barriers across the Product As a Service landscape. Microsoft Corporation leverages its Azure infrastructure stack to anchor enterprise software subscriptions at scale. IBM Corporation specializes in hybrid cloud service bundles that integrate hardware monitoring with predictive maintenance. Cisco Systems controls networking-as-a-service channels through embedded financing partnerships with regional distributors.
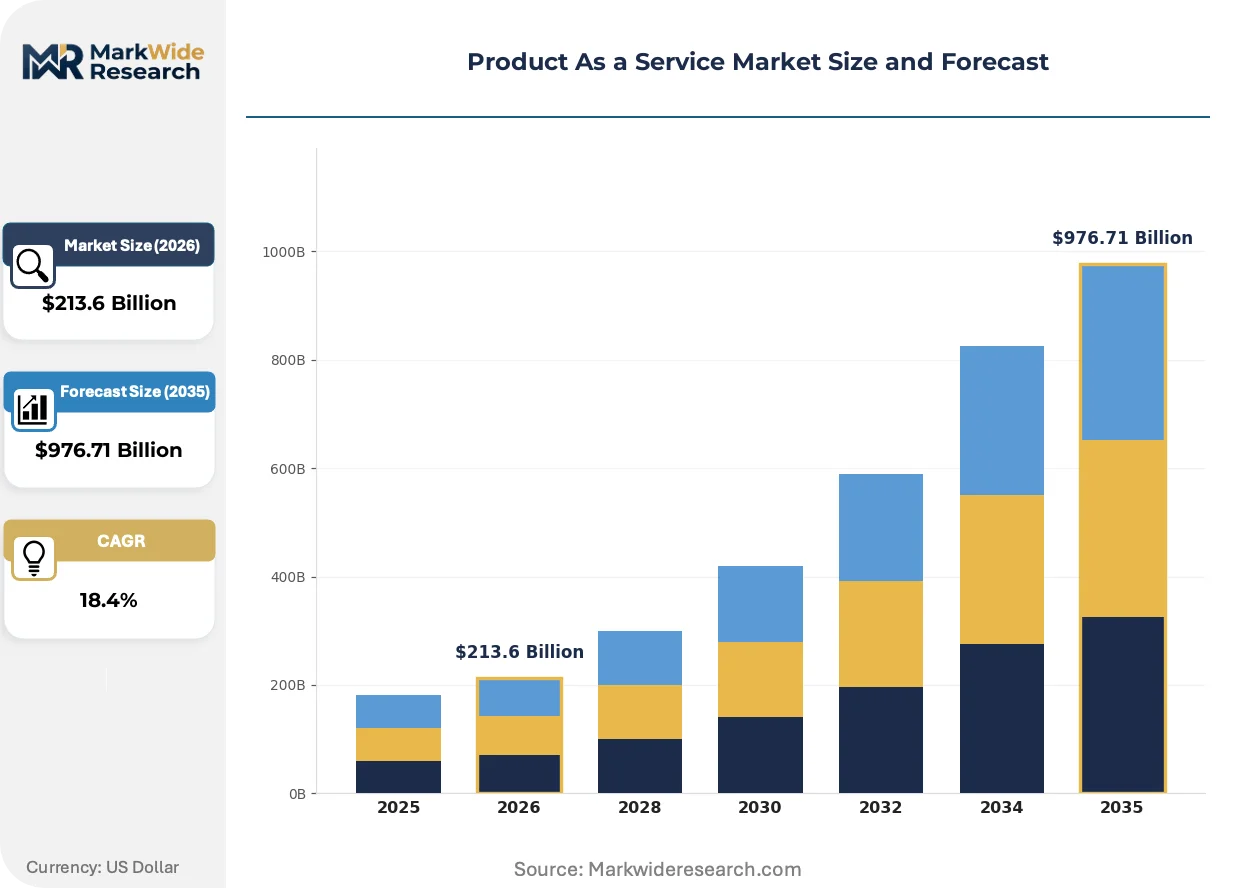
Product As a Service denotes a commercial arrangement where physical or digital assets are accessed via recurring payment structures rather than outright ownership, typically governed by usage telemetry, uptime guarantees, and lifecycle responsibility clauses. The model shifts capital expenditure to operational expenditure while embedding remote diagnostics, firmware updates, and performance analytics into contractual obligations. Software and cloud-based delivery models currently lead margin pools due to near-zero marginal replication costs, while machinery and equipment segments show accelerating conversion as industrial buyers prioritize outcome guarantees over asset possession. Subscription and pay-per-use service types attract the fastest expansion as metering technologies mature and buyers demand consumption-aligned pricing.
The US Federal Trade Commission scrutinizes auto-renewal transparency in subscription contracts, while the EU Digital Services Act imposes accountability standards on cloud platform intermediaries, and Japan's METI promotes servitization guidelines for manufacturing SMEs. These frameworks collectively elevate compliance costs for entrants while rewarding incumbents with established legal infrastructure and certified audit trails. Stakeholders must monitor evolving data localization mandates and circular-economy disclosure requirements as these rules increasingly determine which service architectures qualify for public-sector and regulated-industry procurement.
Market Dynamics
ISO 55000 asset management standards are compressing procurement timelines for subscription-based hardware, forcing industrial buyers to restructure capital allocation frameworks around uptime guarantees and lifecycle responsibility clauses rather than ownership transfer.
Growth Catalysts
- Cloud delivery models:Near-zero marginal replication costs in software stacks allow providers to scale metering infrastructure without proportional infrastructure investment, accelerating pay-per-use adoption across enterprise IT.
- Germany's Industry 4.0 servitization incentives:Federal manufacturing modernization programs subsidize sensor deployment and predictive maintenance integration for mid-cap equipment suppliers transitioning to recurring revenue.
- Hybrid delivery architectures:Enterprise buyers in North American data centers now demand bundled hardware-software-finance packages that embed remote diagnostics and firmware lifecycle management.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabrication bottlenecks delay IoT sensor deployment for usage-based billing infrastructure, extending equipment onboarding cycles.
- EU Digital Services Act compliance:Cloud platform intermediaries face elevated audit costs for data localization and algorithmic transparency, raising barriers for multi-tenant service architectures.
- Residual value uncertainty:Industrial machinery lessors struggle to model end-of-lease equipment valuation without standardized secondary market benchmarks, compressing contract tenors.
Strategic Opportunities
- Japan's METI SME servitization guidelines:Government-backed certification programs for small manufacturers create subsidized entry paths for subscription-based maintenance and performance contracting.
- Edge computing convergence with 5G:Low-latency telemetry enables real-time usage metering for distributed industrial equipment previously excluded from remote monitoring economics.
- United States auto-renewal transparency mandates:FTC enforcement actions against opaque subscription terms reward providers with certified disclosure frameworks and compliant billing infrastructure.
Industry Challenges
- Predictive maintenance algorithm development:Equipment OEMs lack sufficient failure-mode data to train proprietary models, forcing reliance on third-party analytics vendors with incompatible data schemas.
- Legacy ERP integration:SAP and Oracle systems at industrial buyers require custom API development to reconcile subscription billing with capital-asset depreciation workflows, extending implementation timelines.
- Circular economy disclosure requirements:France's AGEC law and similar extended producer responsibility frameworks demand granular component-level tracking that exceeds current supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product As a Service Market |
| Market Size in 2026 | $213.6 Billion |
| Market Size in 2035 | $976.71 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Machinery, Equipment Service Type: Subscription, Pay-per-use, Leasing, Maintenance End User: Consumer Electronics, Industrial, Healthcare, Retail Delivery Model: Cloud-based, On-premises, Remote, Hybrid |
| Companies Covered | Amazon Web Services, Microsoft Corporation, IBM Corporation, Oracle Corporation, Dell Technologies, Cisco Systems, Salesforce, HP Development Company, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product As a Service Market Strategic Shifts
Telemetry-enabled pricing models are compressing the gap between software subscription economics and physical asset deployment, embedding performance analytics and remote diagnostics into contractual obligations across industrial and IT infrastructure.
Digital twin technology is migrating from aerospace prototyping to mainstream manufacturing equipment monitoring. Heavy machinery OEMs in Germany and Japan now deploy virtual replicas to simulate failure modes and optimize maintenance windows. This capability is migrating from premium-tier contracts to standard offerings as sensor costs decline and edge processing matures.
The EU CSRD mandates granular sustainability disclosure for in-scope companies, forcing Product As a Service providers to instrument supply chains for carbon intensity and circular material flows. Industrial lessors must now embed lifecycle emissions tracking into contract terms. German automotive suppliers and French industrial equipment firms face the steepest compliance curves as they restructure reporting infrastructure.
Enterprise buyers now unbundle after-sales service from capital acquisition, treating maintenance and uptime guarantees as separately negotiable subscription components. Industrial procurement teams in the United States negotiate performance-based penalties independent of hardware financing. This pattern is most visible in North American data center infrastructure and Japanese precision manufacturing, where buyers prioritize outcome metrics over vendor relationships.
Product As a Service Market Segmentation
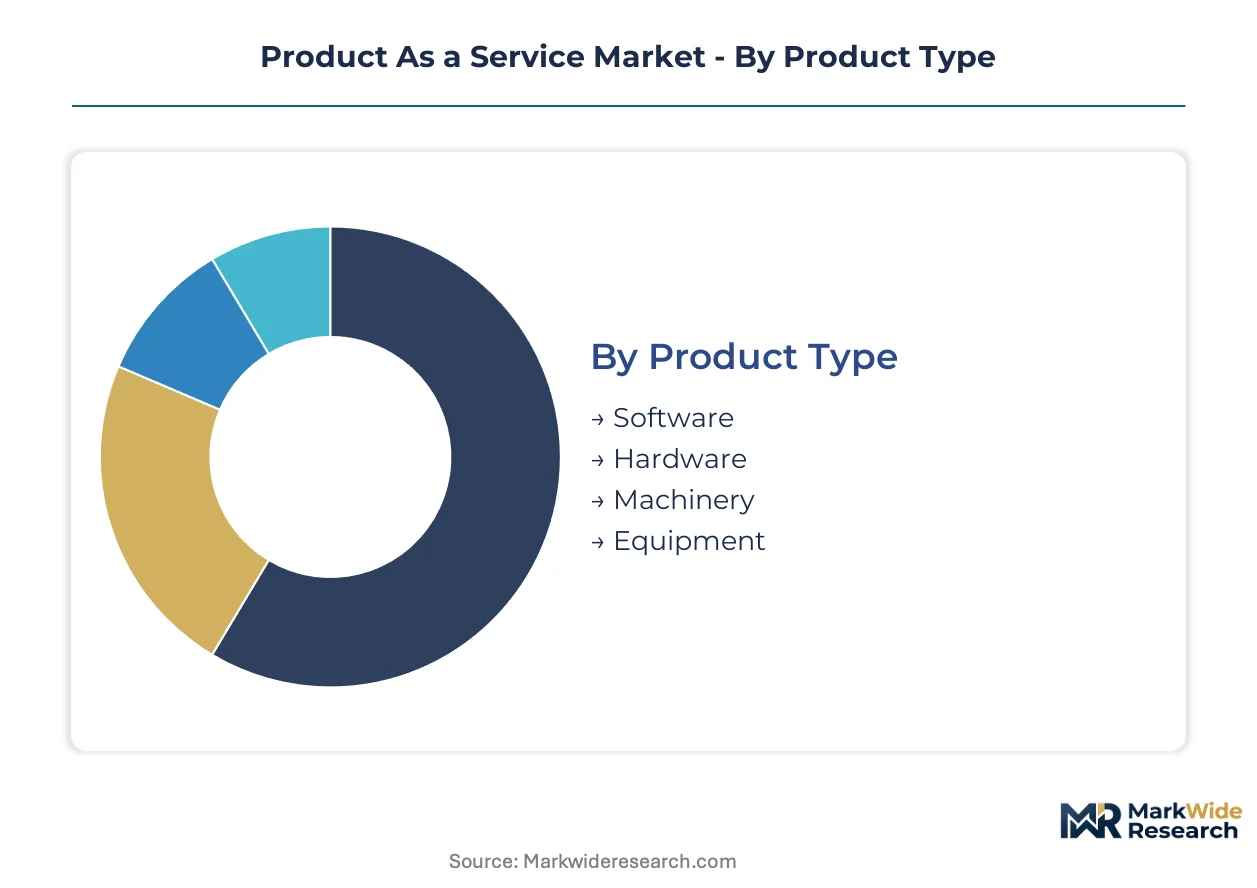
Segmentation in Product As a Service markets reveals divergent margin profiles and contractual complexity across physical and digital asset classes. Buyers structure procurement around telemetry maturity, outcome accountability, and integration burden with legacy enterprise systems.
Product Type:
Mature software stacks contrast with emerging machinery servitization as industrial OEMs retrofit sensor infrastructure for usage-based billing.
- Software:Cloud-native architectures enable instantaneous provisioning and zero-marginal-cost replication. North American enterprise IT buyers dominate procurement, prioritizing API-native integration with existing identity management stacks.
- Hardware:Networking and compute appliances shift from perpetual licenses to subscription firmware entitlements. German industrial buyers drive adoption through Industry 4.0 modernization programs that subsidize sensor deployment.
- Machinery:Heavy equipment OEMs embed predictive maintenance clauses into long-term service agreements. Japan's METI certification programs accelerate SME adoption of performance-based contracting.
- Equipment:General-purpose industrial assets transition via operational leasing structures. Residual value uncertainty compresses contract tenors in the absence of standardized secondary market benchmarks.
Software retains volume leadership; machinery holds the steepest expansion curve.
Service Type:
Pricing architecture spans fixed recurring commitments to variable consumption metering, each imposing distinct technical and contractual requirements on providers.
- Subscription:Fixed-interval billing with tiered feature access dominates enterprise software procurement. United States FTC auto-renewal transparency mandates elevate compliance costs for billing infrastructure.
- Pay-per-use:Telemetry-enabled metering aligns costs with actual consumption. Edge computing convergence with 5G low-latency networks enables real-time billing for distributed industrial equipment.
- Leasing:Operational finance structures transfer lifecycle responsibility to lessors. French AGEC circular economy disclosure requirements demand component-level tracking exceeding current supply chain visibility.
- Maintenance:Outcome-based service contracts separate uptime guarantees from capital acquisition. North American data center buyers negotiate performance penalties independent of hardware financing arrangements.
Subscription captures the largest revenue pool; pay-per-use expands most quickly.
End User:
Demand concentration varies sharply across sectors, with industrial buyers prioritizing asset-light balance sheets and healthcare procurement teams navigating stringent compliance frameworks.
- Consumer Electronics:Device-as-a-service models bundle hardware refresh cycles with technical support. United States enterprise mobility programs drive adoption through operational expenditure reclassification.
- Industrial:Manufacturing buyers restructure capital allocation around ISO 55000 uptime guarantees rather than ownership transfer. German automotive suppliers face steep EU CSRD sustainability disclosure curves.
- Healthcare:Medical equipment servitization embeds regulatory compliance into contractual obligations. FDA quality system requirements extend to remote diagnostics and firmware lifecycle management.
- Retail:Point-of-sale and inventory management hardware shifts to managed service arrangements. Japanese precision manufacturing supply chains influence procurement specifications for upstream retail technology.
Industrial end users dominate contract value; healthcare climbs the fastest.
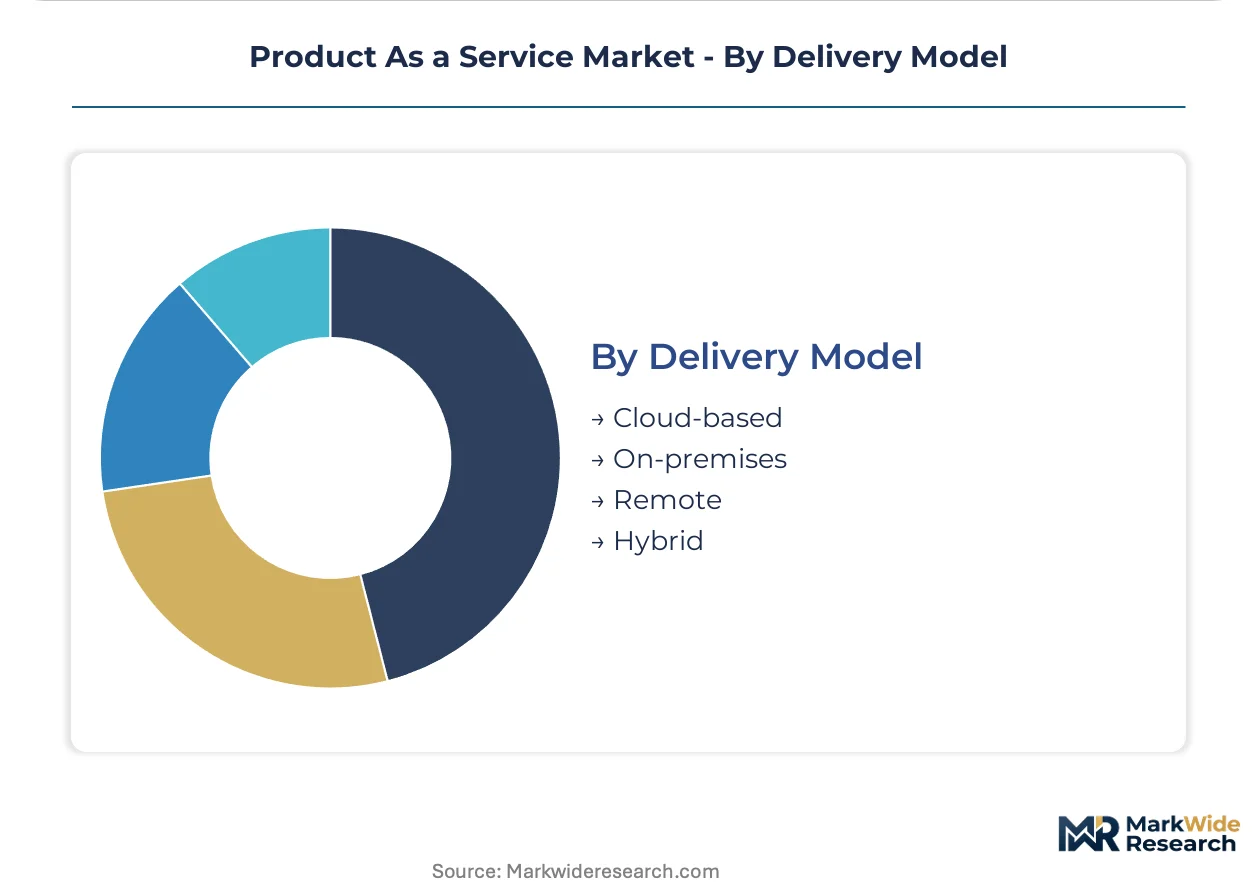
Delivery Model:
Deployment architecture determines telemetry latency, data sovereignty exposure, and integration complexity with buyer-side ERP systems.
- Cloud-based:Multi-tenant architectures centralize analytics and firmware distribution. EU Digital Services Act compliance elevates audit costs for data localization and algorithmic transparency.
- On-premises:Dedicated infrastructure meets stringent data residency requirements in regulated industries. German healthcare and financial services procurement teams mandate air-gapped deployments.
- Remote:Distributed edge nodes process telemetry without continuous cloud connectivity. 5G network slicing enables deterministic latency for time-critical industrial control applications.
- Hybrid:Partitioned workloads balance local processing with centralized analytics. North American enterprise buyers now demand bundled hardware-software-finance packages with embedded lifecycle management.
Cloud-based delivery holds volume leadership; hybrid architectures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT infrastructure teams in the United States drive the largest contract volumes for subscription-based hardware and software bundles, while German industrial buyers and Japanese precision manufacturers accelerate servitization adoption through government-backed modernization programs.
United States
North American data center operators demand hybrid delivery architectures that embed remote diagnostics and firmware lifecycle management into procurement contracts. FTC auto-renewal transparency mandates elevate compliance costs for billing infrastructure providers. Silicon Valley and Northern Virginia clusters concentrate cloud-native subscription deployments at enterprise scale.
Germany
Automotive suppliers and mid-cap equipment manufacturers restructure capital allocation around ISO 55000 uptime guarantees rather than asset ownership transfer. Federal Industry 4.0 servitization incentives subsidize sensor deployment for predictive maintenance integration. Bavarian industrial clusters lead machinery-as-a-service adoption among automotive tier-one suppliers.
Japan
Precision manufacturing SMEs transition to performance-based contracting through METI-backed certification programs. National servitization guidelines reduce entry barriers for subscription-based maintenance providers. Nagoya and Osaka industrial corridors concentrate digital twin deployments for heavy equipment monitoring.
United Kingdom
Financial services procurement teams mandate hybrid delivery models that partition sensitive workloads across cloud and on-premises infrastructure. FCA operational resilience requirements extend to third-party service provider continuity planning. London and Southeast England clusters dominate enterprise software subscription volumes.
South Korea
Electronics manufacturers and semiconductor fabricators adopt pay-per-use models for capital-intensive production equipment. National smart manufacturing initiatives accelerate IoT sensor deployment for usage-based billing infrastructure. Seoul Capital Area and Busan-Ulsan corridors concentrate operational leasing arrangements for advanced process tools.
Product As a Service Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service architectures. The market structure concentrates around hyperscale cloud infrastructure providers, legacy hardware OEMs transitioning to recurring revenue, and vertical-specific software vendors. Three archetypes dominate: platform orchestrators with embedded financing capabilities, equipment OEMs retrofitting sensor infrastructure for telemetry billing, and independent software vendors delivering API-native subscription stacks. Competitive moves center on strategic partnerships with regional distributors and portfolio diversification into outcome-based maintenance contracts.
Among hyperscale platform providers, Amazon Web Services and Microsoft Corporation exemplify the cloud-native archetype with near-zero marginal replication economics. IBM Corporation occupies a position bridging legacy hardware maintenance and hybrid cloud service bundles. These three anchors represent distinct strategic postures: infrastructure commoditization, enterprise software subscription scaling, and industrial equipment servitization integration.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Dell Technologies |
| Cisco Systems |
| Salesforce |
| HP Development Company |
| Lenovo |
| Others |
Value Chain & Pricing Dynamics
Taiwan semiconductor fabrication concentration creates dual exposure for Product As a Service providers, compressing hardware subscription margins through component scarcity while forcing supply chain redesign around single-source sensor dependencies. This chokepoint simultaneously widens pricing spreads between cloud-native software tiers and telemetry-enabled machinery contracts while accelerating regional diversification mandates from industrial buyers.
Pricing Analysis
Cost-plus contracts with Taiwan Semiconductor Manufacturing Company indexation dominate hardware-as-a-service procurement, embedding foundry wafer pricing into multi-year equipment subscription terms. Price differentiation rests on ISO 55000 certification tier and predictive maintenance algorithm maturity, with German automotive suppliers commanding premium spreads over uncertified mid-cap equipment vendors. Pricing pressure stems from residual value uncertainty in industrial machinery secondary markets, compressing contract tenors and elevating monthly rates. Healthcare procurement teams demonstrate lowest price sensitivity due to FDA-mandated uptime guarantees, while retail point-of-sale buyers negotiate aggressively on per-terminal economics.
Supply Chain Analysis
Supplier-financing facilities from Taiwan and South Korean component vendors extend payment terms to 180 days for IoT sensor module procurement, easing working capital burdens for machinery OEMs transitioning to recurring revenue. Geographic supply concentration centers on Taiwan for semiconductor fabrication, South Korea for memory and display components, and Germany for precision mechanical assemblies. Raw material dependencies span silicon wafers, rare earth magnets for motor assemblies, and lithium-ion cells for edge computing power reserves. Single-source vulnerability in Taiwan semiconductor fabrication creates systemic risk for usage-based billing infrastructure deployment. Distribution runs through regional systems integrators in North America, authorized distributors in Germany, and METI-certified service networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product As a Service represents a high-growth disruption anchored by 5G-edge convergence and EU CSRD sustainability disclosure mandates, which together restructure procurement specifications toward outcome-accountable contracting. The technological inflection in low-latency telemetry and the regulatory inflection in lifecycle emissions tracking create simultaneous entry windows for platform orchestrators and vertical specialists.
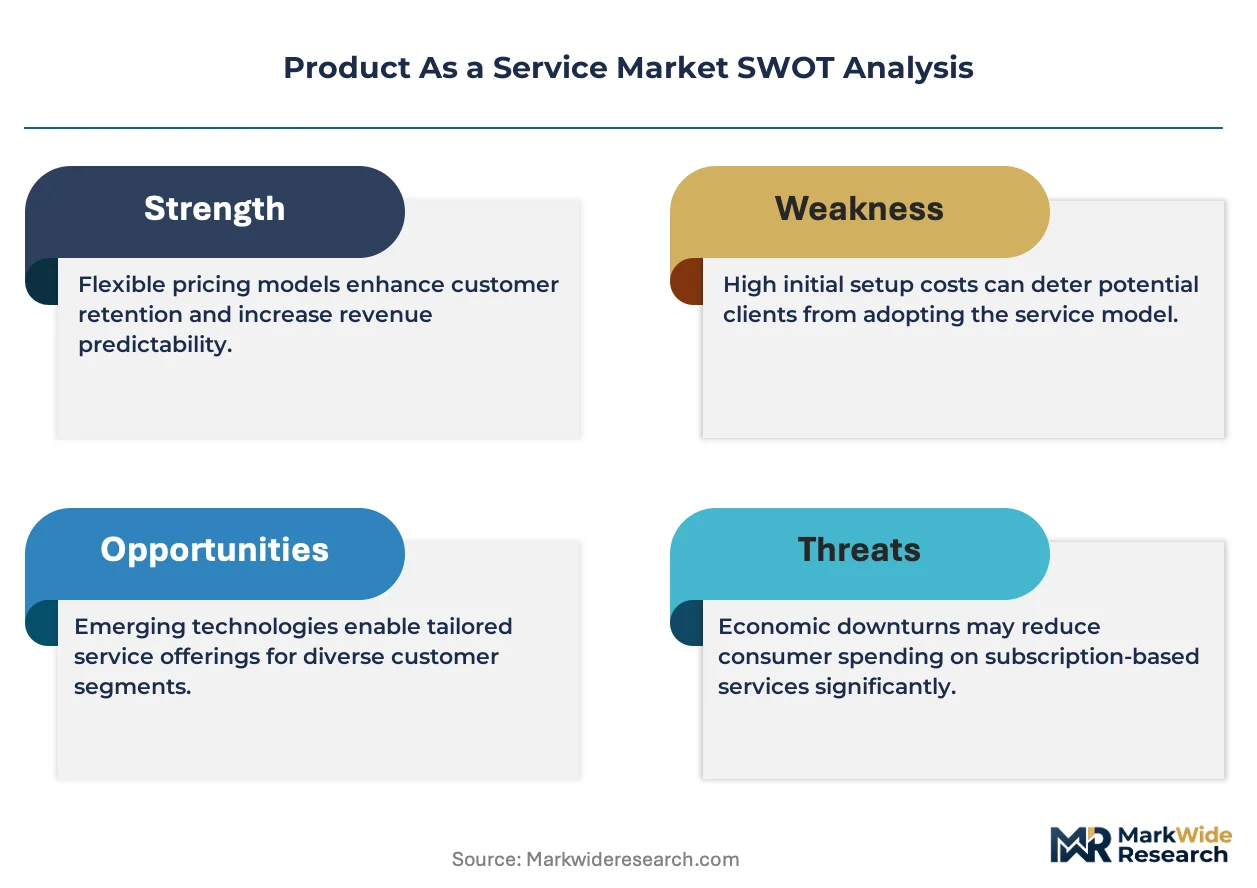
For Market Incumbents: Pre-empt margin erosion in hardware subscriptions by embedding proprietary predictive maintenance algorithms before third-party analytics vendors achieve schema standardization. Consolidate channel control through exclusive financing partnerships with regional distributors, particularly in North American data center and German automotive verticals where ISO 55000 compliance creates switching costs. Prioritize backward integration into edge computing hardware to reduce dependency on Taiwan semiconductor supply. For New Entrants and Emerging Players: Build out certified service networks targeting Japan's METI-backed SME servitization programs, where government subsidies reduce customer acquisition costs for performance-based maintenance contracts. White-space concentration exists in French industrial equipment lessors facing AGEC circular economy disclosure requirements without existing component-level tracking infrastructure. Lead with hybrid delivery architecture expertise, as North American enterprise buyers now demand bundled hardware-software-finance packages that legacy ERP systems struggle to provision. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors platform orchestrators with embedded financing capabilities over point-solution vendors. Long-term viability favors providers controlling both telemetry infrastructure and outcome-accountable contract terms, as buyer procurement teams increasingly unbundle capital acquisition from maintenance guarantees. Monitor FTC enforcement patterns on auto-renewal transparency as the signal to watch for compliance-cost barriers favoring incumbents with certified billing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | Proprietary failure-mode training data creates differentiation against third-party analytics vendors with incompatible schemas. |
| Hybrid Cloud Service Bundle Integration | IBM and Microsoft architectures demonstrate how hardware monitoring firmware locks enterprise buyers into multi-year subscription cycles. |
| ISO 55000 Certification Investment | German Industry 4.0 incentives reward certified providers with subsidized sensor deployment and compressed procurement timelines. |
| Regional Distribution Partnership | Cisco's embedded financing alliances with North American distributors control networking-as-a-service channel economics. |
| EU CSRD Compliance Infrastructure | Granular carbon intensity tracking capabilities qualify providers for French automotive and German industrial procurement mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with enterprise IT procurement officers, industrial maintenance directors, OEM service strategy heads, and cloud platform engineering leads. Secondary validation drew from SEC filings of hyperscale providers, EU Digital Services Act implementation guidance, METI servitization program documentation, and ISO 55000 certification registry data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical subscription billing adoption curves and machinery operational leasing penetration rates anchored the analytical framework. Segmentation dimensions modeled span product type, service architecture, end-user vertical, and delivery model complexity. CAGRs were derived from installed base telemetry deployment trajectories and recurring revenue conversion rates at industrial OEMs. Forecast inputs incorporated 5G network slicing availability timelines and EU circular economy disclosure phase-in schedules.
Stress conditions across semiconductor supply concentration, auto-renewal regulatory enforcement intensity, and residual value modeling uncertainty were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sensor cost decline curves and enterprise ERP integration friction. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Electronic Discovery Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Super Apps Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
UX Services Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Community Forum Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Online Dating Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Global E-Filing Platforms Market