
 Data Center Market | 2026-2036
Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Market Intelligence
The capital-intensive nature of hyperscale facility construction is bifurcating the competitive landscape. Hyperscale operators like Amazon Web Services (AWS) build massive, proprietary fleets to support their cloud platforms. In contrast, colocation specialists such as Equinix and Digital Realty provide multi-tenant infrastructure, enabling enterprises to deploy assets without the high upfront capital expenditure. This structural split defines the primary routes to market for end users.
A data center is a secured physical facility that centralizes an organization's IT operations and equipment for storing, processing, and disseminating data. These facilities are engineered with redundant power, advanced cooling systems like liquid cooling, and high-bandwidth network connectivity to ensure continuous uptime and service level agreements. Cloud deployment models dominate new workload deployments, while colocation remains critical for hybrid IT strategies. Within applications, the resource demands of big data analytics are pushing infrastructure requirements.
Regulations increasingly focus on energy efficiency, with frameworks like the EU's CSRD and the EPA's ENERGY STAR program setting new performance benchmarks. In Asia, China's dual carbon goals also influence design and operational standards for new facilities. Operators must balance performance and scalability with verifiable sustainability metrics to maintain market access and secure long-term contracts.
Market Dynamics
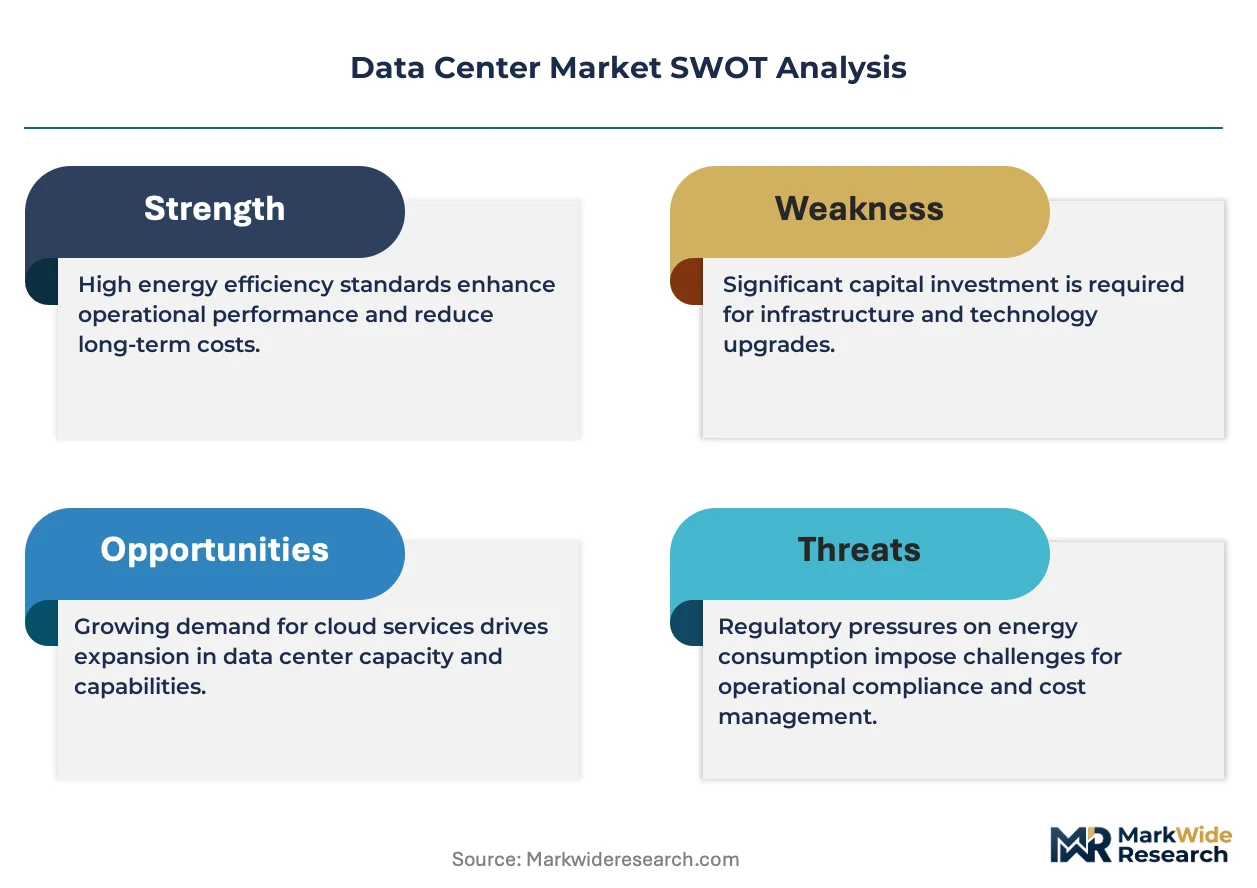
The central structural force shaping the data center market is the collision between exponential demand for data processing, driven by AI, and stringent new sustainability mandates, exemplified by the EU's Corporate Sustainability Reporting Directive (CSRD).
Growth Catalysts
- Big Data Analytics:The expansion of big data applications within financial services and e-commerce sectors is a primary driver, requiring immense computational and storage capacity.
- Sustainability Mandates:Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) are compelling operators to invest in new, energy-efficient infrastructure to meet compliance and attract ESG-conscious clients.
- Geographic Hub Concentration:Demand continues to consolidate in established hubs like Northern Virginia, Singapore, and Frankfurt, concentrating capital investment in these highly connected regions.
Market Restraints
- High Capital Expenditure:The immense upfront cost of constructing hyperscale facilities, including land acquisition and specialized equipment, limits new market entrants.
- Power Grid Constraints:In key markets like Northern Virginia and Dublin, securing sufficient and reliable power from utility providers is a significant bottleneck for new projects.
- Heat Dissipation Limits:Conventional air cooling methods are reaching their physical limits with high-density server racks, constraining rack power density for AI workloads.
Strategic Opportunities
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling technologies offer a path to manage heat from high-performance computing, opening a market for specialized infrastructure upgrades.
- Emerging Secondary Markets:Development in secondary markets like Poland or Malaysia can bypass the power and land constraints of primary hubs, offering growth potential.
- Government Incentives:Tax abatements for sustainable construction, such as those tied to the US Inflation Reduction Act (IRA), create favorable investment conditions for greenfield projects.
Industry Challenges
- Specialized Skills Gap:A shortage of qualified personnel with expertise in advanced cooling systems and sustainable facility management hinders operational efficiency and new builds.
- Navigating Multi-Jurisdictional Regulations:Operators face complexity in aligning facility designs with a patchwork of global energy standards, from the EPA's ENERGY STAR in the US to China's dual carbon goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Market |
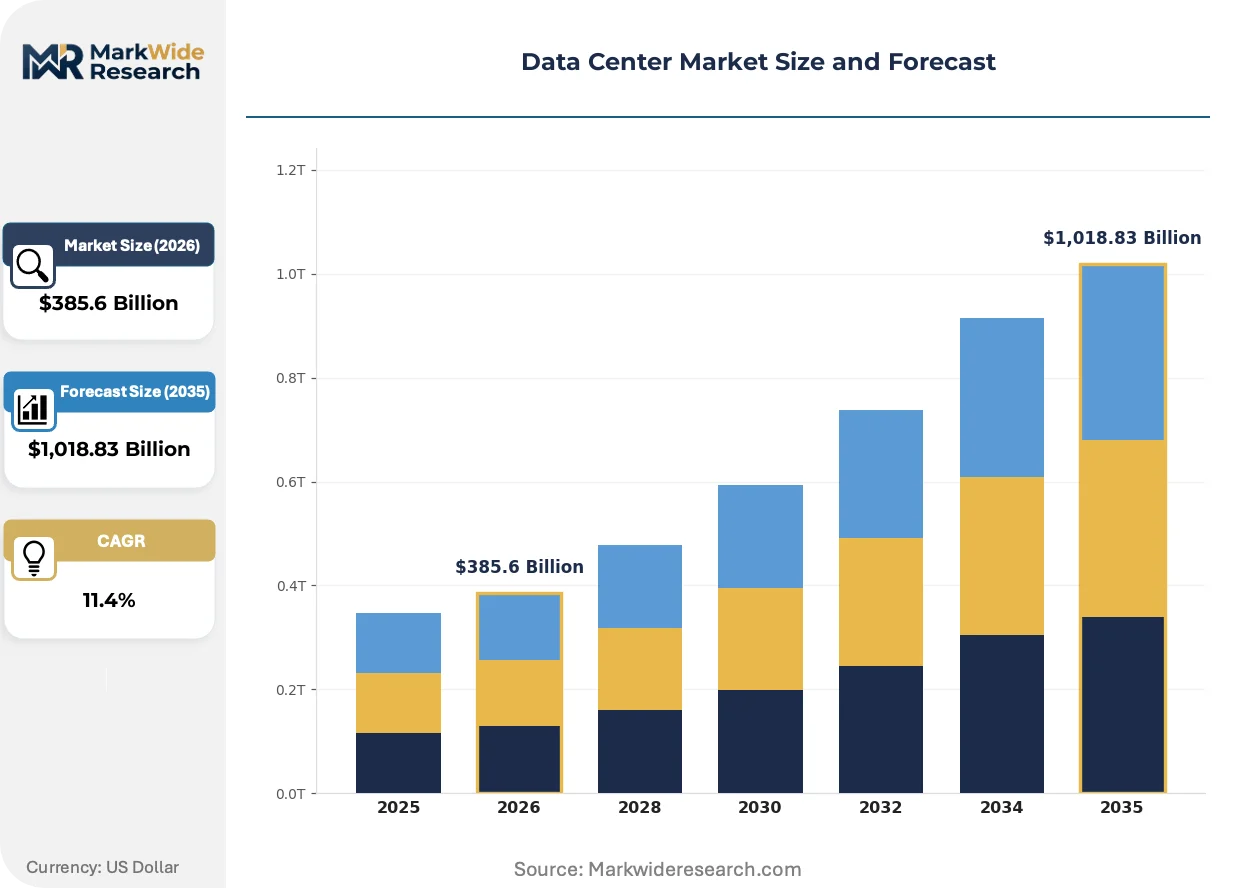
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,018.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Colocation, Cloud, Hybrid, Edge Solution/Offering: Infrastructure Management, Network Security, Storage Solutions, Virtualization, Backup & Recovery Application: Big Data Analytics, E-commerce Platforms, Streaming Services, Financial Trading, Scientific Research End User: Telecommunication Providers, Cloud Service Providers, Research Institutions, Public Sector Agencies, Content Delivery Networks |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud, Equinix, Digital Realty, Meta, NTT Global Data Centers, CyrusOne, QTS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Market Strategic Shifts & Innovations
The fundamental architecture of data center infrastructure is undergoing a significant transformation, driven by workload-specific hardware demands. This shift moves the market away from monolithic servers toward more specialized and disaggregated systems designed for efficiency and performance.
Disaggregated infrastructure separates compute, storage, and networking into independent, composable resource pools. Hyperscale operators are adopting this model to improve utilization for AI and cloud-native applications. This approach is decomposing the traditional, tightly integrated server into more flexible, software-defined components, enabling more efficient hardware lifecycle management.
Regulations such as the EU's F-Gas Regulation are phasing down the use of fluorinated greenhouse gases common in traditional cooling systems. This mandate directly impacts data center cooling strategies, accelerating the shift away from legacy computer room air conditioners. Operators in Europe are most affected, now prioritizing investments in liquid cooling or systems using low global warming potential refrigerants.
Enterprise clients are increasingly moving from fixed-space colocation contracts toward more flexible, on-demand capacity models. This shift disrupts the traditional multi-year lease model, favoring providers who offer cloud-like, pay-as-you-go infrastructure services. This consumption-based procurement is most visible in North American and European markets among enterprises executing hybrid cloud strategies.
Data Center Market Segmentation
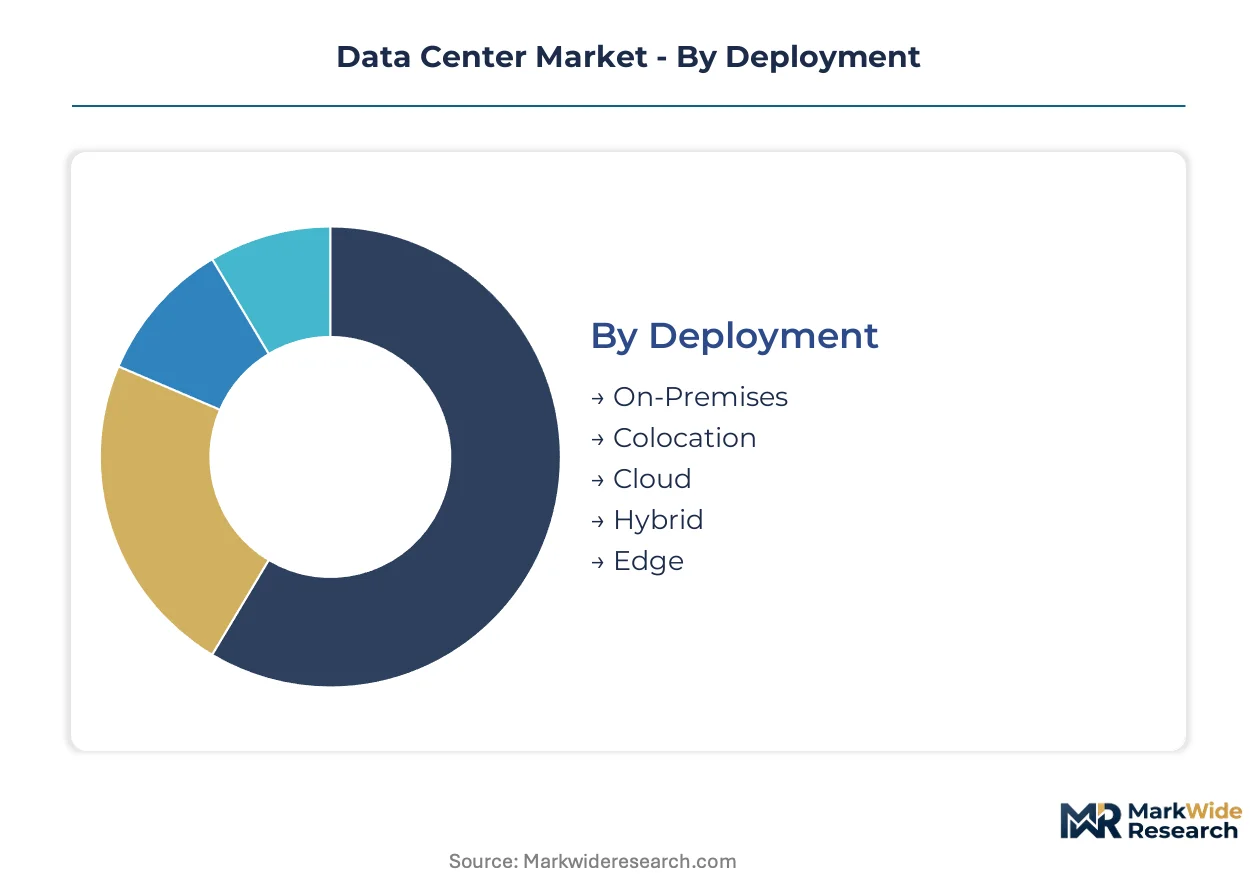
The data center market's segmentation provides a granular view of how distinct operational models and technological solutions cater to diverse end-user requirements. Understanding these segments helps identify where capital investment generates the highest returns and where specialized solutions address specific industry pain points.
Deployment:
Margin pools within deployment models reflect the balance between capital expenditure and operational control.
- Colocation:This model provides shared data center space, power, cooling, and network connectivity for customer-owned equipment. Demand is concentrating in established hubs like Singapore, driven by enterprises seeking hybrid IT strategies without large upfront investments.
- Cloud:This model leverages virtualized, on-demand resources delivered over the internet, abstracting underlying infrastructure from users. Demand is concentrating in North America and Europe, propelled by the need for scalable, flexible infrastructure for AI and cloud-native applications.
- On-Premises:Organizations host IT infrastructure within their own facilities, retaining full control over data and operations.
- Hybrid:This model integrates on-premises, private cloud, and public cloud environments, optimizing workload placement for cost and performance.
- Edge:This model decentralizes computing closer to data sources and end-users, reducing latency for applications like IoT and real-time analytics.
On-Premises holds installed capacity. Cloud is rotating up the share rankings.
Solution/Offering:
Cost tiers within solutions are influenced by the complexity and criticality of the service provided.
- Infrastructure Management:This encompasses tools and processes for monitoring, optimizing, and automating data center physical and logical components. Demand is concentrating in hyperscale environments, driven by the need for verifiable sustainability metrics and operational efficiency.
- Network Security:This protects data center networks and systems from unauthorized access, cyber threats, and data breaches through firewalls, intrusion detection, and encryption. Demand is concentrating in financial services, driven by stringent compliance requirements and the increasing sophistication of cyberattacks.
- Storage Solutions:This provides data retention and retrieval capabilities through various technologies like SAN, NAS, and object storage.
- Virtualization:This creates virtual versions of computing resources, enabling efficient hardware utilization and flexible resource allocation.
- Backup & Recovery:This ensures data availability and business continuity through regular data copies and rapid restoration capabilities.
Network Security solutions are gaining share fastest, driven by escalating cyber threats across all sectors.
Application:
Volume demands across applications dictate the scale and specialized hardware requirements for underlying infrastructure.
- Big Data Analytics:This processes and analyzes large, complex datasets to extract insights and patterns, requiring immense computational and storage capacity. Demand is concentrating in financial services and e-commerce, driven by the need for predictive modeling and customer behavior analysis.
- E-commerce Platforms:This hosts online retail operations, managing product catalogs, transactions, and customer interactions with high availability and scalability. Demand is concentrating in Asia-Pacific, propelled by the rapid expansion of online shopping and digital marketplaces.
- Streaming Services:This delivers on-demand video and audio content, requiring high-bandwidth networking and distributed content delivery networks.
- Financial Trading:This executes high-frequency transactions and complex algorithmic strategies, demanding ultra-low latency and robust processing power.
- Scientific Research:This supports complex simulations, data modeling, and experimental analysis for fields like genomics and climate science.
Big Data Analytics applications are experiencing the steepest expansion trajectory, reflecting increasing data-driven decision-making.
End User:
Customer types define procurement patterns and the long-term contractual engagements within the data center market.
- Cloud Service Providers:These operate massive, distributed data centers to offer Infrastructure-as-a-Service, Platform-as-a-Service, and Software-as-a-Service to global clients. Demand is concentrating in established data center hubs like Northern Virginia, driven by the need for scalable, interconnected infrastructure.
- Telecommunication Providers:These utilize data centers for network infrastructure, core routing, mobile switching, and supporting their own cloud and edge services. Demand is concentrating in urban centers, propelled by the rollout of 5G networks and increased data traffic.
- Research Institutions:These deploy high-performance computing resources for scientific discovery, academic collaboration, and complex data analysis.
- Public Sector Agencies:These host sensitive government data and critical services, often adhering to strict security and compliance mandates.
- Content Delivery Networks:These distribute digital content closer to end-users, enhancing delivery speed and reducing latency for web applications and media.
Cloud Service Providers are driving significant new facility development, reflecting their continuous infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The data center market exhibits a dynamic regional landscape, where the flow of digital services and data often transcends national borders, creating both opportunities and infrastructure deficits. Key regions serve as net exporters of cloud capacity while others are net importers of critical IT services. This structural imbalance influences capital allocation and strategic development.
United States
Demand for hyperscale cloud services and advanced AI workloads drives significant investment across the United States. The US Inflation Reduction Act (IRA) provides tax abatements for sustainable construction, incentivizing greenfield projects. Northern Virginia remains a primary hub, concentrating capital for new facility development and interconnected infrastructure.
Singapore
Strong financial services and e-commerce growth fuel demand for colocation services within Singapore. The Singapore Green Plan 2030 encourages energy-efficient data center operations and sustainable practices. This island nation serves as a critical regional hub, attracting significant foreign direct investment in digital infrastructure.
Germany
Enterprise adoption of hybrid cloud strategies and stringent data sovereignty laws propel data center expansion in Germany. The EU's Corporate Sustainability Reporting Directive (CSRD) compels operators to adopt more energy-efficient infrastructure. Frankfurt is a major European internet exchange point, attracting substantial data center investment and new builds.
China
Exponential demand for big data analytics and e-commerce platforms requires massive computational capacity across China. China's dual carbon goals influence design and operational standards for new facilities, prioritizing green solutions. Major technology zones like Beijing and Shanghai are centers for hyperscale and cloud deployments.
Poland
Emerging as a secondary market, Poland offers growth potential by bypassing power and land constraints of primary hubs. The EU Green Deal initiatives support investments in sustainable digital infrastructure across the region. Warsaw is attracting new data center projects, leveraging its strategic location and lower operational costs.
Data Center Market Key Industry Players
Concentration sits with hyperscale operators and specialized colocation providers, shaping a bifurcated competitive landscape. The market structure exhibits a tiered consolidation, where a few large players dominate cloud infrastructure and multi-tenant facilities. Strategic archetypes include proprietary cloud platform builders and independent infrastructure service providers. Dominant competitive moves involve continuous capacity expansion and strategic geographic expansion into underserved markets.
Within the hyperscale operator archetype, Amazon Web Services (AWS) anchors global cloud infrastructure, providing extensive computing and storage resources. Colocation specialists such as Equinix and Digital Realty exemplify multi-tenant infrastructure provision. These providers occupy a position enabling enterprises to deploy assets without significant upfront capital expenditure. They offer critical connectivity and physical security for diverse IT deployments.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud |
| Equinix |
| Digital Realty |
| Meta |
| NTT Global Data Centers |
| CyrusOne |
| QTS |
| Others |
Cost & Logistics Intelligence
Liquid cooling adoption, replacing traditional air cooling, simultaneously reshapes data center supply geography for specialized components and impacts pricing economics for high-density infrastructure. This technological shift encourages new vendor ecosystems focused on thermal management solutions.
Pricing Analysis
Customization-premium spread defines data center pricing, with bespoke colocation solutions commanding higher rates than standardized cloud capacity. Long-term contracts for colocation and consumption-based models for cloud services represent the dominant pricing structures. Geographic delivery costs and the volume scale of deployments drive significant price differentiation. Pricing pressure intensifies for basic capacity due to commoditization and power grid constraints in established hubs. Cloud Service Providers exhibit lower price sensitivity for strategic, high-performance capacity, while smaller enterprises prioritize cost for standard colocation.
Supply Chain Analysis
Lead times for specialized data center equipment, particularly advanced cooling systems and high-capacity power units, influence project timelines and costs. Geographic supply concentrates in China for server components and cooling hardware, Taiwan for advanced semiconductors, and the United States for specialized software and design. Raw material dependencies include rare earth elements for magnets in cooling pumps and specialized fluids for immersion cooling. Single-source vulnerability for specific chip architectures or advanced cooling components presents a structural supply chain risk. Distribution runs through direct sales channels for hyperscale operators and a network of channel partners for colocation and enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center market is undergoing high-growth disruption, driven by exponential AI workloads and stringent sustainability mandates like the EU's Corporate Sustainability Reporting Directive (CSRD).
For Market Incumbents:Shield existing market share by aggressively investing in advanced liquid cooling technologies to support high-density AI workloads. Acquire specialized engineering talent in sustainable facility design and operations to meet evolving regulatory benchmarks. Address the threat of commoditization by offering differentiated, high-performance computing solutions in established hubs like Northern Virginia. Leverage certification investments, such as ENERGY STAR, to attract ESG-conscious clients.
For New Entrants and Emerging Players:Specialized liquid cooling services for AI workloads represent a significant service-layer gap where incumbents currently under-serve. Target emerging secondary markets like Poland, which offer lower operational costs and fewer power grid constraints. Focus on enterprises with specific sustainability mandates, providing verifiable green solutions. Offer outcome-based contracts tied to measurable energy efficiency metrics as a compelling go-to-market angle.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with niche colocation providers focused on specific high-growth applications or sustainable facility operators. Data center infrastructure remains a critical asset class over the next five to ten years, offering stable, long-term returns. Identify acquisition targets that possess proprietary cooling technologies or established footprints in underserved secondary markets. Increased M&A activity for specialized cooling technology firms or regional edge data center providers represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Secondary Markets | Bypasses power and land constraints in primary hubs, diversifying geographic risk. |
| Liquid Cooling Technology Integration | Manages heat from high-performance computing, enabling higher rack densities for AI. |
| Green Certification Program Development | Attracts ESG-conscious clients and ensures compliance with sustainability mandates like CSRD. |
| Specialized Skills Training Initiatives | Addresses the shortage of qualified personnel in advanced cooling and sustainable facility management. |
| Flexible Consumption Model Adoption | Aligns with enterprise demand for cloud-like, pay-as-you-go infrastructure services. |
Research Approach
A standing panel of data center architects, hyperscale operations managers, colocation sales directors, and sustainability officers provided ongoing calibration for market sizing and forecasting. This primary research combined with extensive secondary validation from public data center operator SEC filings, government energy reports, and industry association publications. Bottom-up data collection from individual projects was triangulated with top-down validation against macroeconomic indicators.
Consistency checks against external benchmarks ensured the robustness of the quantitative model, which integrates historical trends and projected demand drivers across the analysis window. Segmentation dimensions modeled include deployment model, solution/offering, application, end user, and power density tier. Compound annual growth rates were derived from a detailed analysis of market dynamics, technological shifts, and anticipated infrastructure investments. Projected AI workload growth and new facility construction pipelines served as key forecast inputs.
Forecasts assume regulatory continuity in the EU, US, and China; material policy shifts would require re-modeling. Unforeseen power supply disruptions, rapid advancements in quantum computing, or geopolitical trade restrictions represent specific risk factors that could revise forecasts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Chile Data Center Networking Market