
 Global WAN Optimization Market | 2026-2036
Global WAN Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Global WAN Optimization Market Foresight
Enterprise buyer concentration is broadening as mid-market manufacturers and regional healthcare networks join traditional telecommunications and banking clients in deploying WAN optimization. Cisco Systems leverages extensive routing infrastructure to anchor large-scale hybrid deployments across multinational footprints. Riverbed Technology specializes in application-aware acceleration that sustains performance for latency-sensitive workloads. Aryaka Networks competes through cloud-native managed services that eliminate hardware dependency for distributed enterprises.
Wide Area Network optimization encompasses techniques and appliances that reduce bandwidth consumption, minimize latency, and improve application response across geographically dispersed locations through protocol acceleration, traffic prioritization, and intelligent caching at Layer 4 through Layer 7. Cloud-based deployment is capturing the fastest expansion as enterprises abandon capex-heavy hardware refresh cycles, while data deduplication technology dominates margin pools due to its compute efficiency and storage cost reduction. Disaster recovery applications are maturing into standard infrastructure, whereas virtual desktop infrastructure represents an emerging growth vector as remote work patterns persist.
The FCC governs interstate data transmission standards in the United States, while GDPR mandates cross-border data flow controls that shape European procurement specifications, and Japan's METI promotes digital infrastructure resilience through industrial connectivity guidelines. Regulatory fragmentation across these jurisdictions forces vendors to architect region-specific compliance modules rather than universal platforms. Stakeholders must evaluate whether sovereign cloud requirements in key markets will fragment product roadmaps or create first-mover advantages for vendors with pre-certified regional deployments.
Market Dynamics
Cloud migration is compressing hardware refresh cycles across enterprise networks, forcing vendors to pivot from appliance sales toward subscription-based service models that align with IT consumption patterns.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border data governance requirements in Europe are accelerating procurement of sovereign-certified WAN solutions that embed encryption and residency controls.
- Industrial IoT deployments:Manufacturing facilities in Germany are driving demand for deterministic latency guarantees to support real-time machine coordination across distributed plants.
- SD-WAN convergence:The integration of software-defined networking with optimization stacks is collapsing procurement decisions into single-vendor relationships.
Market Restraints
- Semiconductor supply concentration:Specialized packet-processing chips sourced from Taiwan create vulnerability in hardware appliance lead times.
- GDPR territorial enforcement:Fragmented interpretations of lawful data transfer mechanisms across EU member states complicate pan-European deployment architectures.
- Cloud-native substitution:Hyperscaler edge computing services are absorbing workloads previously routed through dedicated optimization infrastructure.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for electronics manufacturing are creating greenfield site demand for managed connectivity services.
- Healthcare network consolidation:HIPAA-covered entities merging into regional systems require unified compliance frameworks across previously siloed locations.
- AI inference at edge:The pairing of WAN optimization with GPU-equipped edge nodes opens latency-sensitive applications in autonomous systems.
Industry Challenges
- Legacy MPLS integration:Enterprises maintaining hybrid environments face protocol translation complexity during phased cloud transitions.
- Zero-trust certification timelines:FedRAMP and equivalent national security accreditations extend sales cycles for public-sector deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global WAN Optimization Market |
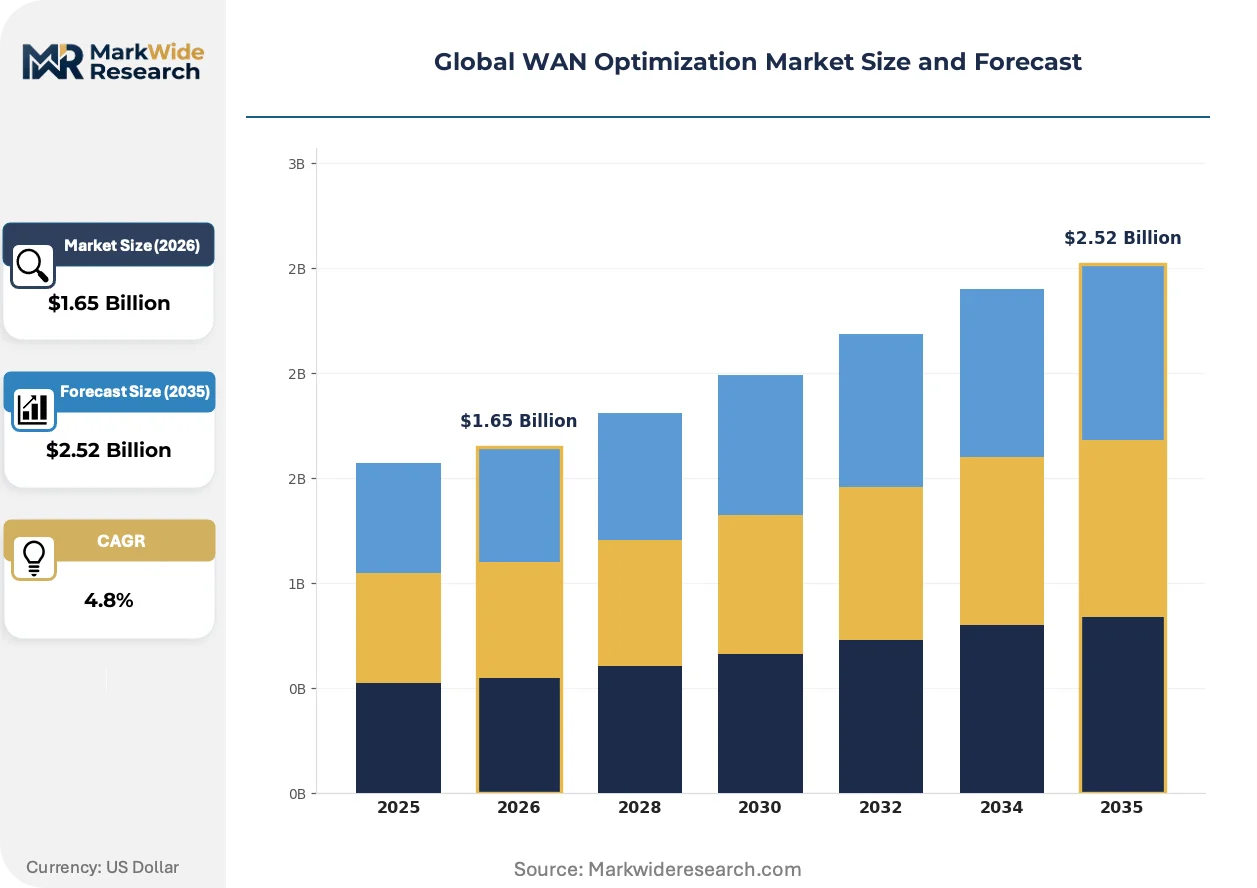
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Technology: Data Deduplication, Compression, Traffic Shaping, Protocol Optimization, Caching Application: Data Center Connectivity, Disaster Recovery, Virtual Desktop Infrastructure, Video Conferencing, Voice over IP, File Sharing End User: Telecommunications, Banking & Finance, Government Agencies, IT & Software, Education, Manufacturing |
| Companies Covered | Cisco Systems, Riverbed Technology, Citrix Systems, VMware, Fortinet, HPE, Aryaka Networks, F5 Networks, NTT Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global WAN Optimization Market Shifts & Advancements
Artificial intelligence is embedding into traffic management systems, enabling predictive path selection that anticipates congestion before application performance degrades.
Application-aware traffic classification is consolidating multiple point solutions into unified platforms that handle compression, deduplication, and protocol acceleration through common policy engines. Financial services firms in London and Singapore are deploying these stacks to collapse vendor management overhead. The technology is consolidating procurement authority into infrastructure teams previously fragmented across network and application silos.
The EU AI Act's risk-based classification system is mandating audit trails for automated decision-making in network routing. Vendors must now document how AI-driven path selection meets transparency requirements. German automotive manufacturers with connected vehicle platforms are requiring these attestations in procurement specifications.
Subscription consumption models are displacing perpetual licensing for hardware appliances, compressing upfront capital requirements into operational expenditure streams. Mid-market enterprises in Brazil and South Korea are adopting managed service wrappers that bundle optimization with SD-WAN and security. This shift is most visible in healthcare networks where capital constraints intersect with cloud migration urgency.
Global WAN Optimization Market Segmentation
WAN optimization vendors architect product portfolios around four intersecting dimensions that determine procurement specifications. Deployment mode dictates capital structure and operational control. Technology selection governs performance characteristics and hardware requirements. Application targeting shapes latency tolerances and throughput needs. End-user verticals impose compliance and reliability standards that filter vendor eligibility.
Deployment:
Cloud-native architectures are displacing appliance-centric delivery models as enterprises restructure network expenditure from capital to operational categories.
- On-Premises:Physical appliances deployed at enterprise edge locations process traffic through dedicated hardware with deterministic performance. Banking networks in Switzerland and government facilities in Germany maintain these deployments for air-gapped security requirements and sub-millisecond latency guarantees.
- Cloud-Based:Virtualized optimization functions delivered through hyperscaler marketplaces eliminate hardware refresh cycles and scale consumption with actual traffic volumes. Financial services firms in Singapore and healthcare networks in the United States are migrating here to align network spending with cloud migration timelines.
- Hybrid:Split traffic processing between local appliances and cloud gateways accommodates phased cloud transitions without forklift upgrades. Manufacturing conglomerates with distributed plants across Germany and Poland deploy this architecture to preserve existing MPLS investments while enabling SaaS acceleration.
- Hosted:Single-tenant optimization infrastructure operated by service providers in carrier-neutral facilities delivers dedicated capacity without on-site hardware management. Regional healthcare systems in France and mid-market manufacturers in Italy select this model to access enterprise-grade features without internal specialist staffing.
- Managed:Fully outsourced network optimization bundled with monitoring, support, and capacity planning transfers operational risk to vendor or service provider. Telecommunications operators in Brazil and education networks in South Korea are standardizing procurement on these comprehensive service wrappers.
Established deployment concentrates with on-premises appliances in regulated verticals. Cloud-based and managed services are climbing the fastest as mid-market enterprises prioritize agility over control.
Technology:
Compression ratios and computational efficiency separate margin performance across the technology stack, with deduplication commanding premium positioning due to storage cost reduction.
- Data Deduplication:Elimination of redundant data blocks before transmission slashes bandwidth consumption for backup and replication workloads. Disaster recovery applications across financial services in London and healthcare systems in Toronto rely on this technology to meet recovery point objectives without circuit overprovisioning.
- Compression:Algorithmic reduction of payload size through lossless encoding maximizes throughput on constrained links. Remote oil and gas facilities in Norway and mining operations in Australia deploy compression-heavy stacks where satellite bandwidth costs dominate total cost of ownership.
- Traffic Shaping:Prioritization and rate-limiting policies enforce quality-of-service hierarchies that protect latency-sensitive applications from bulk data transfers. Voice over IP deployments in call centers across India and the Philippines depend on this capability to maintain mean opinion score thresholds during peak hours.
- Protocol Optimization:TCP window scaling, connection pooling, and transaction bundling overcome protocol inefficiencies across high-latency paths. Video conferencing platforms serving distributed teams in Japan and Australia leverage these techniques to sustain interactive performance across transpacific routes.
- Caching:Local storage of frequently accessed content reduces round-trips to origin servers and accelerates application response. Education networks with concentrated user bases in South Korea and corporate campuses in the United States deploy edge caching to optimize SaaS application delivery.
Protocol optimization and caching represent mature, widely deployed capabilities. Data deduplication is gaining share fastest as backup modernization and ransomware recovery requirements intensify.
Application:
Latency tolerance thresholds and throughput burst patterns segment application requirements into distinct procurement categories with incompatible technical specifications.
- Data Center Connectivity:High-capacity, low-latency interconnection between primary and secondary facilities supports active-active application architectures. Financial exchanges in Chicago and Frankfurt require deterministic performance for this use case.
- Disaster Recovery:Asynchronous replication with compression and deduplication enables recovery point objectives measured in minutes rather than hours. Healthcare networks subject to HIPAA in the United States prioritize this application.
- Virtual Desktop Infrastructure:Display protocol optimization and intelligent caching deliver responsive remote desktop experiences across variable network conditions. Government agencies in the United Kingdom and Australia expanded deployment following remote work mandates.
- Video Conferencing:UDP optimization and packet loss concealment sustain real-time video quality across congested or lossy paths. Corporate headquarters in Japan and regional offices in Brazil represent concentrated demand.
- Voice over IP:Jitter buffering, echo cancellation, and priority queuing protect call quality from network variability. Business process outsourcing operations in India and the Philippines drive volume here.
- File Sharing:Delta synchronization and block-level deduplication accelerate collaborative document workflows across distributed teams. Professional services firms in Germany and technology companies in Israel deploy these capabilities.
Disaster recovery and data center connectivity constitute established, high-volume applications. Virtual desktop infrastructure is expanding most quickly as hybrid work patterns persist and GPU-accelerated remote workstations proliferate.
End User:
Compliance certification requirements and network scale economies create distinct vendor qualification barriers across vertical segments.
- Telecommunications:Carrier-grade reliability and massive scale distinguish requirements, with operators integrating optimization into managed service portfolios. Tier-1 providers in Germany and Japan maintain in-house development for this segment.
- Banking & Finance:Regulatory scrutiny over data residency and transaction integrity mandates encryption and audit capabilities. Institutions in Switzerland and Singapore impose the strictest procurement specifications.
- Government Agencies:National security accreditations and sovereign cloud mandates limit vendor eligibility to domestic or pre-cleared providers. Defense and civilian agencies in the United States, United Kingdom, and Australia operate separate procurement frameworks.
- IT & Software:Agile deployment and API-driven automation prioritize cloud-native delivery and DevOps integration. Technology companies in Israel and Estonia concentrate demand for these characteristics.
- Education:Capital constraints and seasonal usage patterns favor subscription consumption and managed service bundles. University systems in Canada and Australia are consolidating procurement across previously autonomous campuses.
- Manufacturing:Industrial IoT latency requirements and operational technology security boundaries demand edge-deployed optimization with deterministic performance. Automotive and machinery producers in Germany drive the most demanding specifications.
Telecommunications and banking represent mature, high-value verticals with entrenched vendor relationships. Manufacturing is gaining share fastest as Industry 4.0 digitization and connected vehicle platforms multiply connected endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Taiwan feeds specialized packet-processing chips that underpin hardware appliance supply chains for WAN optimization vendors worldwide.
United States
Financial services firms in New York and Chicago drive cloud migration projects requiring low-latency connectivity between primary and disaster recovery sites. HIPAA governs healthcare network procurement specifications, mandating encryption and audit capabilities for covered entities consolidating regional systems. The Dallas-Fort Worth metroplex hosts major data center clusters where hybrid deployment architectures predominate.
Germany
Automotive manufacturers in Stuttgart and Munich require deterministic latency guarantees for real-time machine coordination across distributed plants. The EU AI Act mandates audit trails for automated network routing decisions, forcing vendors to document transparency compliance. Industrial digitization in Bavaria and North Rhine-Westphalia concentrates enterprise investment in secure connectivity solutions.
Japan
METI industrial connectivity guidelines promote digital infrastructure resilience across manufacturing supply chains. Video conferencing platforms serving Tokyo-Osaka corridors leverage protocol optimization to sustain interactive performance. The Kanto region anchors demand for managed services bundling optimization with SD-WAN and security.
Singapore
Banking institutions impose strictest procurement specifications for data residency and transaction integrity across ASEAN operations. Financial services firms migrate to cloud-based deployment to align network spending with digital transformation timelines. The city-state's carrier-neutral facilities host single-tenant optimization infrastructure for regional headquarters.
Brazil
Telecommunications operators standardize procurement on comprehensive managed service wrappers transferring operational risk to vendors. Capital constraints among mid-market enterprises in São Paulo favor subscription consumption models over perpetual licensing. The PLI scheme for electronics manufacturing creates greenfield site demand for managed connectivity services.
Global WAN Optimization Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery and AI-embedded traffic management. The vendor base spans networking incumbents with routing infrastructure, specialists in application-aware acceleration, and managed service providers eliminating hardware dependency. Three archetypes dominate: infrastructure-anchored platforms, software-defined optimization stacks, and subscription-based service wrappers. Consolidation pressures favor single-vendor relationships as SD-WAN convergence collapses procurement decisions, while technology licensing partnerships accelerate feature parity across tiers.
Within the infrastructure-anchored tier, Cisco Systems occupies a position exemplifying extensive routing infrastructure deployment across multinational footprints. Riverbed Technology and Aryaka Networks represent contrasting specialization vectors—one in application-aware acceleration for latency-sensitive workloads, the other in cloud-native managed services for distributed enterprises. These three anchors illustrate the competitive spectrum from hardware-centric delivery to fully outsourced operational models.
| Leading Market Players |
|---|
| Cisco Systems |
| Riverbed Technology |
| Citrix Systems |
| VMware |
| Fortinet |
| HPE |
| Aryaka Networks |
| F5 Networks |
| NTT Communications |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists consolidating mid-market WAN optimization vendors impose pricing discipline through centralized procurement of packet-processing silicon while extracting margin via subscription-model conversions. This ownership pattern concentrates supply negotiations with Taiwan-based semiconductor foundries and feeds through to tiered service pricing across enterprise segments.
Pricing Analysis
Volume concentrates in cloud-native subscription tiers while margins pool in data deduplication technology and managed service bundles. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified deployments for government agencies from mid-market SaaS wrappers and basic compression appliances. Cost compression in hardware-dependent tiers is intensifying because hyperscaler edge computing services absorb workloads previously routed through dedicated infrastructure. Healthcare networks with capital constraints exhibit highest price sensitivity; Swiss banking networks with air-gapped security requirements show lowest.
Supply Chain Analysis
Specialized packet-processing chips rest on Taiwan, South Korea, and United States fabrication capacity, with advanced node production concentrated at TSMC and Samsung foundries. Hardware appliance assembly draws from China, Mexico, and Malaysia for chassis, power supplies, and memory modules. Single-source vulnerability in Taiwan wafer supply creates lead time exposure for vendors maintaining on-premises appliance portfolios. Distribution runs through hyperscaler marketplaces for cloud-native delivery and carrier-neutral facilities for hosted deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native managed services are displacing hardware-centric delivery models across enterprise procurement, with SD-WAN convergence collapsing vendor relationships into single-stack decisions.
For Market Incumbents: Extend routing infrastructure dominance into unified optimization-SD-WAN platforms to counter cloud-native substitution from Aryaka Networks and emerging service providers. Invest in FedRAMP and EU AI Act compliance certification to defend public-sector and European automotive accounts. Deepen backward integration into packet-processing silicon allocation agreements with Taiwan foundries. For New Entrants and Emerging Players: Launch via managed service wrappers targeting mid-market manufacturers in India's PLI scheme corridors and regional healthcare networks consolidating under HIPAA compliance mandates. White-space concentrates in AI-embedded traffic management for autonomous vehicle platforms and GPU-equipped edge inference nodes. Lead with outcome-based pricing tied to latency SLA guarantees rather than capacity-based subscriptions. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with pre-certified regional deployments in Germany and Singapore where sovereign cloud requirements fragment procurement. Long-term viability hinges on subscription revenue durability and hyperscaler marketplace presence. Monitor hyperscaler edge computing capex disclosures as inflection signal for dedicated optimization infrastructure displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SD-WAN convergence collapses procurement into single-vendor relationships at Deutsche Telekom and NTT. |
| Acquisition of Specialist Firm | AI traffic management capabilities from Israeli startups address EU AI Act audit trail mandates. |
| Geographic Expansion | India PLI scheme electronics manufacturing corridors create greenfield managed connectivity demand. |
| Strategic Partnership | Hyperscaler marketplace listings align network spending with cloud migration timelines at Singapore banks. |
| Product Launch | GPU-equipped edge nodes paired with optimization open latency-sensitive autonomous systems applications. |
Research Methodology
Independent corroboration across network infrastructure executives, cloud procurement officers, and regulatory compliance leads underwrites the qualitative findings in this study. Primary fieldwork with SD-WAN integration specialists, carrier service managers, and industrial IoT architects combines with secondary validation from FCC filings, METI industrial connectivity guidelines, GDPR enforcement actions, and hyperscaler capex disclosures. Bottom-up sizing of deployment mode segments triangulates against top-down enterprise IT expenditure benchmarks.
Rate-of-change decomposition separates volume effects from mix-shift and pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment architecture, optimization technology, target application latency tolerance, and vertical compliance requirements. CAGRs derive from fitted growth curves anchored to disclosed enterprise network refresh cycles and cloud migration timelines. Industry-specific inputs encompass semiconductor lead time indices and sovereign cloud certification pipeline status.
Semiconductor supply disruption, EU AI Act territorial enforcement fragmentation, and hyperscaler edge computing absorption are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding enterprise cloud migration velocity and regulatory certification timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Global Network Configuration and Change Management Market