
 Global Managed SD-WAN Service Market | 2026-2036
Global Managed SD-WAN Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed SD-WAN Service Market Outlook
Market Context
The certified SD-WAN engineering workforce is reorganizing around cloud-native specializations, creating bottlenecks for providers scaling multi-tenant platforms. Cisco Systems leverages its routing heritage to dominate enterprise migration from legacy MPLS. Palo Alto Networks differentiates through integrated SASE architectures that collapse networking and security procurement. Fortinet anchors mid-market expansion with bundled firewall-SD-WAN appliances and aggressive channel economics.
Technical Definition and Segment Structure
Managed SD-WAN service denotes a third-party-operated wide-area networking solution that abstracts transport independence across MPLS, broadband, and LTE links through centralized policy controllers, typically delivering sub-50ms failover and application-aware path selection. The primary commercial purpose replaces static branch routing with dynamic, software-defined traffic engineering that reduces dedicated circuit spend while improving SaaS performance. Deployment model segmentation reveals hybrid cloud configurations capturing the dominant margin pool as enterprises straddle private data centers with Azure and AWS workloads. End-user segmentation shows large enterprises sustaining the revenue base while SMEs represent the fastest expansion vector as managed service providers package standardized templates. Technology segmentation positions VNF-based implementations as the growth frontier displacing hardware-centric SDN deployments in greenfield sites.
Regulatory Framework
The FCC governs transport-layer competition and interconnection obligations affecting last-mile diversity options available to managed SD-WAN providers in the United States. GDPR enforcement across European Union member states shapes data residency requirements that constrain controller placement and cross-border failover architectures. NIS2 directives mandate incident reporting timelines that force managed service providers to embed automated telemetry and sovereign Security Operations Center presence. Stakeholders must monitor how fragmented national encryption standards affect template standardization across multi-country deployments.
Market Dynamics
The transition from hardware-centric branch routers to cloud-native orchestration platforms is compressing deployment timelines and forcing managed service providers to restructure engineering workflows around Kubernetes-based controller architectures.
Growth Catalysts
- CISA Zero-Trust Mandates:Federal agencies and defense contractors in the United States must encrypt all WAN traffic by 2027, accelerating demand for managed SD-WAN with integrated SSE stacks.
- Industrie 4.0 Automation:German automotive and precision manufacturing facilities require deterministic sub-10ms latency for robotic coordination, pulling managed SD-WAN into brownfield OT environments.
- Telemedicine Expansion:Healthcare networks across the United States are extending SD-WAN footprints to secure remote patient monitoring and diagnostic imaging flows between clinics and cloud PACS archives.
Market Restraints
- Controller Hardware Concentration:Taiwan-based semiconductor foundries supply the majority of merchant silicon for SD-WAN CPE, creating geopolitical supply vulnerability.
- GDPR Data Residency Friction:European Union member states enforce divergent interpretations of cross-border controller placement, complicating multi-tenant platform standardization.
- MPLS Contract Lock-in:Enterprises face 3-5 year residual obligations with incumbent carriers, delaying full transport abstraction even where technical readiness exists.
Strategic Opportunities
- India Manufacturing Corridors:Tamil Nadu and Gujarat industrial zones are greenfield sites lacking legacy MPLS infrastructure, enabling pure cloud-native SD-WAN deployment without migration complexity.
- SASE Convergence:Managed service providers bundling SD-WAN with cloud-delivered security edge capture 40% higher ARPU than standalone networking contracts.
- NIS2 Compliance Services:The European Union's expanded incident reporting deadlines create attach revenue for automated telemetry and sovereign SOC integration.
Industry Challenges
- Cloud-Native Engineering Scarcity:Service providers struggle to recruit Kubernetes and Terraform specialists capable of managing multi-tenant controller farms.
- Legacy Router Integration:Brownfield enterprises require phased coexistence with existing Cisco and Juniper branch infrastructure, extending deployment timelines.
Report Scope
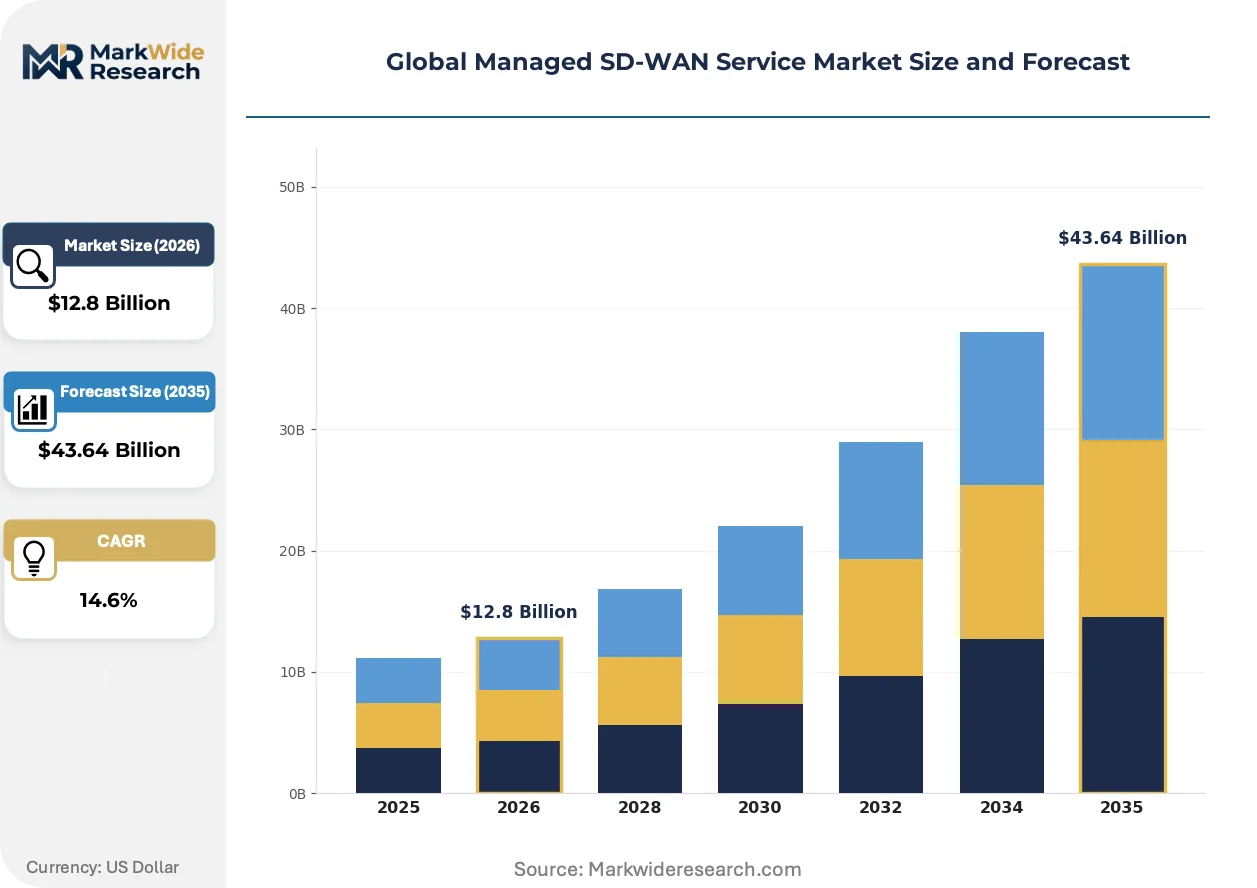
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed SD-WAN Service Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Dedicated, Managed, Co-Managed Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing End User: SMEs, Large Enterprises, Service Providers, Government Institutions Technology: VNF, SDN, MPLS, Internet-Based |
| Companies Covered | Aryaka, AT&T, Cisco Systems, Palo Alto Networks, Fortinet, VMware, Verizon Communications, Silver Peak Systems, Masergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed SD-WAN Service Market Strategic Shifts
Artificial intelligence is embedding into traffic engineering decisions, shifting WAN optimization from static policy rules toward real-time path prediction based on application telemetry and transport-layer analytics.
Intent-based networking is bifurcating the managed SD-WAN stack into declarative policy layers and autonomous enforcement engines. Large financial services institutions in Singapore and London are piloting natural language provisioning interfaces that compress change-window durations from days to minutes. This architectural shift is bifurcating vendor roadmaps between closed proprietary controllers and open API-first platforms.
The EU AI Act's risk classification framework is constraining how European managed service providers deploy automated traffic optimization. High-risk designations for critical infrastructure operators now require human-in-the-loop approval for path changes affecting healthcare and energy networks. German and French providers are responding by segmenting controller architectures into explainable decision modules and black-box optimization engines.
Enterprise procurement teams are unbundling managed SD-WAN from traditional managed security service contracts. Mid-market buyers in Australia and Canada now source networking and security from separate vendors, compressing standalone SD-WAN pricing and forcing providers to differentiate through vertical-specific SLA templates rather than bundled discounts.
Global Managed SD-WAN Service Market Segmentation
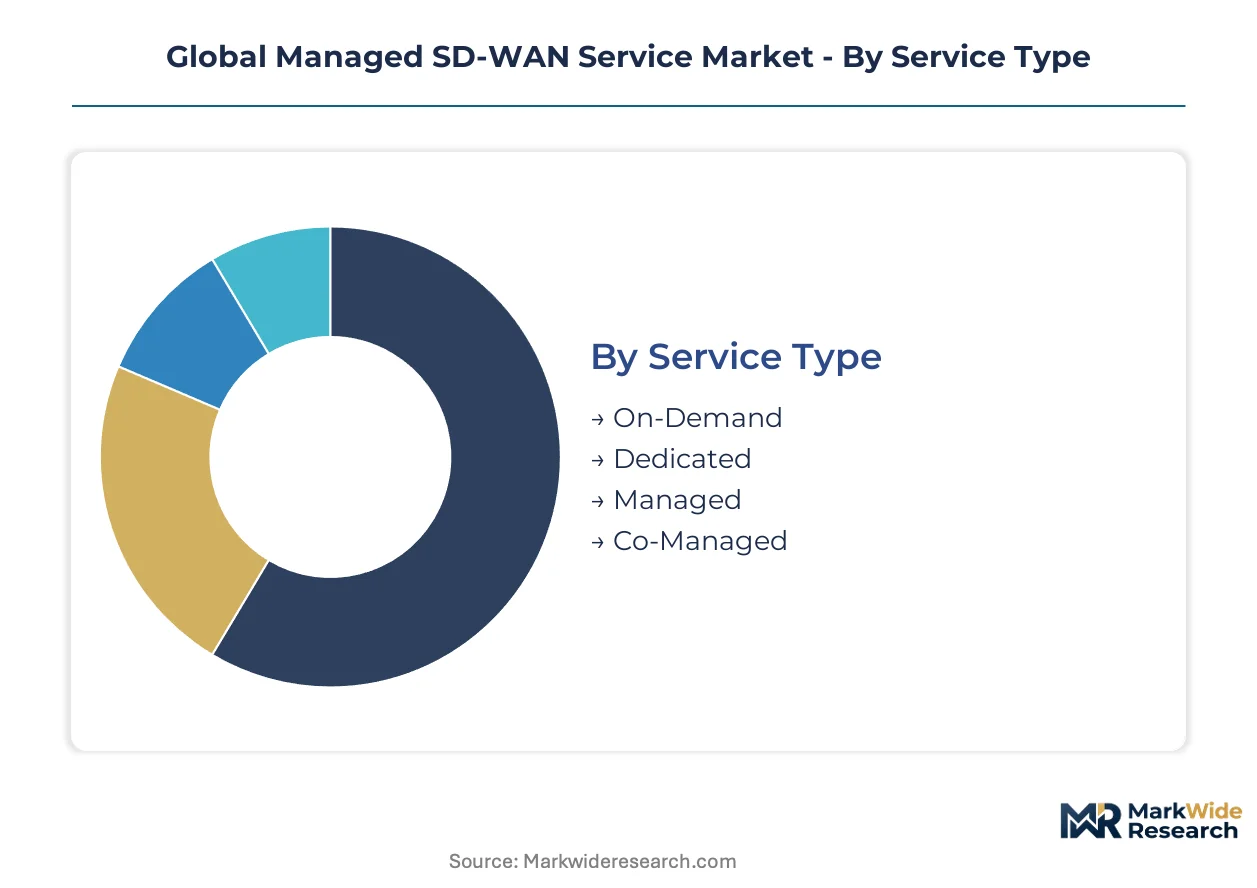
Managed SD-WAN service segmentation reveals how procurement patterns split between control-retention preferences and outsourcing appetite. Regulatory pressure on encryption and data residency is fragmenting deployment choices across verticals and geographies.
Service Type:
FCC net neutrality restoration and CISA zero-trust mandates are reshaping how organizations balance operational control against compliance outsourcing.
- On-Demand:Elastic consumption models provision bandwidth via API-driven orchestration, matching traffic spikes without long-term capacity planning. Healthcare networks in the United States deploy this for seasonal telemedicine surges, though HIPAA audit trails complicate pay-as-you-go telemetry retention.
- Dedicated:Reserved infrastructure with fixed SLAs guarantees throughput for latency-sensitive workloads. German automotive manufacturers operating Industrie 4.0 lines mandate dedicated circuits to meet sub-10ms robotic coordination requirements under factory safety regulations.
- Managed:Fully outsourced operations transfer CPE lifecycle, policy administration, and incident response to service providers. Full treatment: Third-party operation of controllers, edge devices, and transport abstraction removes internal Kubernetes expertise requirements. United States federal contractors facing CISA's 2027 encryption deadline favor managed services to accelerate SSE stack integration without building sovereign Security Operations Centers.
- Co-Managed:Shared operational responsibility allows enterprises to retain policy definition while outsourcing tier-1 support. This hybrid model appeals to mid-market financial services firms in Singapore seeking local control over routing logic with overnight coverage from offshore Network Operations Centers.
Managed handles the majority of throughput; On-Demand is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates commodity cloud consumption from sovereignty-premium private infrastructure.
- Public Cloud:Controller hosting on hyperscaler infrastructure minimizes capital expenditure and accelerates provisioning. Australian retail chains expanding into Southeast Asia leverage public cloud SD-WAN to avoid data center buildouts, though GDPR cross-border failover constraints limit European adoption.
- Private Cloud:Dedicated controller instances within enterprise-owned facilities satisfy data residency mandates. French healthcare providers deploy private cloud SD-WAN to keep patient diagnostic imaging within national borders under CNIL enforcement of GDPR health data provisions.
- Hybrid Cloud:Straddling private data centers with Azure and AWS workloads, this configuration dominates margin pools by combining legacy application hosting with cloud-native SaaS acceleration. Large United States enterprises with 3-5 year MPLS residual obligations use hybrid models to phase transport abstraction without wholesale rip-and-replace.
- Edge Computing:Distributed controller placement at branch or near-premise locations minimizes latency for real-time applications. Full treatment: Kubernetes-based microcontrollers deployed at factory floors or retail outlets process traffic engineering decisions locally. Japanese automotive suppliers in Nagoya industrial corridors deploy edge SD-WAN to coordinate just-in-time logistics with sub-50ms failover independent of centralized cloud connectivity.
Hybrid Cloud commands the largest revenue base; Edge Computing is climbing the fastest as OT networks converge with IT infrastructure.
End User:
Customer type determines SLA complexity and procurement cycle length.
- SMEs:Standardized templates and aggressive channel economics drive fastest expansion. United Kingdom mid-market manufacturers adopt templated SD-WAN through managed service provider bundles to avoid dedicated networking staff.
- Large Enterprises:Sustaining the revenue base through complex multi-site deployments with custom integration requirements. Full treatment: Global footprints with hundreds of branch locations demand bespoke policy hierarchies and phased coexistence with Cisco or Juniper legacy infrastructure. United States defense contractors subject to CISA mandates require large enterprise-grade managed SD-WAN with integrated SSE and sovereign SOC presence.
- Service Providers:Wholesale procurement for resale to downstream customers. Tier-2 telecommunications carriers in India source managed SD-WAN platforms to package connectivity-plus-orchestration for Tamil Nadu manufacturing corridors lacking legacy MPLS.
- Government Institutions:Sovereign security requirements and incident reporting mandates dominate procurement. Full treatment: Federal agencies and state-level entities enforce encrypted overlays, domestic controller placement, and automated telemetry for NIS2-equivalent compliance timelines. German federal ministries specify government-grade SD-WAN with explainable AI routing decisions under EU AI Act high-risk system designations for critical infrastructure.
Large Enterprises anchor current revenue; SMEs represent the steepest expansion trajectory as channel packaging matures.
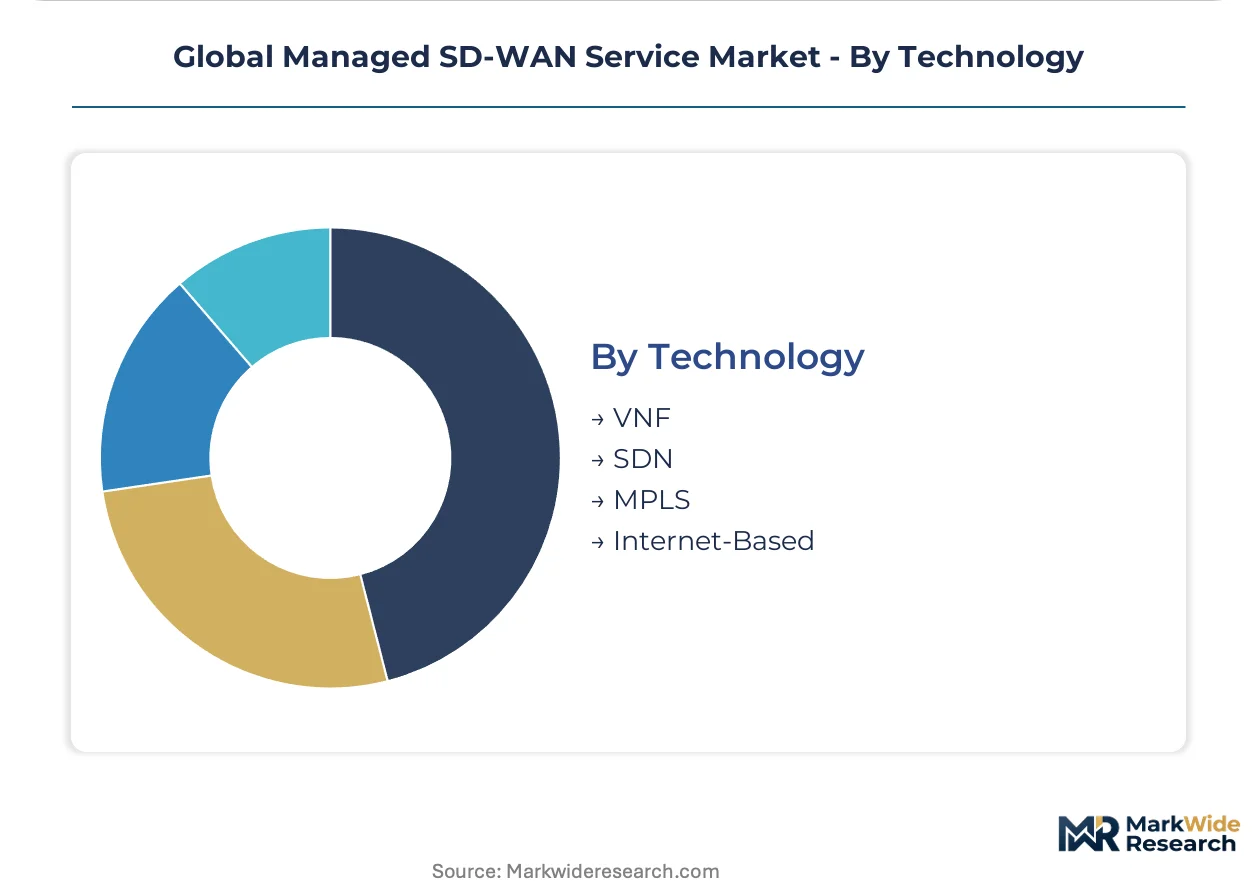
Technology:
Technology maturity curves separate growth-frontier virtualization from declining hardware-centric alternatives.
- VNF:Virtualized network functions running on commodity hardware displace purpose-built appliances. Full treatment: Software-defined CPE deployed on universal customer premises equipment enables rapid service chaining and controller updates without truck rolls. Greenfield industrial zones in Gujarat, India deploy pure VNF-based SD-WAN without migration complexity from legacy router estates.
- SDN:Software-defined networking architectures with centralized control planes abstract underlying transport. Full treatment: OpenFlow-based or proprietary controller implementations separate data and control planes for programmable traffic engineering. Early adopters in Netherlands logistics hubs utilize SDN overlays to dynamically route across multiple carrier backhauls based on real-time congestion metrics.
- MPLS:Legacy dedicated circuit technology persists through contractual lock-in and residual performance requirements. Swiss private banking networks maintain MPLS for guaranteed latency to trading co-location facilities despite SD-WAN cost advantages.
- Internet-Based:Broadband and LTE transport without dedicated private circuits. United States rural healthcare clinics leverage internet-based SD-WAN with encrypted overlays to reach cloud PACS archives where MPLS penetration remains economically unviable.
VNF handles the majority of new deployment throughput; Internet-Based is gaining share fastest as broadband reliability improves and encryption overhead diminishes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC net neutrality restoration and CISA zero-trust mandates anchor United States demand, while GDPR enforcement and NIS2 directives reshape European deployment architectures across Germany, France, and the United Kingdom.
United States
Healthcare networks secure telemedicine traffic and federal contractors accelerate SSE stack integration under CISA's 2027 encryption deadline. FCC interconnection obligations affect last-mile diversity options available to managed SD-WAN providers. Defense contractors in Northern Virginia and Texas aerospace corridors demand sovereign SOC presence with automated telemetry.
Germany
Industrie 4.0 factories prioritize deterministic sub-10ms latency for robotic coordination on automated production lines. NIS2 directives mandate incident reporting timelines forcing embedded telemetry and sovereign Security Operations Center presence. Automotive suppliers in Baden-Württemberg and Bavaria deploy edge SD-WAN for just-in-time logistics coordination.
United Kingdom
Mid-market manufacturers adopt templated SD-WAN through managed service provider bundles to avoid dedicated networking staff. GDPR health data provisions enforced by the Information Commissioner's Office constrain cross-border controller placement. London financial services firms pilot natural language provisioning interfaces compressing change-window durations.
India
Tamil Nadu and Gujarat industrial zones present greenfield sites lacking legacy MPLS infrastructure, enabling pure cloud-native deployment. TRAI regulations shape transport-layer competition affecting broadband and LTE link aggregation strategies. Tier-2 telecommunications carriers package connectivity-plus-orchestration for manufacturing corridors without migration complexity.
France
Healthcare providers deploy private cloud SD-WAN to keep patient diagnostic imaging within national borders under CNIL enforcement. EU AI Act risk classification constrains automated traffic optimization requiring human-in-the-loop approval for critical infrastructure. Paris-based financial institutions segment controller architectures into explainable decision modules.
Global Managed SD-WAN Service Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with routing heritage vendors and security-first platforms commanding premium positioning against mid-market appliance bundlers. The vendor landscape organizes around three strategic archetypes: networking incumbents leveraging installed base migration, converged SASE platforms collapsing procurement categories, and channel-centric specialists targeting standardized SME templates. Competitive intensity manifests through M&A activity absorbing point-solution vendors and strategic partnerships embedding security stacks into networking contracts.
Within the integrated leader tier, Cisco Systems represents the routing heritage archetype anchoring enterprise migration from legacy MPLS, while Palo Alto Networks exemplifies the converged SASE platform approach that collapses networking and security procurement decisions. Fortinet occupies the mid-market expansion vector with bundled firewall-SD-WAN appliances and aggressive channel economics.
| Leading Market Players |
|---|
| Aryaka |
| AT&T |
| Cisco Systems |
| Palo Alto Networks |
| Fortinet |
| VMware |
| Verizon Communications |
| Silver Peak Systems |
| Masergy |
| Others |
Value Chain & Pricing Dynamics
Merchant silicon substitution for custom ASICs in SD-WAN customer premises equipment simultaneously redistributes manufacturing toward Taiwan and South Korea while compressing hardware margins and elevating software licensing premiums in managed service contracts.
Pricing Analysis
Geographic price spreads between North American and European managed SD-WAN deployments reflect divergent regulatory compliance burdens. Pricing stratifies across premium sovereign-cloud tiers, standard multi-tenant configurations, and economy internet-overlay packages, with GDPR data residency requirements and CISA encryption mandates driving premium tier differentiation. Cost compression in economy segments intensifies as broadband reliability improvements reduce MPLS dependency. Mid-market enterprises exhibit highest price sensitivity, while United States federal contractors facing compliance deadlines accept premium pricing for integrated SSE stacks.
Supply Chain Analysis
Inventory strategy preferences in the SD-WAN hardware layer favor just-in-time provisioning for standardized CPE, though strategic stockpiling of merchant silicon persists among Taiwanese foundries amid geopolitical contingency planning. Supply concentrates in Taiwan for semiconductor fabrication, China for printed circuit board assembly, and Mexico for final integration serving North American deployments. Component dependencies include merchant silicon from Broadcom and Marvell, memory modules from South Korean suppliers, and power management ICs. Single-source vulnerability around advanced node semiconductor access represents the dominant structural risk. Distribution runs through tier-1 managed service providers and systems integrators rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from cloud-native networking stacks that bypass traditional managed service provider orchestration entirely, threatening the controller-based abstraction layer that underpins current revenue models.
For Market Incumbents: Consolidate cloud-native engineering capabilities through targeted acquisition of Kubernetes-specialist firms to address the talent scarcity constraining multi-tenant platform scaling. Deepen backward integration into sovereign Security Operations Center infrastructure to capture NIS2 compliance attach revenue and defend margin position against pure-play security vendors encroaching on networking contracts.
For New Entrants and Emerging Players: Anchor in India's Tamil Nadu and Gujarat manufacturing corridors where greenfield industrial sites lack legacy MPLS infrastructure and procurement cycles favor standardized templates over custom integration. Target tier-2 telecommunications carriers seeking white-label SD-WAN platforms for resale to mid-market manufacturing clients, leveraging API-first architectures to bypass incumbent channel lock-in.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converged SASE platforms with demonstrated SSE integration over standalone networking specialists. Long-term viability hinges on recurring revenue depth rather than hardware shipment volumes. Acquisition target archetypes include regional managed service providers with sovereign SOC presence and vertical-specific SLA expertise. The signal to watch is federal contractor procurement shifting from pilot deployments to multi-year managed service commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| SASE Platform Integration | Cisco and Palo Alto capture 40% higher ARPU by collapsing networking and security procurement decisions. |
| Sovereign SOC Buildout | European providers embed automated telemetry to satisfy NIS2 incident reporting timelines for German federal clients. |
| Edge Computing Deployment | Japanese automotive suppliers in Nagoya coordinate just-in-time logistics with sub-50ms failover independent of cloud connectivity. |
| Channel Partner Expansion | Fortinet's aggressive channel economics drive mid-market penetration through standardized SME template bundles. |
| AI-Driven Traffic Optimization | German providers segment controllers into explainable decision modules to comply with EU AI Act high-risk system designations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with managed service provider engineering directors, enterprise IT procurement officers, channel partner principals, and telecommunications carrier product managers; and secondary validation against FCC regulatory filings, CISA security directive documentation, EU NIS2 implementation guidance, and hyperscaler SD-WAN partnership announcements. Bottom-up triangulation across deployment model segmentation and top-down reconciliation against service provider revenue disclosures anchored volume estimates.
Across the projection horizon, the analytical framework modeled deployment model configurations, end-user organization scale, technology implementation type, and geographic regulatory cluster to generate segment-level trajectories. CAGRs were derived from elasticity-adjusted adoption curves incorporating MPLS contract expiration schedules, broadband quality improvements, and compliance mandate enforcement timelines. Industry-specific inputs included CISA's encryption deadline acceleration effects and Industrie 4.0 latency requirements for German manufacturing automation.
Decision-makers should treat outputs as directional under assumptions of sustained broadband reliability improvements and stable geopolitical access to merchant silicon; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for severe supply disruption or regulatory timeline acceleration. Revision becomes warranted when federal procurement velocity or foundry capacity allocation crosses thresholds that alter adoption elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Global Data Warehouse Market