
 North America Data Center Cooling Market | 2026-2036
North America Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Cooling Market Foresight
High-density liquid cooling specifications are redrawing competitive boundaries in North America. Vertiv Group Corp leverages its integrated power and thermal platform to anchor large hyperscale deployments across the United States. Schneider Electric sustains technology leadership through precision cooling systems purpose-built for artificial intelligence workloads. Asetek specializes in direct-to-chip liquid cooling and dominates high-performance computing installations where air cooling fails.
Data center cooling encompasses the engineered systems that extract waste heat from information technology equipment to maintain operational temperatures within specified thermal envelopes, typically 18°C to 27°C per ASHRAE guidelines, using refrigerants, chilled water, or dielectric fluids as heat transfer media. Liquid cooling solutions now lead growth as rack power densities surpass 30 kW, while air cooling remains mature in legacy facilities with lower density requirements. Among end users, cloud service providers represent the fastest-expanding segment as they build dedicated AI training clusters, whereas colocation providers occupy established margin pools through long-term service contracts.
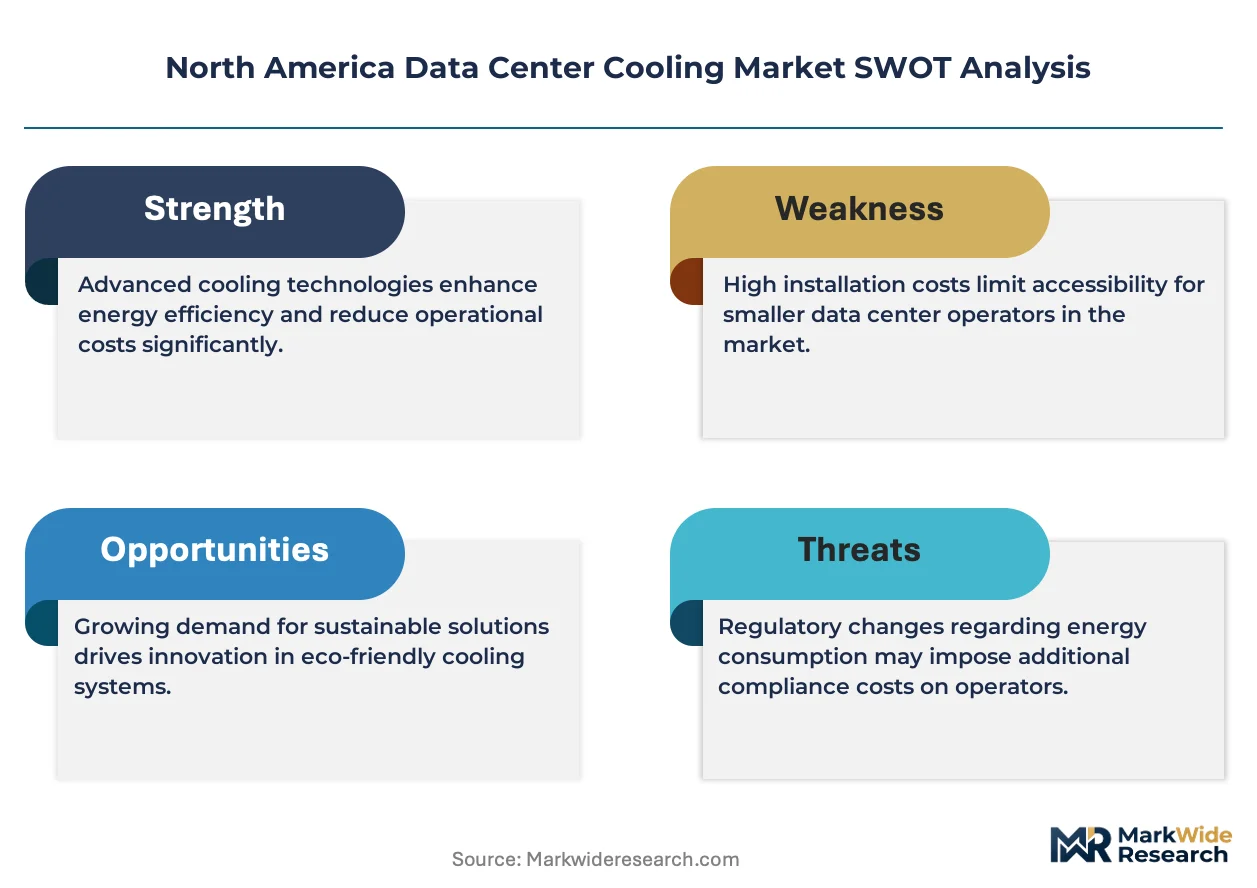
The U.S. Environmental Protection Agency's ENERGY STAR program and the Department of Energy's Better Buildings Challenge shape product efficiency benchmarks, while California's Title 24 building standards and emerging state-level clean energy mandates restrict refrigerant choices and drive adoption of low-global-warming-potential alternatives. Stakeholders must monitor evolving ASHRAE thermal guidelines and state-specific carbon disclosure rules to align capital planning with compliance timelines.
Market Dynamics
Rack power densities exceeding 50 kW in Northern Virginia are forcing wholesale architectural redesigns across the region's data center corridor, compressing legacy air-cooling economics and accelerating liquid-cooling deployment timelines.
Growth Catalysts
- AI Training Clusters:Hyperscale cloud service providers are building dedicated facilities for generative AI workloads, mandating direct-to-chip liquid cooling architectures that extract heat more efficiently than traditional methods.
- California Title 24:The state's building energy efficiency standards now impose strict thermal performance requirements on new data center construction, driving adoption of advanced cooling technologies that reduce energy consumption intensity.
- Department of Energy Mandates:Federal efficiency benchmarks under the Better Buildings Challenge are tightening thermal design specifications, compelling operators to retrofit legacy facilities with higher-performance cooling infrastructure.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger and piping fabrication depends on base metal inputs whose price swings compress equipment margins and complicate long-term contract pricing.
- Specialized Contractor Concentration:Installation of immersion and direct liquid cooling systems requires certified technicians concentrated in Texas, California, and Virginia, creating regional bottlenecks.
- Refrigerant Phase-Down:The EPA's phased reduction of hydrofluorocarbon availability under the AIM Act is restricting choices for facilities still dependent on vapor-compression cooling.
Strategic Opportunities
- Canada Hydroelectric Zones:Quebec and Ontario offer carbon-neutral power with ambient cooling advantages, attracting hyperscale builds that need thermal systems optimized for lower wet-bulb temperatures.
- Waste Heat Recovery:District heating integration in Minneapolis-St. Paul and Toronto allows data centers to monetize thermal output, requiring cooling architectures designed for heat extraction rather than rejection.
- State Clean Energy Mandates:New York's CLCPA and Illinois' CEJA create regulatory tailwinds for cooling technologies that demonstrate measurable carbon intensity reductions in utility interconnection agreements.
Industry Challenges
- Thermal-Fluid Chemistry Expertise:Dielectric fluid selection and maintenance protocols require specialized knowledge scarce among traditional HVAC technicians, forcing operators to build in-house training programs.
- ASHRAE Guideline Alignment:Evolving thermal envelope recommendations for IT equipment create compliance uncertainty during multi-year facility design cycles, risking specification obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Cooling Market |
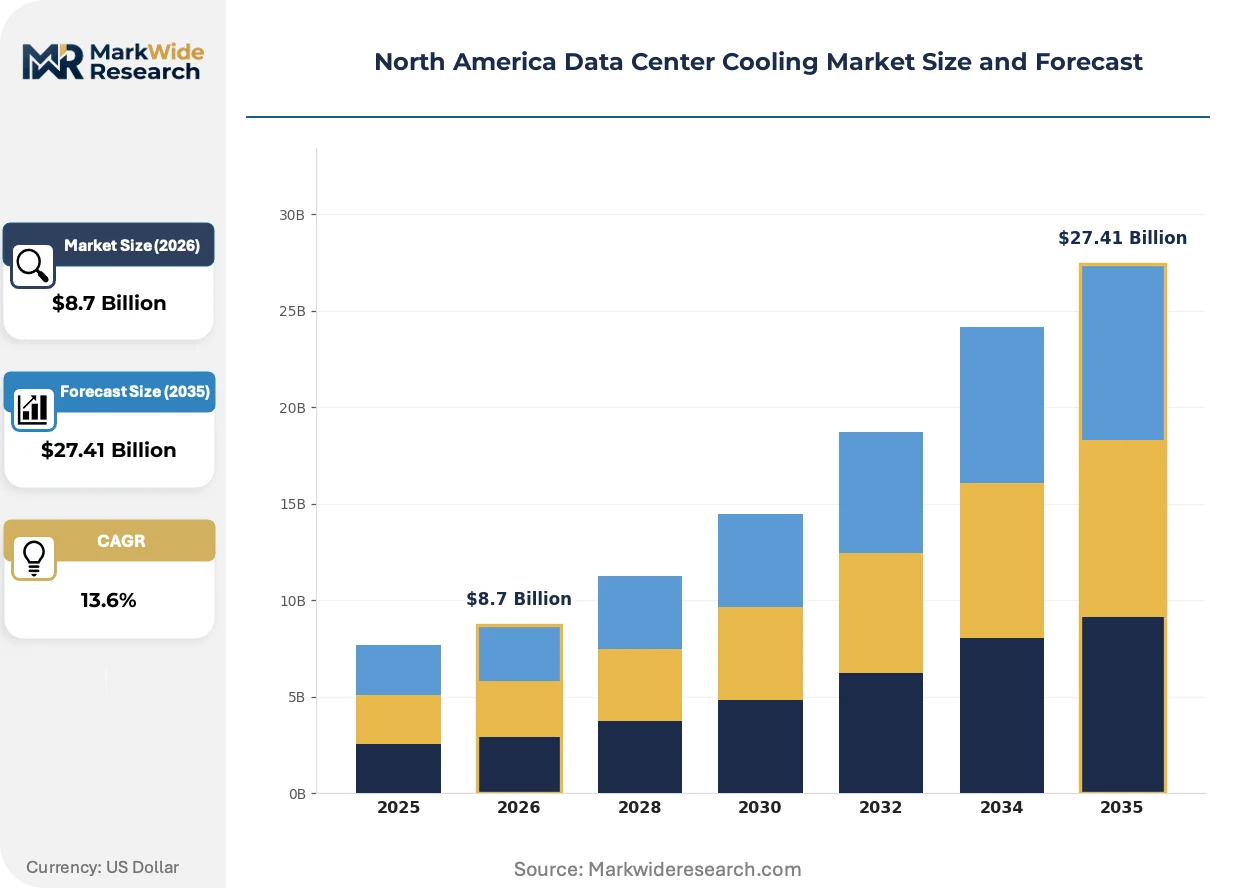
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Immersion Cooling, Thermoelectric Cooling End User: IT Companies, Telecommunications, Cloud Service Providers, Colocation Providers Technology: Chilled Beams, CRAC Units, CDU Systems, Heat Exchangers Configuration: Modular, Rack-Mounted, Centralized, Distributed |
| Companies Covered | Vertiv Group Corp, Schneider Electric, STULZ GmbH, Johnson Controls, Rittal GmbH & Co. KG, Asetek, Nortek Air Solutions, Daikin Industries, Ltd., Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Cooling Market Shifts & Advancements
Liquid-cooling architectures are fragmenting into multiple competing approaches as rack densities diverge across deployment types, with each hyperscale operator pursuing proprietary thermal designs that resist standardization.
Direct-to-chip cold plates are fragmenting the high-performance computing segment as cloud providers deploy customized solutions for GPU-intensive training clusters. Meta and Microsoft are scaling these systems fastest, with adoption curves compressing from pilot to production in under eighteen months. Vendor consolidation around integrated power-and-thermal platforms is fragmenting historically separate procurement categories.
The EPA's phasedown of hydrofluorocarbons under the AIM Act is restricting refrigerant availability for legacy chiller replacements. Equipment manufacturers are accelerating development of low-global-warming-potential alternatives including hydrofluoroolefins and natural refrigerants. Colocation providers in California and New York face the tightest compliance timelines, with some operators advancing replacement schedules to secure supply.
Buying committees are consolidating vendor relationships around full-stack thermal infrastructure rather than discrete component sourcing. Systems integrators and OEMs with captive cooling portfolios are displacing pure-play cooling specialists in hyperscale procurement cycles. This pattern concentrates most visibly in Northern Virginia, where power purchase agreements now bundle thermal performance guarantees with electricity supply contracts.
North America Data Center Cooling Market Segmentation
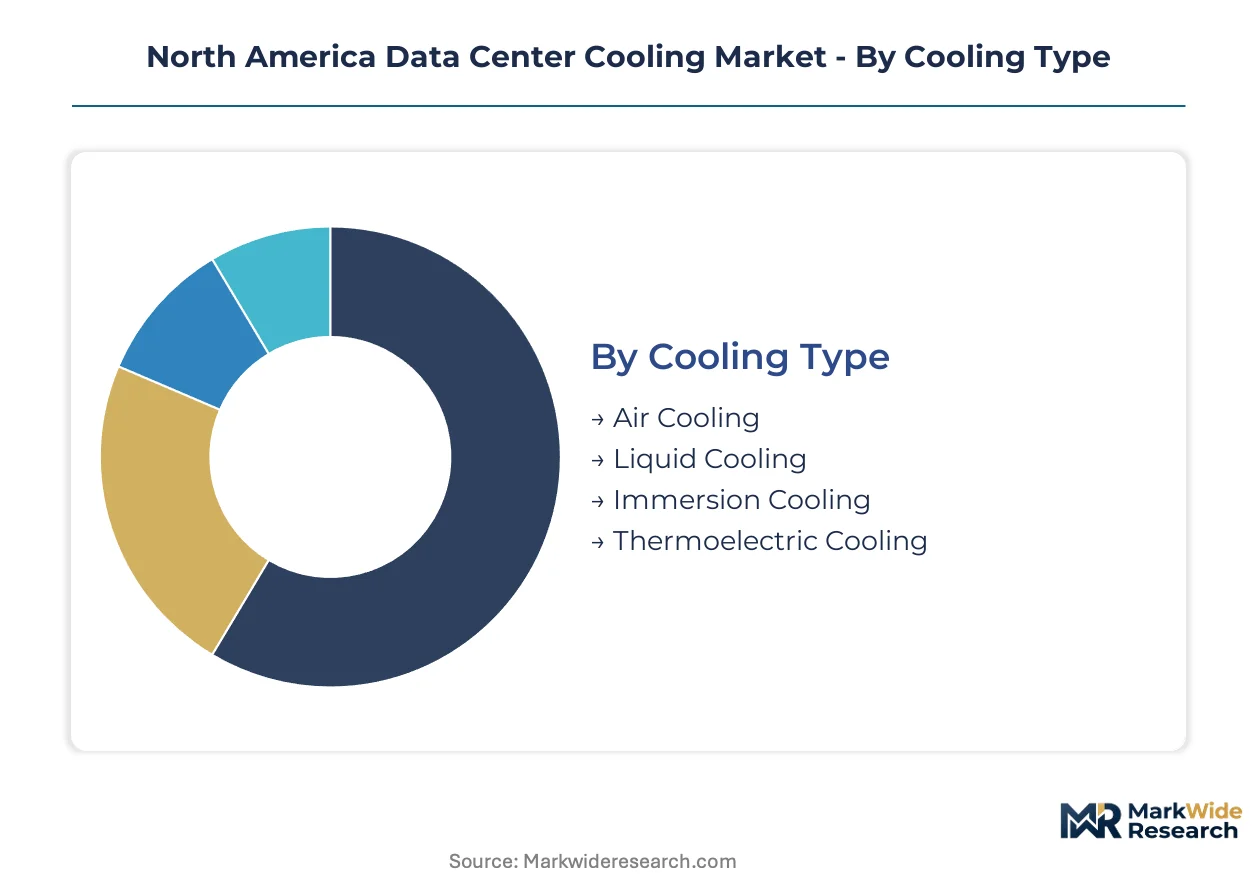
Cooling technology selection in North America increasingly hinges on compliance positioning against federal efficiency mandates and state carbon regulations. Procurement committees now weight thermal performance specifications against California's Title 24 standards and emerging clean energy disclosure rules.
Cooling Type:
Federal refrigerant phase-down schedules under the EPA's AIM Act are fragmenting technology roadmaps across deployment scales.
- Liquid Cooling:Direct-to-chip and cold-plate architectures circulate dielectric fluids or water-glycol mixtures through microchannels bonded to processor heat spreaders. Demand concentrates in Northern Virginia's hyperscale corridor where rack densities exceed 50 kW and ASHRAE thermal envelopes require sub-ambient delivery temperatures.
- Air Cooling:Raised-floor perimeter CRAC and CRAH units deliver conditioned air through perforated tiles to maintain 18°C to 27°C inlet temperatures per ASHRAE guidelines. Legacy facilities in secondary markets retain this architecture where power densities remain below 30 kW and capital retrofit timelines conflict with lease expirations.
- Immersion Cooling:Single-phase and two-phase dielectric fluid baths submerge entire server assemblies for extreme heat flux applications.
- Thermoelectric Cooling:Solid-state Peltier modules provide precision temperature control for edge computing and laboratory environments.
Liquid cooling handles the majority of new hyperscale throughput; immersion cooling is gaining share fastest among AI training cluster deployments.
End User:
Customer procurement sophistication varies sharply across ownership models and capital deployment horizons.
- Cloud Service Providers:Hyperscale operators design proprietary thermal architectures integrated with power distribution and rack infrastructure. These buyers dominate direct-to-chip liquid cooling volumes through dedicated AI training facilities in Northern Virginia, Phoenix, and Dallas-Fort Worth.
- Colocation Providers:Multi-tenant facility operators standardize on modular cooling units to accommodate diverse client density requirements. Their procurement prioritizes refrigerant flexibility under EPA AIM Act compliance timelines and long-term service contract margins.
- IT Companies:Enterprise data centers balance legacy air-cooling investments against selective liquid-cooling pilots for high-performance computing workloads.
- Telecommunications:Edge and central office deployments emphasize thermoelectric and compact air-cooling solutions for space-constrained environments.
Cloud service providers command the largest absolute capacity additions; colocation providers are expanding most quickly into liquid-cooled premium suites.
Technology:
Equipment selection tracks facility vintage, density tier, and integration depth with building management systems.
- CDU Systems:Coolant distribution units regulate flow rates, temperatures, and pressure drops between primary and secondary cooling loops in liquid-cooled deployments. Demand clusters in new hyperscale builds where facility-scale thermal management requires centralized pumping and heat rejection coordination.
- CRAC Units:Computer room air conditioners provide direct expansion or chilled water cooling for raised-floor environments. These systems retain installed base dominance in legacy facilities across Chicago, Silicon Valley, and secondary markets where retrofit economics remain unfavorable.
- Heat Exchangers:Plate-and-frame and shell-and-tube designs enable heat transfer between facility water loops and external cooling towers or dry coolers.
- Chilled Beams:Passive and active beam systems deliver cooling through convection and radiation for office-adjacent data halls.
CDU systems anchor new liquid-cooling infrastructure; CRAC units retain the largest installed base requiring refrigerant transition planning.
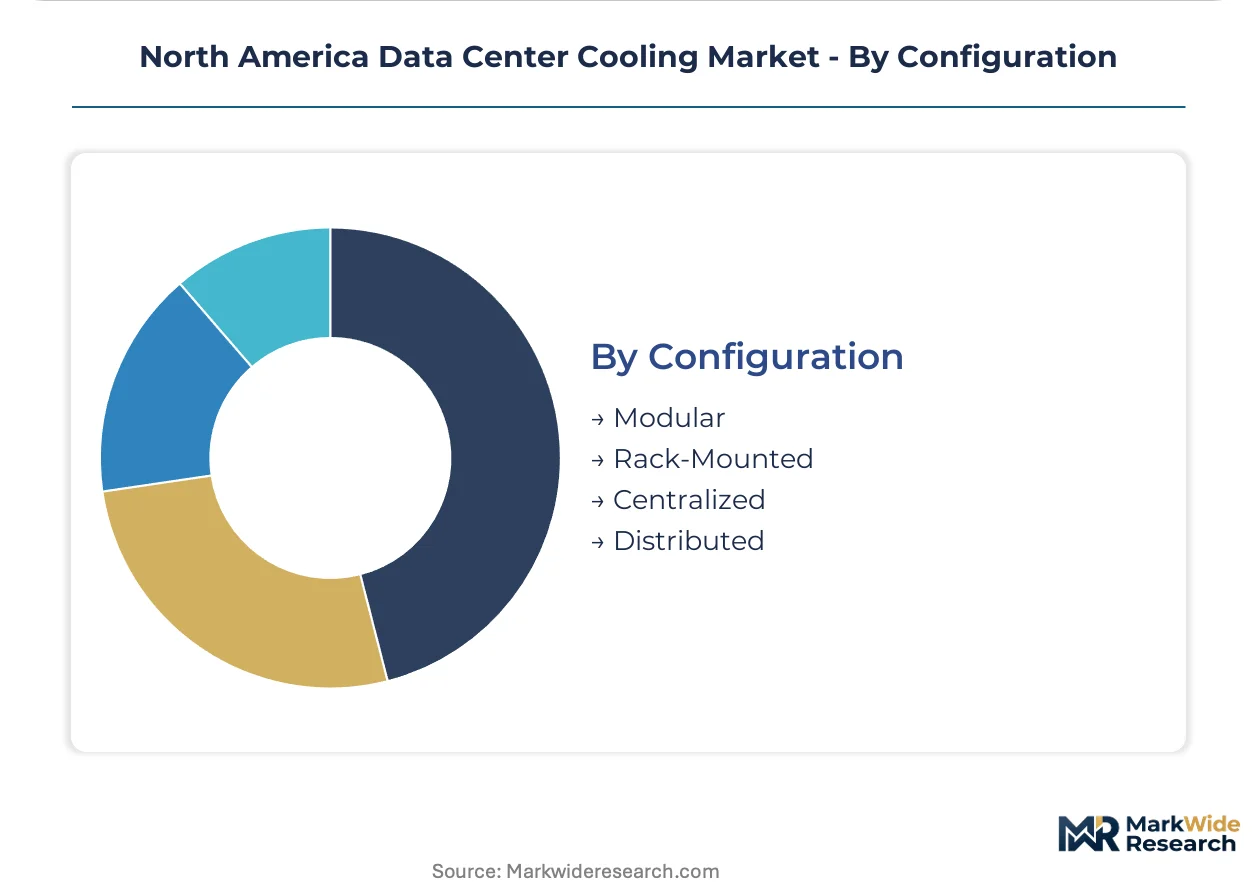
Configuration:
Physical deployment topology determines scalability, redundancy architecture, and maintenance accessibility.
- Modular:Factory-integrated cooling units with standardized power and fluid connections enable rapid deployment and capacity scaling. These configurations dominate colocation and edge builds across Texas, Arizona, and Nevada where speed-to-market compresses construction schedules.
- Rack-Mounted:In-row and rear-door heat exchangers position cooling capacity adjacent to heat sources. Adoption concentrates in retrofit scenarios and high-density zones within existing facilities where perimeter cooling proves insufficient.
- Centralized:Facility-scale chiller plants and cooling towers serve entire data halls through distribution piping.
- Distributed:Multiple smaller units provide zonal redundancy and isolation for mixed-density environments.
Modular configurations handle the majority of greenfield deployment velocity; rack-mounted solutions are climbing fastest in retrofit and upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility construction concentrates in jurisdictions with favorable utility rates and renewable energy access, while legacy markets face retrofit pressure from efficiency mandates. Canada and the United States dominate capacity additions, with Mexico emerging as a secondary location for edge and latency-sensitive deployments.
United States
Northern Virginia's data center corridor now processes over 35 percent of global internet traffic, driving rack power densities past 50 kW and mandating liquid-cooling retrofits. The Department of Energy's Better Buildings Challenge tightens thermal performance benchmarks for federal contractors. Phoenix and Dallas-Fort Worth hyperscale campuses are scaling direct-to-chip architectures for AI training clusters.
Canada
Quebec and Ontario attract carbon-neutral hyperscale builds through hydroelectric baseload and ambient cooling advantages that reduce mechanical refrigeration loads. The country's federal carbon pricing mechanism and provincial clean energy mandates align data center interconnection agreements with thermal efficiency disclosures. Toronto's downtown core hosts district heating integrations that monetize waste heat recovery from liquid-cooled facilities.
Mexico
Querétaro and Mexico City metros are capturing edge computing and content delivery investments seeking sub-50 millisecond latency to US Southwest markets. The national energy regulator's interconnection standards are evolving to accommodate high-density cooling loads from foreign cloud operators. Monterrey's industrial corridor is testing modular liquid-cooling deployments for manufacturing-adjacent IT infrastructure.
North America Data Center Cooling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across deployment scales. Integrated power-and-thermal platforms anchor hyperscale procurement cycles, while specialized component vendors retain positions in high-performance computing niches. The market consolidates around three strategic archetypes: full-stack infrastructure integrators, precision cooling specialists, and dielectric fluid technology pure-plays. Dominant competitive moves include vertical integration into captive power distribution portfolios and strategic partnerships that bundle thermal performance guarantees with renewable energy supply contracts.
Among US-based infrastructure providers, Vertiv Group Corp exemplifies the integrated platform archetype, while Schneider Electric occupies a position spanning power distribution and precision thermal management. Asetek represents the specialized liquid-cooling tier with concentration in direct-to-chip architectures. These three anchors demonstrate how vendor selection in North America increasingly favors full-stack procurement over discrete component sourcing.
| Leading Market Players |
|---|
| Vertiv Group Corp |
| Schneider Electric |
| STULZ GmbH |
| Johnson Controls |
| Rittal GmbH & Co. KG |
| Asetek |
| Nortek Air Solutions |
| Daikin Industries, Ltd. |
| Eaton |
| Others |
Supply & Pricing Matrix
Long-term thermal performance guarantees bundled with power purchase agreements lock in supply access and price visibility for hyperscale operators across Northern Virginia's data center corridor. These contract structures align cooling infrastructure procurement with electricity supply commitments, compressing vendor negotiation cycles and stabilizing capex forecasting against copper and aluminum volatility.
Pricing Analysis
California's Title 24 building energy efficiency standards dictate the pricing tier structure across the North American data center cooling market. Three-tier pricing separates liquid-cooled premium installations from standard air-cooled retrofits and economy-grade legacy maintenance contracts. Price differentiation hinges on ASHRAE thermal compliance certification and volume scale of hyperscale deployments. Cost compression in standard-tier CRAC replacements is intensifying because refrigerant phase-down timelines under the EPA's AIM Act are compressing supplier margins. Cloud service providers exhibit the lowest price sensitivity due to bundled power-and-thermal procurement, while colocation providers face acute margin pressure from multi-tenant cooling standardization requirements.
Supply Chain Analysis
The United States and Mexico anchor heat exchanger fabrication and precision cooling component assembly for the North American market. Dielectric fluid formulations draw from specialized chemical production concentrated in Texas and Louisiana, while copper tubing and aluminum fin stock rest on domestic smelter output and Canadian primary metal imports. Single-source vulnerability around certified technician pools in Virginia, California, and Texas creates regional installation bottlenecks for direct liquid cooling deployments. Distribution runs through systems integrators and OEM captive channels rather than independent distributors, concentrating procurement leverage among vertically integrated infrastructure providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America data center cooling market functions as a service-attach opportunity where thermal-fluid chemistry maintenance contracts and dielectric fluid replacement programs expand faster than hardware shipments. Recurring revenue layers from ASHRAE compliance monitoring and refrigerant transition consulting now exceed equipment margin profiles for leading vendors.
For Market Incumbents: Secure proprietary dielectric fluid formulations through backward integration into chemical supply partnerships, insulating margin profiles from refrigerant price volatility under EPA AIM Act phase-down schedules. Expand captive technician certification programs in Northern Virginia and Dallas-Fort Worth to defend against regional installation bottlenecks that threaten project delivery timelines. Control channel access by bundling thermal performance guarantees with renewable energy supply contracts, raising switching costs for hyperscale procurement committees. For New Entrants and Emerging Players: Anchor in Quebec and Ontario hydroelectric zones where carbon-neutral power procurement and ambient cooling advantages attract hyperscale builds seeking thermal systems optimized for lower wet-bulb temperatures. Target waste heat recovery integration projects in Minneapolis-St. Paul and Toronto district heating networks, where cooling architectures designed for heat extraction rather than rejection command premium positioning. Pursue go-to-market partnerships with Canadian provincial clean energy agencies to align interconnection agreements with thermal efficiency disclosure requirements. For Investors and Strategic Acquirers: Specialized dielectric fluid technology pure-plays with captive chemistry expertise and ASHRAE guideline alignment capabilities represent the most defensible acquisition targets over the long-term viability window. These entities command scarcity rents as traditional HVAC technician pools lack thermal-fluid maintenance protocols for liquid-cooled AI training clusters. Monitor hyperscale capex disclosure patterns for direct-to-chip liquid cooling adoption curves as the primary inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Fluid Supply | Captive chemistry expertise insulates margins from EPA refrigerant phase-down volatility. |
| Technician Certification Program Expansion | Certified installation pools in Virginia and Texas alleviate regional deployment bottlenecks. |
| Waste Heat Recovery Architecture Development | District heating integration in Toronto and Minneapolis-St. Paul monetizes thermal output. |
| Modular Factory-Integrated Cooling Platform Launch | Standardized power and fluid connections compress construction schedules in Arizona and Nevada. |
| Renewable Energy Supply Contract Bundling | Thermal performance guarantees paired with clean power procurement raise switching costs. |
Research Methodology
A standing panel of data center facility engineers, hyperscale procurement directors, thermal systems integrators, and refrigerant compliance specialists provided ongoing calibration for demand assumptions and technology adoption timelines. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through EPA AIM Act regulatory filings, Department of Energy Better Buildings Challenge documentation, ASHRAE technical guideline publications, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down facility construction pipeline analysis were triangulated to reconcile volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled cooling type, end user segment, technology category, and physical configuration dimensions alongside regional regulatory cluster variations. CAGRs were derived from equipment replacement cycle analysis and new build penetration curves for liquid-cooled architectures. Hyperscale AI training cluster deployment schedules and state-level clean energy mandate compliance timelines served as industry-specific forecast inputs.
Material uncertainties — copper and aluminum price volatility, EPA refrigerant availability rulings, and ASHRAE thermal envelope revisions — sit outside the modeled envelope. Forecasts reflect assumptions about hyperscale capital commitment continuity and state regulatory enforcement intensity that could shift with macroeconomic conditions or federal policy transitions. Recalibration cycles align with material shifts in hyperscale capex disclosure patterns and state-level carbon disclosure rule implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market