
 Chile Data Center Networking Market | 2026-2036
Chile Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Networking Market Insights
Cloud service provider expansion is realigning procurement patterns across Chile's data center networking landscape. Cisco Systems leverages its installed base in enterprise campus networks to extend into colocation interconnection. Huawei Technologies competes aggressively on total cost of ownership for greenfield hyperscale builds. Arista Networks specializes in low-latency spine architectures for Santiago's financial services corridors.
Data center networking encompasses the switching, routing, and security infrastructure that enables compute and storage resource interconnection within and between facilities, typically operating at speeds from 10 Gbps to 400 Gbps with sub-microsecond latency tolerances for high-frequency workloads. Ethernet switching dominates Chile's installed base due to its interoperability with existing enterprise infrastructure and compatibility with cloud provider architectures. Fiber Channel retains presence in legacy financial and mining enterprise data halls where storage area network investments remain amortized. Wireless segments occupy niche roles for edge provisioning in remote mining operations where cabled infrastructure proves cost-prohibitive.
SUBTEL enforces equipment homologation and electromagnetic compatibility standards that condition import timelines for networking hardware. Chile's central bank (BCCh) imposes cybersecurity resilience requirements on financial sector data infrastructure that elevate demand for certified firewall and segmentation platforms. Stakeholders must monitor submarine cable landing station developments and regulatory harmonization with Pacific Alliance digital trade frameworks to anticipate bandwidth cost trajectories and cross-border data flow architectures.
Market Dynamics
Hyperscale cloud provider facility construction in Santiago and Valparaiso is compressing procurement cycles for spine-leaf architectures while SUBTEL spectrum reforms accelerate fiber densification timelines across metropolitan corridors.
Growth Catalysts
- SUBTEL spectrum reforms:Chile's telecommunications subsecretariat has liberalized millimeter-wave allocations for 5G backhaul, enabling faster fiber-to-the-tower deployments that feed directly into data center interconnection nodes.
- Financial services latency requirements:Santiago's trading floors and mining technology operations demand sub-microsecond switching fabrics, pulling investment toward specialized low-latency spine architectures.
- Submarine cable landing investments:New Pacific cable systems terminating at Valparaiso and Quintero are expanding international bandwidth capacity, reducing transit costs for hyperscale facilities.
Market Restraints
- Copper and optical component cost volatility:Switching fabric production depends on refined copper cathode and coherent optical transceiver supply chains concentrated in East Asian manufacturing clusters, exposing Chilean integrators to input price swings.
- Equipment homologation timelines:SUBTEL electromagnetic compatibility certification processes extend lead times for non-domestic networking hardware, compressing deployment windows for time-sensitive builds.
- Legacy Fiber Channel infrastructure:Amortized storage area network investments in mining and financial enterprise data halls create switching-protocol lock-in that slows Ethernet migration.
Strategic Opportunities
- Antofagasta mining corridor edge deployment:Remote extraction operations in Chile's northern desert regions present first-mover potential for wireless edge networking where cabled backhaul remains economically unviable.
- BCCh cybersecurity resilience mandates:Chile's central bank has imposed segmentation and firewall certification requirements on financial infrastructure, creating compliance-driven demand for certified security platforms.
- Converged infrastructure software stacks:Integration of software-defined networking with network function virtualization is enabling multi-tenant colocation providers to offer programmable interconnection services.
Industry Challenges
- Specialized fiber splicing and photonics technician scarcity:Deployment of 400 Gbps coherent optical systems requires skills concentrated in Santiago, constraining expansion timelines in secondary metropolitan regions.
- Hyperscale contract negotiation complexity:Cloud provider procurement teams demand custom spine-leaf configurations and extended warranty terms that strain vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Networking Market |
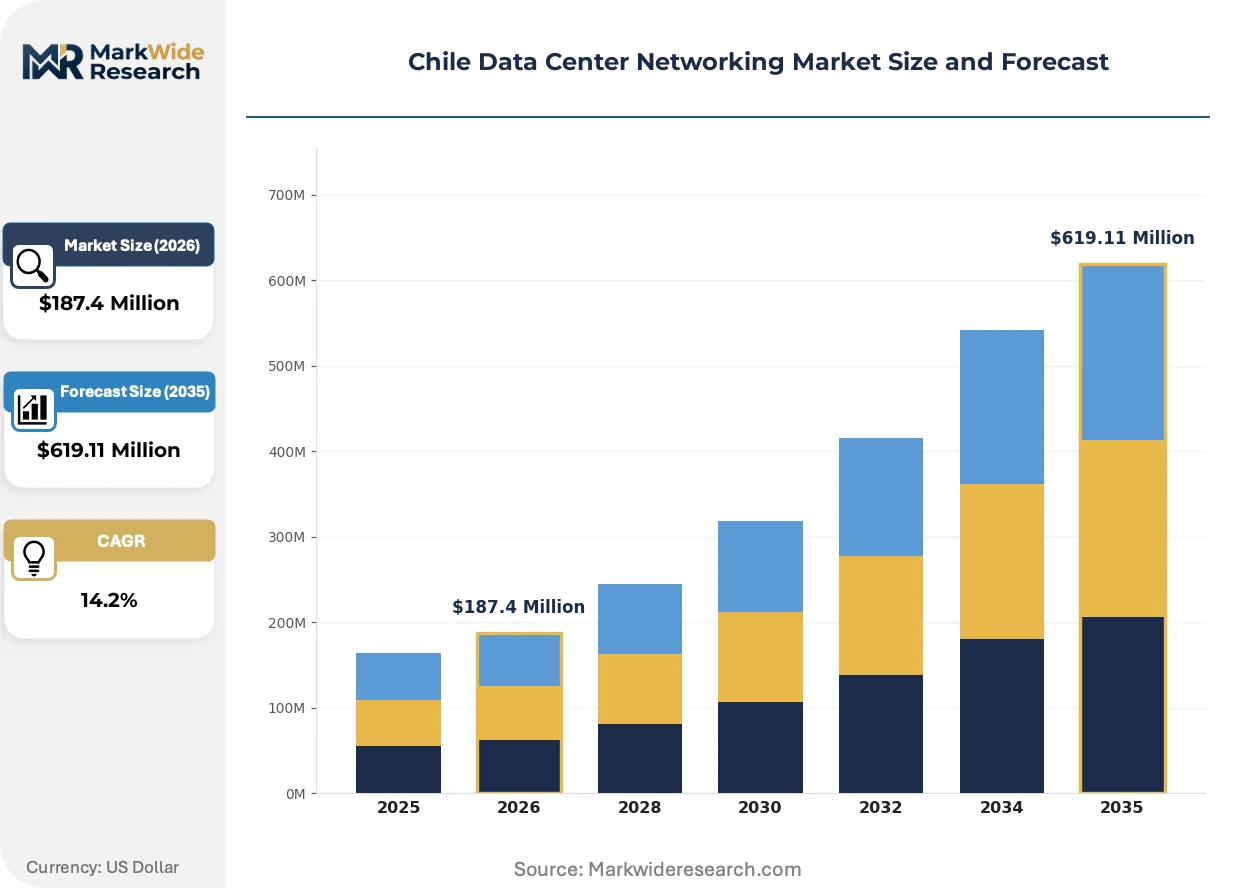
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Fiber Channel, InfiniBand, Wireless End User: Telecom Providers, IT Companies, Government Entities, Cloud Service Providers Installation: On-Premises, Colocation, Managed Services, Hybrid |
| Companies Covered | Cisco Systems, Huawei Technologies, Juniper Networks, Hewlett-Packard Enterprise, VMware, Schneider Electric, Arista Networks, Extreme Networks, Nokia Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Networking Market Trends and Innovations
Software-defined architectures are dissolving traditional hardware procurement boundaries while regulatory pressure on data sovereignty reshapes interconnection topology decisions across Chilean facilities.
Disaggregated white-box switching hardware is modularizing procurement patterns for Chilean colocation providers. These stripped-down platforms separate merchant silicon from network operating system software, allowing Santiago-based operators to source commodity hardware from Asian ODMs while running certified NOS stacks. Financial services tenants are adopting these configurations fastest, compressing traditional three-year refresh cycles into eighteen-month increments as merchant silicon roadmaps accelerate.
BCCh cybersecurity resilience requirements are mandating zero-trust segmentation architectures for all payment system infrastructure. Financial institutions must now deploy micro-segmentation platforms that enforce workload-to-workload policies independent of network topology. Mining sector data halls serving autonomous extraction systems are adopting similar frameworks preemptively, anticipating convergence with critical infrastructure classification standards.
Cloud service provider procurement teams are consolidating vendor relationships around full-stack infrastructure partners capable of delivering switching, optics, and automation software through unified contracting vehicles. This concentration is displacing best-of-breed component sourcing that previously dominated Chilean enterprise networking. Colocation operators in Santiago Metropolitan Region are responding by developing in-house integration capabilities to maintain margin capture on interconnection services.
Chile Data Center Networking Market Segmentation
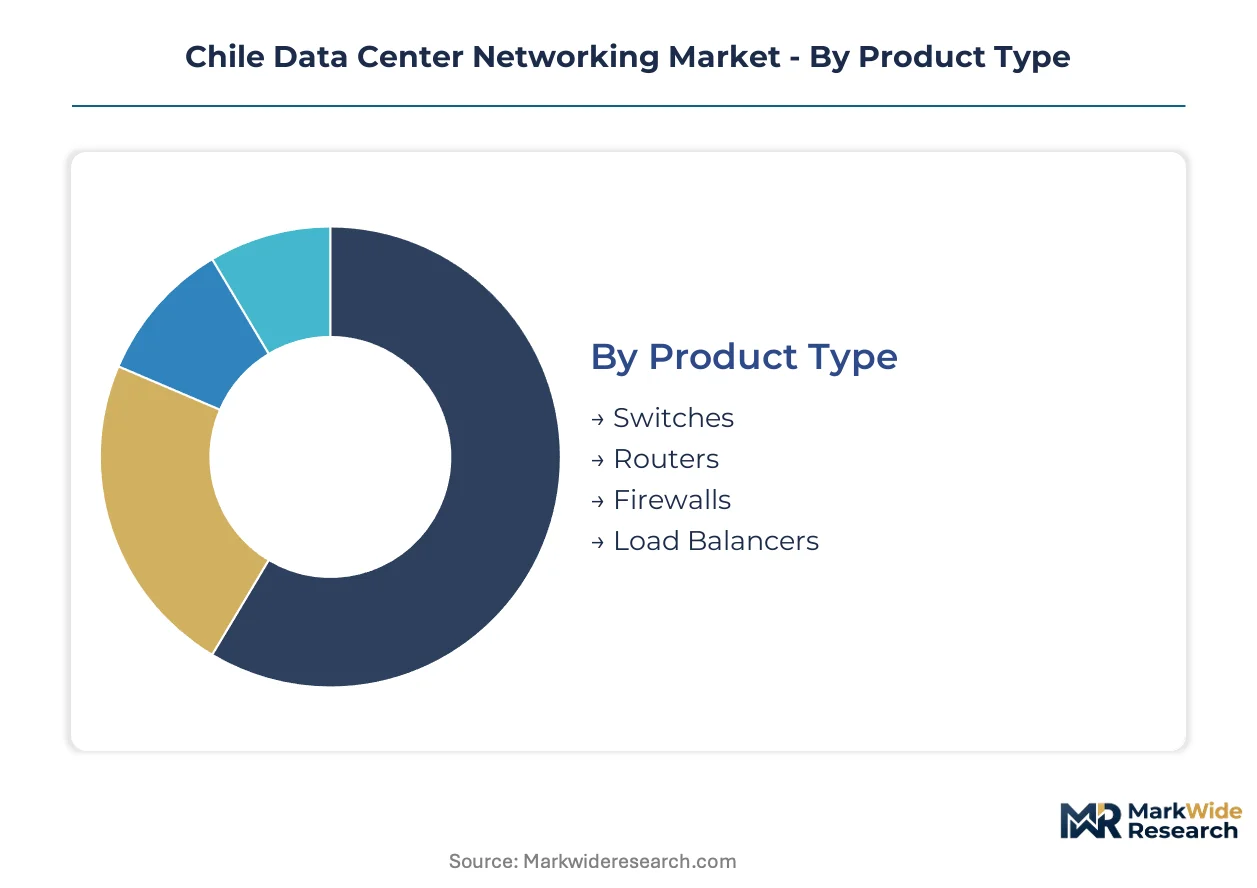
Segmentation in Chile's data center networking market reveals how procurement patterns diverge between hyperscale cloud builds and legacy enterprise refresh cycles. Each dimension exposes distinct integration requirements, from protocol compatibility in financial services to deployment flexibility in remote mining corridors.
Product Type:
Standalone networking appliances dominate high-throughput core installations, while embedded security functions increasingly displace discrete hardware at the network edge.
- Switches:Spine-leaf architectures in Santiago's hyperscale facilities drive demand for 400 Gbps merchant silicon platforms with sub-500 nanosecond port-to-port latency. Cloud service providers in the Metropolitan Region compress refresh cycles to eighteen months as merchant roadmaps accelerate.
- Routers:Border gateway platforms handle inter-facility traffic across Valparaiso's submarine cable landing zones, with demand concentrating where international bandwidth expansion reduces transit cost structures for content delivery networks.
- Firewalls:BCCh-mandated segmentation platforms enforce zero-trust policies on payment system infrastructure, creating compliance-driven procurement distinct from throughput-optimized core switching.
- Load Balancers:Application delivery controllers distribute traffic across multi-tenant colocation environments, with software-defined virtual editions displacing hardware appliances in smaller Santiago facilities.
Switches lead volumes today; firewalls are gaining share fastest.
Technology:
Protocol selection reflects amortization timelines and interoperability requirements across Chile's enterprise installed base.
- Ethernet:Dominates new builds through interoperability with cloud provider architectures and existing campus infrastructure. SUBTEL's spectrum reforms accelerate fiber densification that feeds directly into Ethernet interconnection nodes across metropolitan corridors.
- Fiber Channel:Retains presence in legacy financial and mining data halls where storage area network investments remain amortized, creating protocol lock-in that slows migration timelines.
- InfiniBand:High-performance computing clusters in research institutions deploy RDMA-capable fabrics for latency-sensitive simulation workloads.
- Wireless:Edge provisioning in Antofagasta mining operations where cabled backhaul proves economically unviable, serving autonomous extraction systems with limited connectivity options.
Ethernet leads volumes today; wireless is expanding most quickly.
End User:
Procurement authority concentrates differently across customer types, from centralized cloud provider engineering teams to distributed government IT departments.
- Telecom Providers:SUBTEL-regulated carriers deploy 5G backhaul infrastructure that interconnects with data center fiber nodes, with millimeter-wave spectrum allocations enabling faster tower-to-facility links.
- IT Companies:Enterprise technology vendors integrate networking hardware into bundled infrastructure offerings for mid-market Chilean firms lacking dedicated network engineering capabilities.
- Government Entities:Public sector procurement follows centralized contracting frameworks with extended vendor qualification timelines, prioritizing certified security platforms for sensitive administrative systems.
- Cloud Service Providers:Hyperscale engineering teams demand custom spine-leaf configurations and unified contracting vehicles that consolidate switching, optics, and automation software procurement.
Cloud service providers lead volumes today; government entities are climbing the fastest.
Installation:
Deployment model selection tracks capital availability and operational expertise across Chile's heterogeneous customer base.
- On-Premises:Financial institutions in Santiago maintain owned facilities to satisfy BCCh cybersecurity resilience mandates, retaining direct control over physical segmentation and access logging systems.
- Colocation:Multi-tenant facilities in the Metropolitan Region offer programmable interconnection services through converged infrastructure stacks, enabling smaller enterprises to access carrier-neutral peering.
- Managed Services:Mining sector firms outsource network operations to specialists who maintain remote edge deployments across northern desert regions with limited local technical labor pools.
- Hybrid:Enterprises combine owned core infrastructure with burst capacity from cloud providers, requiring consistent policy enforcement across administrative boundaries.
Colocation leads volumes today; hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santiago Metropolitan Region anchors Chile's data center networking demand through hyperscale cloud facilities and financial services infrastructure clustering in the capital corridor.
Santiago Metropolitan Region
Hyperscale cloud provider construction in Cerrillos and Quilicura drives procurement of 400 Gbps spine-leaf architectures with sub-500 nanosecond latency specifications. SUBTEL's millimeter-wave spectrum reforms accelerate fiber densification timelines across the capital's metropolitan corridors. Latency-sensitive trading floors in Santiago's financial district pull investment toward specialized low-latency switching fabrics.
Valparaiso Region
Submarine cable landing stations at Valparaiso and Quintero expand international bandwidth capacity for content delivery networks and cloud interconnection nodes. The regional development authority coordinates data center zone permitting with port infrastructure expansion. Hyperscale facilities cluster within kilometers of cable landing points to minimize transit cost structures.
Antofagasta Region
Autonomous mining operations across the Atacama Desert generate edge networking demand where cabled backhaul remains economically unviable for remote extraction sites. Wireless edge provisioning serves autonomous haulage systems with limited connectivity alternatives. Mining sector firms outsource network operations to specialists maintaining distributed edge deployments.
Bio Bio Region
Manufacturing and logistics operations in Concepcion's industrial corridor drive mid-market colocation demand for disaster recovery and business continuity infrastructure. Regional data center operators compete on proximity to manufacturing clusters rather than international bandwidth scale. SUBTEL's rural connectivity programs extend fiber reach into secondary metropolitan zones.
Chile Data Center Networking Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors position for hyperscale procurement contracts and colocation interconnection services. The vendor base stratifies between full-stack infrastructure consolidators and specialized low-latency component suppliers. Three archetypes occupy distinct competitive positions: cloud-integrated platform providers, financial services specialists, and industrial edge networking suppliers. Portfolio diversification and unified contracting vehicles represent the dominant competitive moves as procurement teams consolidate vendor relationships.
Among North American networking vendors, Cisco Systems and Arista Networks exemplify contrasting strategic positions within the Chilean market. Cisco Systems leverages its installed base in enterprise campus networks to extend into colocation interconnection and managed service provider channels. Arista Networks occupies a position as a low-latency spine architecture specialist serving Santiago's financial services corridors. Huawei Technologies represents the Asian vendor archetype competing aggressively on total cost of ownership metrics for greenfield hyperscale builds.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Juniper Networks |
| Hewlett-Packard Enterprise |
| VMware |
| Schneider Electric |
| Arista Networks |
| Extreme Networks |
| Nokia Corporation |
| Others |
Pricing and Supply Chain Analysis
BCCh cybersecurity resilience mandates gate qualified supply for premium-tier networking hardware, restricting certified firewall and segmentation platform access to vendors meeting central bank certification timelines while elevating pricing power for compliant suppliers serving Santiago's financial services corridors.
Pricing Analysis
Distributor margins compress pricing tiers across Chilean data center networking procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by certification grade and after-sales service bundling. SUBTEL homologation requirements elevate certified equipment pricing above gray-market alternatives, though hyperscale cloud providers leverage volume scale to extract direct-to-OEM discounts. Price erosion runs through standard-tier switching as merchant silicon roadmaps accelerate refresh cycles, while mining sector buyers in Antofagasta exhibit highest price sensitivity due to remote deployment cost structures.
Supply Chain Analysis
Single-source vulnerability sits with East Asian coherent optical transceiver suppliers, where Taiwan, South Korea, and China anchor production of refined copper cathode and merchant silicon platforms that feed Chilean integrators. Switching fabric production draws from concentrated photonics manufacturing clusters, exposing procurement timelines to logistics chokepoints at Pacific maritime terminals. Distribution runs through Santiago-based systems integrators who maintain buffer inventory for SUBTEL certification delays, with Valparaiso port infrastructure serving as the primary entry node for submarine cable-linked facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's data center networking market functions as a stable compounder, with SUBTEL spectrum reforms and hyperscale facility construction providing steady demand visibility across the analysis window.
For Market Incumbents: Anticipate procurement consolidation by hyperscale cloud providers demanding unified contracting vehicles, and respond through backward integration into optics manufacturing to defend margin position against Asian ODM price pressure. Prioritize certification investment for BCCh cybersecurity mandates to maintain access to financial services corridors where switching-protocol lock-in slows Ethernet migration from legacy Fiber Channel infrastructure.
For New Entrants and Emerging Players: Capture white-space opportunity in Antofagasta mining corridor edge deployments where wireless networking serves autonomous extraction systems with limited cabled backhaul alternatives. Target managed services outsourcing by mining sector firms lacking distributed technical labor pools, positioning through specialized field maintenance capabilities for remote desert operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among colocation operators developing in-house integration capabilities to maintain margin capture on interconnection services. Long-term viability hinges on software-defined networking convergence with network function virtualization stacks. Monitor submarine cable landing station developments at Valparaiso and Quintero as bandwidth cost inflection indicators for hyperscale facility expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | BCCh compliance unlocks financial sector procurement with mandated zero-trust segmentation requirements. |
| Edge Deployment Capability | Wireless networking expertise captures Antofagasta mining autonomous haulage system connectivity demand. |
| Optics Manufacturing Integration | Merchant silicon platform control reduces exposure to East Asian supply chain volatility. |
| Colocation Interconnection Services | Programmable peering platforms differentiate Santiago Metropolitan Region multi-tenant facilities. |
| Submarine Cable Proximity Positioning | Valparaiso landing zone clustering minimizes transit cost structures for international bandwidth. |
Research Methodology
Coverage spans Santiago Metropolitan Region, Valparaiso Region, Antofagasta Region, and Bio Bio Region, with primary inputs from each combining interviews with data center engineering directors, SUBTEL regulatory affairs specialists, cloud provider procurement teams, and mining sector IT operations managers. Secondary validation draws from SUBTEL spectrum allocation filings, BCCh cybersecurity resilience circulars, submarine cable landing station development records, and hyperscaler capex disclosures. Bottom-up facility-level capacity estimates triangulate against top-down regional demand projections.
Granularity-level modeling disaggregates revenue across product type, technology protocol, end user category, and installation model dimensions, with additional segmentation by regional bandwidth cost tier and certification compliance status. CAGRs derive from fitted growth curves anchored to observable hyperscale construction timelines and SUBTEL regulatory implementation schedules. Forecast inputs include merchant silicon roadmap acceleration patterns, Fiber Channel amortization schedules in legacy financial data halls, and 5G backhaul densification trajectories across metropolitan corridors.
Copper and optical component cost volatility, SUBTEL electromagnetic compatibility certification timeline extensions, and hyperscale contract negotiation complexity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about submarine cable capacity expansion and regulatory harmonization with Pacific Alliance frameworks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Europe Data Center Networking Market