
 Europe Data Center Interconnect Market | 2026-2036
Europe Data Center Interconnect Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Interconnect Market Foresight
Coherent optical transmission at 800G and beyond is rewriting how data center operators architect inter-facility links across European metro and regional footprints. Ciena Corporation leverages programmable silicon to sustain leadership in high-capacity wavelength services between hyperscale campuses. Nokia Corporation anchors its position through IP-over-DWDM convergence, while Infinera Corporation specializes in open optical line systems that compete on interoperability with disaggregated routing platforms.
Europe Data Center Interconnect encompasses the fiber-optic networking infrastructure, optical transport equipment, and software-defined control planes that link geographically separate data center facilities to function as unified computing resources. These systems typically operate at 100G to 800G per wavelength with latency budgets under 10 milliseconds for synchronous replication workloads, enabling disaster recovery, load balancing, and distributed cloud orchestration. Wavelength Division Multiplexing retains the dominant share of installed capacity due to its spectral efficiency across long-haul fiber pairs, though Ethernet overlays are gaining ground in campus-style deployments where dark fiber abundance simplifies physical layer economics. Managed Services and Cloud Connect offerings are expanding fastest as enterprises outsource interconnection complexity to carrier-neutral operators, while Cross Connects remain the margin pool for colocation providers controlling meet-me-room real estate in Frankfurt and Amsterdam.
The EU's Data Act and GDPR framework shape how providers architect cross-border connectivity, with the European Data Protection Board enforcing strict sovereignty requirements for sensitive data flows. ETSI standards and the EU Cybersecurity Act mandate encryption and resilience certifications for critical digital infrastructure, creating compliance barriers for non-European equipment vendors. The F-Gas Regulation also influences thermal design of amplification huts and repeater stations along fiber routes. Stakeholders must monitor how the EU AI Act's risk classification tiers will reshape data localization patterns and interconnection density requirements across member states.
Market Dynamics
Coherent optical transmission at 800G wavelengths is collapsing the cost-per-bit economics of metro interconnection across European hyperscale campuses. The EU's Data Act and Digital Markets Act are simultaneously rewriting data portability obligations and interconnection governance, forcing operators to rearchitect cross-border fiber routes.
Growth Catalysts
- AI Workload Proliferation:Hyperscale operators in Frankfurt, Paris, and Amsterdam are deploying distributed computing architectures that demand sub-10-millisecond synchronous replication between facilities.
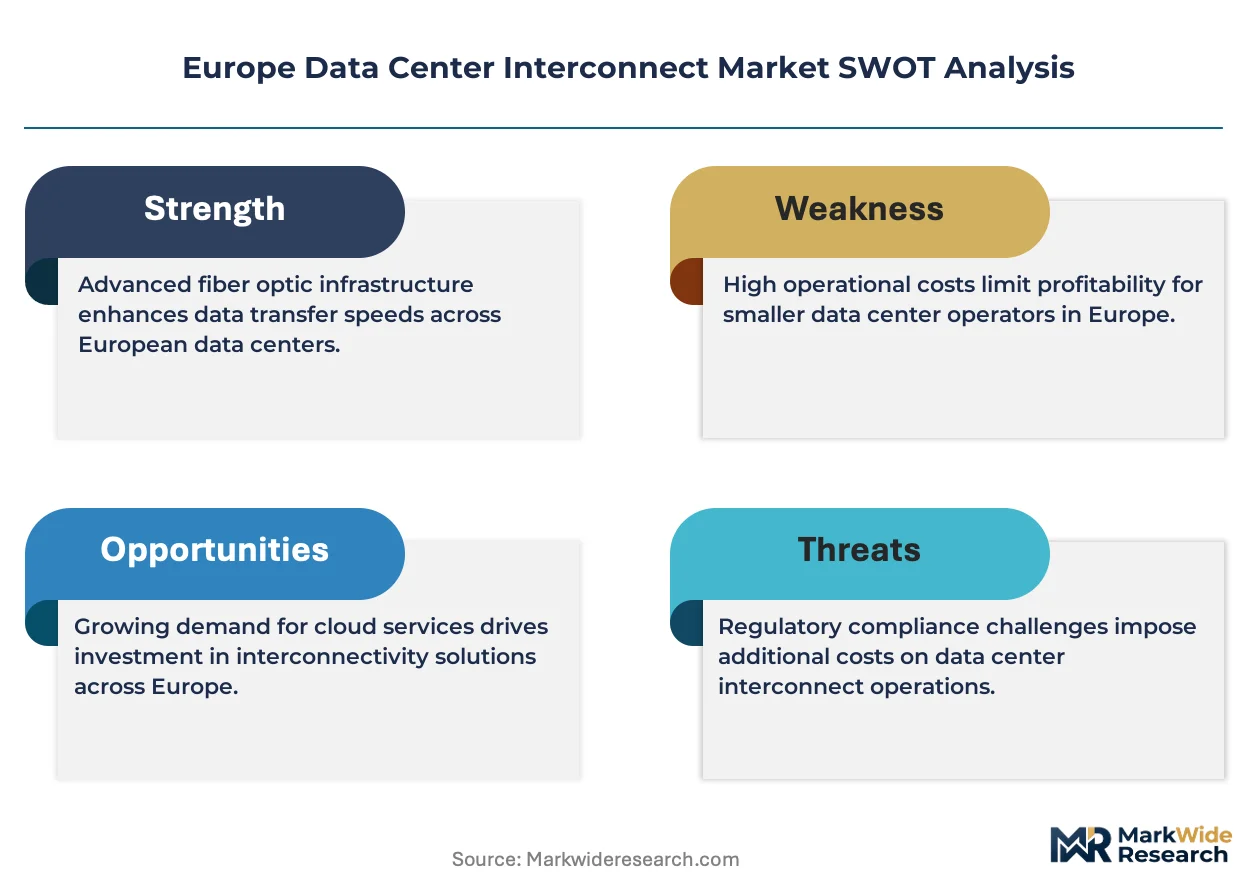
- EU Data Act Mandates:The regulation's data portability requirements are compelling enterprises to establish dedicated interconnects for multi-cloud orchestration and vendor switching.
- Managed Services Expansion:Carrier-neutral operators are capturing enterprise demand by outsourcing wavelength provisioning, optical layer management, and SLA enforcement.
Market Restraints
- Amplification Hut Thermal Constraints:The F-Gas Regulation restricts refrigerant choices for cooling erbium-doped fiber amplifiers along long-haul routes, raising equipment costs.
- Dark Fiber Supply Concentration:Incumbent telecom operators in Germany and France control the majority of metro fiber pairs, limiting price competition for wavelength services.
- Submarine Cable Landing Monopolies:A handful of coastal landing stations in the Netherlands and Portugal gatekeep transatlantic capacity for continental interconnection backbones.
Strategic Opportunities
- Eastern European Campus Expansion:Poland and Romania are attracting hyperscale developments where land and power costs undercut Frankfurt and Amsterdam premiums.
- Open Optical Line System Convergence:Disaggregated routing platforms from multiple vendors are interoperating through standardized APIs, reducing vendor lock-in.
- EU Cybersecurity Act Certification:The resilience certification mandate for critical digital infrastructure creates a compliance-driven upgrade cycle for encryption and monitoring capabilities.
Industry Challenges
- Coherent DSP Engineering Talent Scarcity:The specialized skill set for programming silicon photonics and digital signal processors is concentrated among a small pool of designers.
- Legacy SDH/SONET Migration Complexity:Financial services and government facilities in Frankfurt maintain synchronous optical networking equipment that complicates IP-over-DWDM overlay deployment.
- Cross-Border Permitting Delays:Fiber route construction across German Länder and French regions faces divergent underground infrastructure regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Interconnect Market |
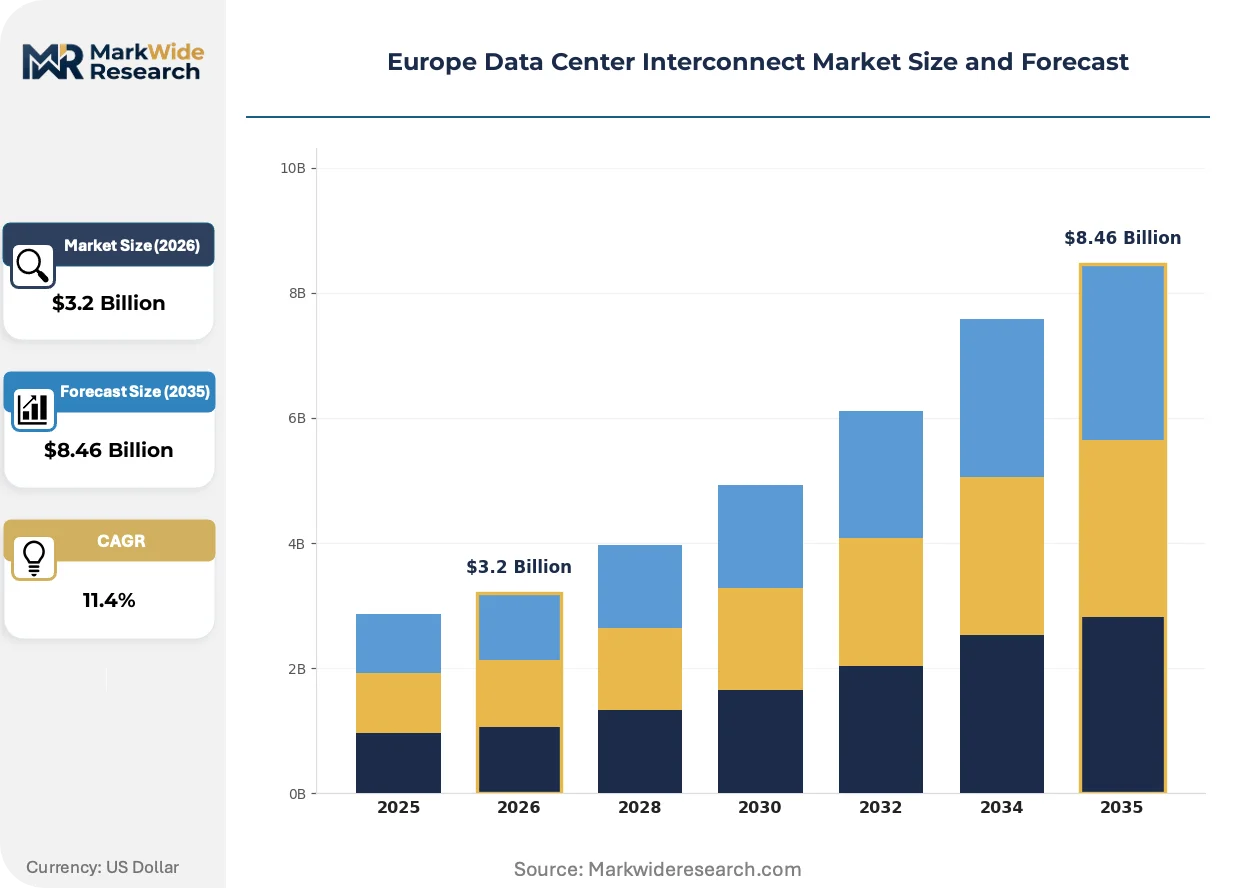
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wavelength Division Multiplexing, Ethernet, SDN, MPLS Service Type: Cross Connects, Dark Fiber, Managed Services, Cloud Connect Deployment: On-Premises, Hybrid, Colocation, Virtualized Customer Type: Telecom Providers, Enterprises, Cloud Service Providers, Government |
| Companies Covered | Ciena Corporation, Cisco Systems, Juniper Networks, Nokia Corporation, Huawei Technologies, Infinera Corporation, Equinix, Digital Realty Trust, Fujitsu, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Interconnect Market Shifts & Advancements
Programmable silicon and software-defined control planes are rewriting how European operators provision capacity between data centers. Three developments are compressing deployment timelines and reshaping procurement patterns.
Coherent pluggable optics at 400G and 800G is collapsing the traditional boundary between router ports and optical transport systems. Hyperscale operators are adopting these modules for intra-campus links, eliminating standalone transponder shelves. This convergence is compressing equipment footprints and power consumption while simplifying sparing strategies across Amsterdam and Frankfurt facilities.
The EU AI Act's risk classification tiers are mandating data localization for high-risk artificial intelligence training workloads. ETSI standards bodies are responding with enhanced encryption specifications for cross-border fiber routes. Financial services and healthcare verticals in Germany and France are driving demand for certified quantum-safe key distribution overlays.
Enterprise procurement of interconnection services is consolidating under network-as-a-service contracts with committed volume tiers. Colocation providers in Amsterdam and Paris are unbundling cross-connect fees from port charges, shifting revenue recognition toward recurring managed wavelengths. This restructuring is visible most acutely among mid-market enterprises outsourcing disaster recovery topology design.
Europe Data Center Interconnect Market Segmentation
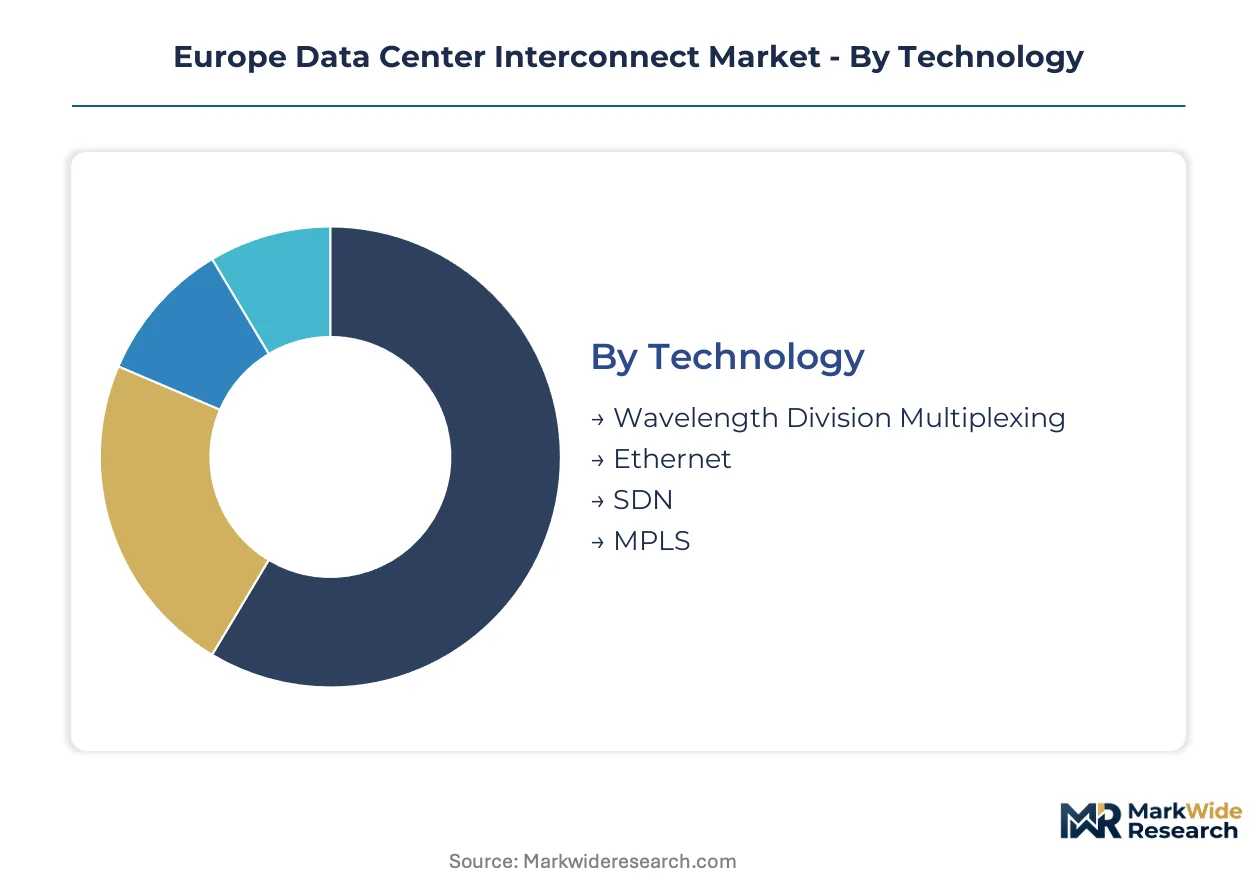
Segmentation in the Europe Data Center Interconnect Market reveals how optical transport economics, regulatory mandates, and customer procurement patterns fragment demand across distinct technology and service tiers. Understanding these divisions illuminates where capacity investments concentrate and where margin pools shift between hardware vendors and service operators.
Technology:
Optical transport technology selection hinges on spectral efficiency requirements, fiber pair availability, and latency budgets across European metro and regional footprints.
- Wavelength Division Multiplexing:Dense and coarse WDM systems multiplex multiple optical signals onto single fiber pairs, achieving 800G per wavelength with amplification huts spaced every 80-100 kilometers. German and Dutch hyperscale campuses deploy C-band and L-band systems for synchronous replication between Frankfurt, Amsterdam, and Paris facilities where fiber scarcity justifies spectral optimization.
- Ethernet:Direct fiber Ethernet overlays operate at 100G to 400G without wavelength conversion, reducing equipment complexity and power draw. Campus-style deployments in Amsterdam and emerging Polish facilities favor Ethernet where dark fiber abundance from carrier-neutral providers collapses physical layer economics.
- SDN:Software-defined networking abstracts optical transport control into centralized orchestration planes, enabling bandwidth-on-demand provisioning across multi-vendor infrastructure.
- MPLS:Multiprotocol Label Switching persists in financial services interconnects requiring traffic engineering and deterministic latency for trading floor replication.
Wavelength Division Multiplexing holds installed capacity. Ethernet is rotating up the share rankings.
Service Type:
Service model selection reflects customer willingness to own optical layer complexity versus outsource wavelength provisioning and SLA enforcement to specialized operators.
- Managed Services:Carrier-neutral operators provision, monitor, and maintain end-to-end optical paths, absorbing equipment sparing and field engineering costs. Mid-market enterprises in France and Germany outsource disaster recovery topology design to these providers, driven by GDPR-mandated data sovereignty requirements and the EU Cybersecurity Act's resilience certification complexity.
- Cloud Connect:Direct, private connectivity to hyperscale cloud regions bypasses public internet routing, guaranteeing throughput and latency for multi-cloud orchestration. Financial services and healthcare verticals in Frankfurt and Paris procure Cloud Connect to satisfy ETSI encryption specifications and EU AI Act data localization mandates for high-risk AI training workloads.
- Cross Connects:Physical fiber patching within meet-me-rooms enables carrier-neutral interconnection between colocation tenants.
- Dark Fiber:Unlit fiber pairs leased on long-term contracts allow customers to deploy proprietary optical equipment and control amplification strategies.
Managed Services is climbing the fastest. Cloud Connect is gaining share fastest.
Deployment:
Deployment architecture reflects capital intensity preferences, legacy infrastructure inheritance, and regulatory data residency obligations across member states.
- Colocation:Interconnection deployed within third-party data centers leverages existing meet-me-room infrastructure and cross-connect marketplaces. Hyperscale operators in Amsterdam and Frankfurt favor colocation for edge node deployment, minimizing fiber construction permitting delays across German Länder and French regional boundaries.
- Hybrid:Architectures combine on-premises optical equipment with cloud-orchestrated control planes, balancing capital control with operational flexibility. Enterprises navigating EU Data Act portability mandates adopt hybrid models to maintain switching capability between cloud providers without physical infrastructure overhaul.
- On-Premises:Customer-owned optical transport equipment and fiber plant delivers maximum control over encryption and physical security.
- Virtualized:Network functions virtualization decouples optical control plane software from proprietary hardware, enabling white-box transport deployment.
Colocation dominates current deployment volumes. Hybrid is expanding most quickly.
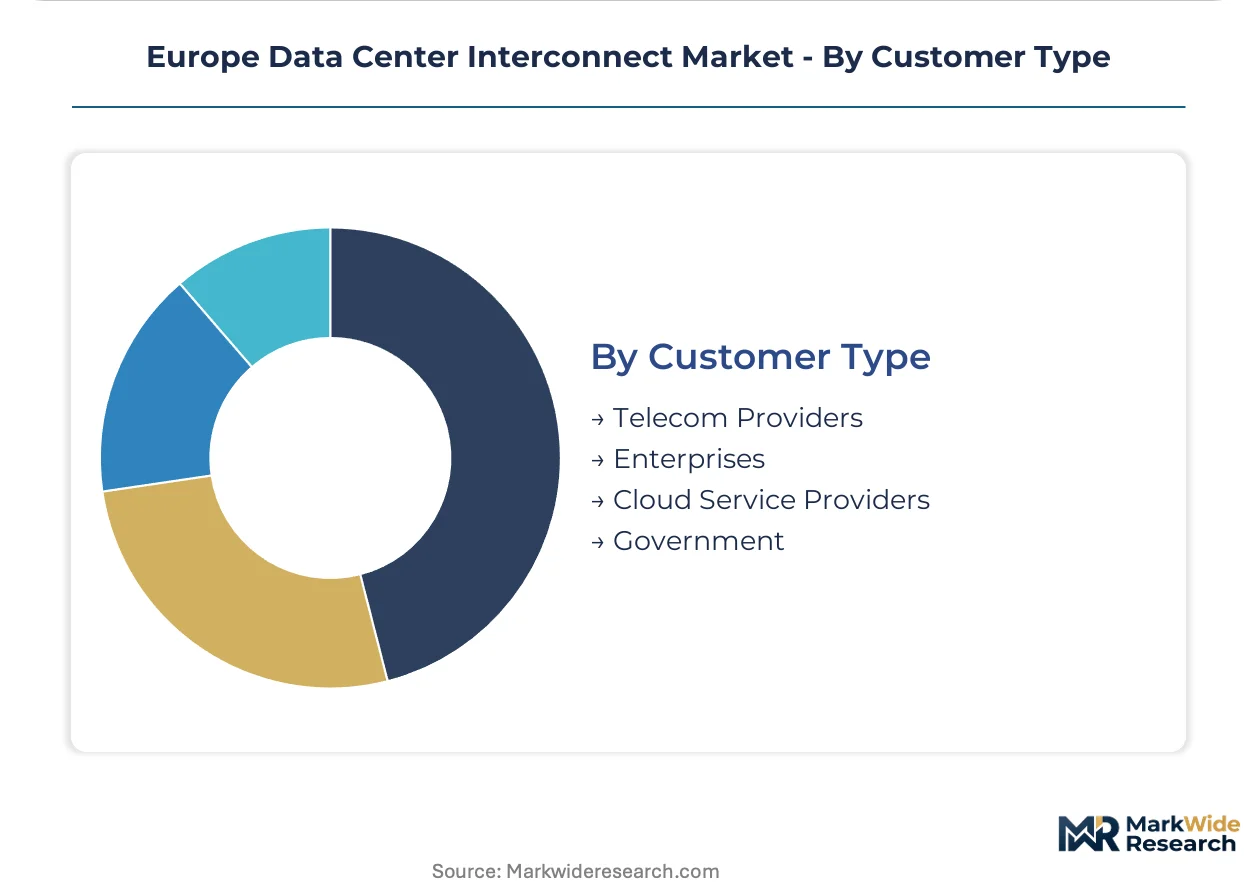
Customer Type:
Customer procurement patterns diverge sharply between wholesale capacity buyers, enterprise risk managers, and sovereign infrastructure operators.
- Cloud Service Providers:Hyperscale operators procure optical transport at 800G wavelengths in multi-terabit volumes, driving coherent pluggable adoption and open optical line system standardization. AWS, Microsoft, and Google facilities in Frankfurt, Paris, and Amsterdam demand sub-10-millisecond synchronous replication for distributed AI training clusters, compressing procurement timelines and forcing vendor interoperability commitments.
- Telecom Providers:Incumbent and alternative carriers monetize fiber assets through wholesale wavelength services and managed optical layer offerings. Deutsche Telekom, Orange, and Liberty Global leverage submarine cable landing positions and metro fiber dominance in Germany and France to gatekeep transatlantic capacity for continental backbones.
- Enterprises:Corporate and mid-market organizations purchase interconnection for disaster recovery, multi-cloud access, and business continuity.
- Government:Sovereign entities procure certified, encrypted optical transport for defense, intelligence, and critical infrastructure interconnection.
Cloud Service Providers command the steepest expansion trajectory. Telecom Providers retain wholesale revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt exports wavelength capacity to Amsterdam and Paris, forming the backbone of continental hyperscale interconnection. Dutch landing stations redistribute transatlantic traffic across German and French fiber backbones.
Germany
Frankfurt's hyperscale campuses demand sub-10-millisecond synchronous replication for distributed AI training clusters. The F-Gas Regulation restricts cooling options for erbium-doped fiber amplifiers along long-haul routes to Hamburg and Munich. North Rhine-Westphalia hosts secondary interconnection nodes in Düsseldorf and Cologne, serving financial services disaster recovery requirements.
Netherlands
Amsterdam's carrier-neutral ecosystem attracts cloud service providers seeking EU Data Act-compliant data portability infrastructure. The Dutch Authority for Digital Infrastructure enforces submarine cable landing station security standards. Rotterdam and Eindhoven emerge as edge deployment targets where land costs undercut Amsterdam premiums.
France
Parisian financial services drive MPLS-based trading floor replication with deterministic latency requirements. ANSSI mandates encryption certifications for cross-border fiber routes under the EU Cybersecurity Act. Île-de-France hyperscale developments cluster around Magny and Stains, feeding interconnection demand toward Frankfurt.
United Kingdom
London's cloud on-ramps serve enterprises navigating post-Brexit data residency obligations. The UK National Cyber Security Centre enforces resilience standards for critical digital infrastructure interconnection. Slough and Docklands data centers anchor transatlantic capacity distribution to continental European backbones.
Poland
Warsaw attracts hyperscale developments where power and land costs undercut Frankfurt premiums by significant margins. The Polish Digital Affairs Ministry aligns national cybersecurity frameworks with ETSI standards for cross-border fiber encryption. Katowice and Kraków host emerging carrier-neutral facilities serving Eastern European latency requirements.
Europe Data Center Interconnect Market Competitive Landscape
On the supply side, the industry is tiered between integrated optical transport vendors, carrier-neutral interconnection operators, and cloud-orchestrated connectivity specialists. Equipment providers compete on coherent DSP programmability and open line system interoperability. Strategic archetypes include wavelength-optimized hardware vendors, meet-me-room real estate controllers, and managed service aggregators. Dominant competitive moves encompass submarine cable consortium participation and metro fiber acquisition.
Within the optical transport tier, Ciena Corporation and Nokia Corporation exemplify divergent architectural philosophies around programmable silicon and IP-over-DWDM convergence. Infinera Corporation occupies a position within the open optical systems segment. Among interconnection infrastructure operators, Equinix and Digital Realty Trust represent the carrier-neutral real estate archetype controlling critical meet-me-room capacity in Frankfurt and Amsterdam.
| Leading Market Players |
|---|
| Ciena Corporation |
| Cisco Systems |
| Juniper Networks |
| Nokia Corporation |
| Huawei Technologies |
| Infinera Corporation |
| Equinix |
| Digital Realty Trust |
| Fujitsu |
| Others |
Supply & Pricing Matrix
F-Gas Regulation compliance costs for erbium-doped fiber amplifier cooling compress pricing spreads between legacy 400G wavelengths and next-generation 800G coherent systems while simultaneously reshaping where amplification hut manufacturing concentrates.
Pricing Analysis
The 800G-to-400G-to-100G technology-generation pricing gap structures procurement decisions across European hyperscale campuses. Managed Services and Cloud Connect offerings command premium positioning against Cross Connects and Dark Fiber due to GDPR-mandated data sovereignty enforcement and EU Cybersecurity Act certification complexity. Cost compression in standard-tier wavelength services intensifies as coherent pluggable optics collapse router-transponder boundaries. Mid-market enterprises exhibit the sharpest price sensitivity, while cloud service providers absorb premium pricing for sub-10-millisecond synchronous replication guarantees.
Supply Chain Analysis
Export-control restrictions on coherent digital signal processor silicon limit flows from United States, Taiwan, and South Korea into European optical transport equipment assembly. DSP photonics, indium phosphide modulators, and specialized cooling subsystems anchor component dependencies. Single-source vulnerability concentrates in programmable silicon foundry capacity. Distribution runs through carrier-neutral colocation operators controlling meet-me-room real estate in Frankfurt and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against wireless millimeter-wave and free-space optical alternatives that threaten to bypass fiber infrastructure for campus-style deployments.
For Market Incumbents: Build switching-cost moats through deep integration of managed wavelength services with EU Cybersecurity Act compliance automation. Incumbents should anchor proprietary optical line systems in open API standardization to neutralize disaggregated routing threats. Capacity expansion into Polish and Romanian hyperscale corridors captures cost-arbitrage demand migrating from Frankfurt premiums.
For New Entrants and Emerging Players: Build out Eastern European edge interconnection nodes where German and Dutch fiber scarcity has not yet concentrated supply. Warsaw and Katowice carrier-neutral facilities represent the most penetrable geography for greenfield meet-me-room real estate. Go-to-market positioning should emphasize EU Data Act portability orchestration as a managed service wedge against incumbent wholesale wavelength offerings.
For Investors and Strategic Acquirers: The EU AI Act's high-risk data localization mandates reshape the acquisition landscape toward encryption-certified optical transport assets. Long-term viability centers on providers controlling submarine cable landing positions and metro fiber pairs in Germany, France, and the Netherlands. Acquisition target archetypes include open optical line system specialists with ETSI-standardized interoperability. The signal to watch is hyperscale cloud provider capex allocation shifts toward Eastern European campus developments.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Optical Line System Certification | ETSI-standardized interoperability reduces vendor lock-in for hyperscale procurement teams. |
| Eastern European Campus Expansion | Polish and Romanian facilities capture cost-arbitrage demand from Frankfurt power premiums. |
| Managed Services Portfolio Buildout | GDPR-mandated data sovereignty outsourcing deepens recurring revenue concentration. |
| Submarine Cable Landing Position Acquisition | Dutch and Portuguese coastal stations gatekeep transatlantic capacity for continental backbones. |
| Quantum-Safe Encryption Overlay Development | ANSSI and BSI mandates for cross-border fiber routes drive certified solution demand. |
Research Methodology
Cross-validation between equipment vendor shipment disclosures and carrier-neutral operator port utilization data anchors the qualitative findings. Primary interviews with optical transport engineers, data center interconnection procurement managers, regulatory compliance officers at German and French telecom incumbents, and hyperscale cloud network architects combined with secondary validation. Secondary sources encompass ETSI standards documentation, EU Cybersecurity Act certification registries, submarine cable consortium filings, and national regulatory authority spectrum and infrastructure reports. Bottom-up wavelength port deployment counts and top-down hyperscale capex allocation analysis triangulate market sizing.
Calibration against historical coherent optics adoption curves and metro fiber construction permitting timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include technology generation, service model, deployment architecture, and customer procurement archetype. CAGRs derive from equipment replacement cycle analysis and managed services contract renewal velocity. Forecast inputs incorporate EU AI Act implementation pacing and F-Gas Regulation compliance cost trajectories.
Stress conditions across coherent DSP supply availability, cross-border fiber permitting delays, and hyperscale cloud demand volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and equipment vendor interoperability commitments. Material shifts in EU Data Act portability mandate interpretation or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Computer Servers Market