
 Data Center Cooling Market | 2026-2036
Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Cooling Market Analysis
Modular cooling packages bundling chillers with in-row units and thermal storage is restructuring procurement patterns for hyperscale buyers. Vertiv leverages its integrated power and thermal portfolio to anchor large retrofit contracts across North American facilities. Schneider Electric competes through prefabricated modular designs that compress deployment timelines for cloud service providers. Daikin sustains manufacturing scale advantages in precision air-conditioning components for enterprise data halls.
Data center cooling encompasses engineered systems that regulate temperature, humidity, and airflow within IT environments, typically maintaining server inlet conditions between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads exceeding 50 kW per rack in high-density configurations. Liquid cooling systems, including direct-to-chip and immersion architectures, are capturing the fastest expansion as GPU clusters push thermal densities beyond air-handling limits. Air cooling remains the volume base but faces margin compression as efficiency standards tighten and refrigerant transitions raise equipment costs. Installation type dynamics favor modular and hybrid approaches for speed-to-market, while new build projects in cloud and colocation segments concentrate the premium solution demand.
The EPA SNAP program and EU F-Gas Regulation are accelerating refrigerant phase-downs and reshaping chiller product roadmaps toward low-GWP chemistries and natural refrigerants. ASHRAE thermal guidelines and ISO 50001 energy management standards further constrain system design choices and validate efficiency claims for market access. Stakeholders must monitor evolving refrigerant compliance deadlines and liquid cooling interoperability standards to avoid stranded asset risk in next-generation facilities.
Market Dynamics
Liquid cooling infrastructure is overtaking conventional air-handling architectures as GPU clusters push rack densities beyond 100 kW, forcing hyperscale operators to reengineer thermal management from the chip level upward.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants is mandating chiller replacements across European facilities, accelerating procurement of low-GWP alternatives and natural refrigerant systems.
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning multi-gigawatt campuses that standardize on liquid-cooled designs for AI training clusters.
- Immersion cooling:Single-phase and two-phase dielectric fluid systems are capturing design wins in cryptocurrency mining and high-performance computing where air cooling fails thermally.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and piping raw material costs swing with commodity markets, compressing margins on precision air-conditioning units.
- Fluorinated fluid supply concentration:Three chemical conglomerates dominate engineered dielectric fluid production, creating single-source risk for immersion cooling deployments.
- ASHRAE thermal guideline lag:The 2021 guidelines still optimize for air-cooled densities, slowing insurance and warranty approvals for liquid-cooled designs exceeding 30 kW per rack.
Strategic Opportunities
- German industrial data halls:Automotive and pharmaceutical manufacturers in Baden-Württemberg and Bavaria are retrofitting legacy facilities with hybrid cooling for digital twin workloads.
- EPA SNAP approval pathways:The program's expanding list of acceptable refrigerants is opening retrofit markets for chillers using R-1234ze and R-513A in US colocation facilities.
- Edge computing convergence:Micro data centers combining modular cooling with on-site power generation are penetrating telecom central offices and manufacturing plant floors.
Industry Challenges
- Thermal-fluid engineering talent scarcity:The specialized skill set spanning heat transfer, materials science, and dielectric chemistry commands premium compensation and extends project timelines.
- Legacy facility integration complexity:Retrofitting 15-20 year old air-cooled data halls with liquid infrastructure requires structural reinforcement, fire suppression redesign, and floor loading analysis.
- ISO 50001 certification timelines:Energy management system audits for large facilities stretch 12-18 months, delaying efficiency claims required for utility incentive programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Cooling Market |
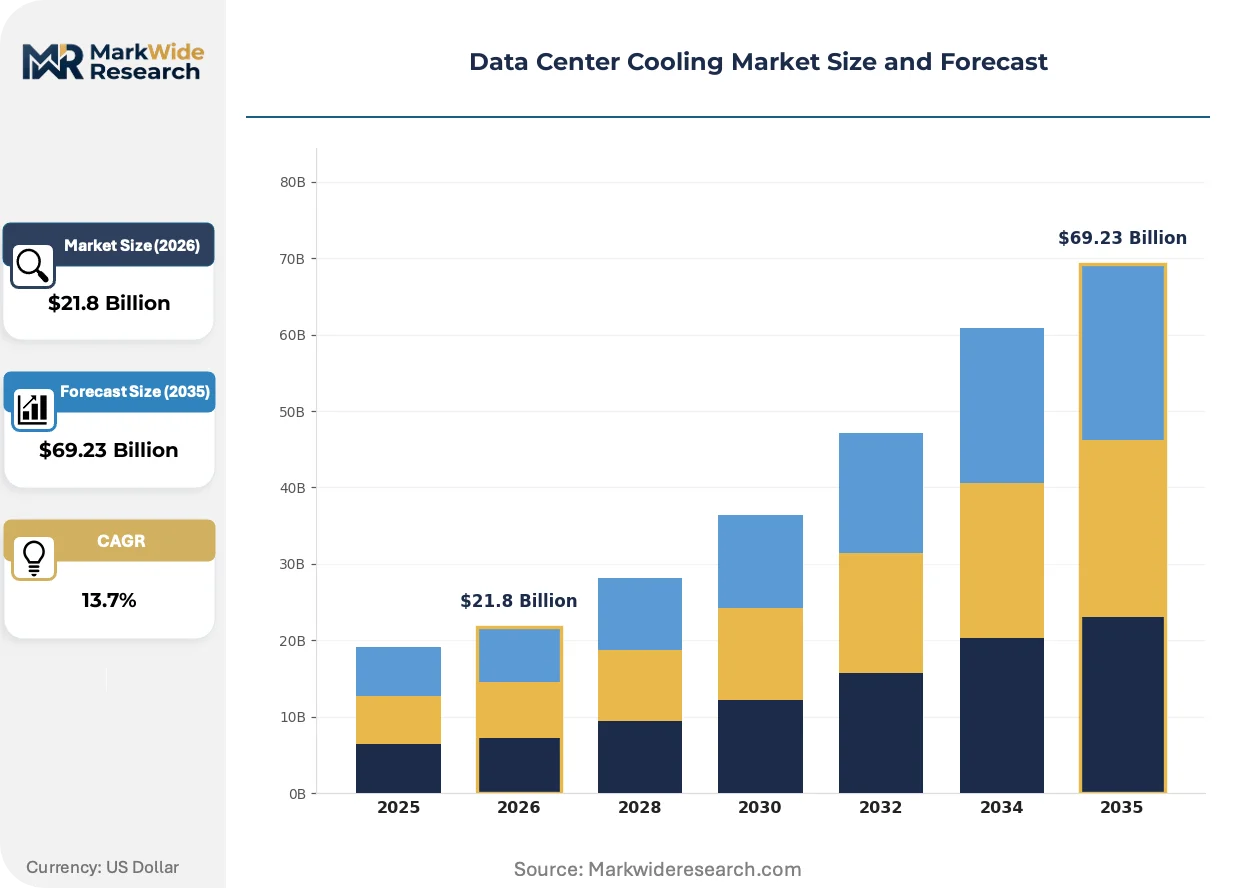
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $69.23 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Liquid Cooling, Air Cooling, Thermal Storage, Evaporative Cooling End User: Colocation Providers, Hyperscale Data Centers, Enterprises, Cloud Service Providers Solution: Chillers, Cooling Towers, Air Handlers, In-Row Cooling Installation Type: Retrofit, New Build, Modular, Hybrid |
| Companies Covered | Daikin, Carrier, Vertiv, Asetek, Trane, Johnson Controls, Danfoss, ZutaCore, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Cooling Market Emerging Trajectories
Direct-to-chip cold plates and two-phase immersion systems are compressing the technology adoption cycle from pilot to production deployment. Three developments are restructuring competitive positioning.
Direct-to-chip liquid cooling is overtaking rear-door heat exchangers as the default architecture for AI training infrastructure. Cold plates bonded to GPU and CPU packages circulate dielectric fluid at temperatures enabling 40°C inlet water, eliminating the energy penalty of chilled water loops. Hyperscale operators in the United States and China are specifying this architecture for all new 50 MW+ builds. The technology is overtaking air-cooled designs in total cost of ownership calculations within three-year depreciation windows.
The EU F-Gas Regulation's 2030 phase-down targets are forcing chiller manufacturers to redesign product lines around R-515B, R-1234ze, and ammonia circuits. Equipment OEMs must recertify entire portfolios under the CE machinery directive, absorbing engineering resources that would otherwise advance liquid cooling development. German and French data center operators face the most compressed compliance timelines, with 2027 refrigerant quota cuts already priced into 2025 procurement decisions.
Cloud service providers are consolidating vendor relationships around integrated power and thermal packages that compress deployment timelines. Single-source accountability for UPS, busway, cooling, and controls is displacing best-of-breed procurement that fragmented responsibility across mechanical and electrical contractors. This pattern concentrates most visibly in Northern Virginia and Frankfurt, where hyperscale clusters exceed 500 MW of simultaneous construction.
Data Center Cooling Market Segmentation
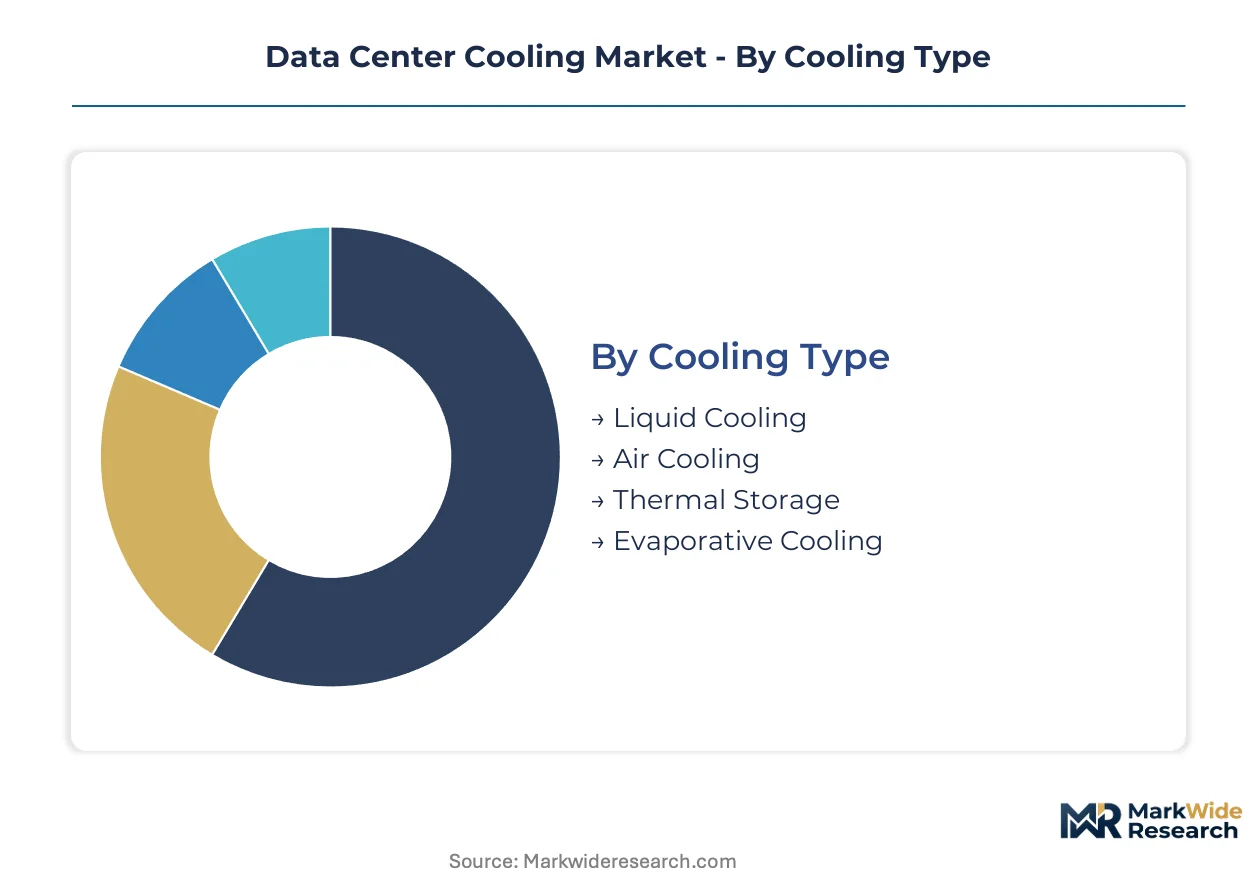
Segmentation in data center cooling reveals how thermal infrastructure procurement splits across divergent compliance burdens, deployment timelines, and density requirements. Understanding these divisions exposes where certification complexity concentrates and which technology bundles command premium positioning.
Cooling Type:
Liquid cooling architectures carry heavier certification loads under ASHRAE thermal guidelines and dielectric fluid safety standards, while air cooling faces EPA SNAP refrigerant approvals and EU F-Gas Regulation recertification cycles.
- Liquid Cooling:Direct-to-chip cold plates and immersion systems circulate engineered dielectric fluids to dissipate GPU cluster heat loads exceeding 100 kW per rack. Hyperscale operators in the United States and China are standardizing this architecture for AI training campuses, driven by total cost of ownership advantages within three-year depreciation windows.
- Air Cooling:Precision air-conditioning units and computer room air handlers maintain server inlet temperatures between 18°C and 27°C through conditioned air distribution. Enterprise data halls in Germany and legacy facilities across North America continue procurement despite margin compression from refrigerant transition costs and efficiency standard tightening.
- Thermal Storage:Ice storage and chilled water tanks shift cooling load to off-peak electricity periods.
- Evaporative Cooling:Adiabatic and direct evaporative systems reduce mechanical refrigeration energy in dry climates.
Air cooling sits at the top of the volume ranking, with liquid cooling climbing the fastest.
End User:
Procurement scale and speed-to-market urgency vary sharply across customer types, from hyperscale multi-gigawatt standardization to enterprise retrofit complexity.
- Hyperscale Data Centers:Amazon Web Services, Microsoft Azure, and Google Cloud commission simultaneous 500 MW+ construction clusters with liquid-cooled designs specified from inception. These operators consolidate vendor relationships around integrated power and thermal packages that compress deployment timelines.
- Cloud Service Providers:Second-tier platforms and regional cloud operators adopt prefabricated modular cooling to match hyperscale efficiency without captive engineering resources.
- Colocation Providers:Multi-tenant facilities in Northern Virginia and Frankfurt balance flexibility across customer density requirements.
- Enterprises:Automotive and pharmaceutical manufacturers in Baden-Württemberg and Bavaria retrofit legacy air-cooled halls with hybrid architectures.
Hyperscale data centers anchor the premium tier by procurement value, while cloud service providers are expanding most quickly.
Solution:
Equipment categories map to distinct supply chain concentrations and refrigerant compliance timelines under regional environmental regulations.
- Chillers:Centrifugal and screw compressor systems face forced redesign under EU F-Gas Regulation 2030 phase-down targets, with manufacturers recertifying portfolios around R-515B, R-1234ze, and ammonia circuits. German and French operators price 2027 quota cuts into 2025 procurement decisions.
- Air Handlers:Fan arrays and filtration systems integrate with chilled water loops or direct expansion refrigerant circuits.
- Cooling Towers:Open and closed circuit evaporative heat rejection equipment serves large-scale central plant configurations.
- In-Row Cooling:Close-coupled units deploy between server racks for targeted heat capture in high-density zones.
Chillers command the largest equipment spend, with in-row cooling gaining share fastest in edge and modular deployments.
Installation Type:
Project delivery models determine how thermal infrastructure interfaces with structural constraints, fire suppression systems, and floor loading limits in existing versus greenfield facilities.
- New Build:Greenfield data centers in Northern Virginia and Frankfurt integrate liquid cooling from architectural design phase, enabling optimized piping infrastructure and waste heat recovery systems without structural compromise.
- Retrofit:15-20 year old air-cooled facilities require structural reinforcement, fire suppression redesign, and floor loading analysis to accommodate liquid infrastructure weight and fluid containment.
- Modular:Prefabricated cooling packages bundle chillers with in-row units and thermal storage for rapid deployment.
- Hybrid:Combined air and liquid architectures bridge legacy infrastructure with next-generation density requirements.
New build captures the dominant share of liquid cooling deployment, with modular installations expanding most quickly in edge computing and telecom central office conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center cooling infrastructure originated in North American enterprise facilities during the 1990s internet buildout, then migrated to hyperscale campuses in the 2010s as cloud computing centralized compute loads. Today thermal management procurement clusters in jurisdictions with dense fiber interconnection, low electricity costs, and permissive zoning for multi-megawatt facilities.
United States
Hyperscale operators commission liquid-cooled designs for AI training clusters exceeding 50 MW in Northern Virginia and Dallas-Fort Worth. The EPA SNAP program accelerates refrigerant transitions toward R-1234ze and R-513A in retrofit colocation facilities. Phoenix and Atlanta data hall construction concentrates procurement of modular cooling packages for rapid deployment timelines.
China
Domestic cloud providers and GPU cluster operators drive demand for direct-to-chip liquid cooling in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor. MIIT energy efficiency standards constrain PUE targets for new data center approvals, favoring advanced thermal architectures. Chongqing and Guiyang facilities integrate evaporative and liquid hybrid systems for reduced mechanical refrigeration load.
Germany
Automotive and pharmaceutical manufacturers in Baden-Württemberg and Bavaria retrofit legacy air-cooled halls with hybrid cooling for digital twin workloads. The EU F-Gas Regulation's 2027 quota cuts compress procurement timelines for low-GWP chillers using R-515B and ammonia circuits. Frankfurt's hyperscale cluster exceeds 500 MW of simultaneous construction with integrated power and thermal packages.
India
Cloud service providers and fintech operators expand capacity in Mumbai and Bangalore despite tropical climate challenges for air-cooled efficiency. CEA data center guidelines mandate energy consumption reporting and cooling efficiency thresholds for facilities above 5 MW. Hyderabad and Chennai campuses adopt modular cooling for speed-to-market in competitive colocation segments.
United Kingdom
Financial services and media streaming operators sustain demand in Slough and London Docklands despite land and power constraints. The Climate Change Agreement scheme rewards facilities achieving PUE targets below 1.4 through advanced cooling architectures. Manchester and Edinburgh edge deployments penetrate telecom central offices with compact liquid-cooled modules.
Data Center Cooling Market Vendor Landscape
The competitive structure tilts toward integrated power and thermal specialists serving hyperscale procurement cycles. Equipment vendors cluster around three capability bundles: precision air-conditioning manufacturing, liquid cooling engineering, and modular system integration. Consolidation pressures concentrate among chiller manufacturers facing EU F-Gas recertification costs, while liquid cooling entrants capture design wins through GPU cluster partnerships. Dominant competitive moves include strategic partnerships with semiconductor foundries and geographic expansion into secondary cloud markets.
Within the integrated infrastructure tier, Vertiv and Schneider Electric exemplify full-stack positioning spanning electrical distribution and thermal management. Daikin occupies a position representing precision air-conditioning manufacturing scale for enterprise data hall retrofits. These three anchors illustrate how vendor selection increasingly favors single-source accountability over fragmented mechanical and electrical contracting arrangements.
| Leading Market Players |
|---|
| Daikin |
| Carrier |
| Vertiv |
| Asetek |
| Trane |
| Johnson Controls |
| Danfoss |
| ZutaCore |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Captive dielectric fluid production by Vertiv and Schneider Electric anchors both supply security and pricing power for liquid-cooled infrastructure, insulating integrated vendors from commodity volatility while compressing margins for air-conditioning specialists facing refrigerant transition costs.
Pricing Analysis
Project-based contract pricing with performance guarantees dominates hyperscale procurement, separating integrated power-thermal packages from standalone chiller transactions. Price differentiation hinges on ASHRAE certification tier and volume scale, with multi-gigawatt buyers extracting steepest discounts. Cost compression in precision air-conditioning is intensifying because EU F-Gas recertification engineering absorbs R&D budgets. Cloud service providers exhibit highest price sensitivity; GPU cluster operators prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Dual-sourcing mandates from AWS and Microsoft Azure require qualified second sources for cold plates and dielectric fluids, fragmenting procurement across domestic and Asian suppliers. Manufacturing concentrates in the United States, Germany, and China for precision components; Taiwan and South Korea anchor semiconductor-grade heat spreader supply. Raw material dependencies span copper heat exchangers, aluminum fin arrays, and engineered fluorinated fluids. Single-source vulnerability concentrates in dielectric chemistry where three chemical conglomerates dominate. Distribution runs through direct OEM relationships for hyperscale, regional integrators for enterprise retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory-driven replacement cycles, with the EU F-Gas Regulation's 2030 phase-down forcing premature chiller retirements across European facilities.
For Market Incumbents: Anticipate margin compression in air-cooled portfolios by accelerating backward integration into dielectric fluid formulation and cold plate machining. Vertiv and Schneider Electric should defend their integrated positioning through captive engineering resources that match hyperscale deployment velocities. Threat substitution from two-phase immersion entrants demands R&D prioritization of chip-level thermal interfaces. For New Entrants and Emerging Players: The price-point gap between premium liquid-cooled systems and legacy air-handling retrofits opens white-space in hybrid cooling for German automotive and pharmaceutical facilities. Edge computing micro data centers in telecom central offices represent the most penetrable segment. A go-to-market angle bundling modular cooling with on-site power generation bypasses incumbent electrical-thermal fragmentation. For Investors and Strategic Acquirers: Roll-up economics work for regional liquid-cooling specialists because certification complexity under ASHRAE and dielectric fluid safety standards creates defensible moats. Target mid-cap engineering firms with GPU cluster deployment experience and existing foundry partnerships. Watch hyperscale capital expenditure announcements as the inflection signal for thermal infrastructure procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Portfolio Transition | Chiller OEMs recertify around R-515B and ammonia to meet EU F-Gas 2030 targets. |
| Liquid Cooling Engineering Acquisition | Integrated infrastructure vendors capture GPU cluster design wins through thermal-fluid talent. |
| Modular System Integration | Prefabricated packages compress deployment timelines for cloud service providers in Northern Virginia. |
| Dielectric Fluid Supply Agreement | Long-term offtake contracts with chemical suppliers mitigate single-source concentration risk. |
| Edge Computing Partnership | Cooling vendors penetrate telecom central offices through compact liquid-cooled module alliances. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, hyperscale procurement officers, thermal-fluid R&D leads, and chiller OEM product managers with secondary validation against SEC filings, hyperscaler capex disclosures, ASHRAE technical standards, and EPA SNAP regulatory dockets. Bottom-up installation tracking and top-down infrastructure spend estimates triangulated market sizing.
Comparable-period anchoring calibrated the projection horizon against historical hyperscale construction cycles and refrigerant phase-down compliance deadlines. Segmentation modeling spanned cooling architecture, end-user type, solution category, and installation method. CAGRs derived from density-driven technology substitution curves and regulatory replacement pull-forwards. Forecast inputs incorporated GPU cluster thermal design power trajectories and regional electricity cost differentials.
Caveats apply where ASHRAE guideline revisions or dielectric fluid safety standard updates could materially shift the outlook. Deviation in hyperscale AI training cluster deployment schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market