
 Netherlands Data Center Networking Market | 2026-2036
Netherlands Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Networking Market Insights
Amsterdam's metropolitan fiber ring is reconfiguring interconnection density across North Holland's digital infrastructure cluster. Cisco Systems Inc. leverages its entrenched enterprise channel to sustain switching revenue in Dutch banking and trading venues. Juniper Networks Inc. differentiates through carrier-grade routing specialization at AMS-IX peering points. Arista Networks, Inc. dominates cloud-scale deployments with low-latency leaf-spine architectures for local hyperscale tenants.
Data center networking encompasses the switching, routing, and interconnect fabric that enables server-to-server, server-to-storage, and external traffic exchange within and between compute facilities, typically operating at speeds from 10 Gbps to 800 Gbps with latency budgets under microseconds for intra-rack connections. Its primary purpose is to deliver deterministic bandwidth, fault isolation, and programmable traffic engineering for virtualized workloads, AI training clusters, and distributed storage pools. Ethernet switching captures the largest installed base among product types due to universal compatibility with cloud orchestration stacks, while InfiniBand technology leads growth velocity as Dutch research institutions and AI labs adopt NVIDIA's end-to-end interconnect strategy. Enterprise end users represent the most fragmented buyer segment, creating margin pressure for vendors without vertical workflow integration.
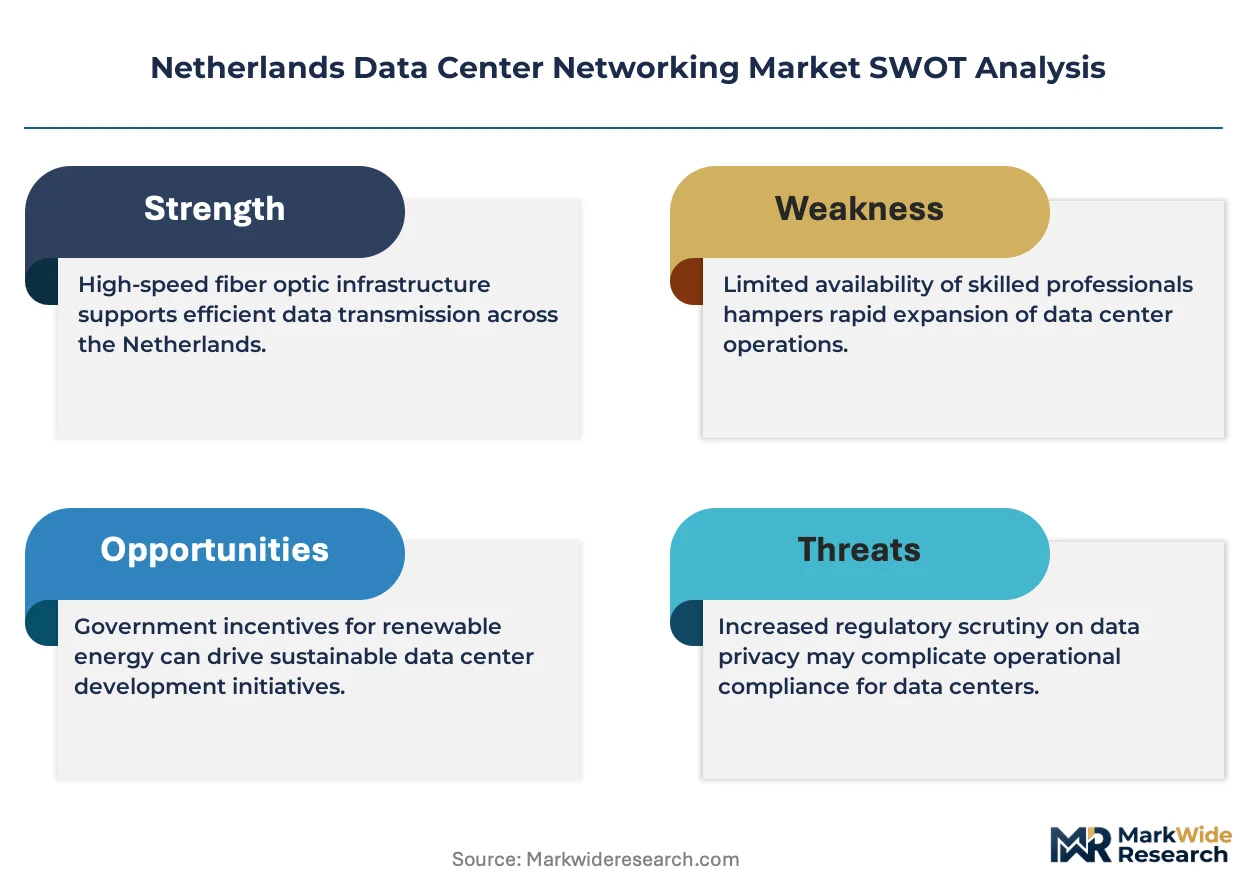
The Dutch Authority for Digital Infrastructure and the Netherlands Enterprise Agency shape procurement standards through national cybersecurity certification schemes and energy efficiency disclosure requirements for critical digital infrastructure. BIS and ISO 27001 compliance frameworks further constrain vendor selection for government and financial end users, elevating documentation and audit costs for market entrants. Stakeholders must monitor whether proposed EU AI Act infrastructure obligations will mandate real-time network telemetry and explainability hooks in Dutch AI training clusters.
Market Dynamics
Dutch financial institutions face escalating DNB operational resilience mandates that compel software-defined networking overhauls across primary and secondary data center sites. This regulatory compression is restructuring procurement priorities toward programmable fabrics with embedded telemetry.
Growth Catalysts
- DNB Operational Resilience Mandates:Dutch financial regulators require redundant network paths and sub-second failover capabilities, forcing incumbent banks to modernize core switching infrastructure.
- Hyperscale Corridor Expansion:Amsterdam's Schiphol-Rijk and Science Park clusters attract concentrated cloud provider investment, driving demand for 400G/800G optical interconnects.
- AI Training Cluster Proliferation:Dutch research institutions and semiconductor labs deploy high-radix InfiniBand fabrics to support large language model training workloads.
Market Restraints
- Optical Component Supply Concentration:Coherent DSP and silicon photonics sourcing depends on a limited supplier base concentrated in East Asian foundries, creating delivery volatility for Dutch integrators.
- Energy Infrastructure Bottlenecks:North Holland grid interconnection queues delay new data center energization, compressing revenue recognition timelines for networking deployments.
- Specialized Engineering Talent Scarcity:Domestic universities produce insufficient optical networking and network automation specialists relative to deployment demand.
Strategic Opportunities
- Edge Computing Satellite Facilities:Rotterdam and Eindhoven industrial zones present underdeveloped colocation sites requiring distributed switching architectures.
- EU AI Act Telemetry Requirements:Proposed real-time network monitoring mandates for AI training infrastructure create embedded software and hardware certification opportunities.
- Sustainability-Linked Procurement:CSRD disclosure obligations push enterprise buyers toward vendors with validated Scope 3 emissions data for networking equipment.
Industry Challenges
- Multi-Vendor Automation Integration:Dutch enterprises struggle to unify Ansible, Terraform, and vendor-native APIs across heterogeneous switching estates.
- ISO 27001 Certification Timelines:Security audit backlogs delay go-live dates for government and healthcare networking projects.
- Legacy MPLS Migration Complexity:Incumbent carriers face stranded asset risks when transitioning enterprise customers to EVPN-VXLAN fabrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Networking Market |
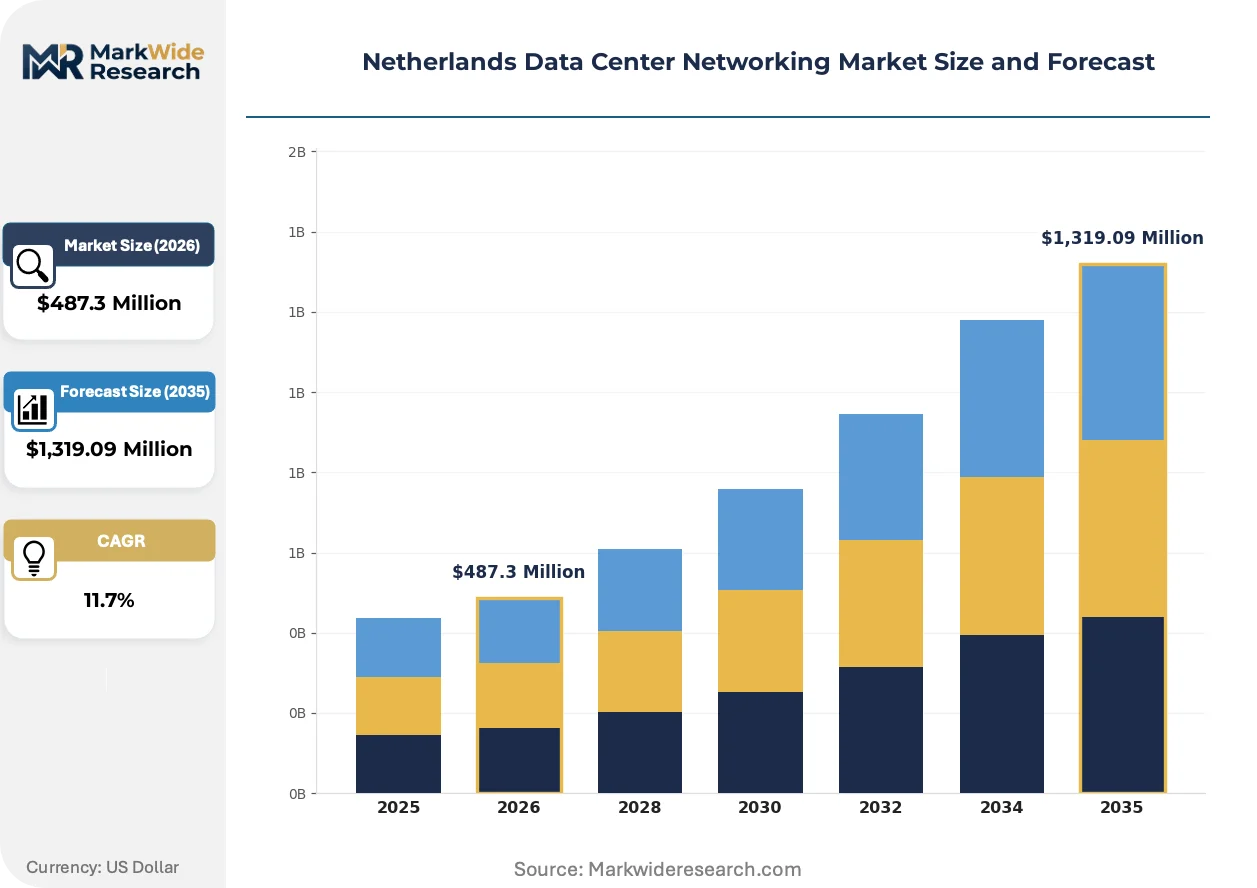
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Adapters, Cables Technology: Ethernet, Fiber Channel, InfiniBand, MPLS End User: Cloud Providers, Enterprises, Colocation Facilities, Government Installation: On-premises, Hybrid, Remote, Others |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Arista Networks, Inc., Dell Technologies Inc., Huawei Technologies Co., Ltd., Extreme Networks, Inc., Hewlett Packard Enterprise, Broadcom Inc., NVIDIA Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Networking Market Trends and Innovations
Network virtualization is collapsing traditional hardware boundaries as Dutch enterprises adopt cloud-native operating models. Three developments are restructuring competitive requirements.
SmartNICs and DPUs are virtualizing server-side networking functions that previously consumed dedicated switch ports and CPU cycles. Dutch cloud providers and high-frequency trading venues are deploying these accelerators at rack scale to reduce latency and free compute resources for revenue-generating workloads. This virtualization is compressing the addressable market for standalone top-of-rack switches in performance-sensitive deployments.
DNB cross-border operational resilience guidelines are mandating geographic separation of active network paths between Dutch primary sites and failover locations in Germany or Belgium. Financial institutions must document traffic engineering policies and conduct quarterly resilience testing. Large Dutch banks are responding by diversifying carrier contracts and deploying software-defined WAN controllers with automated path computation.
Enterprise buyers are consolidating networking procurement under infrastructure platform teams rather than siloed network operations groups. This organizational shift elevates vendors with robust API ecosystems and cloud orchestration integrations. Dutch mid-market enterprises show the fastest adoption of this model, often bypassing traditional value-added resellers for direct vendor relationships with consumption-based licensing.
Netherlands Data Center Networking Market Segmentation
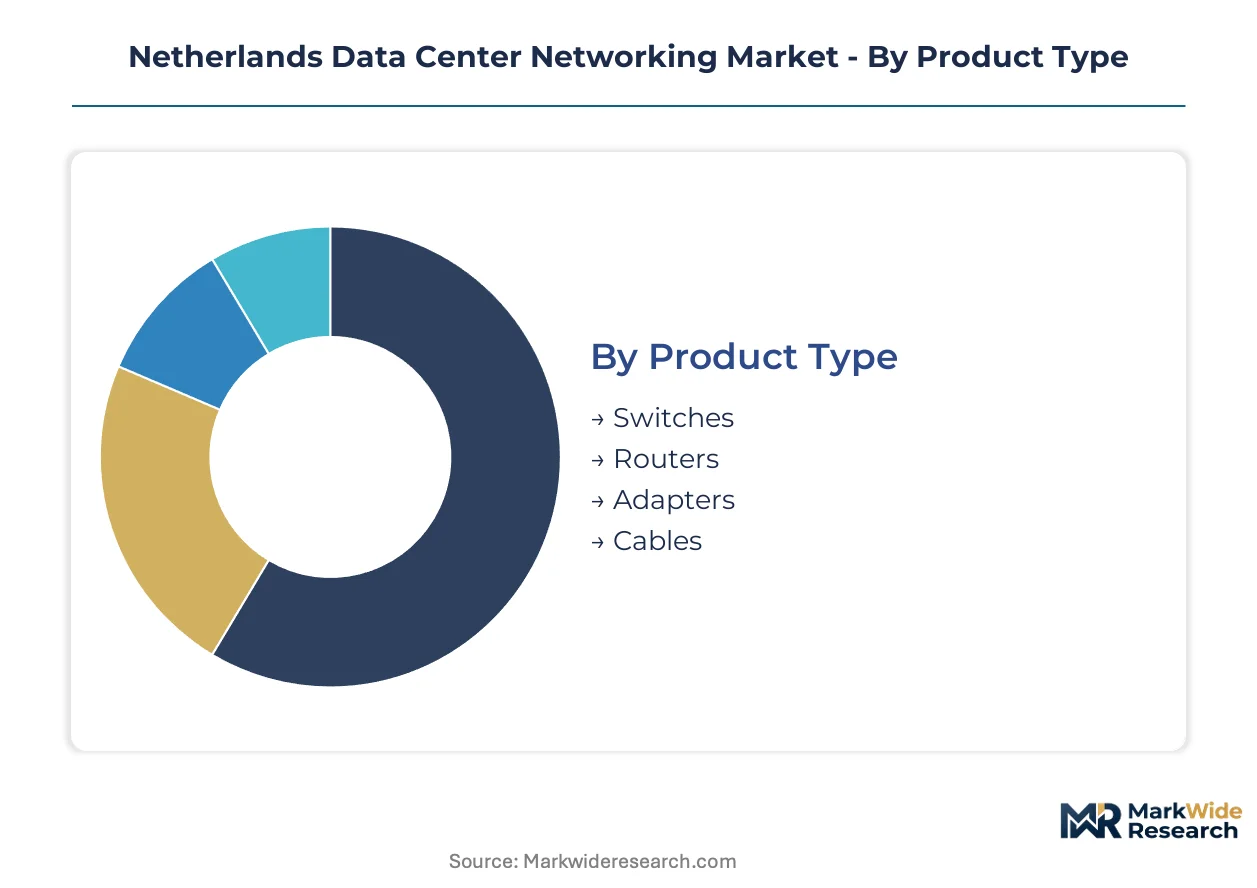
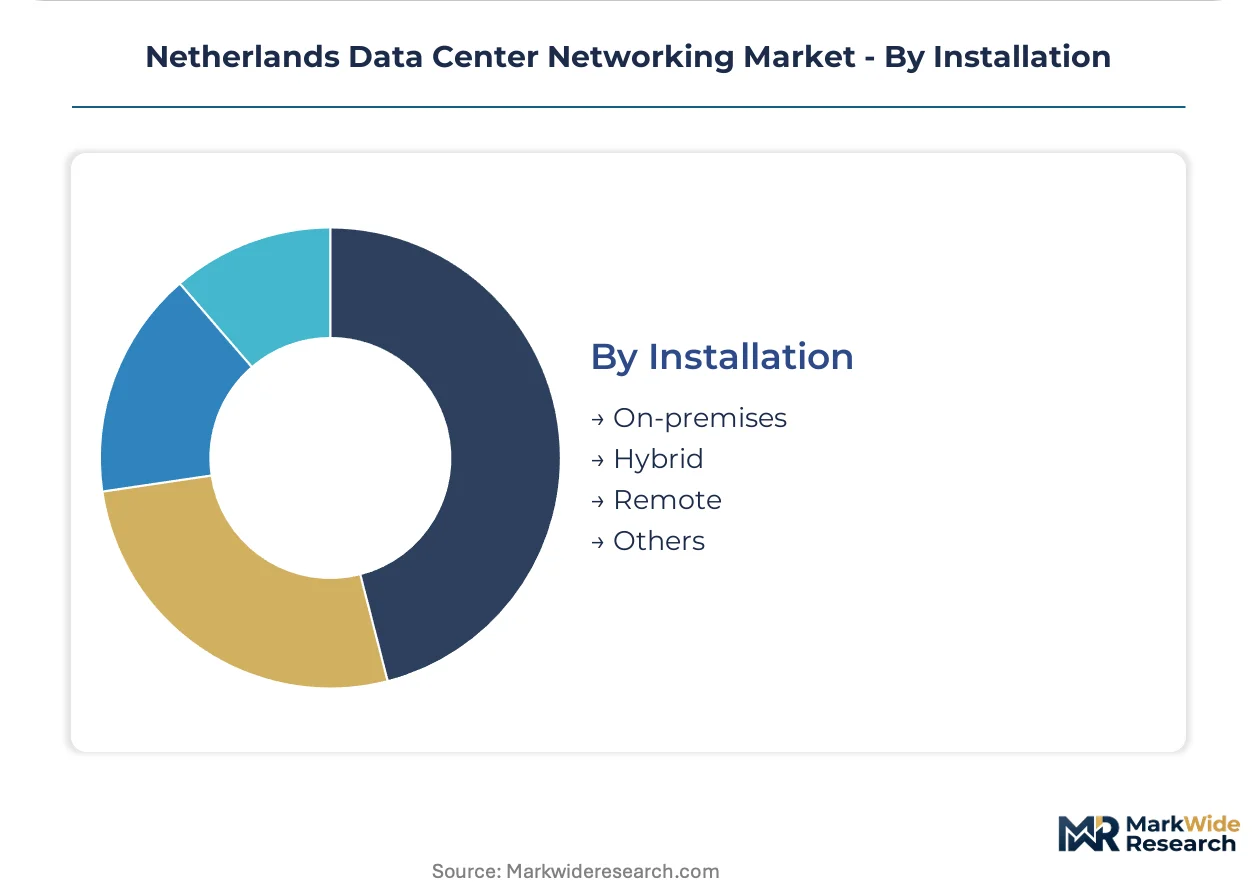
Segmentation reveals how procurement patterns diverge across Dutch data center networking deployments. Technology choices and installation models are restructuring as DNB mandates and hyperscale expansion reshape infrastructure requirements.
Product Type:
Mature switching hardware dominates installed value while emerging interconnect components capture expansion investment.
- Switches:Ethernet switches from 1G to 800G ports form the backbone of Dutch data center fabrics, with leaf-spine architectures now standard at Amsterdam hyperscale facilities. Dutch financial institutions prioritize switches with embedded telemetry to satisfy DNB operational resilience audit requirements.
- Routers:Carrier-grade routers manage inter-facility and WAN connectivity, with programmable routing tables enabling automated failover between North Holland primary sites and German or Belgian disaster recovery locations.
- Adapters:SmartNICs and DPUs are virtualizing server-side network functions at Dutch cloud providers and high-frequency trading venues, reducing top-of-rack switch port density requirements.
- Cables:Active optical cables and direct attach copper interconnects span intra-rack and inter-rack distances across Dutch colocation facilities.
Switches retain volume leadership; adapters hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity Ethernet deployments from premium low-latency interconnects.
- Ethernet:Universal compatibility with cloud orchestration stacks makes Ethernet the default for Dutch enterprise and hyperscale deployments, with 400G now standard and 800G emerging at AI training clusters.
- InfiniBand:NVIDIA's end-to-end interconnect strategy is gaining traction at Dutch research institutions and semiconductor labs running large language model training workloads, commanding premium pricing for sub-microsecond latency.
- Fiber Channel:Storage area network connectivity persists in legacy Dutch enterprise data centers, though adoption is plateauing as NVMe-over-TCP displaces dedicated storage fabrics.
- MPLS:Incumbent carriers face stranded asset risks as Dutch enterprises migrate WAN connectivity to EVPN-VXLAN overlays and SD-WAN controllers.
Ethernet maintains installed base dominance; InfiniBand is expanding most quickly among Dutch AI infrastructure deployments.
End User:
Customer type determines procurement sophistication and vendor relationship structures across the Dutch market.
- Cloud Providers:Hyperscale tenants at Amsterdam's Schiphol-Rijk and Science Park clusters drive 400G/800G optical interconnect demand through direct vendor relationships and consumption-based licensing models.
- Enterprises:Fragmented buyer segment spanning Dutch mid-market firms to multinational headquarters, with infrastructure platform teams consolidating networking procurement under cloud-native operating models.
- Colocation Facilities:Interconnection density at Amsterdam metropolitan fiber ring sites is reconfiguring as cross-connect and metro wavelength services expand.
- Government:BIS and ISO 27001 compliance frameworks constrain vendor selection, with security audit backlogs delaying project timelines at national and municipal levels.
Cloud providers anchor high-end volume; enterprises represent the most fragmented addressable base.
Installation:
Deployment model reflects organizational cloud maturity and regulatory data sovereignty requirements.
- On-premises:Dutch financial institutions and government agencies maintain primary network infrastructure on-site to satisfy DNB operational resilience mandates and data localization requirements.
- Hybrid:Split traffic engineering across private facilities and public cloud is becoming standard for Dutch enterprises, requiring consistent network policies across boundary zones.
- Remote:Edge computing satellite facilities in Rotterdam and Eindhoven industrial zones are deploying distributed switching architectures for latency-sensitive workloads.
- Others:Specialized deployment models including sovereign cloud and classified environments serve Dutch defense and intelligence community requirements.
On-premises retains compliance-driven dominance; hybrid is gaining share fastest as Dutch enterprises rebalance cloud strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DNB operational resilience mandates anchor procurement standards across Dutch sub-regions, with North Holland's hyperscale corridor driving concentrated infrastructure investment and provincial grid constraints shaping deployment timelines.
Randstad
Amsterdam's metropolitan fiber ring concentrates interconnection density at Schiphol-Rijk and Science Park clusters. Dutch Authority for Digital Infrastructure certification schemes constrain vendor selection for financial institutions headquartered in the capital. Cloud providers deploy 400G/800G optical interconnects at Amsterdam colocation facilities to serve pan-European traffic exchange.
Brabant
Eindhoven's semiconductor ecosystem generates specialized demand for low-latency fabrics at AI research labs and photonics foundries. CSRD disclosure obligations push enterprise buyers toward vendors with validated Scope 3 emissions data. High-frequency trading venues at Tilburg industrial zones deploy SmartNICs to reduce latency and free compute resources.
Northern Netherlands
Groningen and Friesland data center projects face extended grid interconnection queues that compress revenue recognition timelines for networking deployments. National cybersecurity certification schemes elevate documentation costs for market entrants seeking government contracts. Edge computing satellite facilities in Leeuwarden deploy distributed switching architectures for latency-sensitive agricultural technology workloads.
Netherlands Data Center Networking Market Competitive Landscape
Enterprise networking specialists and cloud-scale fabric providers split the market between incumbent channel relationships and direct hyperscale procurement. The vendor base concentrates around three strategic archetypes: legacy enterprise platforms with entrenched financial services channels, carrier-grade routing specialists peering at internet exchange points, and low-latency cloud-scale architects serving AI training clusters. Dominant competitive moves include strategic partnerships with Dutch system integrators and portfolio diversification into software-defined WAN controllers.
Within the enterprise platform tier, Cisco Systems Inc. and Dell Technologies Inc. occupy positions sustained by long-standing banking and trading venue relationships. Juniper Networks Inc. exemplifies the carrier-grade specialization archetype at AMS-IX peering infrastructure. Arista Networks, Inc. anchors the cloud-scale vector through direct relationships with Amsterdam hyperscale tenants.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Arista Networks, Inc. |
| Dell Technologies Inc. |
| Huawei Technologies Co., Ltd. |
| Extreme Networks, Inc. |
| Hewlett Packard Enterprise |
| Broadcom Inc. |
| NVIDIA Corp. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at East Asian silicon photonics foundries is compressing lead times for coherent DSP modules and amplifying pricing leverage among Dutch optical component distributors serving Amsterdam hyperscale corridors.
Pricing Analysis
Amsterdam-to-Rotterdam price spreads for 400G optical transceivers reveal geographic delivery cost as the dominant differentiation driver alongside volume scale commitments from cloud providers. Three-tier pricing structure across premium InfiniBand, standard Ethernet, and economy copper interconnect levels stratifies procurement budgets across Dutch financial institutions and research labs. Cost compression in mid-range Ethernet switching is intensifying because SmartNIC virtualization reduces standalone top-of-rack switch port density requirements. Cloud providers exhibit the lowest price sensitivity due to consumption-based licensing models, while fragmented Dutch mid-market enterprises negotiate aggressively on per-port costs.
Supply Chain Analysis
Extended payment terms from Dutch system integrators to Taiwanese and South Korean optical component suppliers signal working capital stress rippling through the procurement chain. Coherent DSP silicon, silicon photonics wafers, and high-speed electrical connectors draw from concentrated East Asian manufacturing hubs. Single-source vulnerability around 800G optical engine production creates exposure for Dutch integrators awaiting AMS-IX expansion timelines. Distribution runs through authorized distributor networks and direct vendor relationships with Amsterdam hyperscale tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring vendor-customer relationships as Dutch enterprises consolidate networking procurement under infrastructure platform teams and demand API-native interoperability across switching estates.
For Market Incumbents: Pre-empt displacement by SmartNIC virtualization through embedded telemetry partnerships with Dutch financial institutions facing DNB audit requirements. Deepen backward integration into software-defined WAN controller development to capture cross-border operational resilience spending. Channel control at AMS-IX peering points remains critical for carrier-grade routing specialists. For New Entrants and Emerging Players: Edge computing satellite facilities in Rotterdam and Eindhoven industrial zones represent the most penetrable entry point for distributed switching architectures underserved by incumbent channel structures. Dutch mid-market enterprises bypassing traditional value-added resellers for direct vendor relationships create openings for API-first networking vendors. A consumption-based licensing go-to-market angle aligns with infrastructure platform team procurement consolidation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across InfiniBand fabric deployments for Dutch AI training clusters as NVIDIA's end-to-end interconnect strategy commands premium positioning. Acquisition targets with validated Scope 3 emissions data and CSRD disclosure capabilities will outcompete peers in enterprise sustainability-linked procurement cycles. Watch for EU AI Act telemetry mandate finalization as an inflection signal for embedded software certification opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| SmartNIC Virtualization Partnership | Reduces standalone switch port density requirements at Dutch high-frequency trading venues. |
| DNB Compliance Certification Investment | Unlocks Dutch financial institution procurement budgets for embedded telemetry fabrics. |
| Edge Computing Facility Expansion | Captures latency-sensitive workloads in Rotterdam and Eindhoven industrial zones. |
| API-First Platform Integration | Aligns with Dutch enterprise infrastructure platform team consolidation trends. |
| Sustainability Data Validation Program | Meets CSRD disclosure obligations for Dutch enterprise Scope 3 procurement requirements. |
Research Methodology
Cross-validation between primary interviews with data center infrastructure directors, network automation engineers, procurement officers at Dutch financial institutions, and cloud provider platform architects anchors the qualitative findings. Secondary validation draws from SEC filings of networking equipment vendors, hyperscaler capex disclosures, AMS-IX traffic statistics, and DNB regulatory guidance documents. Bottom-up installation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical deployment trajectories at Amsterdam Schiphol-Rijk and Science Park clusters informs the projection framework. Segmentation dimensions span product type, technology protocol, end-user archetype, and installation model across the modeling period. CAGRs derive from regression analysis of port shipment velocities and average selling price trends. InfiniBand adoption curves at Dutch semiconductor labs and DNB-mandated failover architecture requirements constitute industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rates, energy infrastructure investment cycles, or East Asian foundry utilization would shift the trajectory. Forecasts reflect documented assumptions around regulatory timeline adherence and supply chain normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Sweden Data Center Networking Market