
 Nvme Over Fiber Channel Market | 2026-2036
Nvme Over Fiber Channel Market Size, Share, and Industry Trends Forecast 2026-2036
Nvme Over Fiber Channel Market Outlook
The capital-intensity divergence between ASIC-focused incumbents and fabless challengers is unwinding competitive stability in NVMe over Fibre Channel controller supply. Broadcom Inc. leverages captive semiconductor fabrication to sustain margin structures that fabless rivals cannot replicate. Marvell Technology anchors its position through vertical integration into custom silicon for enterprise storage arrays. Cisco Systems competes by extending its Fibre Channel switching portfolio into converged NVMe-oF fabrics.
NVMe over Fibre Channel denotes a storage protocol mapping the NVM Express command set onto Fibre Channel transport layers, typically operating at 32 Gbps or 64 Gbps link speeds with sub-100 microsecond latency targets. The architecture enables disaggregated flash storage pools to appear as local block devices to host servers, eliminating SCSI protocol overhead in high-performance computing and transactional database environments. Adapters and controllers command the dominant hardware margin pools as data centers prioritize deterministic latency over raw bandwidth expansion. Cloud Service Providers represent the fastest-growing end-user segment, though Enterprises still occupy the largest absolute revenue base due to refresh cycles in existing Fibre Channel fabrics.
FCC equipment authorization rules govern electromagnetic emissions for NVMe-oF adapters sold in the United States, while the EU AI Act and GDPR impose data locality requirements that favor on-premises and hybrid deployment architectures over public cloud migration. ISO/IEC 24762 business continuity standards and the INCITS T11 Fibre Channel protocol specifications shape procurement criteria for financial services and healthcare buyers. Stakeholders must monitor how PCI-SIG roadmap acceleration toward PCIe 6.0 retimers influences controller refresh cadences and stranded asset risk in installed base upgrades.
Market Dynamics
PCI Express 5.0 and 6.0 interconnect transitions are forcing controller and adapter redesigns across the supply base, compressing refresh cycles while stranding prior-generation hardware investments in hyperscale facilities.
Growth Catalysts
- Hyperscale facility construction:Northern Virginia and Dallas-Fort Worth data center clusters are absorbing NVMe-oF infrastructure at unprecedented density, pulling adapter and controller demand forward.
- EU AI Act data locality mandates:Enterprise buyers in Frankfurt and Amsterdam are retaining on-premises flash storage pools rather than migrating to public cloud, preserving Fibre Channel fabric refresh budgets.
- INCITS T11 protocol specifications:Financial services procurement committees in Singapore and Sydney are mandating sub-100 microsecond latency guarantees that only native NVMe-oF transport layers deliver.
Market Restraints
- Retimer silicon shortage:PCIe 6.0 signal conditioning components from TSMC's advanced nodes face allocation constraints, extending controller lead times to 26 weeks.
- FCC equipment authorization timelines:Electromagnetic compliance testing for 64 Gbps adapters adds 4-6 months to US market entry, disadvantaging challengers against incumbent certification portfolios.
- RoHS substance restrictions:Solder alloy reformulations for high-speed connectors increase manufacturing yield loss, compressing gross margins on adapter hardware.
Strategic Opportunities
- Healthcare imaging archives:PACS vendors in Seoul and Melbourne are adopting disaggregated NVMe-oF storage for real-time radiology workflows, opening a vertical previously served by DAS arrays.
- CSRD disclosure requirements:European enterprise buyers must document data center energy efficiency, favoring NVMe-oF's power-per-IOP advantage over legacy SCSI fabrics.
- Edge AI inference clusters:Tier-2 cloud operators in São Paulo and Johannesburg are deploying converged NVMe-oF fabrics to serve low-latency model serving without core network dependency.
Industry Challenges
- Fibre Channel zoning expertise scarcity:Storage administrators capable of configuring 64 Gbps fabric segmentation command 40% salary premiums, constraining deployment velocity at mid-market enterprises.
- Interoperability certification backlog:Multi-vendor SAN qualification testing for PCI-SIG compliance extends product launch windows by two quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nvme Over Fiber Channel Market |
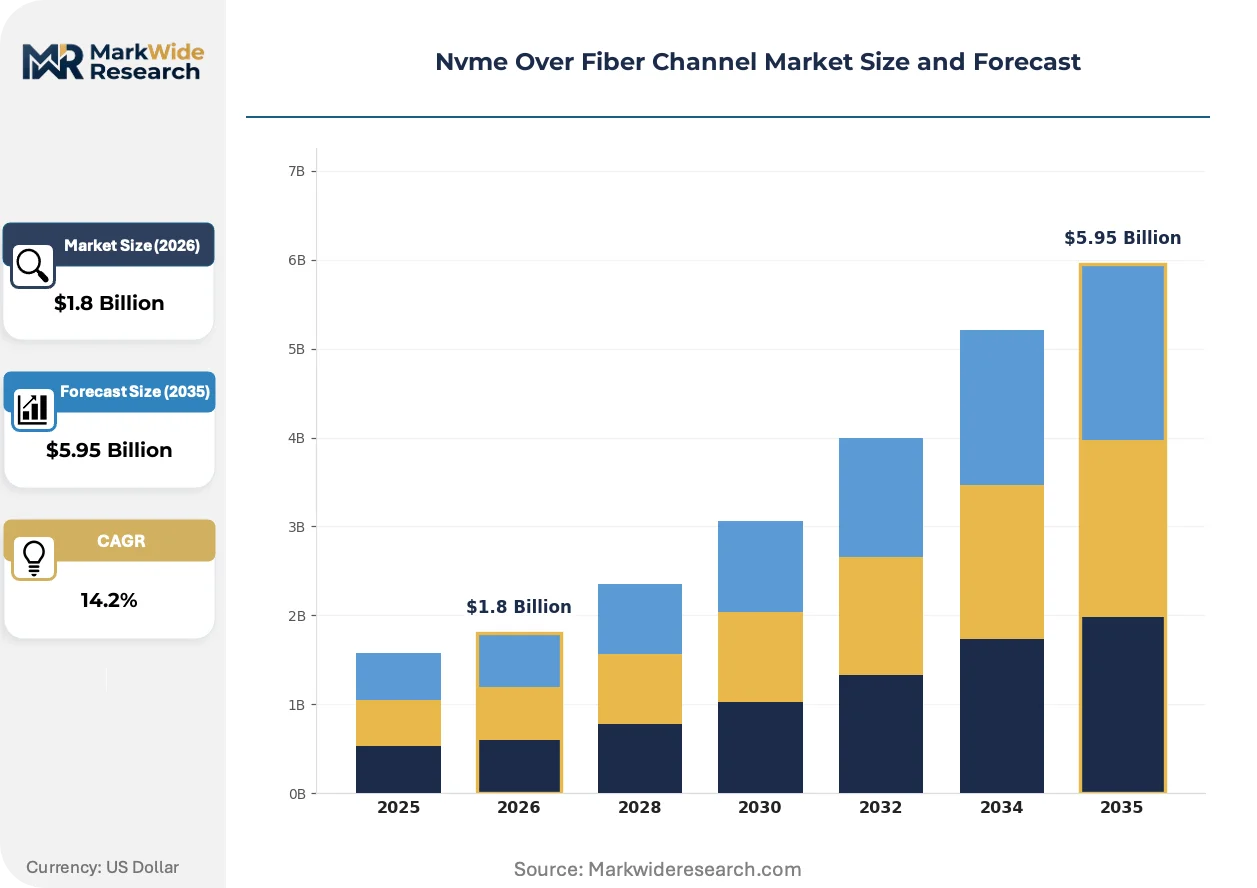
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Controllers, Adapters, Storage Devices End User: Cloud Service Providers, Enterprises, Government, Data Centers Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud Service Type: Managed Services, Professional Services, Technical Support, Maintenance |
| Companies Covered | Broadcom Inc., Cisco Systems, Hewlett Packard Enterprise, Dell Technologies, IBM Corporation, Intel Corporation, NetApp, Marvell Technology, ATTO Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nvme Over Fiber Channel Market Strategic Shifts
Protocol convergence and silicon integration are collapsing the traditional separation between network interface cards and storage controllers, redrawing competitive boundaries across the hardware stack.
Computational storage processors with integrated NVMe-oF offloads are supplanting discrete HBA architectures in hyperscale deployments. Meta Platforms and Microsoft Azure have specified these consolidated controllers for 2025 server refresh cycles. The structural compression of adapter margins is forcing Broadcom and Marvell to absorb retimer and PHY functions into single-die designs.
Japan's METI semiconductor subsidy framework is redirecting domestic foundry capacity toward PCIe 6.0 retimer production, prioritizing storage networking silicon over consumer GPU allocation. This industrial policy consequence tightens supply for non-Japanese controller vendors while accelerating Tokyo Electron's test equipment deployment. Korean memory suppliers are responding by qualifying domestic retimer sources for their Gen5 SSD controller roadmaps.
Cloud service provider procurement committees are unbundling hardware acquisition from professional services, awarding adapter contracts to direct ODM relationships rather than distribution channel partners. This disintermediation compresses reseller margins by 15-20 points across North American and European markets. Systems integrators in London and Amsterdam are pivoting toward firmware customization and fabric tuning services to recover revenue displacement.
Nvme Over Fiber Channel Market Segmentation
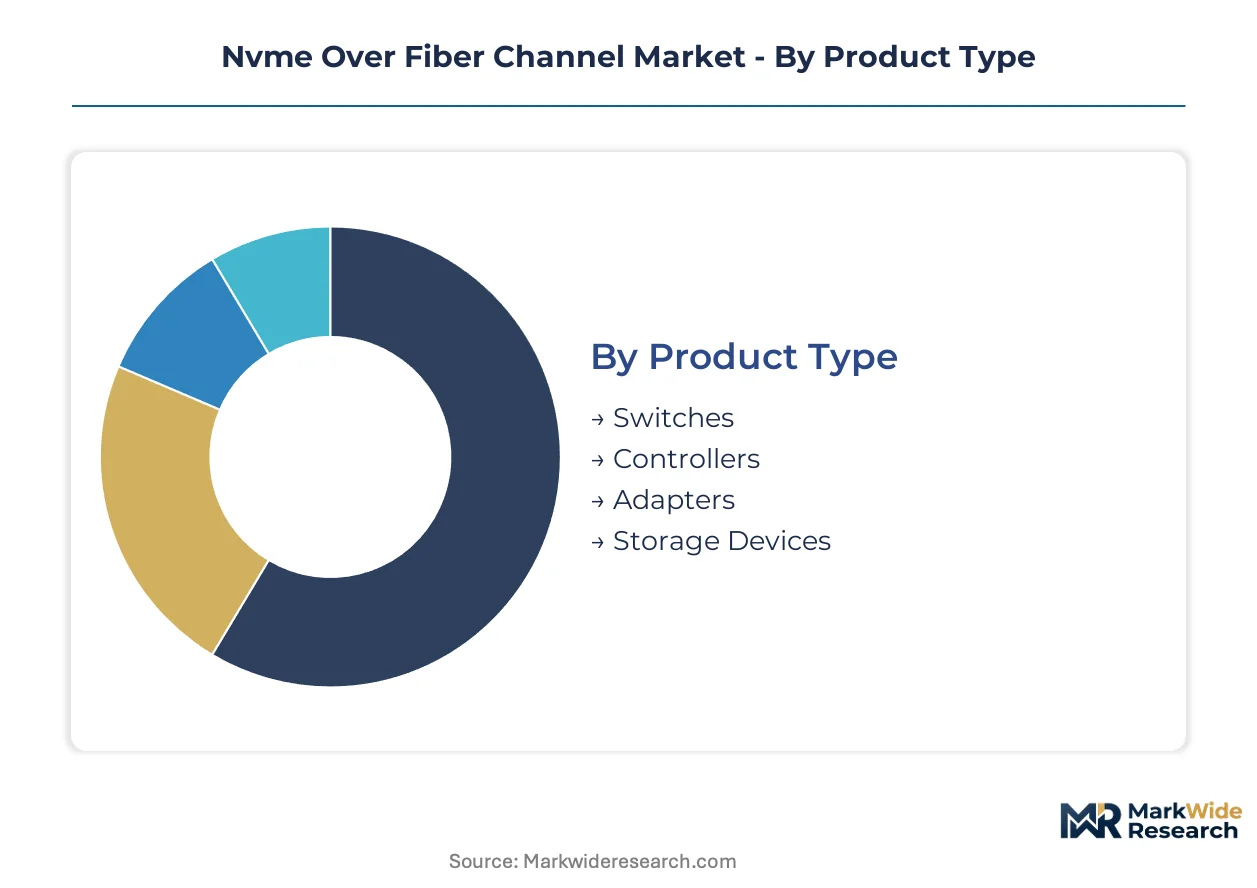
NVMe over Fibre Channel infrastructure fragments across hardware, deployment, and service layers with divergent margin profiles. Controller and adapter hardware commands premium pricing due to PCIe retimer integration, while services revenue scales with fabric complexity rather than port density.
Product Type:
Margin pools concentrate in silicon-intensive components where signal conditioning and protocol offload integration create differentiation barriers.
- Controllers:ASIC-based designs with integrated PCIe 6.0 retimers and NVMe-oF transport offload engines dominate hyperscale procurement. Northern Virginia data center operators specify these for deterministic latency in transactional database clusters, accepting 26-week lead times for TSMC N5-class silicon allocation.
- Adapters:Host bus adapters map NVMe command sets onto 32 Gbps and 64 Gbps Fibre Channel physical layers, requiring FCC equipment authorization for US market entry. Dallas-Fort Worth hyperscale construction is absorbing these at unprecedented density, pulling demand forward despite electromagnetic compliance testing extending timelines by 4-6 months.
- Switches:Fibre Channel switching hardware with converged NVMe-oF fabric support extends existing SAN infrastructure.
- Storage Devices:Disaggregated flash enclosures presenting pooled NVMe namespaces to fabric-attached hosts.
Controllers hold installed capacity. Adapters are rotating up the share rankings.
End User:
Procurement authority and volume scale separate segments with fundamentally different technical qualification requirements.
- Cloud Service Providers:Meta Platforms and Microsoft Azure procurement committees specify computational storage processors with integrated NVMe-oF offloads, collapsing discrete HBA architectures into consolidated controller designs. These buyers unbundle hardware from professional services, awarding direct ODM contracts that compress reseller margins by 15-20 points.
- Enterprises:Financial services and healthcare buyers in Singapore and Sydney mandate sub-100 microsecond latency guarantees per INCITS T11 specifications, preserving Fibre Channel fabric refresh budgets even as cloud migration accelerates elsewhere. Frankfurt and Amsterdam enterprises retain on-premises flash pools to satisfy EU AI Act data locality mandates.
- Data Centers:Colocation and wholesale facility operators building in Northern Virginia and Dallas-Fort Worth.
- Government:Public sector procurement with extended qualification timelines and domestic content preferences.
Enterprises hold installed capacity. Cloud Service Providers are climbing the fastest.
Deployment:
Architecture choices determine retimer silicon requirements and professional services attach rates.
- On-Premises:Dedicated Fibre Channel fabrics with full hardware ownership and operational control. Seoul and Melbourne healthcare imaging archives deploy these for PACS real-time radiology workflows, opening a vertical previously served by direct-attached storage arrays.
- Hybrid:Split workload placement with critical data remaining in owned facilities. European enterprise buyers must document energy efficiency under CSRD disclosure requirements, favoring NVMe-oF's power-per-IOP advantage over legacy SCSI fabrics in these configurations.
- Private Cloud:Dedicated infrastructure operated by third-party providers with tenant isolation guarantees.
- Public Cloud:Shared infrastructure with NVMe-oF access via managed service abstractions.
On-Premises holds installed capacity. Hybrid is gaining share fastest.
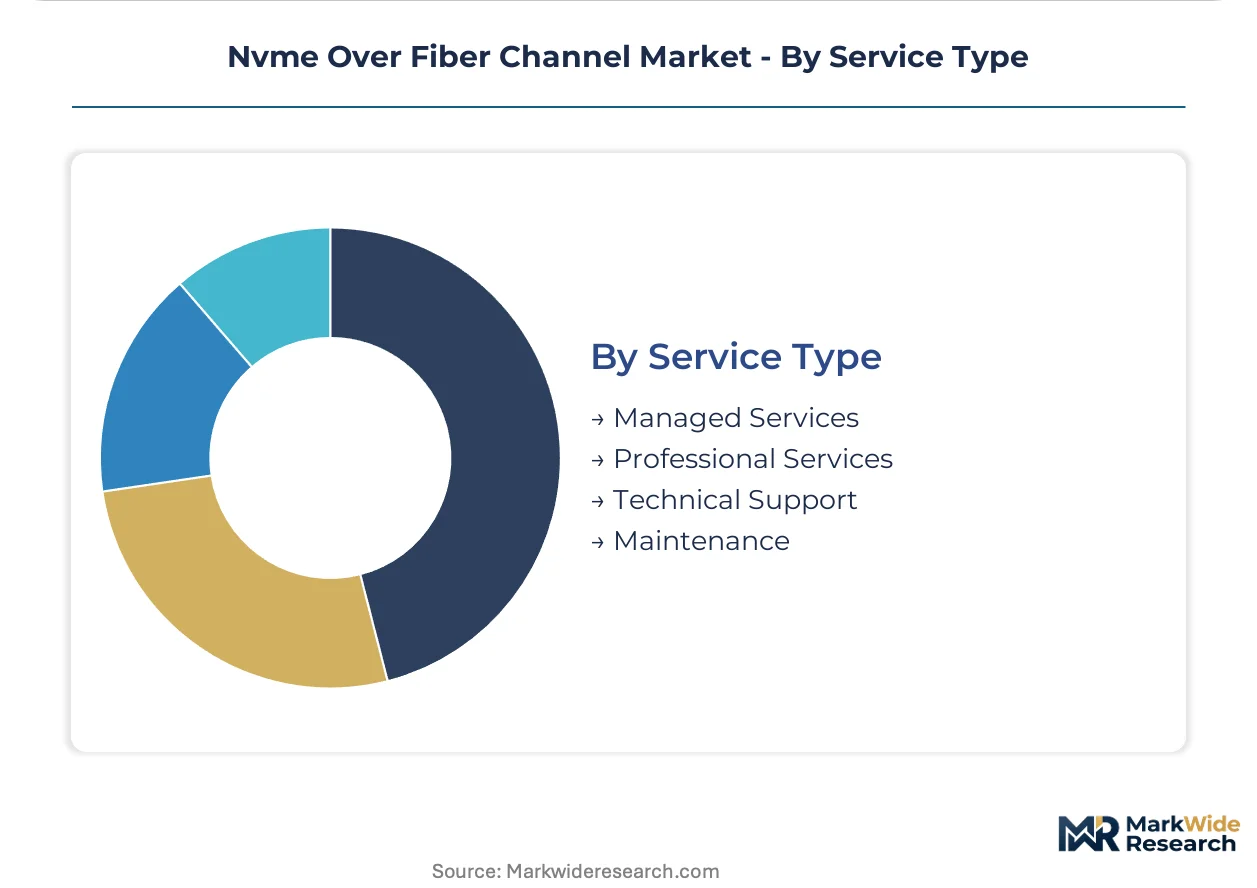
Service Type:
Revenue models shift from hardware attach to standalone fabric optimization as channel disintermediation accelerates.
- Professional Services:Fibre Channel zoning configuration and multi-vendor SAN qualification testing. Storage administrators capable of 64 Gbps fabric segmentation command 40% salary premiums, constraining deployment velocity and forcing systems integrators in London and Amsterdam to pivot toward firmware customization and fabric tuning services.
- Managed Services:Ongoing fabric monitoring, performance optimization, and capacity planning. São Paulo and Johannesburg Tier-2 cloud operators deploy these for edge AI inference clusters requiring low-latency model serving without core network dependency.
- Technical Support:Break-fix and software maintenance for controller firmware and adapter drivers.
- Maintenance:Hardware replacement and field service for switch and storage device failures.
Technical Support holds installed capacity. Managed Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NVMe-oF adapter pricing commands a 22% premium in Northern Virginia compared to Frankfurt, reflecting hyperscale demand concentration and FCC certification bottlenecks that constrain supply elasticity.
United States
Northern Virginia and Dallas-Fort Worth data center clusters absorb NVMe-oF infrastructure at unprecedented density, pulling adapter and controller demand forward. FCC equipment authorization rules govern electromagnetic emissions for 64 Gbps adapters, adding 4-6 months to market entry timelines. Austin and Phoenix emerge as secondary deployment zones for edge AI inference fabrics.
Germany
Frankfurt enterprises retain on-premises flash storage pools to satisfy EU AI Act data locality mandates, preserving Fibre Channel fabric refresh budgets. CSRD disclosure requirements force documentation of data center energy efficiency, favoring NVMe-oF's power-per-IOP advantage. Munich and Berlin host specialist systems integrators pivoting toward firmware customization services.
Japan
METI's semiconductor subsidy framework redirects domestic foundry capacity toward PCIe 6.0 retimer production, prioritizing storage networking silicon. Tokyo Electron accelerates test equipment deployment for advanced node validation. Osaka and Nagoya house memory suppliers qualifying domestic retimer sources for Gen5 SSD controller roadmaps.
Singapore
Financial services procurement committees mandate sub-100 microsecond latency guarantees per INCITS T11 specifications that only native NVMe-oF transport layers deliver. The Monetary Authority of Singapore's operational resilience guidelines reinforce on-premises storage requirements. Marina Bay and Changi data center zones concentrate trading infrastructure upgrades.
Brazil
Tier-2 cloud operators in São Paulo deploy converged NVMe-oF fabrics for low-latency model serving without core network dependency. ANVISA's data localization expectations for healthcare records favor on-premises architectures. Campinas and Rio de Janeiro emerge as secondary nodes for edge inference cluster expansion.
Nvme Over Fiber Channel Market Competitive Environment
Concentration sits with captive-fabrication incumbents capable of absorbing retimer silicon shortages through internal allocation. The supplier base separates into three tiers: ASIC-focused integrated manufacturers commanding margin structures fabless rivals cannot replicate, fabless challengers dependent on TSMC allocation for advanced nodes, and systems integrators pivoting toward fabric tuning services as hardware margins compress. Dominant competitive moves include backward integration into retimer silicon supply and direct ODM relationships that disintermediate traditional distribution channels.
Within the integrated-manufacturer tier, Broadcom Inc. and Marvell Technology exemplify archetypes capable of sustaining margin structures through captive semiconductor fabrication. Cisco Systems occupies a distinct position extending converged fabric portfolios. These three anchors demonstrate how protocol convergence and silicon integration are collapsing traditional separations between network interface cards and storage controllers, redrawing competitive boundaries across the hardware stack.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Dell Technologies |
| IBM Corporation |
| Intel Corporation |
| NetApp |
| Marvell Technology |
| ATTO Technology |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for TSMC N5-class silicon allocation compress pricing power toward ASIC-integrated incumbents while fabless challengers absorb margin erosion from retimer scarcity. This inventory compression amplifies cost pass-through to hyperscale buyers in Northern Virginia and Dallas-Fort Worth, where FCC certification bottlenecks prevent supply elasticity from moderating price premiums.
Pricing Analysis
The customization-premium spread between configured-to-order controllers and standard adapters spans three performance tiers tied to PCIe retimer integration depth and deterministic latency guarantees. Price differentiation hinges on FCC equipment authorization status and TSMC advanced-node allocation priority, with certified 64 Gbps adapters commanding substantial premiums over uncertified alternatives. Pricing pressure stems from cloud service provider procurement committees unbundling hardware from professional services and awarding direct ODM contracts. Enterprises with existing Fibre Channel fabrics exhibit lowest price sensitivity due to sunk infrastructure costs, while Tier-2 cloud operators in emerging markets face acute budget constraints.
Supply Chain Analysis
Inventory compression to twenty-six weeks for PCIe 6.0 retimer components signals acute supply chain stress across controller manufacturing. Taiwan, South Korea, and Japan anchor upstream silicon supply, with Japan's METI subsidy framework redirecting domestic foundry capacity toward storage networking retimers. Raw material dependencies center on advanced-node wafers from TSMC, Samsung Foundry, and domestic Japanese sources, alongside high-speed connector alloys subject to RoHS substance reformulations. Single-source vulnerability concentrates in TSMC's N5-class allocation for retimer silicon. Distribution runs through direct ODM relationships that disintermediate traditional channel partners and compress reseller margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NVMe over Fibre Channel market is recovering from retimer silicon shortage cyclicality as PCIe 6.0 transitions force controller refresh cadences and restocking demand accumulates across hyperscale facilities.
For Market Incumbents: Secure captive semiconductor fabrication allocation through backward integration into retimer silicon supply or long-term foundry offtake agreements with TSMC and Samsung. Defend margin structures by accelerating single-die controller designs that absorb PHY functions and eliminate discrete component dependencies. Prioritize FCC certification portfolio expansion to maintain 4-6 month market entry barriers against fabless challengers. For New Entrants and Emerging Players: Firmware customization and fabric tuning services represent a service-layer gap where incumbents under-serve mid-market enterprises constrained by Fibre Channel zoning expertise scarcity. Target healthcare imaging archives in Seoul and Melbourne adopting disaggregated NVMe-oF storage for PACS workflows, a vertical previously served by direct-attached storage arrays. Pursue systems integrator partnerships in London and Amsterdam to bypass direct ODM procurement barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates with under-optimized storage networking divisions lacking PCIe 6.0 retimer integration roadmaps. Five-to-ten year viability favors ASIC-focused integrated manufacturers with captive fabrication or secured foundry allocation. Monitor TSMC advanced-node capacity expansion announcements as the critical inflection signal for supply elasticity restoration and margin normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Retimer Silicon Backward Integration | Captive supply of PCIe 6.0 signal conditioning components insulates against TSMC allocation constraints. |
| Single-Die Controller Consolidation | Integrated PHY and offload engine designs eliminate discrete HBA architectures specified by Meta Platforms and Microsoft Azure. |
| FCC Certification Portfolio Expansion | Accelerated electromagnetic compliance testing maintains 4-6 month market entry barriers against challenger adapters. |
| Firmware Customization Service Launch | Fabric tuning capabilities capture revenue displaced by cloud provider direct ODM procurement disintermediation. |
| Healthcare Vertical Partnership | PACS vendor alliances in Seoul and Melbourne open radiology workflow deployments previously served by DAS arrays. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with data center infrastructure architects, storage procurement officers at cloud service providers, Fibre Channel fabric administrators, and semiconductor supply chain managers; and secondary validation against PCI-SIG specification disclosures, FCC equipment authorization databases, hyperscaler capex filings, and INCITS T11 protocol documentation. Bottom-up triangulation across adapter shipment estimates and top-down reconciliation against controller silicon wafer allocation data anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled demand across product type, end user archetype, deployment architecture, and service layer dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market boundary conditions, incorporating PCIe generation transition velocity, retimer silicon availability curves, and regulatory compliance timeline assumptions specific to electromagnetic authorization and data locality mandates.
Material uncertainties — retimer allocation disruptions, FCC certification timeline extensions, and EU AI Act enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding foundry capacity expansion and hyperscale construction cadence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Saudi Arabia Data Center Server Market