
 Low-Fat Cheese Nutrition Market | 2026-2036
Low-Fat Cheese Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Cheese Nutrition Market Foresight
Health-conscious consumers is rotating toward fitness enthusiasts and culinary professionals as the fastest-expanding buyer archetypes in low-fat cheese nutrition. Arla Foods amba leverages its cooperative structure to sustain organic and reduced-fat product lines across Northern Europe. Lactalis Group anchors its position through backward integration into dairy farming and processing assets. The Kraft Heinz Company competes on brand recognition and retail shelf space dominance in North American supermarkets.
Low-fat cheese nutrition encompasses dairy products formulated with reduced butterfat content, typically achieved through skim milk processing, membrane filtration, or enzymatic fat reduction while preserving protein matrices and calcium bioavailability. These products serve industrial food manufacturing, commercial food service, and direct retail consumption where calorie control and cardiovascular health positioning drive purchasing decisions. Reduced-fat cheddar and mozzarella lead product type volumes due to their versatility across cooking and snacking applications, while cottage cheese differentiates through high-protein positioning among fitness-oriented end users. The online retail channel represents the fastest-growing distribution pathway as direct-to-consumer subscription models reshape how health-conscious consumers and families replenish specialty dairy inventories.
The EU Green Deal and EFSA nutrient profiling criteria shape formulation standards and front-of-pack labeling requirements across European markets, while FDA nutritional labeling mandates govern product claims and serving-size disclosures in the United States. Japan's Consumer Affairs Agency enforces comparable standards through Food with Function Claims frameworks that restrict how low-fat cheese products communicate health benefits. Stakeholders must monitor evolving cross-border dairy tariff structures and anticipate how carbon-footprint disclosure regulations will reshape sourcing decisions and competitive positioning in premium low-fat segments.
Market Dynamics
Membrane filtration technology is compressing production costs while EU Green Deal carbon-footprint disclosure rules force reformulation investments across European manufacturing footprints.
Growth Catalysts
- EFSA Nutrient Profiling:Front-of-pack labeling mandates in Europe are pulling reformulated low-fat variants into mainstream retail placement, expanding addressable shelf space.
- Fitness-Oriented End Users:High-protein cottage cheese positioning is capturing meal-replacement demand among athletic consumers and CrossFit-affiliated nutrition programs.
- Membrane Filtration:Advanced ultrafiltration systems are enabling butterfat reduction without protein denaturation, preserving functional properties in mozzarella and cheddar applications.
Market Restraints
- Butterfat Input Volatility:Skim milk powder prices fluctuate with global dairy commodity cycles, compressing margin predictability for reduced-fat product lines.
- Supply Concentration Risk:Northern European cooperative structures control disproportionate organic milk supply, creating sourcing bottlenecks for clean-label low-fat variants.
- Regulatory Friction:Japan's Food with Function Claims framework restricts health-benefit communication, limiting premium positioning in East Asian export markets.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Replenishment models for specialty dairy inventories are bypassing traditional retail slotting fees and capturing household lifetime value.
- Carbon-Label Premium Segments:EU Green Deal disclosure requirements are creating defensible positioning for verified low-carbon-footprint cheese production.
- Enzymatic Fat Reduction:Lipase-based processing converging with clean-label demand is opening reformulation pathways without artificial stabilizers.
Industry Challenges
- Dairy Protein Chemistry Expertise:Shortages of food scientists capable of optimizing protein matrices during fat reduction are extending R&D timelines.
- Dual Certification Complexity:Simultaneous organic and reduced-fat credentialing requires navigating overlapping audit protocols from multiple certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Cheese Nutrition Market |
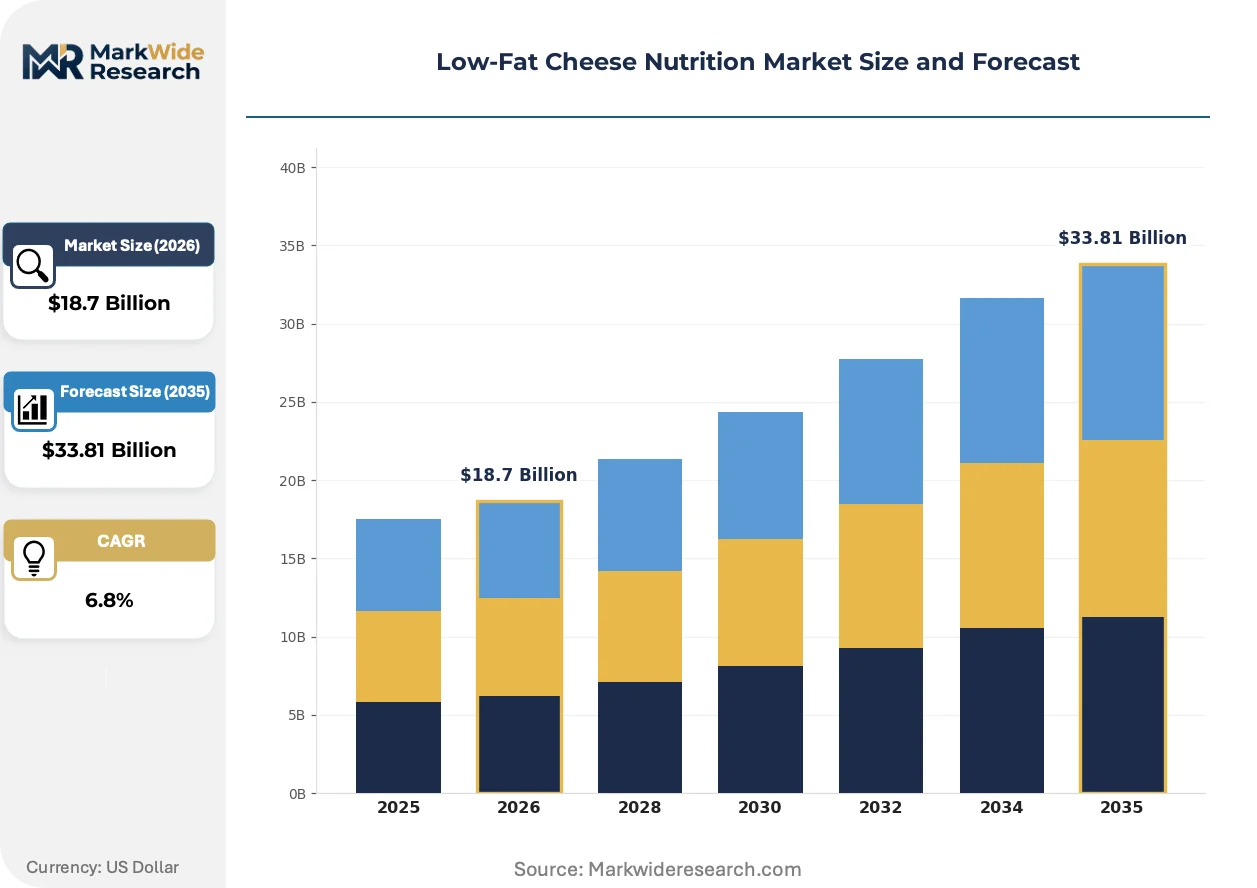
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduced-Fat Cheddar, Mozzarella, Cream Cheese, Cottage Cheese Application: Snacking, Cooking, Baking, Spreading End User: Health-Conscious Consumers, Fitness Enthusiasts, Families, Culinary Professionals Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Arla Foods amba, Lactalis Group, The Kraft Heinz Company, FrieslandCampina, Saputo Inc., Nestlé S.A., Danone S.A., Dairy Farmers of America, Amul Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Cheese Nutrition Market Shifts & Advancements
Processing technology and disclosure mandates are compressing traditional production economics while reshaping how health claims reach end consumers.
Enzymatic fat-reduction systems using microbial lipases are displacing mechanical separation methods in premium low-fat cheese production. Artisanal and specialty dairy processors in Germany and France are adopting these systems to preserve flavor complexity. This displacement is compressing capital requirements for small-batch producers while fragmenting technology supplier power.
EU Green Deal carbon-footprint disclosure regulations are mandating lifecycle assessment documentation across dairy value chains. Manufacturers must now quantify and report emissions from feed cultivation through retail distribution. German and Dutch producers are responding by investing in biogas capture and renewable energy contracts to secure premium positioning.
Direct-to-consumer subscription models are capturing household replenishment demand previously routed through supermarket dairy cases. Fitness-oriented consumers and families with dietary restrictions are shifting toward curated monthly deliveries of specialty low-fat inventories. This channel rotation is most visible in United States metropolitan markets and United Kingdom home-delivery corridors.
Low-Fat Cheese Nutrition Market Segmentation
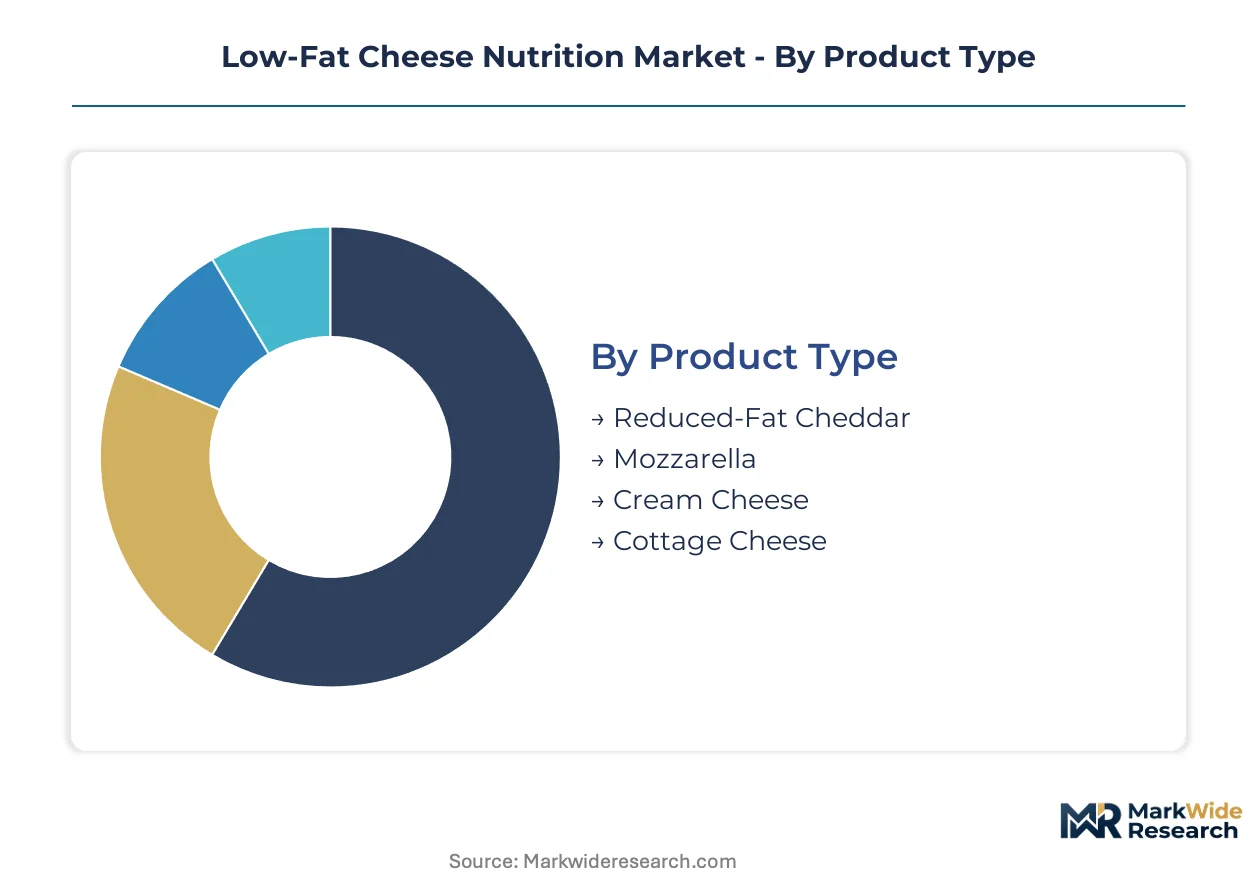
Low-fat cheese nutrition segments fragment across functional use cases and buyer motivation rather than traditional dairy categories. Substitution pressure from plant-based alternatives and high-protein dairy alternatives forces each segment to defend distinct value propositions around taste fidelity, nutritional density, or culinary performance.
Product Type:
Reduced-fat cheddar and mozzarella face intensifying substitution from fermented cashew and oat-based alternatives in cooking applications, while cottage cheese leverages its protein density to resist displacement.
- Reduced-Fat Cheddar:Formulated through skim milk processing and controlled enzymatic aging to preserve sharp flavor profiles at 25-50% fat reduction. Demand concentrates in United States family households for sandwich and casserole applications where melting behavior must match full-fat benchmarks. FDA nutritional labeling mandates on saturated fat disclosures drive reformulation investments.
- Mozzarella:Achieved via membrane filtration to maintain protein matrix integrity essential for stretch and browning in pizza applications. Italian food service operators in Germany and France specify reduced-fat variants for health-positioned menu items. EFSA nutrient profiling criteria pull reformulated products into mainstream retail placement.
- Cream Cheese:Emulsified reduced-fat spreads for bagel and dessert applications.
- Cottage Cheese:High-protein curd positioning captures CrossFit-affiliated meal replacement demand.
Reduced-fat cheddar retains volume leadership; cottage cheese holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity cooking applications from premium snacking formats where branded positioning commands shelf space premiums.
- Snacking:Portion-controlled sticks and cubes formulated for grab-and-go consumption with protein-forward labeling. United Kingdom convenience retail and Japanese convenience store channels drive format innovation. Japan's Food with Function Claims framework restricts health-benefit communication, compressing premium pricing power.
- Cooking:Shredded and block formats engineered for heat-stable melting in pasta and casserole applications. United States family households represent core demand concentration. Butterfat input volatility from skim milk powder commodity cycles squeezes margin predictability.
- Baking:Low-moisture variants for cheesecake and pastry applications.
- Spreading:Whipped and soft-serve formats for cracker and bread applications.
Cooking applications retain volume leadership; snacking holds the steepest expansion curve.
End User:
Customer type segmentation reveals divergent purchasing rhythms between subscription-driven fitness cohorts and episodic family replenishment patterns.
- Fitness Enthusiasts:Macro-tracking consumers prioritizing protein-to-calorie ratios in meal prep and post-workout recovery. United States metropolitan direct-to-consumer subscription channels capture household lifetime value. High-protein cottage cheese positioning dominates this cohort.
- Health-Conscious Consumers:Cardiovascular-risk-aware buyers selecting reduced-fat options for daily cooking rotation. German and French retail supermarkets concentrate demand. EU Green Deal carbon-footprint disclosure requirements influence brand selection.
- Families:Budget-constrained household purchasers balancing child acceptance with nutritional claims.
- Culinary Professionals:Restaurant and catering operators sourcing functional ingredients for health-positioned menu development.
Health-conscious consumers retain volume leadership; fitness enthusiasts hold the steepest expansion curve.
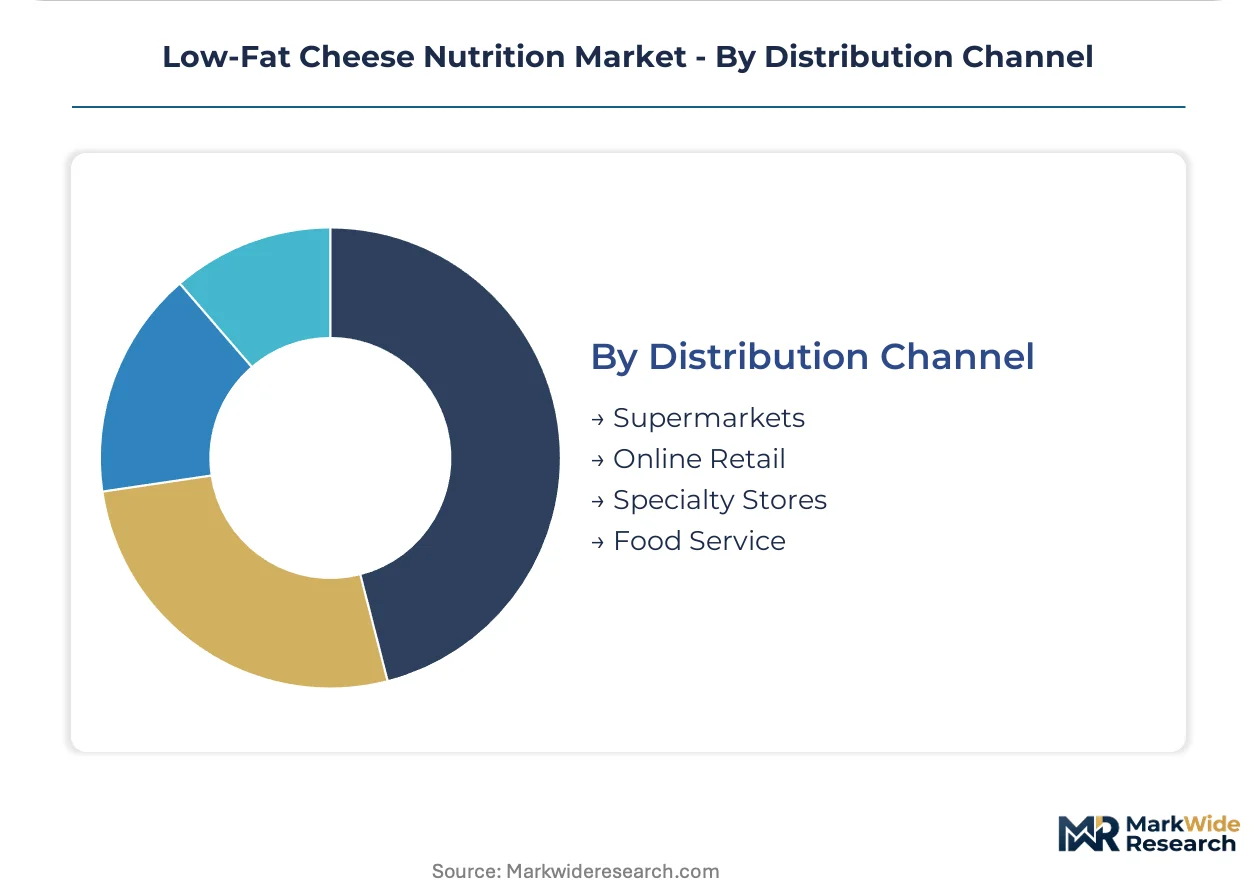
Distribution Channel:
Supply concentration in Northern European cooperative structures creates sourcing bottlenecks that reshape channel economics for clean-label variants.
- Online Retail:Direct-to-consumer subscription models bypassing traditional supermarket slotting fees. United States and United Kingdom home-delivery corridors show strongest uptake. Curated monthly deliveries of specialty low-fat inventories capture replenishment demand.
- Supermarkets:Mass-market retail shelf space dominated by branded players with retail negotiation leverage. North American and European chains concentrate volume. Membrane filtration technology investments compress production costs for private-label entrants.
- Specialty Stores:Artisanal and organic-focused retailers with localized sourcing requirements.
- Food Service:Industrial and commercial purchasing for ingredient and prepared-food applications.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish cooperative exporters supply reduced-fat mozzarella to German food service operators under EU Green Deal carbon-footprint documentation requirements. Cross-border dairy trade flows concentrate through Rotterdam and Hamburg distribution hubs serving retail and industrial buyers.
Germany
Fitness-oriented consumers in Berlin and Munich drive cottage cheese subscription demand through direct-to-consumer channels. EFSA nutrient profiling criteria mandate front-of-pack labeling that pulls reformulated low-fat variants into mainstream supermarket placement. Bavarian dairy cooperatives invest in biogas capture systems to meet EU Green Deal disclosure standards for premium positioning.
United States
Family households in metropolitan markets prioritize reduced-fat cheddar for cooking applications where melting behavior must match full-fat benchmarks. FDA nutritional labeling mandates on saturated fat disclosures compel reformulation investments by domestic processors. Wisconsin and California dairy clusters concentrate membrane filtration capacity for mozzarella production.
France
Artisanal cheese producers in Auvergne-Rhône-Alpes adopt enzymatic fat-reduction systems to preserve flavor complexity in premium low-fat lines. ANSM enforces strict health-claim boundaries that limit how reduced-fat products communicate cardiovascular benefits. Parisian retail chains source clean-label variants from Normandy cooperative structures controlling organic milk supply.
Japan
Convenience store channels in Tokyo and Osaka drive portion-controlled snacking format innovation for health-positioned consumers. The Consumer Affairs Agency's Food with Function Claims framework restricts premium pricing power by limiting health-benefit communication. Kanto region processors concentrate exports of functional low-fat dairy to Southeast Asian markets.
United Kingdom
Home-delivery corridors in London and Manchester show strongest uptake of online retail subscription models for specialty low-fat inventories. Post-Brexit dairy tariff structures reshape sourcing decisions for retailers importing from Irish and continental suppliers. Scottish dairy cooperatives leverage carbon-label credentials to defend shelf space in premium segments.
Low-Fat Cheese Nutrition Market Competitive Landscape
Player mix skews toward cooperative structures and publicly traded multinationals with backward integration into dairy farming assets. Tiered competition separates premium artisanal specialists from scale-driven private-label suppliers. Strategic archetypes include Northern European cooperatives with organic supply control, North American brand conglomerates with retail negotiation leverage, and emerging-market dairy federations with cost-advantaged raw milk access. Dominant competitive moves encompass M&A for regional brand portfolios and capacity expansion in membrane filtration technology.
Among Northern European cooperative structures, Arla Foods amba and FrieslandCampina occupy positions defined by member-farmer governance and cross-border supply coordination. Lactalis Group exemplifies the privately held multinational archetype with integrated processing assets spanning multiple geographies. The Kraft Heinz Company represents the North American brand-centric model competing on retail shelf space dominance and household recognition in supermarket channels.
| Leading Market Players |
|---|
| Arla Foods amba |
| Lactalis Group |
| The Kraft Heinz Company |
| FrieslandCampina |
| Saputo Inc. |
| Nestlé S.A. |
| Danone S.A. |
| Dairy Farmers of America |
| Amul Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Northern European dairy cooperatives and German retail chains lock in organic milk supply and stabilize price visibility for clean-label low-fat variants. These arrangements insulate processors from skim milk powder commodity swings while committing buyers to volume minimums.
Pricing Analysis
Membrane filtration technology-generation pricing gaps separate premium enzymatic-fat-reduction lines from conventional mechanical-separation tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and butterfat reduction depth. Price differentiation stems from organic credentialing and carbon-footprint verification under EU Green Deal mandates. Pricing pressure intensifies in economy tiers as private-label entrants deploy membrane filtration capacity. Fitness enthusiasts show lowest price sensitivity, prioritizing protein density over per-unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion ripple through German and Dutch distribution networks serving continental retail. Supply concentrates in Denmark, Germany, and the Netherlands, where cooperative structures control organic milk flows. Raw material dependencies include skim milk powder, microbial lipases, and biogas-derived energy inputs. Single-source vulnerability from Northern European organic supply creates procurement bottlenecks for clean-label variants. Distribution runs through supermarket dairy cases, food service ingredient channels, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German and United Kingdom supermarket consolidation, shifting negotiation leverage toward retail procurement teams and compressing slotting fee economics for branded entrants.
For Market Incumbents: Consolidate backward integration into dairy farming assets to secure organic milk supply against cooperative bottlenecks. Deepen membrane filtration capacity in Wisconsin and Bavaria to defend cost position against private-label entrants. Lock in long-term offtake with fitness-oriented subscription platforms before channel economics shift further. For New Entrants and Emerging Players: Differentiate on carbon-label credentials verified under EU Green Deal disclosure frameworks to command premium positioning. Target United States metropolitan direct-to-consumer corridors where subscription models bypass retail slotting barriers. Pursue enzymatic fat-reduction partnerships with artisanal German processors to access clean-label technology without captive R&D investment. For Investors and Strategic Acquirers: Mid-scale enzymatic processing specialists with established lipase supply relationships represent priority acquisition targets. Long-term viability hinges on carbon-footprint verification infrastructure becoming table stakes rather than premium differentiator. Monitor EFSA nutrient profiling enforcement intensity as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Reduces unit costs for mozzarella and cheddar while preserving protein functionality. |
| Carbon-Label Certification Program | Secures premium positioning under EU Green Deal lifecycle assessment requirements. |
| Direct-to-Consumer Platform Launch | Bypasses supermarket slotting fees and captures fitness-oriented household lifetime value. |
| Enzymatic Processing Partnership | Accesses lipase-based fat reduction without capital-intensive in-house R&D. |
| Organic Supply Backward Integration | Insulates against Northern European cooperative sourcing bottlenecks for clean-label variants. |
Research Methodology
The analysis maps reduced-fat cheddar, mozzarella, cottage cheese, and cream cheese segments, each validated through dairy cooperative managers, retail category buyers, food service procurement directors, and membrane filtration equipment suppliers. Primary interviews combined with secondary validation from EFSA guidance documents, FDA nutritional labeling databases, EU Green Deal technical standards, and dairy commodity trade flows. Bottom-up volume modeling and top-down value reconciliation ensured cross-check integrity.
Consistency checks against customs data and cooperative export disclosures validated segment-level outputs across the projection horizon. Segmentation dimensions modeled include product type, application use case, end-user motivation, and distribution channel structure. CAGRs derived from fitted growth curves incorporating technology adoption rates, regulatory enforcement timelines, and channel shift velocities. Forecast inputs encompassed membrane filtration penetration rates and carbon-label premium capture assumptions.
Material uncertainties — butterfat input volatility, regulatory enforcement intensity, and subscription platform churn — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology cost trajectories and buyer cohort evolution. Practitioners should keep alternative scenarios live as EU Green Deal disclosure requirements and direct-to-consumer channel economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Camel Dairy Market
Dairy Products
Reconstituted Milk Market
Dairy Products
North America A2 Milk Market
Dairy Products
Emmental Cheese Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
North America Yogurt Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Canada Dairy Market
Dairy Products
Paneer Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
North America Cheese Market
Dairy Products
Global Milk Powder Market