
 GCC Casein Market | 2026-2036
GCC Casein Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Casein Market Intelligence
Multi-source procurement from European and Oceania suppliers is expanding as GCC food manufacturers reduce dependency on single-origin dairy imports. Fonterra Co-operative Group leverages its New Zealand processing network to sustain long-term supply contracts with Saudi dairy processors. Arla Foods amba anchors its GCC position through regional distribution partnerships that bypass traditional European re-export channels. Glanbia plc differentiates via specialized micellar casein formulations targeting sports nutrition brands in the UAE and Qatar.
Casein denotes a family of phosphoproteins precipitated from skim milk through acidification or enzymatic rennet treatment, typically containing 80 percent protein on a dry basis with bound calcium and phosphorus micelles that enable slow gastric digestion and sustained amino acid release. Its primary commercial purpose centers on functional food systems requiring emulsification, water binding, or extended nutrient delivery profiles. Caseinates dominate GCC import volumes due to superior solubility in beverage applications and infant nutrition formulations. Sports nutrition applications exhibit the fastest structural expansion as gym culture and protein supplementation penetrate Saudi and Emirati consumer bases. Powdered form maintains margin concentration through lower logistics costs and extended shelf stability in Gulf climate conditions.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce divergent dairy derivative labeling and contaminant threshold requirements that complicate pan-GCC product registration. GSO harmonization efforts are gradually converging microbiological standards, though implementation timelines vary by member state. Stakeholders must monitor regulatory alignment progress and pre-qualify formulations against the stricter of overlapping national standards to avoid market access delays.
Market Dynamics
Gulf Standardization Organization harmonization is compressing formulation windows for casein derivatives as Saudi Arabia and the UAE tighten additive thresholds ahead of unified GCC standards. Manufacturers must simultaneously satisfy divergent national requirements while preparing for consolidated compliance.
Growth Catalysts
- Sports nutrition expansion:Gym culture penetration across Saudi Arabia and the UAE is pulling slow-release protein formulations into mainstream retail. Casein's sustained amino acid release profile matches post-workout recovery protocols preferred by Emirati fitness chains.
- SFDA-ESMA convergence:Gradual alignment of microbiological standards between Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology is reducing dual-registration burdens for cross-border dairy ingredient suppliers.
- Processed food corridor clustering:Dairy ingredient processing hubs between Riyadh and Jeddah are capturing economies of scale that lower unit costs for caseinate exports to Bahrain, Kuwait, and Oman.
Market Restraints
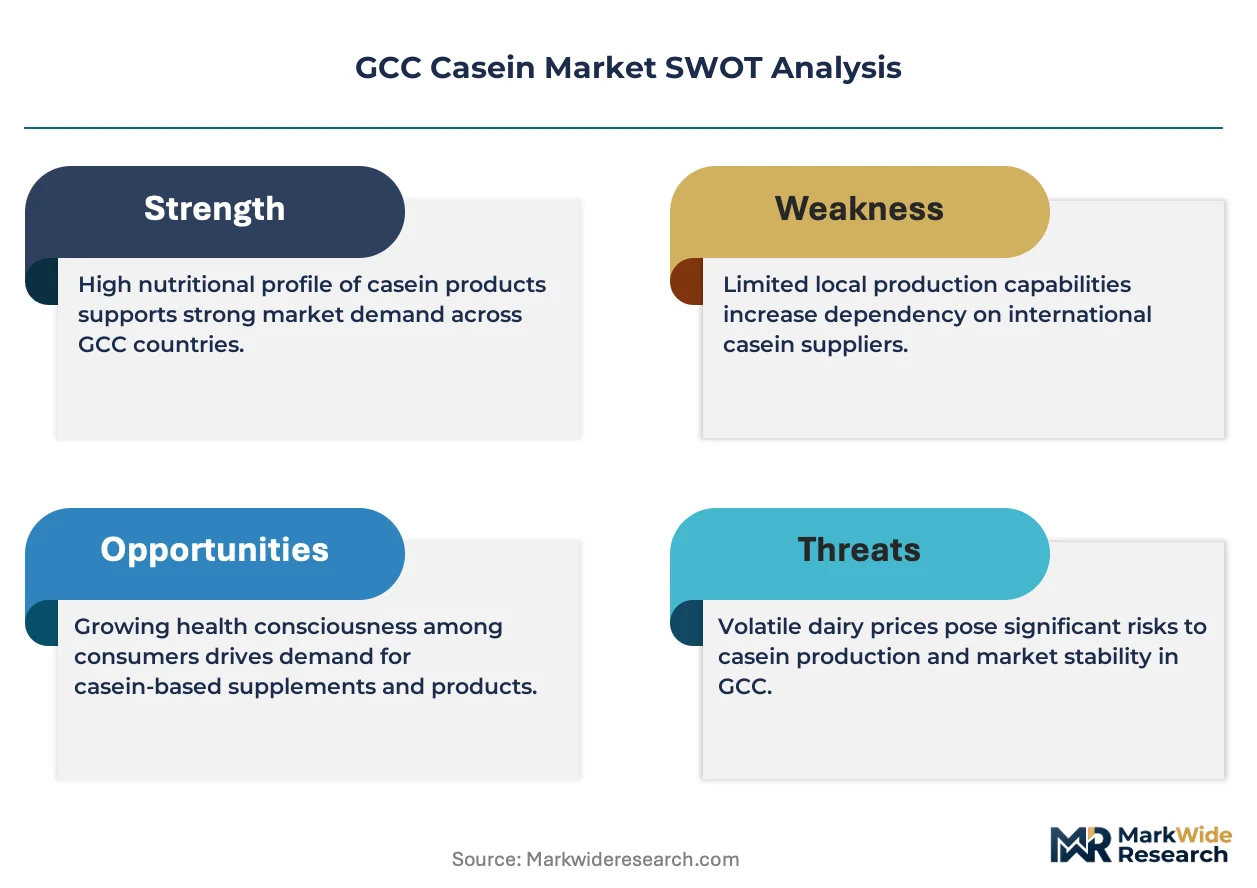
- Single-origin dependency:European Union dairy processors supply the majority of acid casein to GCC food manufacturers, exposing buyers to Euro-denominated price volatility and seasonal production cycles.
- Rennet casein technical limitation:Halal certification requirements for enzymatic processing constrain acceptable source materials, limiting supplier pools and extending qualification timelines.
- Infant nutrition substitution:Whey protein hydrolysates are displacing caseinates in premium pediatric formulations due to perceived digestibility advantages and shorter gastric emptying times.
Strategic Opportunities
- Qatari sports nutrition underpenetration:Doha's fitness sector growth outpaces dedicated casein distribution infrastructure, creating first-mover positioning for specialized micellar formulations.
- Functional beverage channel innovation:Ready-to-drink protein beverages in UAE convenience retail are bypassing traditional food-service distribution, enabling direct-to-shelf relationships with caseinate suppliers.
- Oman dairy processing incentive:Sultanate industrial zone subsidies for food ingredient manufacturing are attracting toll-processing investments that could reconfigure GCC casein trade flows.
Industry Challenges
- Halal certification timeline compression:Casein derivative approvals through Saudi Food and Drug Authority now require parallel documentation to Gulf Standardization Organization pre-standards, stretching regulatory affairs capacity.
- Moisture-controlled storage capex:Gulf climate conditions mandate humidity-controlled warehousing investments that inflate working capital requirements for casein inventory holding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Casein Market |
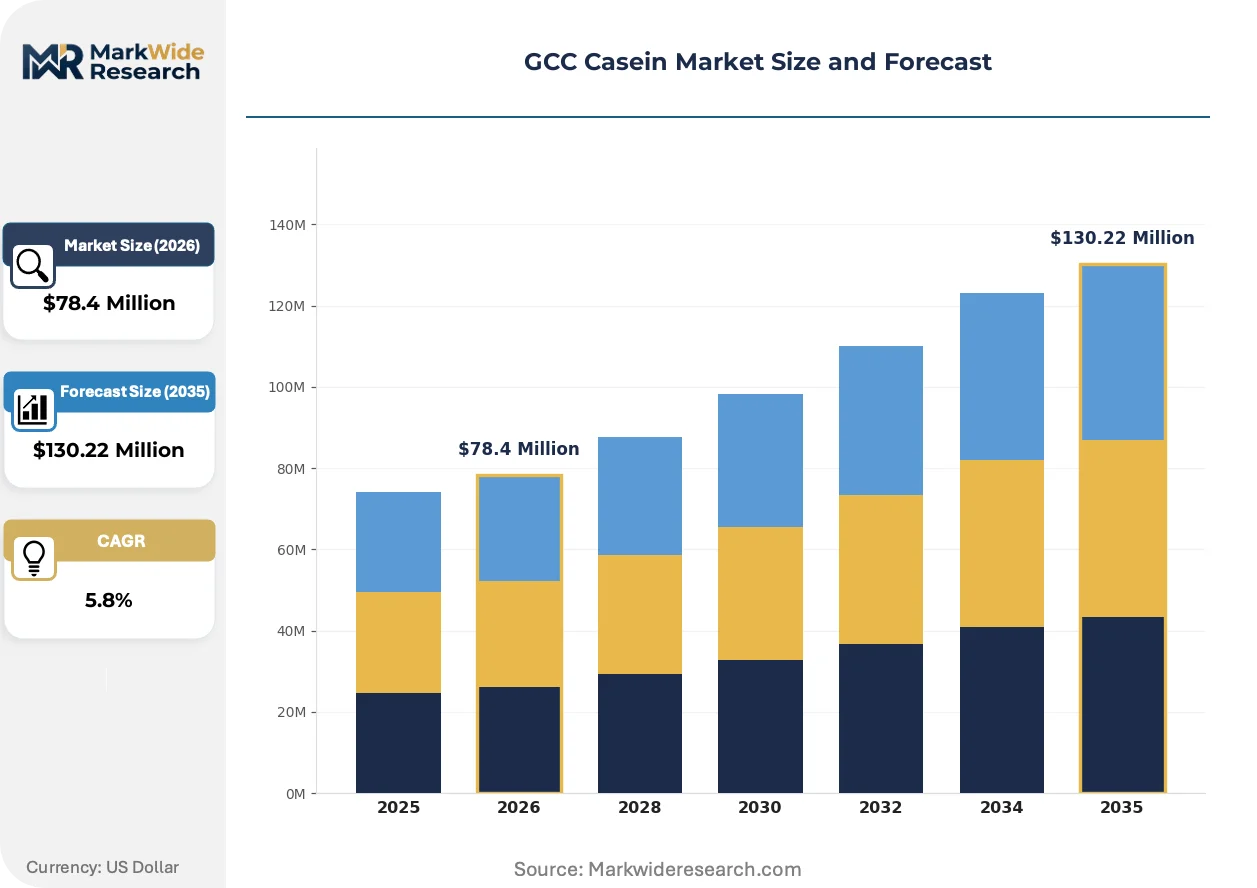
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micellar Casein, Caseinates, Rennet Casein, Acid Casein Application: Dairy Products, Infant Nutrition, Sports Nutrition, Bakery Form: Powdered, Liquid, Granular, Concentrate End User: Food Industry, Pharmaceuticals, Nutraceuticals, Cosmetics |
| Companies Covered | Arla Foods amba, Fonterra Co-operative Group, NZMP, ADM, Lactalis Ingredients, FrieslandCampina Ingredients, Kerry Group plc, Glanbia plc, AMCO Proteins, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Casein Market Strategic Shifts & Innovations
Casein processing technology and procurement patterns across the GCC are converging toward precision nutrition applications and climate-resilient supply architectures. Three developments are compressing traditional formulation and sourcing cycles.
Membrane filtration systems are automating micellar casein isolation from skim milk with reduced acid intervention. Saudi dairy processors are adopting these units at commercial scale to preserve protein micelle integrity for sports nutrition clients. The technology is automating quality consistency that previously required batch-to-batch manual adjustment.
Gulf Standardization Organization food safety protocols are mandating contaminant thresholds and additive disclosure formats that exceed legacy national requirements. Food manufacturers face reformulation costs to meet harmonized microbiological standards ahead of full implementation. Infant nutrition suppliers in the UAE are pre-qualifying caseinate stocks against the stricter of overlapping SFDA and ESMA limits to avoid registration delays.
Direct procurement from New Zealand and Australian dairy cooperatives is displacing European re-export channels for GCC food manufacturers. Large Saudi dairy processors are negotiating long-term supply agreements that bypass Rotterdam and Hamburg consolidation points. The shift is most visible in Riyadh-based ingredient traders establishing ocean freight contracts through Jeddah Islamic Port rather than European hub-and-spoke distribution.
GCC Casein Market Segmentation
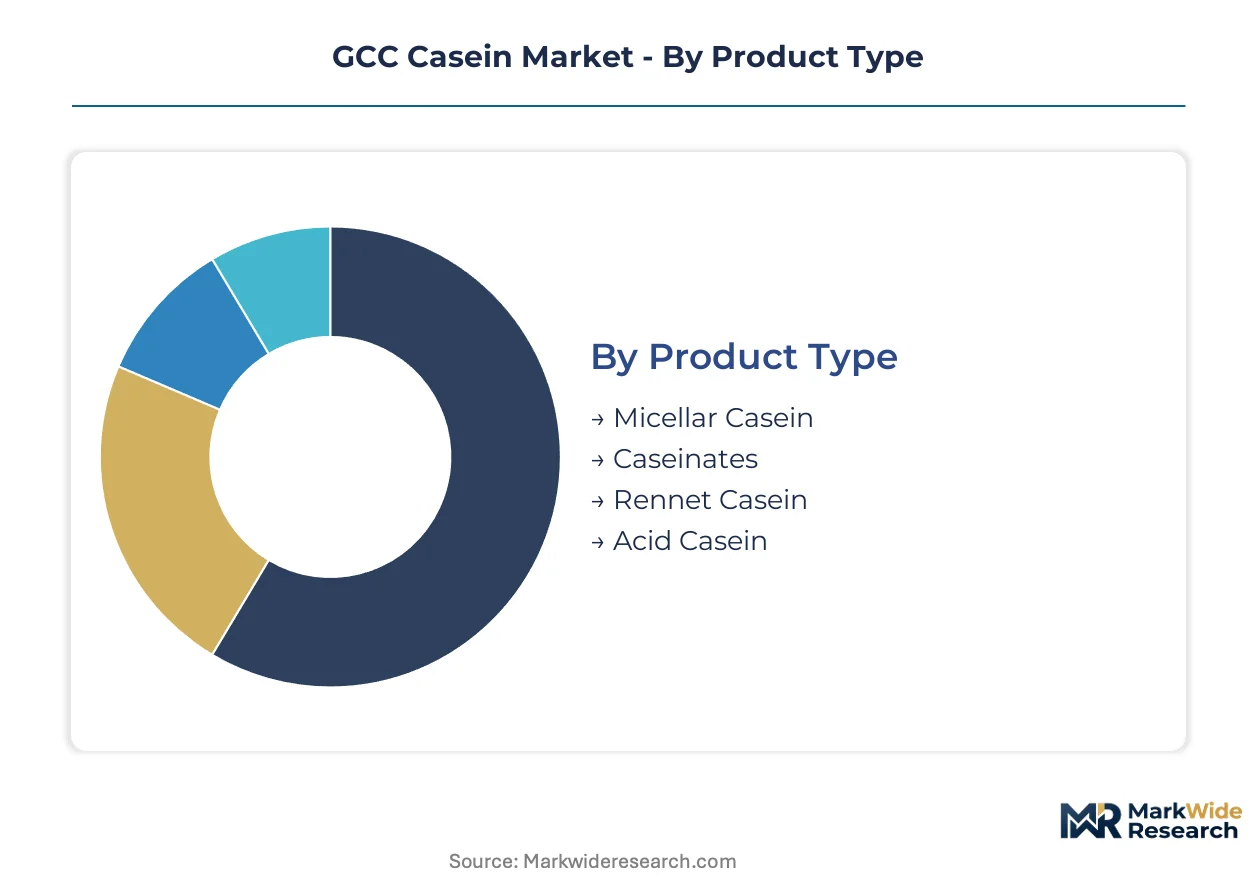
Casein procurement patterns across the GCC diverge sharply by functional specification and end-use requirements. Saudi and Emirati food manufacturers prioritize solubility profiles and halal certification pathways when segmenting supplier contracts.
Product Type:
Supply concentration tilts toward caseinates and micellar variants as Saudi dairy processors build dedicated production lines.
- Caseinates:Alkali-treated derivatives exhibit superior dispersibility in beverage matrices and infant formula applications. Demand clusters in Riyadh-Jeddah processing corridors where dairy ingredient exporters serve both domestic brands and re-export channels to Kuwait and Bahrain.
- Micellar Casein:Native protein structures isolated through membrane filtration retain slow-digestion kinetics prized by sports nutrition formulators. UAE gym chains and protein supplement brands in Dubai are scaling procurement of these specialized fractions.
- Rennet Casein:Enzymatic precipitation yields curd-forming proteins essential for processed cheese manufacturing; halal certification requirements constrain acceptable enzyme sources.
- Acid Casein:Mineral acid precipitation produces technical-grade proteins for industrial adhesives and paper coatings; limited food-grade applications in GCC markets.
Caseinates absorb the bulk of installed capacity; micellar casein is expanding most quickly.
Application:
Volume distribution tracks processed food infrastructure density and retail channel maturation across member states.
- Sports Nutrition:Slow-release amino acid kinetics align with post-workout recovery protocols. Fitness culture penetration in Saudi Arabia and the UAE is pulling casein-enriched protein powders into mainstream hypermarket retail.
- Infant Nutrition:Caseinates provide emulsion stability in follow-on formulas. SFDA and ESMA microbiological threshold convergence is compressing formulation windows for pediatric applications.
- Dairy Products:Processed cheese and yogurt fortification utilize rennet and acid casein fractions; Jeddah-based dairy clusters source these for domestic distribution.
- Bakery:Water-binding and dough-conditioning properties support extended shelf-life bread production; penetration lags behind dairy and nutrition segments.
Sports nutrition commands the steepest expansion trajectory; dairy products retain the largest volume base.
Form:
Logistics economics and climate resilience determine procurement preferences across Gulf distribution networks.
- Powdered:Low moisture content enables ambient storage and extended shelf stability under high-temperature conditions. Saudi and UAE importers favor this form for inventory holding cost efficiency.
- Liquid:Pre-hydrated concentrates reduce reconstitution labor for industrial food-service operators; refrigerated chain requirements limit geographic reach.
- Granular:Intermediate particle size offers flowability advantages for automated dosing equipment; niche adoption in pharmaceutical tableting applications.
- Concentrate:Reduced water content lowers transport costs versus liquid forms; requires reconstitution infrastructure at point of use.
Powdered form dominates import volumes; liquid concentrates are gaining share in food-service channels.
End User:
Customer sophistication and regulatory burden intensity separate tier-one buyers from commodity purchasers.
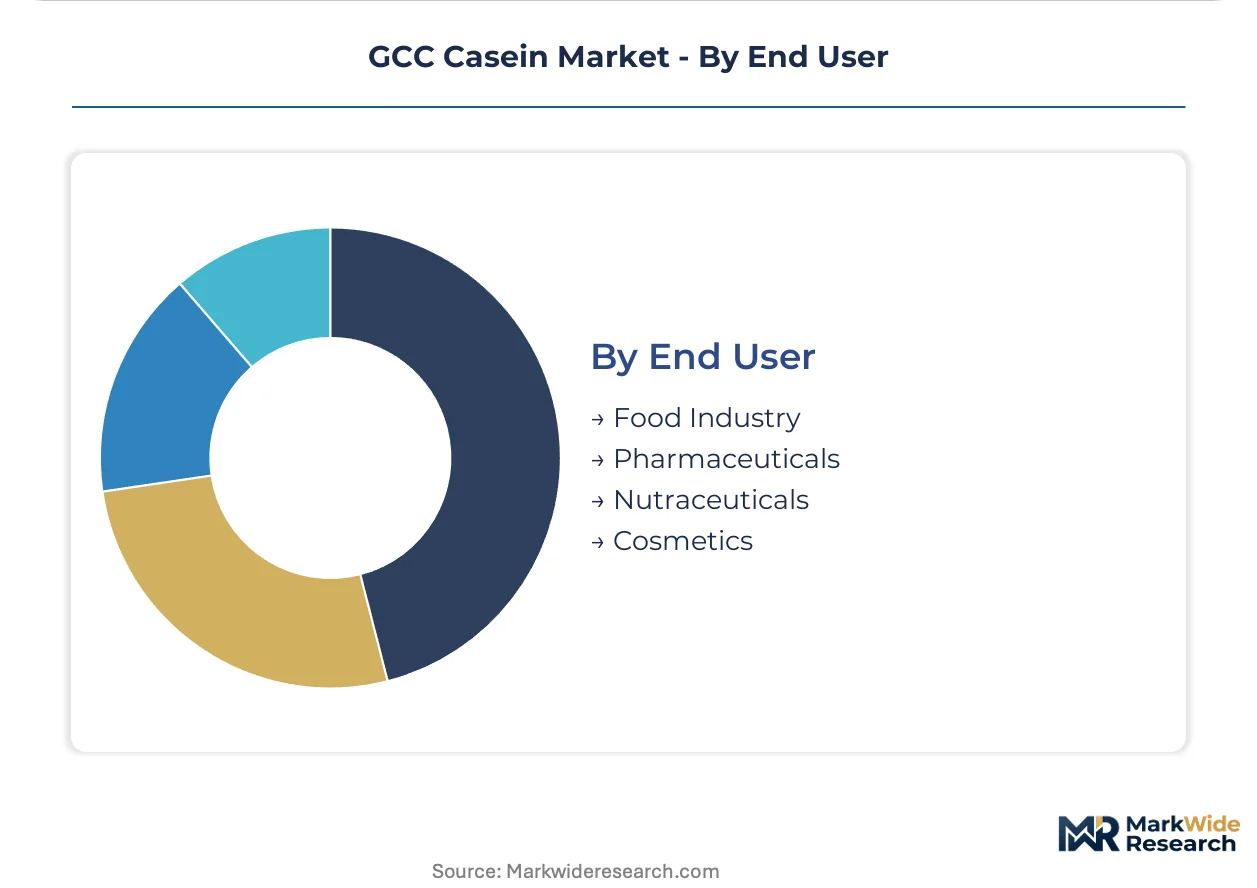
- Food Industry:Processed dairy manufacturers and bakery chains constitute the primary demand pool. Riyadh-based ingredient traders aggregate procurement for redistribution across the GCC.
- Nutraceuticals:Sports supplement brands and wellness product manufacturers require certificate-of-analysis documentation and batch traceability; UAE regulatory scrutiny is tightening.
- Pharmaceuticals:Excipient-grade casein for tablet binding and encapsulation demands pharmacopeia compliance; limited domestic manufacturing in the GCC.
- Cosmetics:Film-forming and moisturizing properties support skincare formulations; nascent demand concentrated in Dubai personal care manufacturing.
Food industry buyers absorb the majority of supply; nutraceuticals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand and Australian dairy cooperatives anchor raw material supply for GCC casein processors, with ocean freight routes through Jeddah Islamic Port displacing traditional European consolidation points. This feedstock geography shapes procurement economics across Gulf food manufacturing clusters.
Saudi Arabia
Sports nutrition brands in Riyadh and Jeddah are scaling micellar casein procurement for protein supplement formulations. SFDA maintains divergent additive thresholds ahead of full GSO harmonization, forcing dual-registration preparation. The Riyadh-Jeddah processing corridor hosts dairy ingredient clusters serving domestic brands and re-export channels to Kuwait and Bahrain.
United Arab Emirates
UAE gym chains and fitness retailers are pulling slow-release casein formulations into mainstream hypermarket distribution. ESMA labeling requirements for dairy derivatives exceed legacy standards, compressing formulation windows. Dubai-based ingredient traders are establishing direct ocean freight contracts with Australasian suppliers, bypassing European hub distribution.
Qatar
Doha's fitness sector expansion outpaces dedicated casein distribution infrastructure, creating positioning opportunities for specialized suppliers. The country's national food safety regulator enforces contaminant thresholds aligned with emerging GSO standards. Industrial zone development around Doha is attracting toll-processing investments for dairy ingredient manufacturing.
Kuwait
Processed food manufacturers in Kuwait City rely on re-export channels from Saudi dairy clusters for caseinate supplies. National standardization authority protocols for imported dairy derivatives track SFDA and ESMA convergence timelines. Shuwaikh industrial area hosts formulation facilities dependent on cross-border ingredient flows from Riyadh-Jeddah hubs.
Oman
Sultanate industrial zone subsidies for food ingredient manufacturing are attracting toll-processing investments that could reconfigure GCC casein trade flows. The country's national investment authority offers capital incentives for dairy derivative production facilities. Sohar Port free zone development targets transshipment positioning for regional ingredient distribution.
GCC Casein Market Key Industry Players
Direct procurement contracting dominates the current landscape as GCC food manufacturers bypass European re-export channels. Supplier concentration tilts toward Oceania and European dairy cooperatives with established halal certification pathways. Two strategic archetypes prevail: large-scale dairy cooperatives with integrated processing networks, and specialized ingredient formulators targeting sports nutrition segments. Capacity expansion in membrane filtration technology and strategic partnerships with regional distributors represent the primary competitive vectors.
Among dairy cooperative suppliers, Fonterra Co-operative Group and Arla Foods amba exemplify scale-driven positions anchored by integrated processing networks. Glanbia plc occupies a specialist tier focused on micellar casein formulations. These three entities represent distinct archetypes within the supplier base: Fonterra exemplifies cooperative-structured raw material dominance, Arla represents European dairy integration with regional distribution partnerships, and Glanbia illustrates specialized fractionation capabilities targeting precision nutrition applications.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Co-operative Group |
| NZMP |
| ADM |
| Lactalis Ingredients |
| FrieslandCampina Ingredients |
| Kerry Group plc |
| Glanbia plc |
| AMCO Proteins |
| Others |
Cost & Logistics Intelligence
Membrane filtration specialists concentrated in New Zealand's Waikato region command wage premiums that compress pricing spreads between standard caseinates and premium micellar fractions. Labor-cost differentials between Oceania processing hubs and European dairy cooperatives feed directly into tiered procurement economics for Saudi and Emirati food manufacturers.
Pricing Analysis
After-sales technical support and halal certification documentation are bundled into long-term offtake contracts rather than unbundled as line items. Contract-based long-term agreements dominate, with price differentiation driven by GSO pre-certification status and volume scale commitments. Pricing pressure stems from direct ocean freight contracting bypassing European consolidation points, compressing margins for traders dependent on Rotterdam hub-and-spoke distribution. Commodity purchasers in Kuwait and Oman exhibit highest price sensitivity; sports nutrition brands in the UAE demonstrate lowest sensitivity due to formulation specificity requirements.
Supply Chain Analysis
Halal certification pathway complexity gates supplier qualification timelines, stretching onboarding for new entrants. Raw material supply concentrates in New Zealand, Australia, and Denmark, drawing from skim milk powder, membrane filtration equipment, and enzymatic processing agents. Single-source vulnerability runs through Jeddah Islamic Port congestion and seasonal Oceania milk production cycles. Distribution runs through Riyadh-Jeddah dairy ingredient clusters serving domestic brands and re-export channels to Bahrain, Kuwait, and Oman.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration automation is displacing acid-precipitation legacy methods across GCC casein processing, compressing batch-to-batch variability and enabling micellar casein scale production.
For Market Incumbents: Hedge against whey protein hydrolysate substitution in infant nutrition by deepening captive supply of membrane filtration capacity in Saudi Arabia's Riyadh-Jeddah corridor. Lock in GSO pre-certification status ahead of full harmonization to defend registration moats against European re-export competitors. Prioritize technical service bundling to justify pricing premiums as direct procurement from Oceania erodes trader margins. For New Entrants and Emerging Players: Enter via Qatar's underpenetrated sports nutrition distribution infrastructure, where Doha fitness sector growth outpaces dedicated casein supplier presence. Target toll-processing partnerships in Oman's Sohar Port free zone, leveraging Sultanate industrial subsidies to establish regional ingredient manufacturing without greenfield capex. Lead with specialized micellar formulations and halal certification documentation to differentiate from commodity caseinate traders. For Investors and Strategic Acquirers: The window for entry favors membrane filtration technology owners with established GSO regulatory affairs capacity and direct Oceania supply relationships. Long-term viability hinges on backward integration into skim milk processing or captive toll-processing agreements in GCC industrial zones. Watch for SFDA-ESMA convergence implementation timelines as inflection signal for pan-GCC product registration economics.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Preserves protein micelle integrity for UAE sports nutrition brands requiring slow-release kinetics. |
| Direct Ocean Freight Contracting | Bypasses European hub consolidation to reduce landed costs for Saudi dairy processors sourcing from Fonterra. |
| GSO Pre-Certification Investment | Accelerates pan-GCC product registration as SFDA and ESMA standards converge toward harmonized thresholds. |
| Toll-Processing Partnership in Oman | Captures Sultanate industrial zone subsidies while reconfiguring regional trade flows through Sohar Port. |
| Specialized Micellar Formulation Development | Targets premium positioning in Qatar's underpenetrated fitness retail channel with differentiated slow-digestion profiles. |
Research Approach
Multi-period observation of casein import volumes, membrane filtration adoption rates, and GSO regulatory filing timelines anchored the trend analysis, supplemented by interviews with dairy ingredient procurement managers at Saudi food manufacturers, regulatory affairs leads navigating SFDA-ESMA convergence, sports nutrition brand formulators in the UAE, and Oceania dairy cooperative export directors. Secondary validation drew from GCC customs trade databases, GSO technical committee proceedings, Fonterra and Arla sustainability disclosures, and food industry import records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the Gulf food processing sector.
Input-output matrices structured demand projections across product type, application, form, and end-user segments, with cross-dimensional elasticity testing against halal certification timeline scenarios and climate-resilient storage cost assumptions. CAGRs were derived from regression analysis of historical procurement patterns and projected fitness sector penetration rates. Industry-specific forecast inputs included membrane filtration capacity buildout timelines in Saudi Arabia and direct ocean freight contract adoption rates at Jeddah Islamic Port.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended SFDA-ESMA divergence or Jeddah port congestion shocks. Model outputs reflect assumptions about GSO implementation timelines and Oceania milk production stability. A model refresh is warranted upon material change in Gulf Standardization Organization harmonization schedules or Saudi industrial zone subsidy structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Japan Dairy Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Global Butter Market
Dairy Products
Africa Yogurt Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Plain Yogurt Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Reconstituted Milk Market
Dairy Products
North America Sour Cream Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Canada Dairy Market