
 North America Yogurt Market | 2026-2036
North America Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
North America Yogurt Market Analytics
USDA Organic certification is bifurcating the competitive landscape into credentialed premium suppliers and conventional processors. Chobani LLC leverages its integrated upstate New York dairy network to control Greek yogurt supply from farm to shelf. General Mills Inc. competes through Yoplait's diversified portfolio spanning kids' snacking and adult functional lines. Danone S.A. anchors its North American position through Dannon's longstanding retail relationships and probiotic R&D infrastructure.
Yogurt denotes a fermented milk product manufactured through controlled bacterial culture of Lactobacillus bulgaricus and Streptococcus thermophilus, typically containing 10-15% milk solids and achieving a pH of 4.0-4.6. The coagulated gel serves nutritional, digestive health, and culinary substitution functions across retail and foodservice channels. Greek Yogurt commands disproportionate shelf space and margin contribution due to its protein density and straining process economics. Plant-Based Yogurt exhibits the steepest volume trajectory as oat and coconut bases displace dairy alternatives in allergen-sensitive households. Single-Serve Cups dominate convenience-oriented channels while Bulk Containers concentrate in club retail and institutional foodservice procurement.
The FDA governs standard of identity requirements under 21 CFR 131.200, while USDA Organic and Non-GMO Project verification create tiered market access thresholds for ingredient sourcing and label claims. State-level dairy compacts in Wisconsin, New York, and California impose additional fluid milk pricing and sourcing constraints that ripple through yogurt cost structures. Stakeholders must monitor evolving FDA guidance on fermented foods and live culture labeling as these determinations will reshape permissible health claims and reformulation investments.
Market Dynamics
The FDA's updated nutrition labeling requirements for added sugars are forcing reformulation investments across branded portfolios while health-conscious consumers in fitness and wellness segments expand purchases of protein-enriched and gut-health products.
Growth Catalysts
- USDA Organic Certification:Premium suppliers capture margin expansion through credentialed positioning that conventional processors cannot replicate without multi-year conversion timelines.
- Protein Density Demand:Fitness-oriented consumers in urban coastal markets prioritize Greek yogurt's straining process economics over standard cultured products.
- Gut-Health Positioning:Live culture labeling under evolving FDA guidance creates permissible health claims that drive repeat purchase behavior in allergen-sensitive households.
Market Restraints
- Fluid Milk Pricing Volatility:State-level dairy compacts in Wisconsin, New York, and California impose sourcing constraints that ripple unpredictably through yogurt cost structures.
- Straining Process Economics:Greek yogurt's protein density requires three to four times milk volume versus standard yogurt, compressing margins when input costs spike.
- Plant-Based Substitution:Oat and coconut bases displace dairy alternatives in allergen-sensitive households, threatening conventional volume retention.
Strategic Opportunities
- Club Retail Bulk Formats:Institutional foodservice procurement and warehouse channels concentrate volume in multi-serve containers with lower per-unit logistics costs.
- Probiotic R&D Infrastructure:Live culture strain development creates defensible intellectual property for functional positioning beyond commodity cultured products.
- Northeast Dairy Corridor:Integrated farm-to-shelf networks in upstate New York enable traceability claims that coastal urban markets premiumize.
Industry Challenges
- Reformulation Timeline Compression:FDA added-sugar disclosure mandates require rapid recipe redevelopment without consumer taste-profile disruption.
- Live Culture Stability:Maintaining probiotic viability through shelf-life duration demands cold-chain precision that strains distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Yogurt Market |
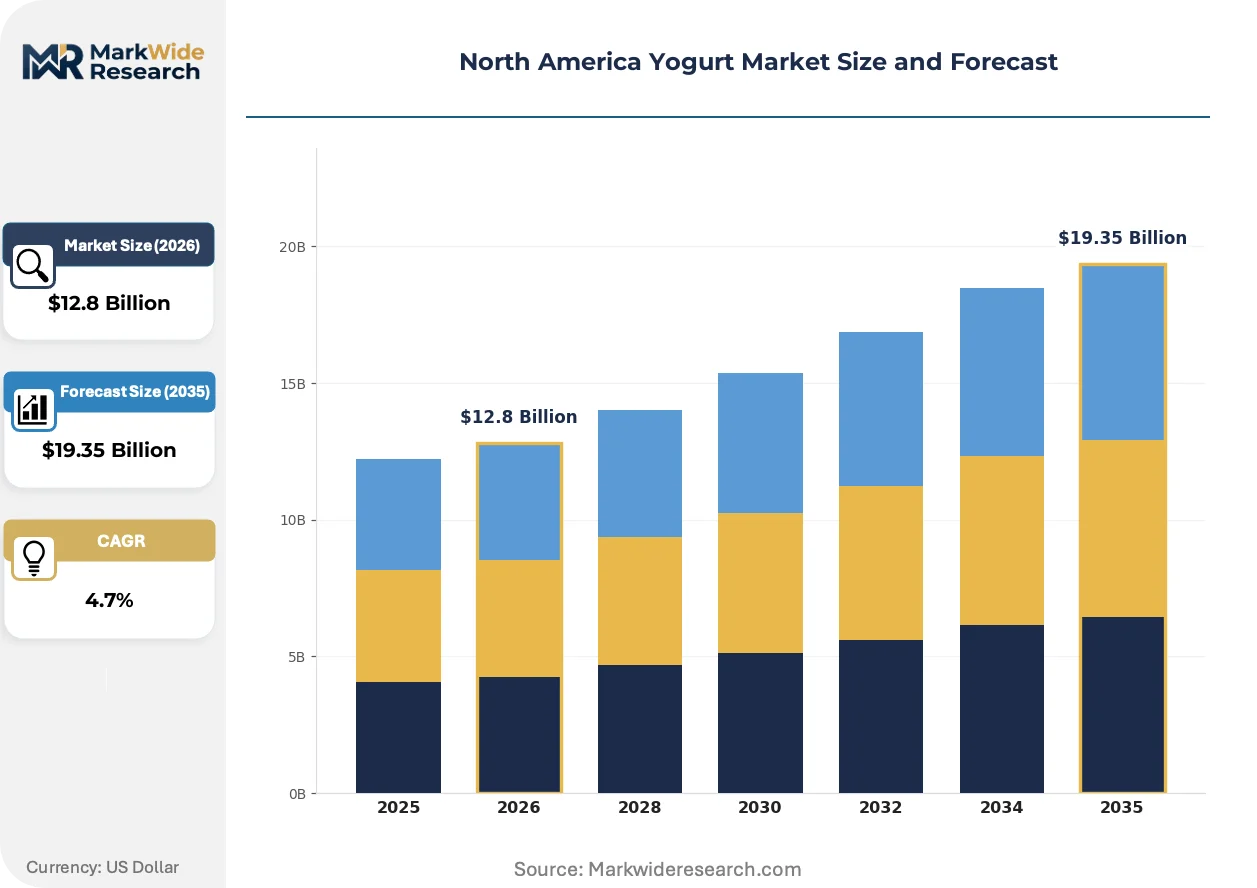
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Yogurt, Greek Yogurt, Plant-Based Yogurt, Low-Fat Yogurt Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores End User: Individuals, Fitness Enthusiasts, Families, Restaurants Packing Type: Single-Serve Cups, Multi-Pack, Pouches, Bulk Containers |
| Companies Covered | FAGE International S.A., Dairy Farmers of America Inc., Chobani LLC, Fairlife LLC, The Dannon Company Inc., Danone S.A., General Mills Inc., Lakeview Farms, LLC, Groupe Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Yogurt Market Evolving Landscape
Product architecture is fragmenting across dairy and plant-based substrates while regulatory disclosure requirements reshape permissible marketing claims and distribution channels consolidate around direct-store-delivery versus warehouse models.
Precision fermentation for dairy protein is decomposing traditional milk sourcing dependencies. Ingredient technology suppliers now license animal-free whey and casein to plant-based yogurt formulators seeking taste parity. This biotechnology is compressing the cost gap between oat-coconut bases and conventional cultured products.
Health Canada and the FDA are converging on stricter live culture count thresholds for probiotic label claims. Manufacturers must now validate colony-forming units through shelf-life testing rather than production-day guarantees. The functional yogurt segment faces reformulation investments or claim reduction.
Direct-to-subscription models are capturing recurring revenue from wellness-focused households. Traditional retail slotting fees lose leverage as digitally native brands build proprietary customer data. Urban coastal markets in the United States show highest trial rates for auto-replenishment programs.
North America Yogurt Market Segmentation
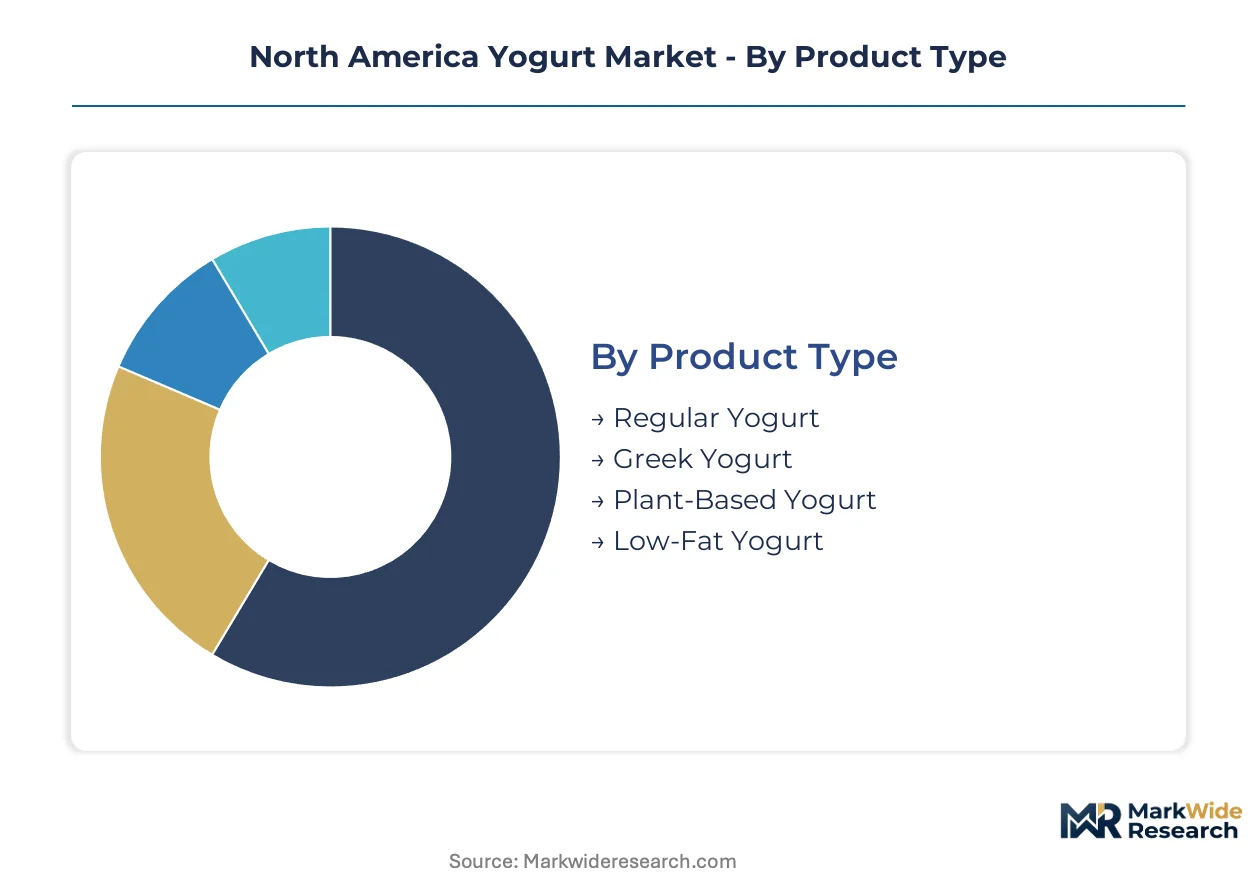
Substitution pressures from plant-based alternatives and protein-enriched formats are fragmenting traditional category boundaries. Manufacturers must align R&D investment and distribution strategy with which segments retain pricing power versus those facing margin compression.
Product Type:
Greek Yogurt and Plant-Based Yogurt face the most acute substitution threats from precision-fermented dairy proteins and cross-category protein snacks.
- Greek Yogurt:Strained cultured milk achieving protein density of 15-20 grams per serving through whey removal. Demand concentrates in urban coastal markets where fitness-oriented consumers prioritize macronutrient labels over price per ounce.
- Plant-Based Yogurt:Fermented oat, coconut, or almond bases targeting allergen-sensitive households. Oat formulations in particular are displacing earlier-generation soy and almond products through superior taste neutrality and barista functionality.
- Regular Yogurt:Standard cultured milk with 8-11 grams protein per serving, manufactured without straining. Volume retention depends on price-competitive positioning in family-oriented retail channels.
- Low-Fat Yogurt:Skim or reduced-fat milk bases meeting FDA standard of identity for light claims. Reformulation challenges intensify under added-sugar disclosure mandates as fat reduction traditionally required sugar compensation.
Greek Yogurt anchors the volume base while Plant-Based Yogurt gains share at the steepest rate.
Distribution Channel:
Cost tier stratification separates high-service retail from logistics-optimized channels with divergent margin structures.
- Supermarkets:Full-service retail with refrigerated case space allocated through slotting fees and scan-based trading. Chobani LLC and General Mills Inc. compete for end-cap positioning in Northeast dairy corridor locations.
- Online Retail:Direct-to-subscription models capturing recurring revenue from wellness-focused households. Urban coastal markets show highest trial rates for auto-replenishment programs bypassing traditional slotting economics.
- Convenience Stores:Grab-and-go refrigerated units targeting single-serve impulse purchases. Limited shelf space favors established brands with proven velocity metrics.
- Health Stores:Specialty retail emphasizing USDA Organic and Non-GMO Project verification. Premium positioning supports credentialed suppliers that conventional processors cannot replicate without multi-year conversion timelines.
Supermarkets retain the revenue base while Online Retail expands most quickly through subscription capture.
End User:
Application-specific formulation requirements separate performance nutrition from household routine consumption.
- Fitness Enthusiasts:Protein-density prioritization drives Greek yogurt preference and post-workout consumption occasions. Straining process economics justify premium pricing in this segment.
- Families:Multi-serve procurement concentrates in club retail with volume-driven cost minimization. Kid-oriented formulations with controlled sugar profiles face reformulation pressure under FDA labeling updates.
- Individuals:Single-serve convenience orientation dominates urban professional households with limited refrigeration capacity. Pouch and cup formats compete for commuter consumption occasions.
- Restaurants:Foodservice procurement of bulk containers for culinary substitution in sauces, marinades, and breakfast service. Cold-chain precision demands strain distribution economics for live culture viability.
Families generate the volume foundation while Fitness Enthusiasts command the steepest price premiums.
Packing Type:
Volume scale and customer type determine format economics from single-serve margin extraction to bulk logistics efficiency.
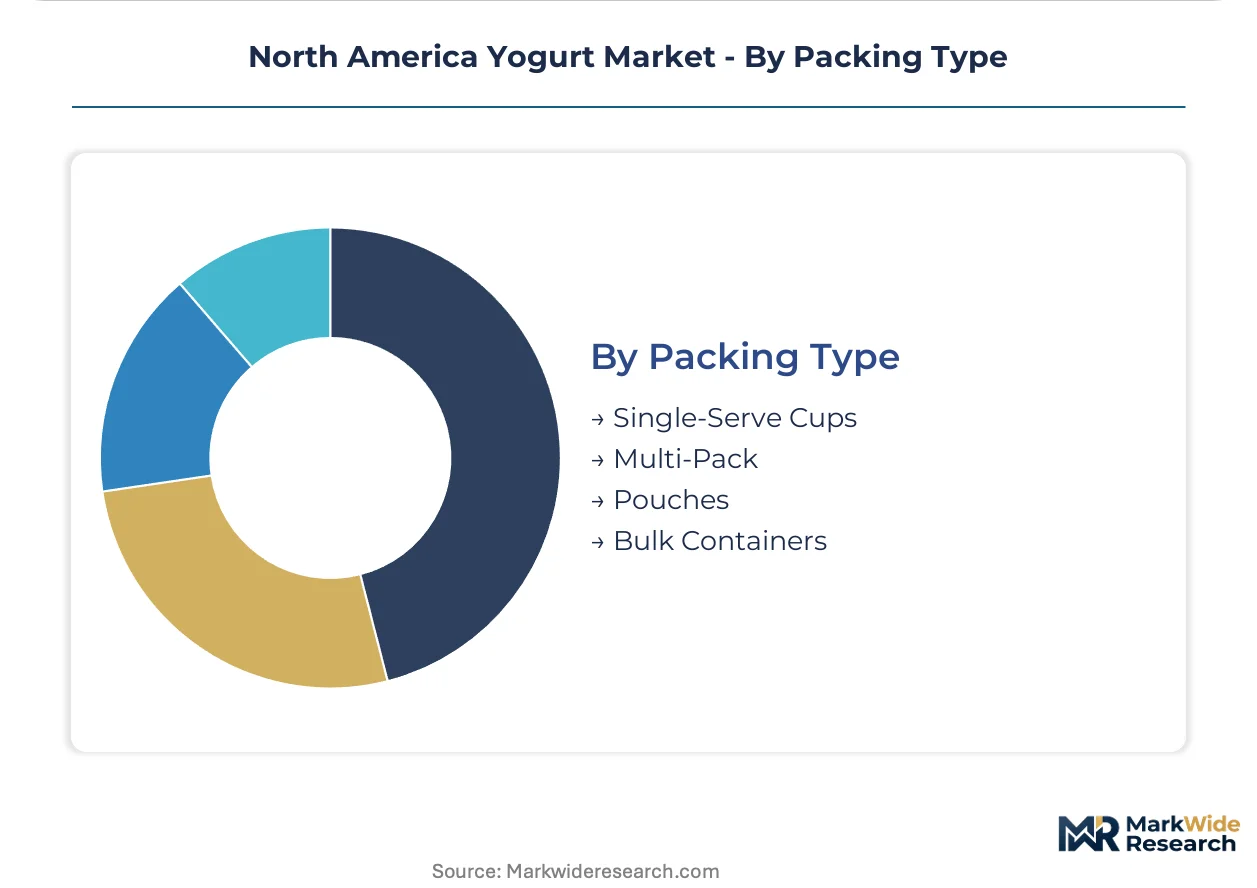
- Single-Serve Cups:Individual portion control with foil lidding for live culture protection. Convenience-oriented channels in United States urban markets concentrate demand for commuter and workplace consumption.
- Bulk Containers:Multi-pound tubs for club retail and institutional foodservice procurement. Lower per-unit logistics costs support margin retention when fluid milk pricing volatility compresses standard yogurt economics.
- Multi-Pack:Four to six unit configurations balancing portion control with household efficiency. Family-oriented retail channels favor this format for refrigerator inventory management.
- Pouches:Flexible packaging for children's snacking and on-the-go consumption. Spill-resistant design targets school lunch and travel occasions where cup stability is constrained.
Single-Serve Cups dominate convenience channels while Bulk Containers capture institutional procurement at scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification incentives and FDA labeling mandates are reshaping procurement patterns across North American markets. State-level dairy compacts in Wisconsin, New York, and California create divergent cost structures that influence regional competitive positioning. Urban coastal corridors concentrate demand for protein-enriched and gut-health positioned products.
United States
Fitness-oriented consumers in urban coastal markets drive Greek yogurt preference through protein-density prioritization. The FDA's updated nutrition labeling requirements for added sugars are pressuring reformulation across branded portfolios. The Northeast dairy corridor, particularly upstate New York, anchors integrated farm-to-shelf networks that enable traceability claims.
Canada
Health Canada is converging with FDA standards on stricter live culture count thresholds for probiotic label claims. Supply management policies through the Canadian Dairy Commission impose distinct pricing frameworks compared to US market structures. Ontario and Quebec dairy processing clusters concentrate manufacturing capacity serving domestic retail and cross-border export channels.
Mexico
Growing middle-class households in Mexico City and Monterrey metro areas are expanding purchases of premium-positioned yogurt formats. COFEPRIS, the national health regulator, maintains distinct fermented food standards that create compliance complexity for multinational portfolios. The Bajío Region dairy belt supplies fluid milk to major processing facilities serving central Mexican population centers.
North America Yogurt Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution channel access. The competitive structure bifurcates between credentialed premium suppliers holding USDA Organic verification and conventional processors facing multi-year conversion timelines. Three archetypes dominate: integrated dairy cooperatives controlling upstream milk supply, multinational CPG conglomerates leveraging diversified brand portfolios, and private specialists concentrating on single-serve convenience formats. Capacity expansion in Greek yogurt straining facilities and direct-to-subscription channel development represent the dominant competitive moves reshaping market access.
Within the multinational CPG tier, Danone S.A. and General Mills Inc. exemplify scale-driven positioning through diversified brand architectures spanning functional, kids', and mass-market lines. Chobani LLC anchors the private specialist archetype with concentrated focus on Greek yogurt production and direct-store-delivery penetration in core Northeast and coastal markets. These three companies collectively represent the competitive tension between scale economies and specialized positioning that defines current market structure.
| Leading Market Players |
|---|
| FAGE International S.A. |
| Dairy Farmers of America Inc. |
| Chobani LLC |
| Fairlife LLC |
| The Dannon Company Inc. |
| Danone S.A. |
| General Mills Inc. |
| Lakeview Farms, LLC |
| Groupe Lactalis |
| Others |
Value Network & Pricing Analysis
USDA Organic certification gates both supplier qualification and price differentiation simultaneously, bifurcating the North American yogurt landscape into credentialed premium tiers and conventional commodity pools. FDA added-sugar disclosure mandates compress reformulation timelines, forcing simultaneous investment in supply chain traceability and label-claim compliance that reshapes procurement economics across the value chain.
Pricing Analysis
Certification level creates the primary spread between premium USDA Organic tiers and conventional standard offerings. Three-tier pricing structure across premium, standard, and economy levels reflects straining process economics, live culture viability investments, and plant-based substrate premiums. Cost compression in Greek yogurt is intensifying because fluid milk pricing volatility from state-level dairy compacts unpredictably inflates input requirements. Families in club retail channels exhibit highest price sensitivity, while fitness enthusiasts in urban coastal markets prioritize protein density over per-ounce cost.
Supply Chain Analysis
Fluid milk procurement from Wisconsin, New York, and California dairy belts anchors upstream concentration, with straining facility capacity in the Northeast dairy corridor creating midstream chokepoints. Raw material dependencies center on Grade A fluid milk, live culture strains, and oat-coconut bases for plant-based lines. Single-source vulnerability in proprietary probiotic strain supply threatens formulation continuity for functional positioning. Distribution runs through direct-store-delivery networks for refrigerated case velocity, supplemented by warehouse club channels for bulk container logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America yogurt market functions as a defensive-moat story where regulatory entrenchment through FDA standard of identity and evolving live culture labeling creates switching costs that protect incumbent positioning against commodity erosion.
For Market Incumbents: Fortify upstream milk supply through backward integration into Northeast dairy corridor farms, securing traceability claims that urban coastal markets premiumize. Expand straining facility capacity to capture Greek yogurt volume retention against precision-fermented protein substitution. Prioritize probiotic R&D infrastructure investment to defend functional positioning as Health Canada and FDA converge on stricter colony-forming unit thresholds. For New Entrants and Emerging Players: Direct-to-subscription service gaps in allergen-sensitive household targeting present white-space opportunity, as incumbent brands under-serve auto-replenishment demand with proprietary customer data capture. Precision-fermented dairy protein licensing enables taste-parity positioning in plant-based segments without multi-year organic conversion timelines. Enter through online retail subscription models bypassing traditional supermarket slotting fee barriers. For Investors and Strategic Acquirers: FDA's evolving guidance on fermented foods and live culture labeling reshapes the acquisition landscape toward targets with validated shelf-life testing infrastructure and cold-chain distribution precision. Long-term viability centers on defensible intellectual property in strain development and integrated farm-to-shelf networks rather than brand equity alone. Watch for Health Canada-FDA regulatory convergence timing as signal for accelerated reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Subscription Channel Development | Auto-replenishment programs capture recurring revenue from wellness-focused households in urban coastal markets. |
| Probiotic Strain R&D Investment | Live culture intellectual property creates defensible positioning beyond commodity cultured products under FDA guidance evolution. |
| Backward Integration into Fluid Milk Supply | Farm-to-shelf networks in upstate New York enable traceability claims that command premium pricing in credentialed tiers. |
| Precision Fermentation Partnership | Animal-free whey licensing compresses cost gaps between oat-coconut bases and conventional dairy alternatives. |
| Club Retail Bulk Format Expansion | Multi-serve containers concentrate institutional procurement volume with lower per-unit logistics costs. |
Research Methodology
Cross-validation between primary interviews with dairy cooperative procurement directors, yogurt brand managers, retail category buyers, and refrigerated distribution specialists anchors the qualitative findings. Secondary validation draws from FDA 21 CFR filings, USDA Organic certification databases, state dairy compact pricing records, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down category spending analysis across the projection horizon.
Sensitivity analysis tests forecast outputs against fluid milk pricing volatility scenarios and regulatory timeline acceleration assumptions. Segmentation dimensions span product type, distribution channel, end user application, and packaging format, with regional regulatory cluster as an additional modeled layer. CAGRs derive from historical trajectory analysis adjusted for structural shift impacts including plant-based substitution rates and precision fermentation adoption curves.
Underlying assumptions cover stable FDA enforcement posture on added-sugar labeling and continued Health Canada convergence with US probiotic standards, with deviation risk concentrated in state-level dairy compact renegotiations and live culture stability breakthroughs. Practitioners should keep alternative scenarios live as precision fermentation cost curves and subscription channel penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Cheese Market
Dairy Products
Filled Cheese Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Skimmed Milk Market
Dairy Products
Dairy Products Market
Dairy Products
India Milk Protein Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Cheese Shreds Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Cheddar Cheese Market