
 GCC Fresh Milk Market | 2026-2036
GCC Fresh Milk Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fresh Milk Market Intelligence
Hypermarket and supermarket buyer consolidation across Saudi Arabia and the UAE is recalibrating procurement leverage toward large-format retailers. Almarai leverages its integrated dairy farming network to sustain volume leadership across the Gulf. NADEC anchors supply security through government-backed agricultural development in Saudi Arabia. Al Ain Dairy competes on proximity advantages, drawing from Emirates-based herd operations to serve UAE retail channels.
Fresh milk denotes raw or minimally processed bovine milk with fat content typically standardized to 3.25% whole milk or reduced to 1-2% for low-fat variants, pasteurized at 72°C for 15 seconds to eliminate pathogens while preserving nutritional integrity. Its primary commercial purpose centers on direct consumption, beverage manufacturing, and foodservice preparation across institutional and retail channels. Conventional fresh milk dominates volume due to price accessibility, though organic variants command premium positioning among health-conscious households in Dubai and Riyadh. Tetra Pak cartons lead packaging formats for ambient distribution, while polyethylene bottles control chilled retail segments across Gulf supermarkets.
Saudi Food and Drug Authority (SFDA) standards govern microbiological limits and labeling requirements, while UAE's Ministry of Climate Change and Environment enforces import protocols and local dairy hygiene benchmarks. SASO certification requirements for dairy products shape market access conditions for regional suppliers. Stakeholders must monitor evolving Gulf harmonization efforts on dairy safety standards and water-use regulations affecting feed crop sustainability.
Market Dynamics
Hypermarket consolidation across Saudi Arabia and the UAE is compressing supplier margins and forcing dairy processors to restructure their distribution networks around large-format retail procurement calendars.
Growth Catalysts
- Foodservice Channel Expansion:Hotel and restaurant procurement of fresh milk is accelerating across the Gulf, driven by tourism infrastructure investments in Dubai and Riyadh.
- SFDA Microbiological Standards:Saudi Food and Drug Authority enforcement of stricter pathogen limits is elevating quality benchmarks and rewarding compliant domestic processors with preferential shelf placement.
- Pasteurization Technology Upgrades:HTST (High-Temperature Short-Time) systems are replacing older batch processes, extending shelf life without chemical preservatives.
Market Restraints
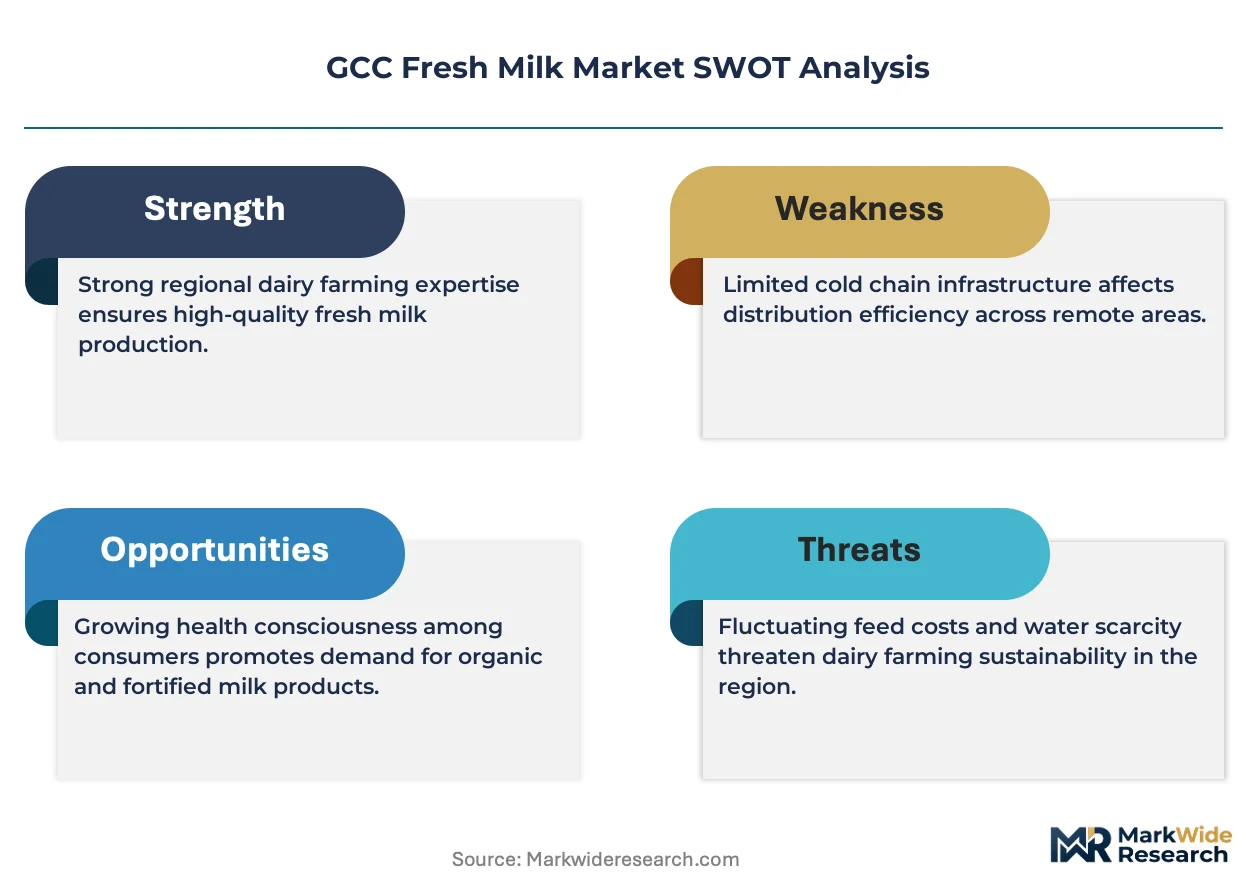
- Feed Import Dependency:Alfalfa and soybean meal price volatility constrains margin predictability for Gulf dairy operations lacking captive feed production.
- Water Scarcity Constraints:Saudi Arabia's groundwater depletion regulations limit herd expansion in traditional dairy regions, capping domestic supply growth.
- Extended Chilled Distribution:Temperature-controlled logistics requirements across the Arabian Peninsula impose infrastructure costs that ambient-stable alternatives circumvent.
Strategic Opportunities
- Organic Certification Uptake:Premium positioning among health-conscious households in Dubai creates margin expansion potential for certified producers meeting EU-equivalent standards.
- Smart Packaging Integration:Time-temperature indicators and NFC-enabled freshness tracking are converging with consumer transparency demands in UAE retail channels.
- Kuwait and Bahrain Penetration:Underdeveloped local dairy infrastructure in smaller Gulf states creates import substitution openings for Saudi and Emirati processors with excess capacity.
Industry Challenges
- Veterinary Specialist Shortage:Gulf dairy operations face recruiting friction for bovine reproductive health and mastitis management expertise.
- Labeling Compliance Timelines:UAE Ministry of Climate Change and Environment updated bilingual labeling mandates require packaging redesign cycles that disrupt seasonal marketing calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fresh Milk Market |
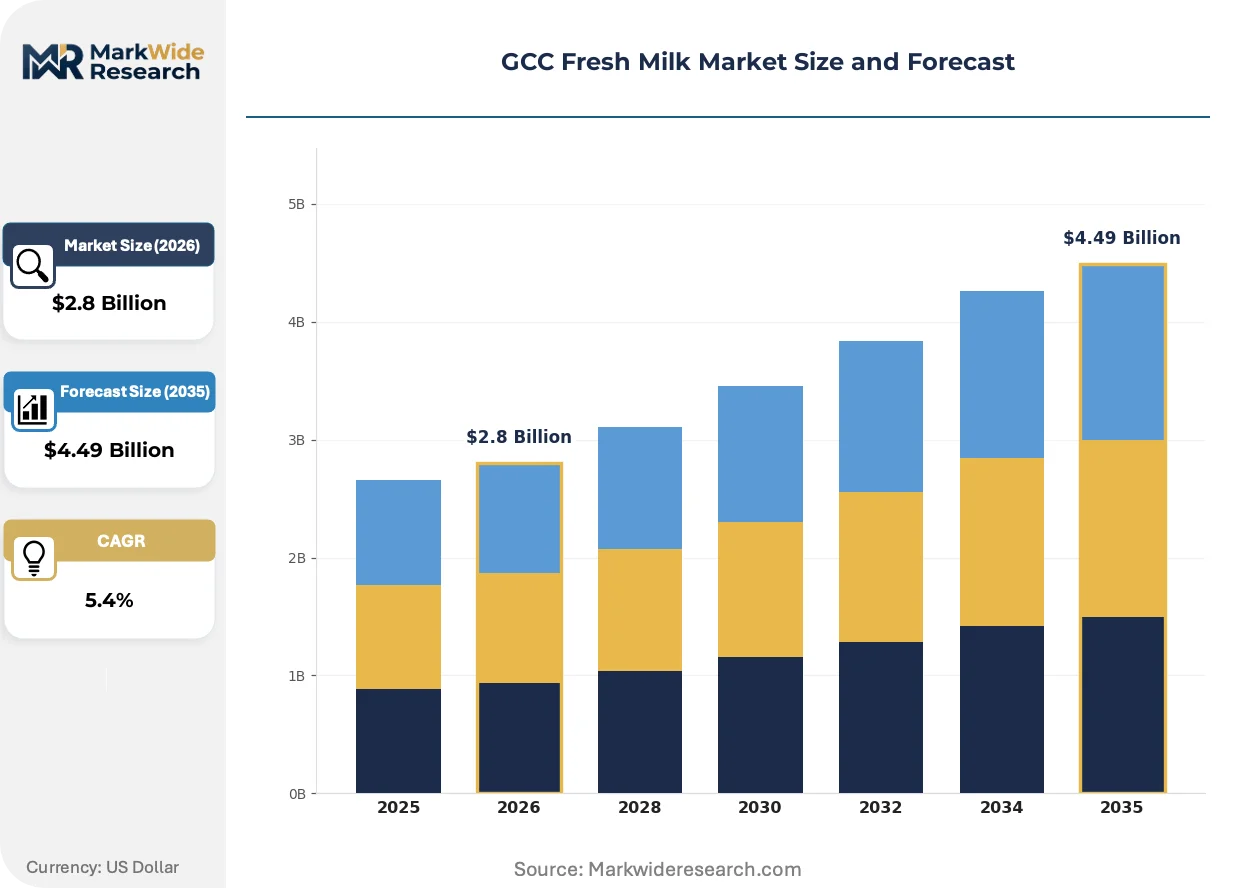
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Flavored, Low-Fat Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Customer Type: Households, Restaurants, Cafeterias, Institutions Packaging Type: Cartons, Bottles, Pouches, Tetra Packs |
| Companies Covered | Al Ain Dairy, National Agricultural Development Company (NADEC), Almarai, Balade, Saudia Dairy & Foodstuff Company (SADAFCO), Al Safi Danone, Al Rawabi Dairy Company, United Dairy Farms, Nada Dairy, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fresh Milk Market Strategic Shifts & Innovations
Processing automation and cold-chain digitization are compressing spoilage rates and enabling just-in-time replenishment models across Gulf retail networks. These shifts favor capital-intensive operators with integrated logistics control.
Extended Shelf Life (ESL) technology is absorbing capital investment across Saudi processing facilities. Almarai and NADEC are retrofitting production lines with microfiltration and advanced thermal systems. This technology is absorbing market share from conventional pasteurized milk by enabling longer distribution radii without freezing infrastructure.
SASO certification requirements for dairy products are tightening ingredient disclosure and nutritional labeling standards. Importers must now demonstrate equivalence with Saudi Food and Drug Authority benchmarks before market entry. Smaller regional traders without dedicated compliance teams are exiting the market, concentrating import channels around established distributors.
Direct-store-delivery (DSD) networks are losing ground to centralized distribution centers serving hypermarket banners. Carrefour and Lulu Group International are consolidating procurement through their own chilled warehouses, bypassing traditional wholesaler intermediaries. This pattern is most visible in the UAE's Dubai-Abu Dhabi corridor, where retail buyer concentration now exceeds 60 percent of organized trade volume.
GCC Fresh Milk Market Segmentation
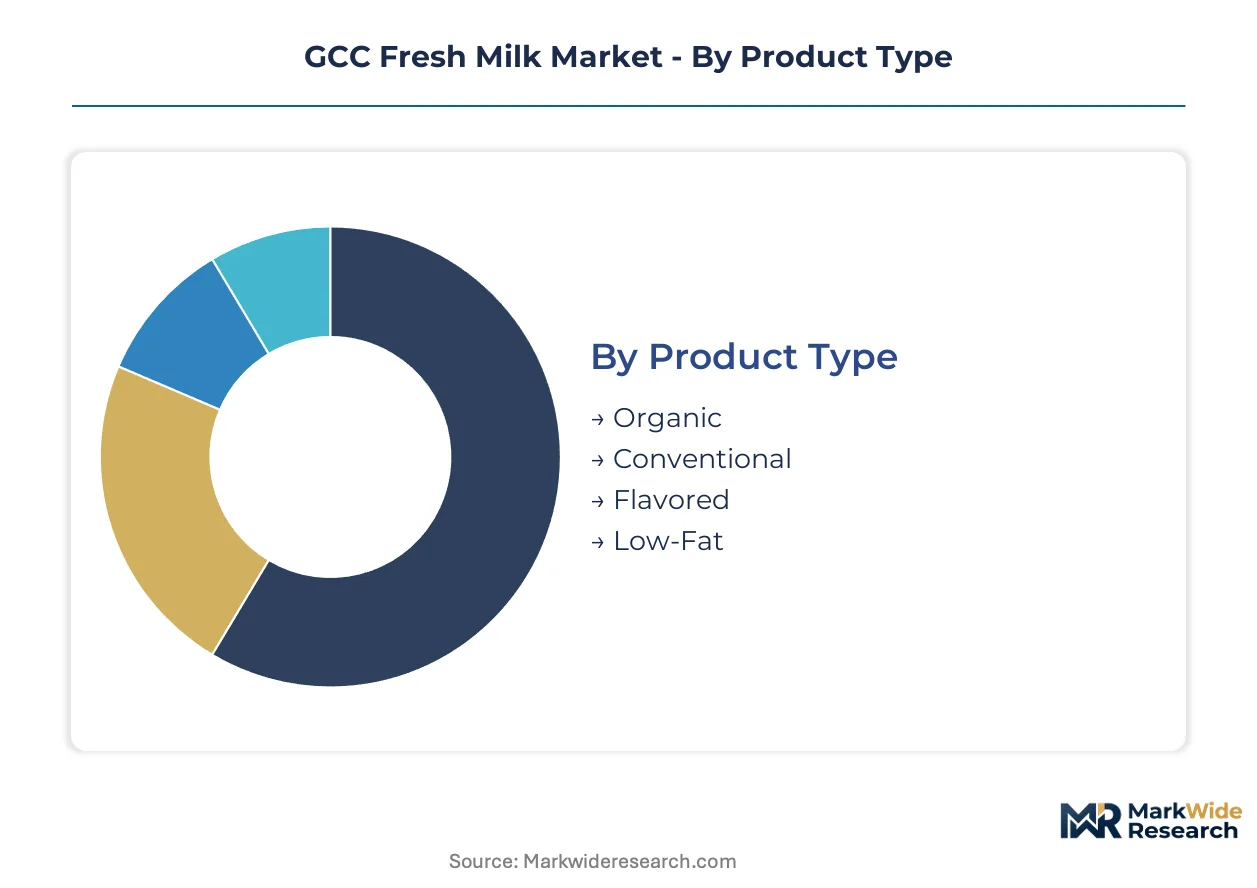
Fresh milk segmentation in the GCC reflects divergent supply chain requirements across ambient-stable and chilled distribution networks. Product type and packaging format choices determine cold-chain intensity, while channel and customer segmentation governs procurement cadence and margin structure.
Product Type:
Integration depth varies sharply: conventional and low-fat variants flow through mass retail as standalone commodities, while organic and flavored offerings embed premium positioning within health-conscious and experience-driven consumption occasions.
- Conventional:Standardized 3.25% whole milk pasteurized via HTST systems at 72°C for 15 seconds. Volume concentrates in Saudi Arabia's Riyadh-Jeddah corridor and UAE's Dubai-Abu Dhabi axis, where hypermarket procurement calendars drive supply scheduling.
- Organic:Milk sourced from herds raised without synthetic hormones or antibiotics, certified to EU-equivalent standards. Dubai households command premium positioning here, with SFDA microbiological standards elevating entry barriers for uncertified suppliers.
- Flavored:Chocolate, strawberry, and vanilla variants targeting children's consumption and foodservice beverage preparation.
- Low-Fat:1-2% fat content variants processed through centrifugal separation before standardization.
Volume placements concentrate in Conventional; the faster expansion belongs to Organic.
Distribution Channel:
Cost tier stratification separates capital-intensive chilled infrastructure from leaner ambient-capable networks, with implications for supplier working capital requirements.
- Supermarkets:Large-format retailers including Carrefour and Lulu Group International operate centralized chilled warehouses bypassing traditional wholesalers. Buyer consolidation across Saudi Arabia and the UAE compresses supplier margins while demanding just-in-time replenishment compliance.
- Wholesalers:Traditional intermediaries serving smaller retail accounts and foodservice operators with bulk breaking and credit extension functions.
- Convenience Stores:High-frequency, small-format outlets prioritizing grab-and-go chilled singleserve packaging.
- Online Retail:E-commerce platforms with dedicated cold-chain last-mile requirements, expanding fastest in UAE urban corridors.
Procurement leverage clusters with Supermarkets; Online Retail climbs the fastest among emerging channels.
Customer Type:
Application context distinguishes direct consumption patterns from ingredient-input requirements, with divergent quality specifications and volume predictability.
- Households:End-consumers purchasing for direct drinking, breakfast cereal preparation, and home cooking applications across Saudi and Emirati residential markets.
- Restaurants:Hotel and foodservice operators procuring standardized volumes for beverage and sauce preparation, with tourism infrastructure investments in Dubai and Riyadh accelerating demand.
- Cafeterias:Institutional feeding operations in corporate and educational facilities with cost-sensitive procurement and consistent delivery requirements.
- Institutions:Healthcare and government facilities with stringent SASO certification compliance and extended payment terms.
Demand scale favors Households; Restaurants gain share fastest on tourism expansion.
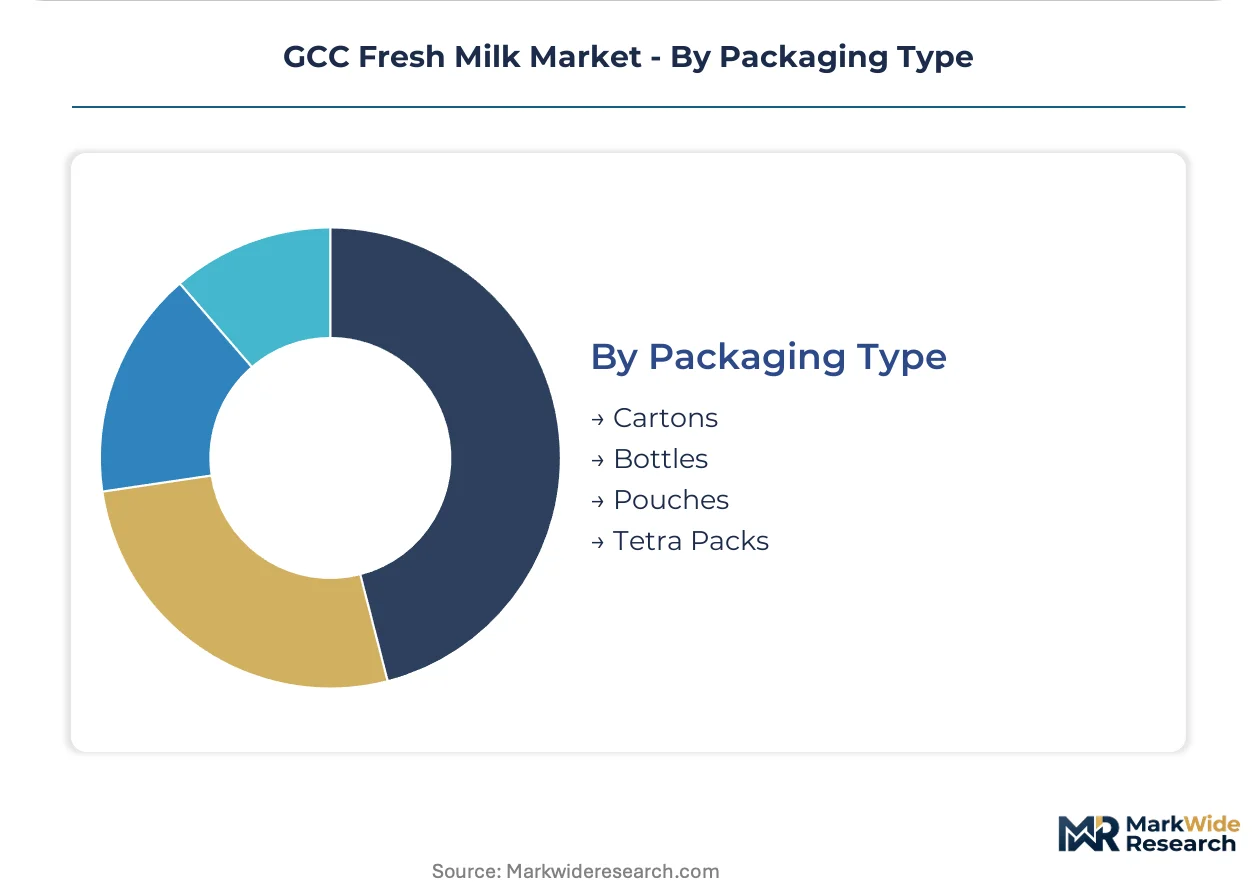
Packaging Type:
Maturity gradients separate established ambient formats from emerging chilled alternatives, with technology investment requirements determining supplier participation thresholds.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without continuous refrigeration, dominating long-shelf-life segments across Gulf retail networks.
- Bottles:Polyethylene containers controlling chilled retail segments, with transparency features supporting freshness signaling in UAE supermarket displays.
- Cartons:Gable-top chilled cartons for shorter-shelf-life pasteurized milk, common in Saudi domestic production.
- Pouches:Flexible film packaging for economy-tier market entry, prevalent in private-label and discount channel positioning.
Installed base concentrates in Tetra Packs; Bottles expand fastest on chilled channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's Riyadh-Jeddah corridor and the UAE's Dubai-Abu Dhabi axis, where hypermarket procurement calendars drive supply scheduling across the Gulf. Hotel and restaurant procurement of fresh milk is rising across the region, with tourism infrastructure investments in Dubai and Riyadh accelerating foodservice channel expansion.
Saudi Arabia
Hypermarket consolidation across Riyadh and Jeddah is compressing supplier margins and forcing dairy processors to restructure distribution networks around large-format retail procurement calendars. Saudi Food and Drug Authority enforcement of stricter pathogen limits elevates quality benchmarks and rewards compliant domestic processors with preferential shelf placement. The Riyadh-Jeddah corridor anchors volume concentration, with Almarai and NADEC leveraging integrated operations to serve concentrated retail demand.
United Arab Emirates
Dubai households command premium positioning for organic variants, creating margin expansion potential for certified producers meeting EU-equivalent standards. The Ministry of Climate Change and Environment enforces updated bilingual labeling mandates that require packaging redesign cycles disrupting seasonal marketing calendars. The Dubai-Abu Dhabi axis dominates organized trade volume, where retail buyer concentration now exceeds 60 percent and centralized chilled warehouses bypass traditional wholesaler intermediaries.
Kuwait
Underdeveloped local dairy infrastructure creates import substitution openings for Saudi and Emirati processors with excess capacity seeking geographic diversification. The country's national food safety regulator maintains import protocols that prioritize suppliers with established Gulf compliance track records. Kuwait City retail channels absorb chilled milk volumes from neighboring producers, though extended distribution radii impose temperature-controlled logistics costs.
Bahrain
Smaller market scale limits captive dairy infrastructure investment, perpetuating dependence on cross-border supply from Saudi Arabia's Eastern Province. National food safety standards align with Gulf harmonization efforts on dairy safety benchmarks and water-use regulations affecting feed crop sustainability. Manama retail and foodservice channels source predominantly from Saudi processors with established cross-border cold-chain logistics.
Qatar
Foodservice channel expansion driven by hospitality sector investments creates incremental demand for standardized fresh milk volumes in beverage and sauce preparation. National import protocols favor suppliers with SASO certification and demonstrated equivalence with Saudi Food and Drug Authority benchmarks. Doha retail consolidation mirrors patterns visible in Dubai and Riyadh, with hypermarket banners operating centralized procurement functions.
GCC Fresh Milk Market Key Industry Players
Saudi producers anchor one tier; UAE specialists hold proximity advantages in their home market. The vendor base stratifies across integrated dairy farming networks, government-backed agricultural operations, and Emirates-based herd operators. Three archetypes dominate: scale-driven processors with captive feed and distribution control, state-affiliated entities securing supply security through agricultural development programs, and proximity-based competitors drawing from localized herd operations. Competitive moves concentrate on HTST pasteurization technology upgrades and Extended Shelf Life line retrofits enabling longer distribution radii.
Within the integrated network tier, Almarai exemplifies scale-driven positioning through its Gulf-spanning dairy farming infrastructure. NADEC occupies a state-affiliated anchor position, leveraging government-backed agricultural development in Saudi Arabia to secure supply security. Al Ain Dairy represents the proximity-based archetype, drawing from Emirates-based herd operations to serve UAE retail channels with shortened cold-chain requirements. These three entities collectively illustrate the geographic and structural fault lines shaping competitive dynamics across the GCC fresh milk market.
| Leading Market Players |
|---|
| Al Ain Dairy |
| National Agricultural Development Company (NADEC) |
| Almarai |
| Balade |
| Saudia Dairy & Foodstuff Company (SADAFCO) |
| Al Safi Danone |
| Al Rawabi Dairy Company |
| United Dairy Farms |
| Nada Dairy |
| Others |
Cost & Logistics Intelligence
Veterinary specialist scarcity across the Arabian Peninsula widens labor-cost spreads between premium and economy tiers, compressing mid-market positioning as processors absorb recruitment premiums or cede quality-sensitive accounts.
Pricing Analysis
Volume-mass conventional milk trades on thin margins through hypermarket procurement calendars, while organic certification and ESL technology command 15-25 percent spreads at shelf. Price differentiation hinges on feed-source traceability and cold-chain integrity certification. Pricing pressure stems from Saudi groundwater depletion regulations capping herd expansion and forcing import substitution. Households in Riyadh and Jeddah exhibit highest price sensitivity; Dubai foodservice operators absorb premiums for consistent quality.
Supply Chain Analysis
Saudi Arabia's SASO certification requirements and UAE's bilingual labeling mandates reshape sourcing toward domestic processors with compliance infrastructure. Feed crop production draws from Argentina, the United States, and Spain; alfalfa and soybean meal dependencies expose margins to commodity volatility. Single-source vulnerability concentrates in chilled distribution networks spanning the Arabian Peninsula. Distribution runs through centralized hypermarket warehouses bypassing traditional wholesaler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypermarket buyer consolidation functions as a consolidation play, with procurement leverage compression forcing sub-scale processors toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from Carrefour and Lulu Group International procurement calendars by securing backward integration into captive feed production and HTST pasteurization upgrades. Defend shelf placement through SFDA compliance investment and DSD network rationalization toward centralized distribution compliance. For New Entrants and Emerging Players: E-commerce direct-to-household channels in Dubai and Abu Dhabi offer lowest barrier-to-entry white-space, with online retail expanding fastest among emerging channels. Target organic certification gaps among health-conscious Emirates households; pursue white-label supply contracts with underdeveloped Kuwaiti retail infrastructure as beachhead. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier Saudi processors possessing SASO certification and excess capacity for Kuwait-Bahrain export substitution, given tourism-driven foodservice demand acceleration. Long-term viability favors integrated operators with captive feed and distribution control; monitor SFDA enforcement intensity as margin-structure inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ESL Technology Retrofit | Microfiltration and advanced thermal systems extend distribution radii without freezing infrastructure across Saudi facilities. |
| Organic Certification Investment | EU-equivalent standards unlock premium positioning among Dubai health-conscious households and command shelf priority. |
| Feed Crop Backward Integration | Captive alfalfa production insulates margin predictability from Argentine and US commodity price volatility. |
| Centralized Distribution Compliance | Hypermarket chilled warehouse integration secures procurement access as Carrefour and Lulu consolidate buying. |
| Kuwait-Bahrain Market Entry | Underdeveloped local dairy infrastructure creates import substitution openings for Saudi processors with excess capacity. |
Research Approach
Trade databases, regulatory filings from SFDA and UAE Ministry of Climate Change and Environment, and dairy processor annual disclosures formed the secondary backbone. Primary interviews with dairy operations managers, hypermarket category buyers, veterinary supply specialists, and cold-chain logistics coordinators combined with secondary validation. Bottom-up volume modeling and top-down value reconciliation anchored triangulation across Saudi, UAE, Kuwait, and Bahrain market clusters.
Historical trendline analysis of pasteurization technology adoption, organic certification uptake, and hypermarket channel penetration informed projection frameworks across the analysis window. Segmentation dimensions encompassed product type, packaging format, distribution channel, and customer application. CAGRs derived from elasticity-adjusted demand curves incorporating feed cost indices and tourism infrastructure investment trajectories.
The model holds under stable Gulf harmonization on dairy safety standards; deviation in groundwater depletion regulation enforcement or feed import tariff shifts would revise trajectory bounds. Forecasts reflect documented assumptions on herd expansion constraints and retail buyer consolidation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Germany Dairy Market
Dairy Products
Kefir Market
Dairy Products
Japan Dairy Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
US Cheese Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Cheese Color Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Natural Cheese Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
United States Dairy Market
Dairy Products
UHT Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
Europe Dairy Based Beverages Market