
 United States Casein and Caseinate Market | 2026-2036
United States Casein and Caseinate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Casein and Caseinate Market Analytics
Domestic dairy protein processing is shifting toward higher-value fractionation as Midwest cooperatives expand micellar casein capacity. AMCO Proteins leverages its Wisconsin manufacturing base to supply food-grade sodium caseinate to meat processors. Fonterra Co-operative Group Limited anchors trans-Pacific supply through its US distribution network for sports nutrition applications. Farbest Brands specializes in spray-dried calcium caseinate for infant formula customers, occupying a defensible niche in pediatric nutrition.
Casein denotes the phosphoprotein family comprising roughly eighty percent of bovine milk protein, precipitated at pH 4.6 and subsequently processed into soluble caseinate salts through alkali neutralization; caseinates function primarily as emulsifiers, water binders, and texture modifiers across food systems. Sodium caseinate leads the product type category due to its superior whipping properties and extensive use in coffee creamers and whipped toppings. Nutritional supplements represent the fastest-expanding end use industry as protein isolate demand from CrossFit and endurance athlete segments drives reformulation of ready-to-drink beverages.
The FDA exercises jurisdiction over casein and caseinate labeling through the Federal Food, Drug, and Cosmetic Act, while USDA's Agricultural Marketing Service administers grade standards for dry milk proteins; these frameworks determine whether products qualify for "natural" or "clean label" positioning on retail shelves. State-level dairy pricing under Federal Milk Marketing Orders further constrains raw skim milk availability for casein manufacture. Stakeholders must monitor pending FDA guidance on plant-protein versus dairy-protein equivalence claims, as this ruling will directly affect caseinate substitution economics in processed foods.
Market Dynamics
Midwest dairy cooperatives are consolidating micellar casein fractionation capacity around Wisconsin and Minnesota processing clusters, tightening raw skim milk availability under Federal Milk Marketing Order pricing structures and forcing downstream formulators toward long-term offtake contracts.
Growth Catalysts
- Protein fortification mandates in school nutrition programs:USDA's updated meal pattern requirements are expanding caseinate procurement for fortified beverages in K-12 cafeterias across the Great Lakes states.
- CrossFit and endurance athlete segments:Ready-to-drink beverage reformulation is accelerating sodium caseinate adoption for post-workout recovery formulations with superior whipping stability.
- Infant formula nutritional standards:FDA's nutrient specifications for iron-fortified formulas are sustaining calcium caseinate demand from pediatric nutrition manufacturers seeking spray-dried emulsion stability.
Market Restraints
- Federal Milk Marketing Order pricing volatility:Class III milk price fluctuations directly compress casein manufacturing margins when raw skim milk costs spike seasonally.
- Plant-protein substitution economics:Pea and oat protein isolates are capturing clean-label positioning in coffee creamers previously dominated by sodium caseinate emulsifiers.
- Midwest processing concentration risk:Wisconsin and Minnesota facilities handle the majority of domestic micellar casein output, creating single-point vulnerability during extreme weather events.
Strategic Opportunities
- Southeastern US manufacturing expansion:Georgia and North Carolina offer underutilized dairy processing infrastructure for caseinate production closer to Atlantic coast distribution hubs.
- Cell-cultured dairy protein convergence:Precision fermentation-derived casein is creating hybrid formulation opportunities with traditional dairy isolates in sports nutrition applications.
- Biodegradable packaging mandates:Several Northeastern states are implementing extended producer responsibility laws that favor caseinate-based edible film coatings for food preservation.
Industry Challenges
- Specialized dairy protein engineering talent scarcity:Fractionation process optimization requires expertise in membrane filtration physics that outpaces university dairy science program output.
- Clean-label certification timelines:Non-GMO Project verification and USDA Organic accreditation for caseinate derivatives extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Casein and Caseinate Market |
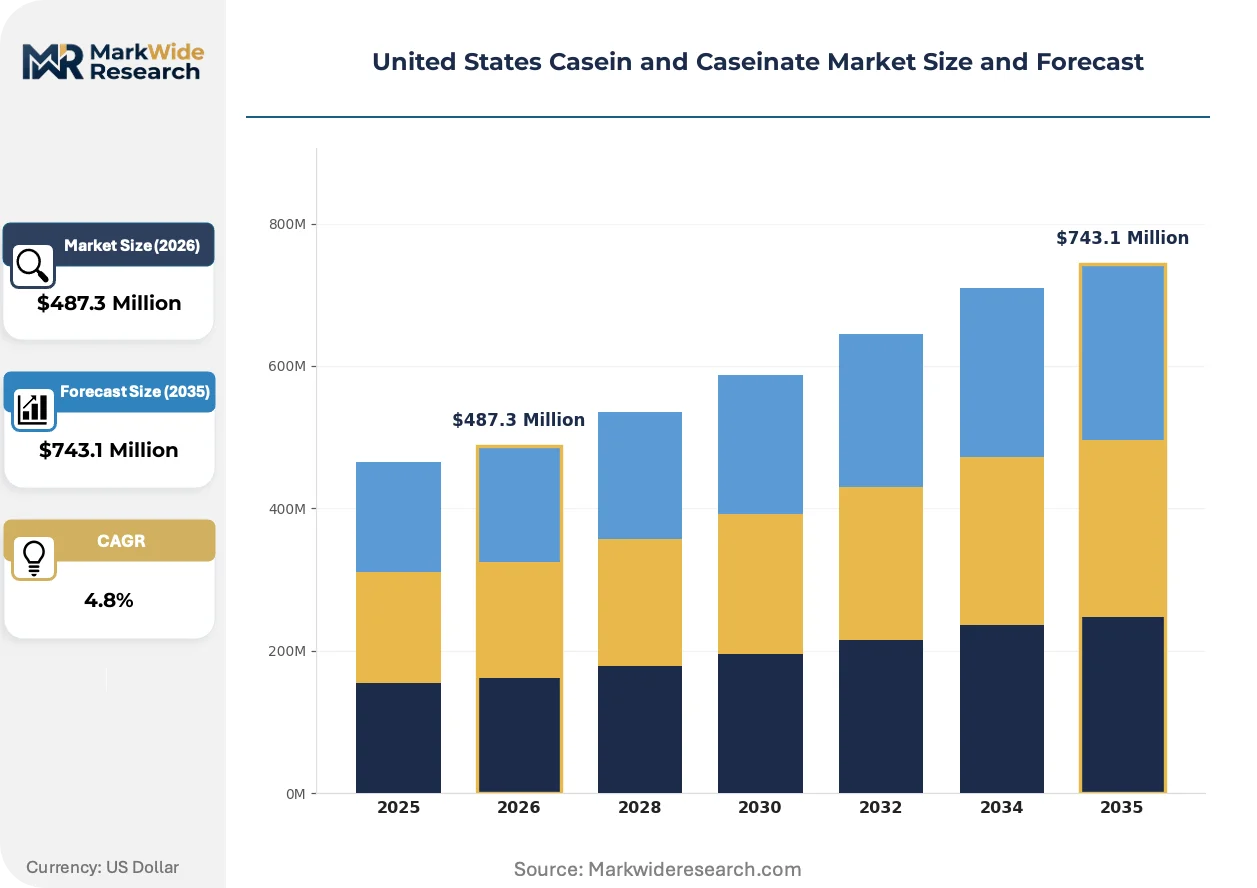
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Caseinate, Sodium Caseinate, Potassium Caseinate, Caseinates Blend End Use Industry: Dairy Products, Beverages, Bakery, Nutritional Supplements Form: Powder, Liquid, Granules, Spray-dried Application: Food Processing, Meat Products, Infant Formula, Dietary Supplements |
| Companies Covered | Hoogwegt Group, AMCO Proteins, Arla Foods amba, Farbest Brands, Erie Foods International Inc., Fonterra Co-operative Group Limited, Milk Specialties Global, Kerry Group, FrieslandCampina Ingredients, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Casein and Caseinate Market Evolving Landscape
Micellar casein isolation technology is advancing filtration efficiency while regulatory scrutiny of dairy-protein labeling equivalence intensifies, reshaping how formulators communicate nutritional content to protein-conscious consumers.
Membrane filtration technology is converging with ceramic microfiltration systems to recover native micellar casein structures without denaturation. Sports nutrition manufacturers in the Rocky Mountain region are adopting these systems at pilot scale. The structural integrity preservation is converging with premium isolate pricing tiers previously reserved for cross-flow ultrafiltration outputs.
FDA guidance on plant-protein versus dairy-protein equivalence claims remains pending, creating formulation uncertainty for processed food manufacturers. The agency's draft framework would require amino acid scoring corrections on labels using caseinate blends. Infant formula and medical nutrition segments are most affected, with several manufacturers preemptively reformulating to single-source protein declarations.
Direct-to-consumer subscription models are disrupting traditional ingredient distribution channels for small-batch protein product startups. Specialty caseinate blends previously sold through foodservice distributors now move through e-commerce portals targeting CrossFit box owners and endurance coaching networks. This channel compression is most visible in Texas and Florida metropolitan markets where micro-roasteries and functional beverage incubators cluster.
United States Casein and Caseinate Market Segmentation
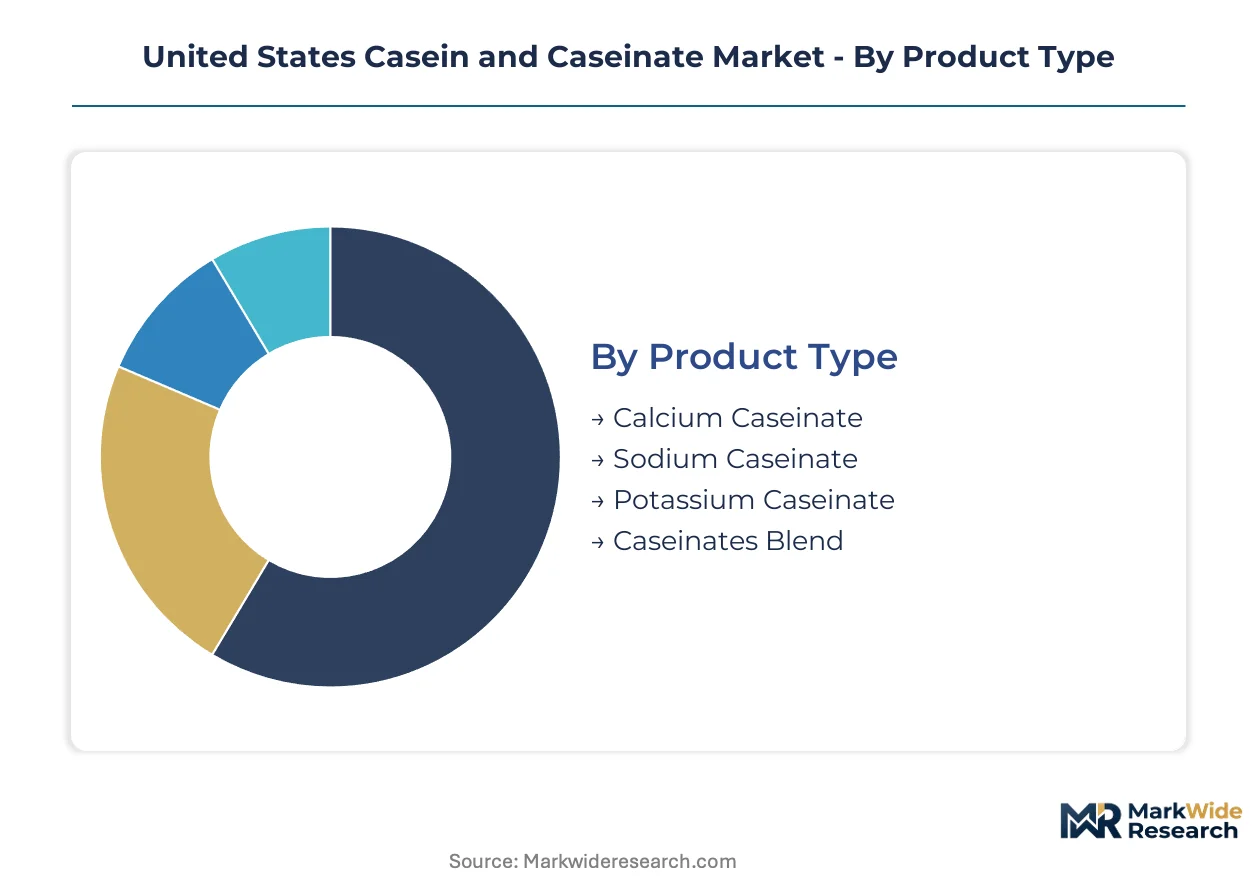
Casein and caseinate manufacturers configure production lines around distinct functional specifications that separate commodity-grade emulsifiers from premium nutritional isolates. Formulators select product types based on mineral content requirements, while end-use industries impose divergent purity and solubility standards that reshape procurement patterns across the value chain.
Product Type:
Buyers differentiate primarily by mineral cation functionality and emulsion stability requirements in target food matrices.
- Sodium Caseinate:Manufactured through alkali neutralization of acid casein with sodium hydroxide, yielding superior whipping properties and foam stability. Coffee creamer manufacturers in the Great Lakes states specify this grade for aerosol whipped topping applications where overrun consistency is critical.
- Calcium Caseinate:Produced via calcium hydroxide neutralization, delivering enhanced heat stability and slower gastric emptying characteristics. Pediatric nutrition compounders in Minnesota and Wisconsin source spray-dried calcium caseinate for iron-fortified infant formulas requiring extended emulsion shelf life.
- Potassium Caseinate:Neutralized with potassium hydroxide to support reduced-sodium labeling claims in processed meat systems.
- Caseinates Blend:Custom mineral ratios formulated for specific viscosity and buffering requirements in industrial food processing.
Volume sits with sodium caseinate; growth tilts toward calcium caseinate.
End Use Industry:
Application-specific regulatory thresholds and protein fortification mandates drive divergent purity requirements across customer segments.
- Nutritional Supplements:Sports nutrition and medical food segments demand micellar casein isolates with native protein structure preservation. CrossFit training facilities and endurance coaching networks in Texas and Florida metropolitan markets are accelerating procurement of instantized sodium caseinate for post-workout recovery beverages.
- Dairy Products:Processed cheese and analogue systems require emulsifying salts with controlled calcium-binding capacity. Wisconsin dairy cooperatives consume bulk sodium caseinate for spreadable cheese matrices where melt stability determines product performance.
- Beverages:Ready-to-drink protein fortification depends on cold-water dispersibility and flavor masking characteristics.
- Bakery:Dough conditioning and crust browning applications utilize calcium caseinate for its water-binding and Maillard reaction properties.
Revenue concentrates in nutritional supplements; expansion is steepest in beverages.
Form:
Downstream handling infrastructure and reconstitution protocols determine physical format selection across manufacturing facilities.
- Spray-dried:Atomized drying produces hollow spherical particles with superior rehydration kinetics and bulk flow characteristics. Infant formula manufacturers specify this format for precise dosing in continuous blending operations.
- Powder:Standard roller-dried or spray-dried particulates serve general food processing applications with conventional mixing equipment.
- Liquid:Pre-hydrated caseinate slurries eliminate dust exposure and reduce hydration time in high-throughput meat processing plants.
- Granules:Agglomerated particles improve dispersibility in low-shear mixing environments common in small-batch nutritional compounding.
Shipments favor powder; premium pricing attaches to spray-dried.
Application:
Finished product regulatory classification and label positioning requirements segment demand by nutritional claim permissibility.
- Infant Formula:FDA nutrient specifications mandate specific protein quality metrics and mineral fortification levels. Calcium caseinate suppliers to pediatric nutrition manufacturers face extended Non-GMO Project verification timelines that compress product launch windows.
- Dietary Supplements:Sports nutrition and medical food categories permit structure-function claims that drive isolate purity requirements. Rocky Mountain region manufacturers are piloting ceramic microfiltration systems to capture premium pricing tiers for native micellar casein.
- Food Processing:Emulsification and texture modification in processed foods depends on cost-optimized caseinate grades with standard functional specifications.
- Meat Products:Binding and moisture retention in comminuted meat systems utilizes sodium caseinate for its gelation and fat emulsification properties.
Volume flows through food processing; value accumulates in infant formula.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's dairy belt anchors domestic casein production through concentrated whey and casein processing infrastructure. Federal Milk Marketing Orders govern raw skim milk allocation across Midwest cooperatives. Regional demand patterns diverge sharply between nutritional supplement hubs on the coasts and traditional dairy processing strongholds in the upper Midwest.
Midwest
Wisconsin and Minnesota processing clusters handle the majority of domestic micellar casein fractionation capacity. USDA's Agricultural Marketing Service administers grade standards for dry milk proteins that determine clean-label positioning eligibility. Minneapolis-St. Paul corridor facilities are expanding ceramic microfiltration pilot programs for native protein structure preservation.
Southeast
Georgia and North Carolina offer underutilized dairy infrastructure for caseinate production closer to Atlantic distribution hubs. State-level extended producer responsibility laws in several Northeastern jurisdictions favor caseinate-based edible film coatings. Atlanta metropolitan incubators are attracting functional beverage startups sourcing specialty caseinate blends through direct-to-consumer channels.
Texas and Florida
CrossFit training facilities and endurance coaching networks in Houston, Dallas, Miami, and Tampa accelerate procurement of instantized sodium caseinate for post-workout recovery beverages. FDA jurisdiction over casein labeling through the Federal Food, Drug, and Cosmetic Act shapes structure-function claim permissibility. Dallas-Fort Worth micro-roasteries and functional beverage clusters are compressing traditional ingredient distribution channels.
Rocky Mountain Region
Sports nutrition manufacturers in Colorado and Utah are adopting ceramic microfiltration systems at pilot scale for premium isolate pricing tiers. State environmental regulations governing industrial dairy processing effluent affect membrane filtration system deployment. Denver-Boulder corridor facilities are capturing native micellar casein structures previously reserved for cross-flow ultrafiltration outputs.
Great Lakes States
USDA's updated school nutrition meal pattern requirements are expanding caseinate procurement for fortified beverages in K-12 cafeterias. Federal Milk Marketing Order pricing volatility directly compresses manufacturing margins when raw skim milk costs spike seasonally. Chicago-area dairy cooperatives are consolidating fractionation capacity and forcing downstream formulators toward long-term offtake contracts.
United States Casein and Caseinate Market Competitive Landscape
Global majors compete with regional champions across supply security and formulation expertise dimensions. The vendor base stratifies into three tiers: trans-Pacific dairy cooperatives with US distribution networks, Midwest-based protein processors leveraging proximity to raw material sources, and specialty ingredient distributors serving niche pediatric and sports nutrition segments. Dominant competitive moves include backward integration into captive skim milk supply and technology licensing for membrane filtration system deployment.
Among trans-Pacific suppliers, Fonterra Co-operative Group Limited and Arla Foods amba occupy positions anchored by cooperative ownership structures and established US distribution infrastructure. Within the domestic processing tier, AMCO Proteins exemplifies regional champions leveraging Wisconsin manufacturing proximity to supply food-grade caseinates, while Farbest Brands represents specialists occupying defensible positions in spray-dried calcium caseinate for pediatric nutrition applications. These archetypes illustrate how geographic concentration of dairy processing infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| Hoogwegt Group |
| AMCO Proteins |
| Arla Foods amba |
| Farbest Brands |
| Erie Foods International Inc. |
| Fonterra Co-operative Group Limited |
| Milk Specialties Global |
| Kerry Group |
| FrieslandCampina Ingredients |
| Others |
Value Network & Pricing Analysis
Extended producer responsibility laws in several Northeastern states are gating qualified supply access and premium-tier pricing eligibility for caseinate-based edible film coatings. Manufacturers without biodegradable packaging certification face exclusion from institutional procurement channels serving K-12 cafeterias and hospital nutrition programs.
Pricing Analysis
Service bundling separates technical formulation support from commodity-grade sodium caseinate transactions, with AMCO Proteins and Farbest Brands unbundling membrane filtration consulting for standard-tier buyers. Three-tier pricing structure across premium native micellar isolates, standard spray-dried caseinates, and economy roller-dried grades reflects certification tier and volume scale differentiation. Cost compression in economy-tier sodium caseinate is intensifying because Federal Milk Marketing Order price spikes compress manufacturing margins seasonally. Institutional buyers in school nutrition programs exhibit highest price sensitivity, while infant formula compounders demonstrate lowest sensitivity due to FDA-mandated protein quality specifications.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin and Minnesota processing clusters handling the majority of domestic micellar casein fractionation capacity. Raw skim milk availability draws from Federal Milk Marketing Order pools, while ceramic microfiltration membranes and alkali neutralization chemicals rest on specialized dairy equipment suppliers. Tariff exposure on New Zealand-sourced micellar casein isolates threatens trans-Pacific supply security for sports nutrition manufacturers. Distribution runs through foodservice distributors for bulk industrial accounts and direct-to-consumer e-commerce portals targeting CrossFit facilities and endurance coaching networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States casein and caseinate market is transitioning from acid precipitation legacy methods toward ceramic microfiltration-native protein preservation technology. Precision fermentation-derived casein is displacing traditional dairy isolates in hybrid sports nutrition formulations.
For Market Incumbents: Anticipate plant-protein substitution threats by securing captive skim milk supply through backward integration into Midwest cooperative ownership structures. Invest in Non-GMO Project verification and USDA Organic accreditation to defend premium-tier positioning against emerging precision fermentation competitors. Expand ceramic microfiltration capacity in Wisconsin and Minnesota facilities to capture native micellar casein pricing premiums previously reserved for cross-flow ultrafiltration outputs.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Texas and Florida metropolitan CrossFit box owners and endurance coaching networks with instantized sodium caseinate blends. Exploit underutilized dairy processing infrastructure in Georgia and North Carolina to establish Atlantic coast manufacturing presence closer to functional beverage startup clusters. Prioritize biodegradable packaging certification to access Northeastern institutional procurement channels implementing extended producer responsibility mandates.
For Investors and Strategic Acquirers: FDA guidance publication on plant-protein versus dairy-protein equivalence claims is the leading indicator that caseinate substitution economics will shift dramatically in processed food applications. Target acquisition candidates with established pediatric nutrition supply relationships and spray-dried calcium caseinate production capabilities. Monitor ceramic microfiltration technology licensing agreements as signals of premium isolate market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Skim Milk Supply | Federal Milk Marketing Order pricing volatility threatens margin stability for non-integrated processors. |
| Ceramic Microfiltration Technology Licensing | Native micellar casein structure preservation commands premium pricing tiers in sports nutrition applications. |
| Non-GMO Project Verification Investment | Clean-label certification extends product launch cycles but defends positioning against plant-protein substitutes. |
| Southeastern US Manufacturing Expansion | Georgia and North Carolina infrastructure reduces distribution costs to Atlantic coast functional beverage clusters. |
| Precision Fermentation Hybrid Formulation Development | Cell-cultured dairy protein convergence creates new application opportunities in medical nutrition segments. |
Research Methodology
Document review covered FDA Federal Register filings, USDA Agricultural Marketing Service grade standards, and Federal Milk Marketing Order administrative records, complemented by interviews with dairy cooperative procurement directors, infant formula compounder R&D leads, sports nutrition brand managers, and membrane filtration equipment specialists. Secondary validation drew from SEC 10-K disclosures of listed dairy processors, customs trade data on casein imports, and industry association technical publications. Bottom-up volume estimates from processing facility capacities were triangulated against top-down demand projections from end-use industry consumption patterns.
Cross-referencing historical Federal Milk Marketing Order pricing volatility against expert panel assessments of skim milk availability shaped the forecast framework across the analysis window. Segmentation modeling incorporated product type mineral cation functionality, end-use industry regulatory thresholds, form reconstitution protocols, and application-specific purity requirements. CAGRs were derived from trend extrapolation of protein fortification mandate implementation timelines and CrossFit facility expansion patterns. Forecast inputs included ceramic microfiltration adoption rates and precision fermentation technology maturation curves.
FDA guidance delays on equivalence claims, Federal Milk Marketing Order pricing reform proposals, and extreme weather events affecting Midwest processing clusters are the dominant revision risks to modeled projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Butter and Margarine Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Gruyere Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Europe Yogurt Market
Dairy Products
Cream Powder Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Fluid Milk Market
Dairy Products
Global Milk Protein Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Lactic Butter Market
Dairy Products
Dairy Concentrates Market
Dairy Products
North America Dairy Market
Dairy Products
Dry Buttermilk Market