
 Latin America Cheese Market | 2026-2036
Latin America Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cheese Market Intelligence
Brazil's southeastern dairy corridor is reshaping regional cheese supply dynamics through expanded pasteurization capacity and whey processing investments. Groupe Lactalis leverages its multi-brand portfolio to dominate premium retail channels across São Paulo and Rio de Janeiro. Conaprole anchors Uruguayan milk supply into Mercosur export flows, while Mastellone Hermanos specializes in mozzarella production for Argentine pizza chains and food service operators.
Cheese comprises curdled milk solids separated from whey, with moisture content, fat-in-dry-matter ratios, and aging protocols defining commercial grades and functional performance in cooking or table applications. Mozzarella captures dominant food service volume across Latin American pizza and quick-service restaurant chains, while cheddar occupies mature retail segments in Chile and Colombia. Cream cheese expands fastest through bakery and dessert applications, though supermarket distribution channels concentrate margin pools through private-label placement and slotting fee structures.
ANVISA in Brazil, COFEPRIS in Mexico, and Senasa in Argentina enforce divergent dairy pathogen limits and labeling standards that fragment cross-border product registration. Mercosur's harmonized sanitary protocols reduce technical barriers for Uruguayan and Argentine exporters, but national fortification mandates and front-of-pack warning label laws in Chile and Mexico force formulation adjustments. Stakeholders must monitor regulatory asymmetries between national dairy agencies while building flexible production lines capable of switching between fortification and clean-label specifications without asset stranding.
Market Dynamics
Cold-chain infrastructure gaps between São Paulo's refrigerated logistics clusters and secondary cities force cheese processors to route through temperature-controlled consolidation hubs, extending lead times and concentrating margin capture with integrated distributors.
Growth Catalysts
- Processed food portfolio expansion:Brazilian and Mexican manufacturers are expanding cheese procurement for ready-to-eat and frozen meal lines, pulling additional whey and curd volumes through industrial dairy channels.
- Mercosur sanitary harmonization:Aligned pathogen testing protocols and traceability standards are reducing technical barriers for cross-border cheese flows between Uruguay, Argentina, and Brazil.
- Urban consumption clustering:São Paulo state and Mexico's central dairy belt concentrate cold-chain investment and retail distribution density, creating efficient last-mile delivery economics for perishable cheese categories.
Market Restraints
- Feed cost volatility:Argentine and Brazilian dairy operations face margin compression from imported soybean meal and corn price swings, transmitting directly to milk procurement costs for cheese plants.
- Supply concentration risk:Groupe Lactalis dominates premium retail channels across São Paulo and Rio de Janeiro, limiting shelf access for mid-tier processors without slotting fee capacity.
- Regulatory fragmentation:Divergent pathogen limits between ANVISA in Brazil, COFEPRIS in Mexico, and Senasa in Argentina force duplicate testing and label reformulation for multi-country product lines.
Strategic Opportunities
- Colombian market underpenetration:Cheddar and aged cheese categories show whitespace in Colombian retail channels, where private-label penetration remains below Brazilian levels and premium import substitution potential exists.
- Clean-label reformulation:Chile's front-of-pack warning label laws and Mexico's sugar-sodium regulations are creating first-mover advantages for processors with flexible production lines capable of fortification switching.
- Food service direct distribution:Argentine pizza chains and Brazilian quick-service operators are bypassing traditional wholesale layers through direct mozzarella supply contracts, compressing distributor margins.
Industry Challenges
- Refrigerated logistics talent scarcity:Cold-chain operations across Brazil's northeastern expansion corridors lack sufficient technicians trained in HACCP-compliant temperature monitoring and equipment maintenance.
- Multi-jurisdiction certification timelines:Cross-border cheese registration requires sequential approvals from national dairy agencies, with ANVISA and COFEPRIS review cycles extending product launch windows by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cheese Market |
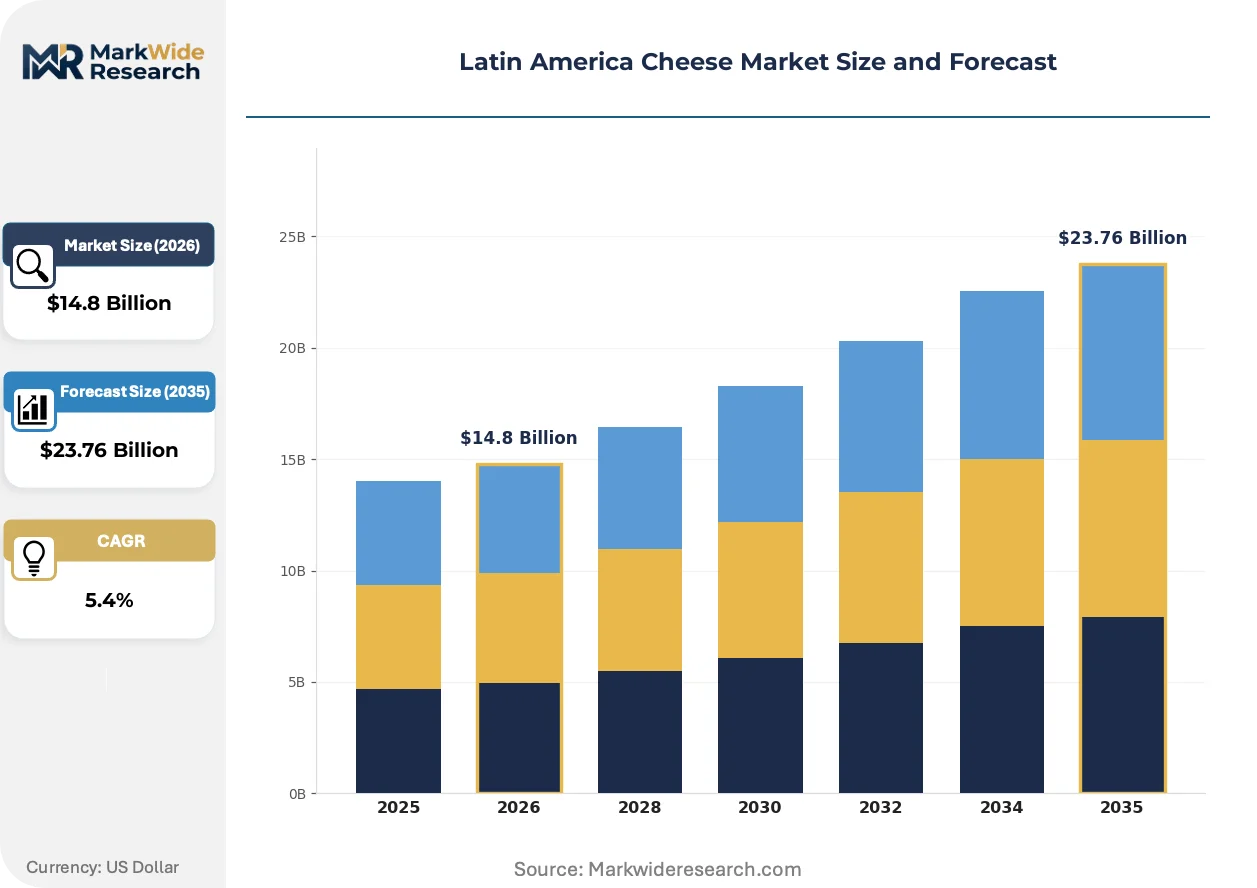
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Cream Cheese, Feta Application: Food Service, Retail, Dairy Products, Snacks End User: Restaurants, Households, Food Manufacturers, Cafes Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores |
| Companies Covered | Arla Foods, FrieslandCampina, Groupe Lactalis, Conaprole, Mastellone Hermanos, Saputo Inc, The Kraft Heinz Company, SanCor, Fonterra Group Cooperative Limited, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cheese Market Strategic Shifts & Innovations
Automation and regulatory digitization are compressing traditional cheese production and compliance workflows, while shifting procurement patterns redistribute power between manufacturers and retail consolidators across Latin American dairy markets.
Membrane filtration technology for whey protein concentration and lactose recovery is rendering obsolete conventional evaporation and spray-drying configurations in large-scale Brazilian cheese plants. São Paulo-based industrial dairy operators are retrofitting existing facilities with ultrafiltration and nanofiltration skids to capture higher-value whey fractions. This capital deployment is rendering obsolete older dryer-dominated process lines that previously treated whey as low-margin byproduct rather than standalone revenue stream.
Chile's front-of-pack warning label law and Mexico's NOM-051 nutritional labeling standards are forcing reformulation of cream cheese and processed cheese spreads. Manufacturers must reduce sodium and saturated fat thresholds to avoid mandatory octagon warnings that depress retail velocity. Premium-positioned brands in Santiago and Mexico City are responding with clean-label ingredient declarations and reduced-fat formulations that maintain functional performance in bakery applications.
Centralized procurement by Brazilian and Mexican supermarket chains is consolidating supplier relationships and compressing switching flexibility for cheese processors. Retail buyers in São Paulo and Mexico City are demanding exclusive private-label production capacity, volume guarantees, and promotional participation as table stakes for shelf placement. This concentration is most visible in cream cheese and mozzarella categories, where three retail banners control majority volume and dictate margin terms to mid-tier dairy processors.
Latin America Cheese Market Segmentation
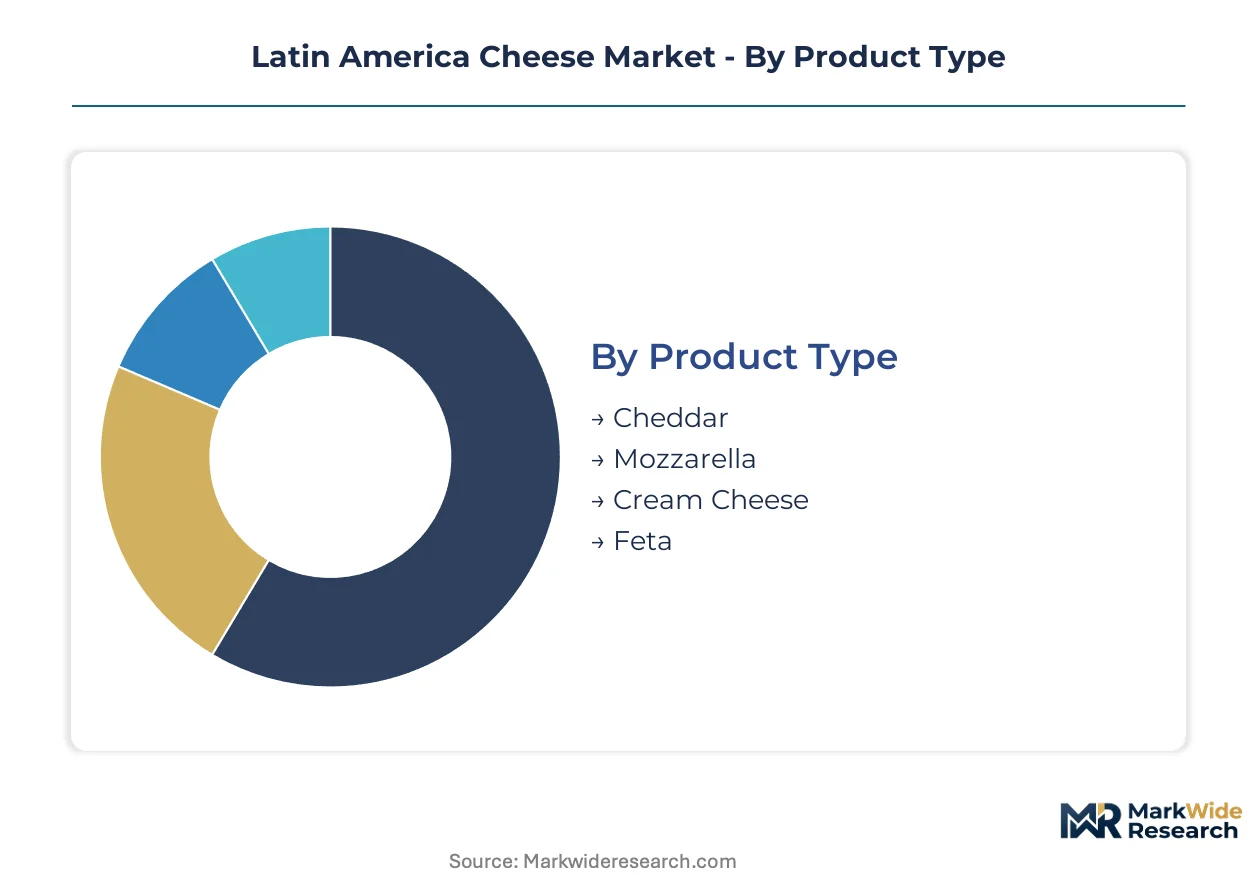
Cheese segmentation across Latin America reflects divergent moisture specifications, aging protocols, and channel economics that determine margin capture. Product type and application splits reveal where cold-chain investment and formulation flexibility concentrate competitive advantage.
Product Type:
Use-case spectrum spans industrial food service throughput to premium table consumption, with moisture content and melt functionality dictating channel placement.
- Cheddar:Aged curd with controlled moisture loss and sharp flavor development through extended cellar protocols. Demand clusters in Chilean and Colombian retail channels where private-label penetration lags Brazilian levels, creating import substitution openings for aged varieties.
- Mozzarella:Fresh pasta filata with high moisture and stretch elasticity optimized for pizza applications. São Paulo's quick-service restaurant chains and Argentine pizzerias pull volume through direct supply contracts, bypassing traditional wholesale layers.
- Cream Cheese:Soft unripened cheese with stabilizer systems for spreadability in bakery and dessert applications.
- Feta:Brined curd with crumbly texture and tangy profile serving Mediterranean restaurant segments and specialty retail.
The dominant share belongs to Mozzarella, while Cream Cheese is closing the gap fastest.
Application:
Margin structure varies sharply by customer procurement scale, with institutional buyers extracting volume discounts unavailable to fragmented retail purchasers.
- Food Service:High-volume procurement by restaurant chains and institutional caterers demanding consistent melt performance and case-ready portioning. Brazilian pizza operators and Argentine casual dining chains specify moisture content tolerances that disqualify smaller processors lacking laboratory quality control.
- Retail:Packaged cheese for supermarket and specialty store channels where front-of-pack labeling laws in Chile and Mexico force sodium and fat reformulation. São Paulo's retail banners consolidate supplier relationships through exclusive private-label capacity demands.
- Dairy Products:Ingredient cheese for processed food manufacturing including frozen meals and prepared sauces.
- Snacks:Portioned cheese for convenience consumption and on-the-go formats.
Food Service commands the largest volume position, though Retail is expanding most quickly through clean-label premium positioning.
End User:
Procurement sophistication separates price-sensitive household purchasers from technical buyers specifying functional performance parameters.
- Restaurants:Full-service and limited-service operators across Brazil's southeastern corridor and Mexico's central dairy belt. Kitchen managers prioritize consistent shred melt and oil-off control for pizza and gratin applications, driving direct sourcing from processors with dedicated food service sales teams.
- Households:Consumer purchasers through retail channels where price elasticity varies by income bracket and urban density.
- Food Manufacturers:Industrial buyers integrating cheese into ready-to-eat and frozen meal portfolios, expanding whey and curd procurement through contracted dairy supply.
- Cafes:Coffee shop and bakery operators specifying cream cheese for pastry applications with clean-label ingredient requirements.
Restaurants absorb the dominant procurement volume, while Food Manufacturers are scaling fastest through processed portfolio expansion.
Distribution Channel:
Cold-chain reliability and last-mile temperature integrity determine channel viability for perishable cheese categories across Latin America's logistics infrastructure.
- Supermarkets:Controlled-environment retail with refrigerated display cases and consolidated procurement by banner groups. São Paulo and Mexico City chains demand slotting fees and promotional participation that exclude mid-tier processors lacking balance sheet depth.
- Online Retail:Direct-to-consumer platforms with temperature-controlled fulfillment emerging in urban consumption clusters where delivery density supports insulated packaging economics.
- Wholesale:Traditional distributor networks serving independent restaurants and smaller retail accounts through cash-and-carry and route delivery.
- Convenience Stores:Limited assortment retail with extended hours targeting impulse and immediate consumption occasions.
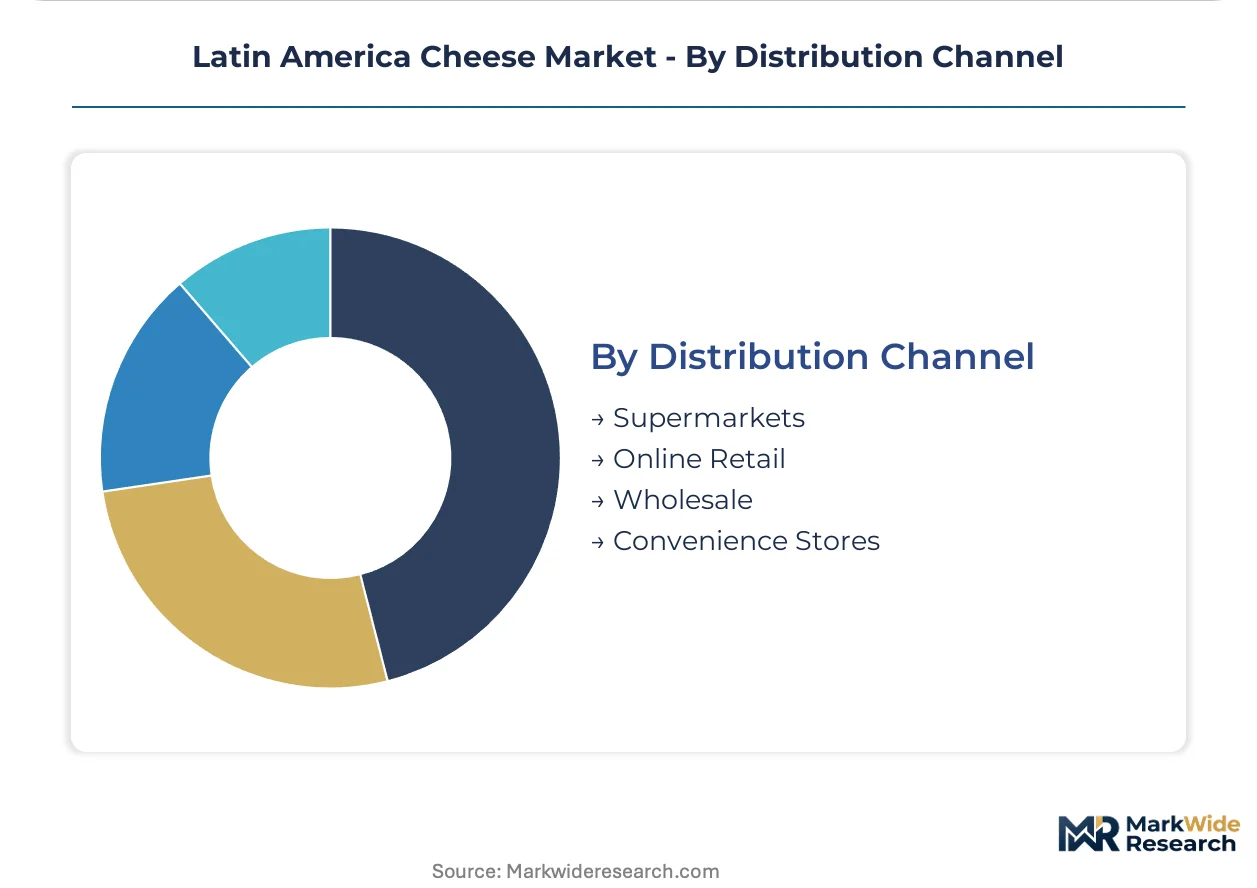
Supermarkets retain the dominant share, while Online Retail is climbing the fastest through urban delivery density improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA in Brazil anchors the regulatory framework for Latin American cheese trade, with São Paulo's cold-chain infrastructure setting the operational benchmark for cross-border dairy flows.
Brazil
Food manufacturers in São Paulo state are expanding mozzarella and cream cheese procurement for frozen pizza and ready-to-eat portfolios. ANVISA's pathogen testing protocols and traceability mandates force reformulation investments for processors seeking multi-state distribution. The southeastern dairy corridor between São Paulo and Minas Gerais concentrates pasteurization capacity and whey processing investments.
Mexico
Quick-service restaurant chains across Mexico City's central dairy belt specify moisture content tolerances that disqualify smaller processors lacking laboratory quality control. COFEPRIS nutritional labeling standards under NOM-051 force sodium reduction in cream cheese spreads to avoid mandatory warning labels. Jalisco and Nuevo León host the dominant concentration of industrial dairy capacity serving food service procurement.
Argentina
Pizzerias in Buenos Aires and Córdoba pull mozzarella volume through direct supply contracts, bypassing traditional wholesale layers. Senasa enforces divergent dairy pathogen limits that fragment cross-border product registration with Brazilian and Uruguayan counterparts. The Pampas dairy belt supplies raw milk to processors specializing in pasta filata production for food service chains.
Uruguay
Conaprole anchors Uruguayan milk supply into Mercosur export flows, leveraging harmonized sanitary protocols to reduce technical barriers for Brazilian market access. Mercosur's aligned traceability standards enable cross-border cheese movements without duplicate testing regimes. Montevideo's port infrastructure supports refrigerated container shipments to São Paulo and Buenos Aires distribution hubs.
Chile
Retail channels in Santiago concentrate cheddar and aged cheese demand where private-label penetration lags Brazilian levels. Front-of-pack warning label laws force sodium and saturated fat reformulation in cream cheese and processed spreads to maintain shelf velocity. The Central Valley dairy region supplies milk to processors adapting formulations for clean-label positioning in premium supermarket banners.
Latin America Cheese Market Key Industry Players
Capability concentration sits with multinational processors possessing brand portfolios and cold-chain scale; scale advantage sits with regional cooperatives controlling raw milk supply. The market structures around three tiers: global dairy conglomerates with multi-brand retail presence, national cooperatives anchored in Mercosur trade flows, and mid-tier specialists serving food service direct contracts. Dominant competitive moves include exclusive private-label capacity commitments to supermarket banners and backward integration into whey protein fractionation.
Among global-scale processors, Groupe Lactalis occupies a position exemplifying premium retail channel dominance through multi-brand portfolio deployment across São Paulo and Rio de Janeiro. Conaprole represents the cooperative archetype, anchoring Uruguayan supply into cross-border Mercosur flows. Mastellone Hermanos exemplifies food service specialization, with production configured for Argentine pizzeria and quick-service procurement specifications.
| Leading Market Players |
|---|
| Arla Foods |
| FrieslandCampina |
| Groupe Lactalis |
| Conaprole |
| Mastellone Hermanos |
| Saputo Inc |
| The Kraft Heinz Company |
| SanCor |
| Fonterra Group Cooperative Limited |
| Others |
Cost & Logistics Intelligence
Uruguayan milk cooperatives anchoring Mercosur export flows concentrate upstream supply leverage, translating directly into margin capture at São Paulo's refrigerated distribution hubs where cold-chain reliability commands premium pricing. Argentine and Brazilian feed cost volatility transmits through processor procurement contracts, reshaping where value pools accumulate across mozzarella and cream cheese tiers.
Pricing Analysis
São Paulo-to-Buenos Aires price spreads for mozzarella widen during Argentine harvest compression periods, compressing processor margins in the Pampas dairy belt. Three-tier pricing structure across premium private-label, standard food service, and economy wholesale levels separates Groupe Lactalis banner exclusives from mid-tier slotting-fee competitors. Pricing pressure stems from Brazilian supermarket chains demanding volume guarantees and promotional participation as shelf-access conditions. Food manufacturers exhibit lowest price sensitivity due to long-term whey supply contracts, while independent pizzerias in Córdoba and Rosario face highest elasticity.
Supply Chain Analysis
Soybean meal and corn feedstock dependencies in Argentina and Brazil hinge on international commodity price swings that transmit directly to milk procurement costs. Raw material flows center on the Pampas dairy belt, São Paulo's southeastern corridor, and Jalisco's central dairy region. Distribution runs through temperature-controlled consolidation hubs bridging São Paulo's logistics clusters and secondary Brazilian cities, extending lead times where cold-chain technician scarcity bites. Single-source vulnerability concentrates in whey processing capacity controlled by integrated multinationals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from feed cost cyclicality as Argentine and Brazilian grain prices stabilize from prior volatility spikes, restoring margin visibility for processors with contracted dairy supply.
For Market Incumbents:Pre-empt slotting fee escalation by locking exclusive private-label capacity with São Paulo retail banners before mid-tier competitors secure balance sheet depth for promotional participation. Anchor backward integration into whey protein fractionation to capture higher-value byproduct revenue streams that offset mozzarella margin compression from direct food service contracting.
For New Entrants and Emerging Players:Establish a beachhead in Colombian cheddar retail channels where private-label penetration trails Brazilian benchmarks and premium import substitution whitespace persists. Target clean-label cream cheese reformulation for Chilean supermarket banners navigating front-of-pack warning label compliance, leveraging flexible production lines as a technical differentiation wedge against legacy processors.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with PE-backed Brazilian dairy processors that expanded pasteurization capacity during prior growth phases and now face working capital strain from supermarket payment term extension. Five-to-ten year viability favors cooperatives with locked-in Mercosur export access and Uruguayan milk supply integration. Monitor ANVISA-COFEPRIS regulatory harmonization progress as an inflection signal for cross-border consolidation feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Processing | Captures higher-value protein fractions from São Paulo mozzarella production waste streams. |
| Clean-Label Reformulation Investment | Enables Chilean and Mexican cream cheese placement avoiding mandatory octagon warning labels. |
| Direct Food Service Distribution | Bypasses wholesale margin layers for Argentine pizzeria chains specifying moisture tolerances. |
| Exclusive Private-Label Capacity Commitment | Secures shelf access with São Paulo banners demanding volume guarantees and promotional participation. |
| Mercosur Sanitary Protocol Alignment | Reduces duplicate testing burdens for Uruguayan exporters accessing Brazilian distribution hubs. |
Research Approach
Cross-validation between dairy processor procurement directors and supermarket category buyers anchors the qualitative findings on margin structure and slotting fee dynamics. Primary interviews with ANVISA regulatory affairs specialists, cold-chain logistics operators, and food service procurement managers combined with secondary validation from ANVISA pathogen testing protocols, COFEPRIS NOM-051 filings, and Mercosur sanitary harmonization documentation. Bottom-up volume modeling from plant-level pasteurization capacity and top-down demand triangulation from retail scanner data establish convergent estimates.
Calibration against historical whey price volatility and feed cost transmission patterns shapes the projection framework across the analysis window. Segmentation dimensions span product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derive from trend extrapolation adjusted for capacity expansion timelines and supermarket consolidation trajectories. Forecast inputs incorporate cold-chain infrastructure investment pipelines and front-of-pack labeling law implementation schedules.
Sensitivities concentrate around Argentine peso volatility affecting feed import costs and Brazilian interest rate shifts impacting processor working capital requirements. Forecasts reflect assumptions on Mercosur sanitary protocol enforcement consistency and supermarket buyer concentration trajectories. Cross-checking against customs trade data on cross-border cheese movements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
A2 Milk Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Colombia Dairy Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Gruyere Market
Dairy Products
A2 Protein Milk Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Butter and Margarine Market
Dairy Products
Low Fat Butter Market