
 United Kingdom Dairy Market | 2026-2036
United Kingdom Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Dairy Market Insights
Supermarket private-label supply chains is rewriting procurement relationships across the United Kingdom dairy sector. Arla Foods UK leverages its cooperative ownership model to sustain direct farmer relationships and secure raw milk volumes. Müller UK & Ireland anchors yogurt and fresh dairy production through large-scale manufacturing sites in Shropshire and Scotland. Dale Farm Cooperative Ltd specializes in cheddar and specialty cheese, competing on regional provenance credentials.
United Kingdom dairy encompasses fluid milk, fermented products, and fat-rich derivatives produced through pasteurization, homogenization, and enzymatic coagulation, with milk composition standardized to minimum fat and protein thresholds for commercial sale. The primary purpose spans direct human nutrition, food manufacturing ingredient supply, and foodservice portion control. Milk retains volume leadership through daily household replenishment cycles, while cheese commands margin concentration due to aging infrastructure requirements and export price premiums. Yogurt competes on probiotic health positioning and chilled distribution efficiency, with foodservice channels recovering as out-of-home breakfast occasions normalize.
DEFRA enforces farm assurance standards through the Red Tractor scheme, while the Food Standards Agency governs compositional specifications and labeling requirements for dairy products sold in England, Wales, and Scotland. The Environment Agency regulates effluent discharge from processing facilities, raising capital costs for smaller creameries. Stakeholders must monitor how post-Brexit border inspection protocols reshape Irish Sea trade flows for cross-border milk pooling arrangements.
Market Dynamics
DEFRA's Environmental Land Management scheme is redirecting farm subsidies toward sustainable pasture practices, compressing operating margins for conventional intensive producers while rewarding regenerative grazing systems across England's southwestern dairy clusters.
Growth Catalysts
- Specialty cheese demand from artisan bakeries:Premium ingredient sourcing from craft bakeries in London and Bristol is pulling aged cheddar and cultured butter volumes through dedicated procurement channels.
- Red Tractor farm assurance standards:DEFRA's certification scheme creates tiered quality signaling that unlocks export access to EU retail buyers still requiring third-country equivalence documentation.
- Pasture-based production systems:Southwestern counties concentrate grass-fed milk pooling that commands price premiums in Middle Eastern and East Asian export markets seeking provenance credentials.
Market Restraints
- Feed input cost volatility:Imported soy and maize prices fluctuate with Black Sea grain flows, squeezing margin predictability for intensive indoor-housed herds dependent on purchased concentrates.
- Cross-border milk pooling concentration:Irish Sea trade arrangements face post-Brexit border inspection friction, disrupting just-in-time raw milk transfers between Northern Ireland and Republic of Ireland processing plants.
- Effluent discharge capital requirements:The Environment Agency's tightening wastewater standards impose six-figure upgrade costs on small-scale creameries lacking anaerobic digestion infrastructure.
Strategic Opportunities
- Carbon-neutral dairy certification:DEFRA's Sustainable Farming Incentive offers payment rates for methane-reduction practices that can be monetized through voluntary carbon credit schemes.
- Precision fermentation convergence:Cellular agriculture startups are partnering with traditional creameries to license enzymatic processes for lactose-free and animal-free fat replication.
- Direct-to-restaurant distribution:Chef-owned supply cooperatives in Manchester and Edinburgh are bypassing wholesale distributors to secure farm-specific milk and seasonal cheese allocations.
Industry Challenges
- Veterinary pharmaceutical residue compliance:The Food Standards Agency's expanded antibiotic testing protocols extend batch-hold times at processing facilities, compressing shelf-life windows for fresh dairy.
- Aging dairy engineering talent:Retirements among plant maintenance specialists familiar with legacy separator and homogenizer systems outpace apprenticeship pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Dairy Market |
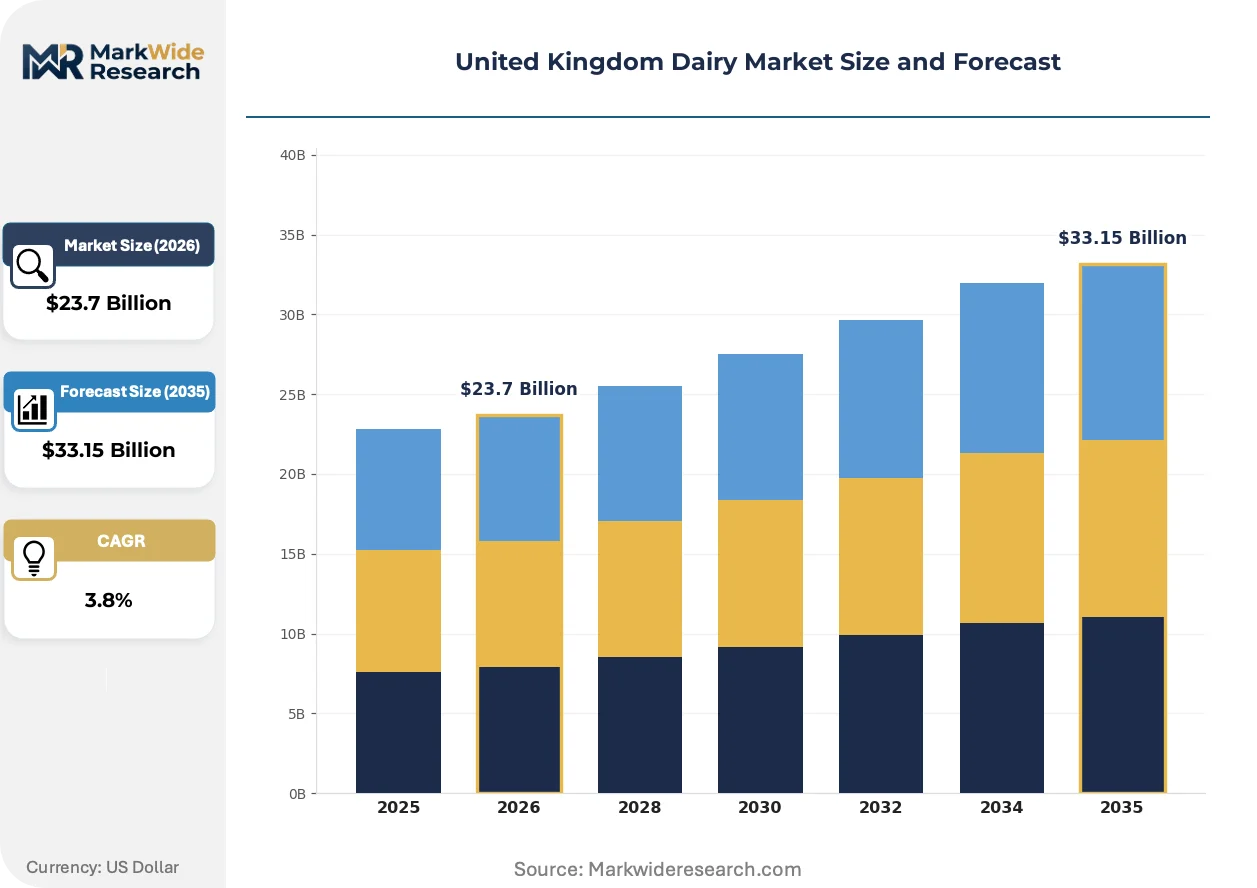
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $33.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Consumer Segment: Households, Restaurants, Cafés, Bakeries Packaging Type: Cartons, Bottles, Tubs, Pouches |
| Companies Covered | Arla Foods UK, Müller UK & Ireland, Dale Farm Cooperative Ltd, Saputo Dairy UK, Meadow Foods, First Milk, Lakeland Dairies, Glanbia Cheese UK, Yeo Valley, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Dairy Market Trends and Innovations
Automation and biosensor technologies are reshaping herd management and processing efficiency across United Kingdom dairy operations, creating divergence between technology-adopting cooperatives and labor-dependent smaller producers.
Robotic milking systems equipped with infrared somatic cell counters are hybridizing traditional parlour operations with continuous data capture. Large-scale herds in Shropshire and Ayrshire are adopting these installations at replacement-cycle pace. The technology is compressing veterinary intervention response times from days to hours while enabling selective dry-cow protocols that reduce antibiotic use.
DEFRA's Slurry Infrastructure Grant is mandating covered lagoon and separator investments ahead of 2027 nitrate-vulnerable zone designations. Dairy processors face capital allocation trade-offs between compliance spending and product-line expansion. Smaller creameries in Devon and Somerset are consolidating through shared anaerobic digestion cooperatives to spread fixed-cost burdens.
Foodservice buyers are consolidating procurement through nominated-supplier agreements that displace spot-market spot purchasing. Contracted volume commitments now dominate hotel and restaurant chain sourcing in London and Birmingham. This concentration is visible in the decline of wholesale dairy markets and the rise of processor-owned logistics fleets serving direct-account customers.
United Kingdom Dairy Market Segmentation
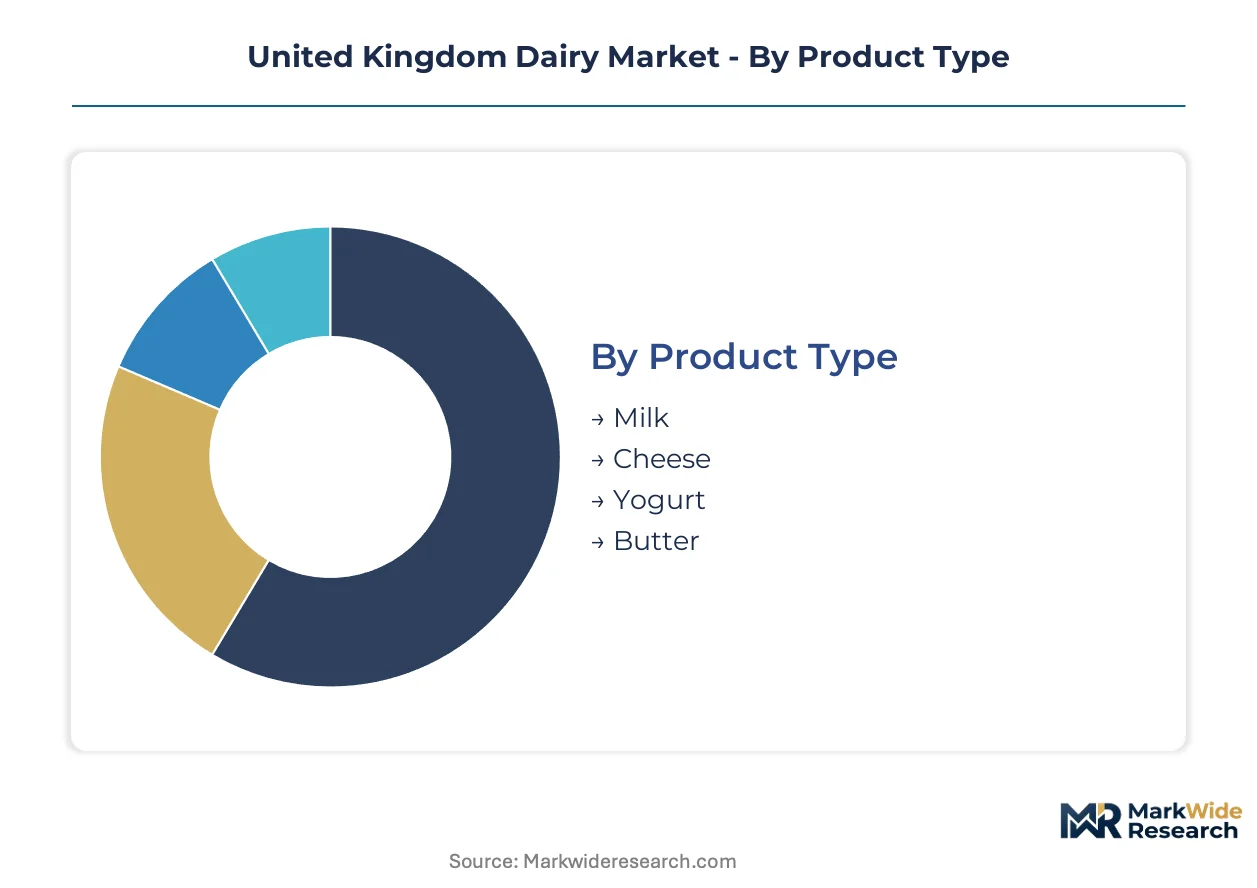
United Kingdom dairy procurement patterns fragment sharply across channel and end-use boundaries, with each segment demanding distinct service intensity, shelf-life management, and traceability protocols. Understanding these divisions reveals where margin pools concentrate and where volume scale dominates.
Product Type:
After-sales service intensity varies dramatically across dairy categories, with fresh milk requiring daily replenishment logistics while aged cheese demands climate-controlled aging infrastructure and provenance documentation.
- Milk:Standardized to minimum fat and protein thresholds through pasteurization and homogenization. Daily household replenishment cycles in England's southwestern counties sustain volume leadership, though supermarket private-label concentration compresses processor margins.
- Cheese:Produced through enzymatic coagulation with aging infrastructure requirements spanning months to years. Aged cheddar from Devon and Somerset commands export price premiums in Middle Eastern markets seeking Red Tractor farm assurance credentials.
- Yogurt:Fermented products competing on probiotic health positioning and chilled distribution efficiency.
- Butter:Fat-rich derivatives pulled by artisan bakery demand in London and Bristol through dedicated procurement channels.
Milk holds the largest share; momentum sits with cheese as specialty aging capacity expands.
Distribution Channel:
Cost tier stratification separates high-volume supermarket contracts from premium foodservice nominations, with capital requirements and payment terms diverging sharply across these channels.
- Supermarkets:Private-label supply chains rewriting procurement relationships through direct farmer relationships and nominated-supplier agreements. Arla Foods UK leverages cooperative ownership to secure raw milk volumes against this consolidation pressure.
- Foodservice:Chef-owned supply cooperatives in Manchester and Edinburgh bypass wholesale distributors for farm-specific allocations. Contracted volume commitments now dominate hotel and restaurant chain sourcing.
- Convenience Stores:Smaller format retail capturing impulse replenishment occasions.
- Online Retail:Direct-to-consumer platforms expanding chilled logistics coverage.
Supermarkets dominate volume; foodservice claims the steepest expansion trajectory as out-of-home breakfast occasions normalize.
Consumer Segment:
Application-specific requirements drive formulation differences, with bakeries demanding cultured butter with specific melting profiles while households prioritize extended shelf-life fluid milk.
- Households:Daily nutrition consumption with replenishment cycles driving milk volume concentration.
- Restaurants:Portion control and consistent quality specifications for menu execution.
- Cafés:Milk frothing performance requirements for espresso-based beverages.
- Bakeries:Specialty cheese and cultured butter demand from craft operations in London and Bristol pulling premium volumes through dedicated channels.
Households anchor volume demand; bakeries generate the fastest margin expansion through ingredient premiumization.
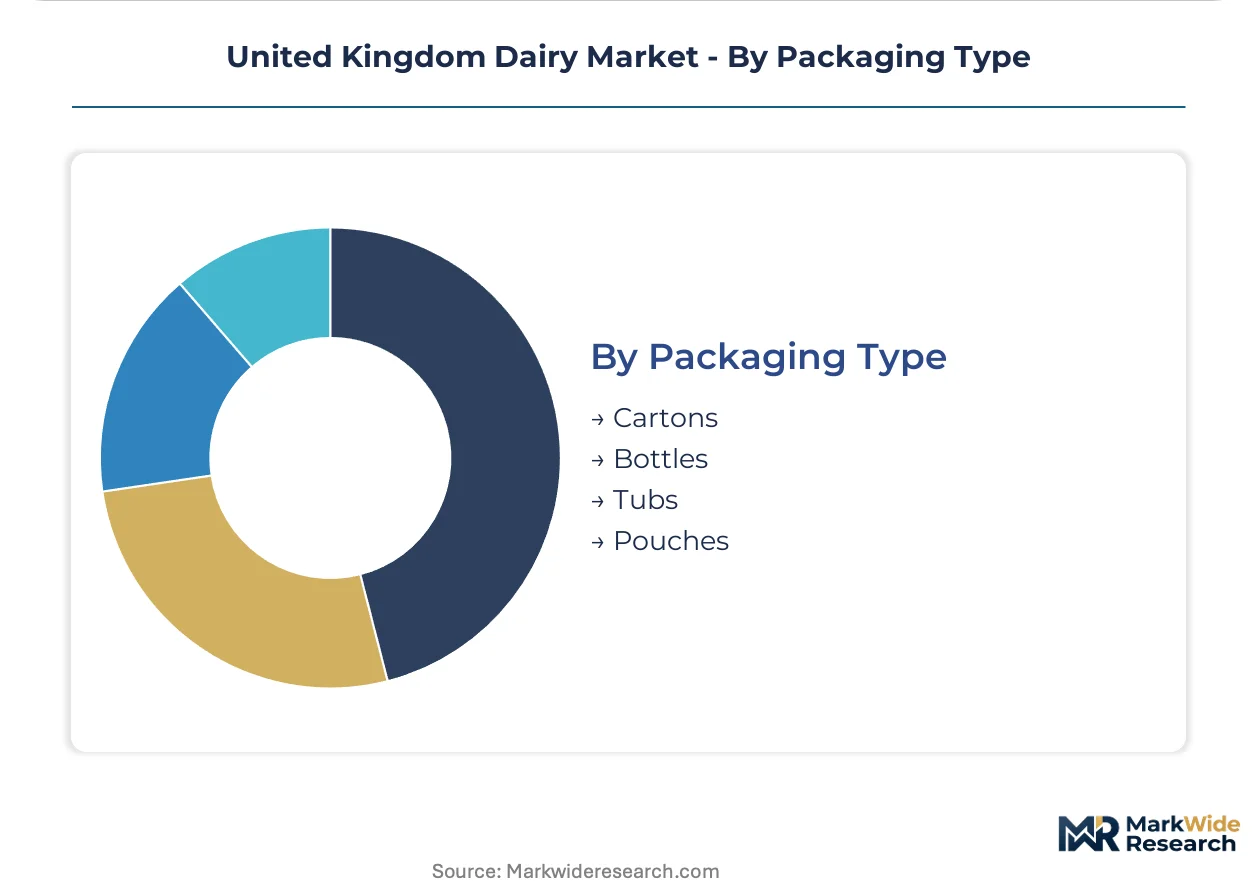
Packaging Type:
Supply concentration in carton manufacturing versus bottle molding creates divergent procurement strategies for processors balancing sustainability signaling against shelf-life extension needs.
- Cartons:Aseptic liquid packaging dominating fluid milk with extended unopened shelf-life.
- Bottles:Polymer and returnable glass formats for premium positioning and local delivery routes.
- Tubs:Injection-molded containers for yogurt and spreadable cheese with reseal functionality.
- Pouches:Flexible formats gaining traction in foodservice portion control and online retail fulfillment.
Cartons retain volume leadership; pouches are climbing the fastest as e-commerce chilled logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southwestern England commands export price premiums that northern processors cannot match, creating a persistent margin gap between pasture-based clusters and intensive indoor systems. This pricing-power asymmetry shapes investment flows across the United Kingdom dairy landscape.
Southwest England
Devon and Somerset anchor grass-fed milk pooling that supplies aged cheddar to Middle Eastern buyers seeking Red Tractor farm assurance credentials. DEFRA's Environmental Land Management scheme rewards regenerative grazing here with subsidy payments unavailable to intensive producers. The Cheddar Gorge processing corridor concentrates aging infrastructure that commands twelve-month maturation premiums.
North England
Yorkshire and Lancashire dairies face compressed margins from supermarket private-label concentration despite substantial fluid milk volumes. The Environment Agency's tightening nitrate-vulnerable zone designations force slurry infrastructure investments ahead of 2027 deadlines. Manchester chef-owned supply cooperatives are bypassing wholesale distributors for farm-specific allocations.
Scotland
Ayrshire robotic milking adoption leads UK installation density, with infrared somatic cell counters compressing veterinary response times. Scottish Environment Protection Agency regulations on anaerobic digestion infrastructure outpace England's timeline. Large-scale yogurt manufacturing sites in central Scotland serve chilled distribution networks recovering as foodservice normalizes.
Wales
Pembrokeshire and Ceredigion concentrate organic dairy conversions driven by Welsh Government Sustainable Farming Scheme payment rates. The Food Standards Wales antibiotic testing protocols extend batch-hold times at smaller creameries. Shared anaerobic digestion cooperatives spread fixed-cost burdens across consolidated processing operations.
Northern Ireland
Cross-border milk pooling with Republic of Ireland processors faces post-Brexit border inspection friction disrupting just-in-time transfers. Dale Farm Cooperative's cheddar operations anchor regional specialty cheese capacity. DAERA farm support schemes diverge from DEFRA's Environmental Land Management structure, creating subsidy asymmetries.
United Kingdom Dairy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in milk pooling and aging infrastructure. Cooperative ownership structures dominate raw milk procurement, locking in farmer loyalty against private-label consolidation pressure. Three archetypes define competitive positioning: farmer-owned cooperatives with backward integration into milk supply, processor-led branded portfolios with foodservice nomination strength, and regional specialty players competing on provenance credentials. M&A activity concentrates among mid-tier creameries seeking anaerobic digestion scale, while direct-to-restaurant distribution partnerships bypass traditional wholesale channels.
Within the cooperative tier, Arla Foods UK and First Milk exemplify farmer-owned structures that secure raw milk volumes through direct producer relationships. Müller UK & Ireland occupies a position among scale-driven branded processors with large-scale manufacturing footprints. Dale Farm Cooperative Ltd represents the regional specialty archetype, competing on cheddar provenance credentials from Northern Ireland.
| Leading Market Players |
|---|
| Arla Foods UK |
| Müller UK & Ireland |
| Dale Farm Cooperative Ltd |
| Saputo Dairy UK |
| Meadow Foods |
| First Milk |
| Lakeland Dairies |
| Glanbia Cheese UK |
| Yeo Valley |
| Others |
Pricing and Supply Chain Analysis
Post-Brexit border inspection friction at Irish Sea ports determines both the premium spread for pasture-verified Southwestern milk and the geographic restructuring of cross-border pooling arrangements. DEFRA's Environmental Land Management subsidy differentials simultaneously compress intensive-producer margins and reward regenerative grazing systems, locking in a two-tier cost structure that propagates through processor negotiations.
Pricing Analysis
Customization-premium spreads separate Red Tractor-assured farm-specific allocations from supermarket private-label base volumes. Contract-based long-term offtake dominates, with price differentiation driven by certification grade and geographic delivery cost. Pricing pressure stems from feed input cost volatility squeezing intensive indoor-housed herds. Supermarket procurement teams exhibit highest price sensitivity; Middle Eastern export buyers seeking provenance credentials show lowest.
Supply Chain Analysis
Supplier-financing facilities through cooperative structures extend payment terms for seasonal milk volume fluctuations. Raw material flows draw from Ireland, the Netherlands, and domestic Southwestern counties for feed concentrates and breeding stock. Black Sea grain flow disruptions create commodity price volatility risk. Distribution runs through processor-owned logistics fleets serving direct-account customers, displacing wholesale market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as chef-owned supply cooperatives bypass wholesale distributors, creating niche procurement channels for farm-specific allocations that incumbent scale players cannot efficiently serve.
For Market Incumbents: Pre-empt precision fermentation convergence by partnering with cellular agriculture startups to license enzymatic processes for lactose-free derivatives. Secure backward integration into anaerobic digestion infrastructure before Environment Agency tightening forces six-figure upgrade costs on smaller competitors. Lock in direct-to-restaurant distribution partnerships in Manchester and Edinburgh to defend against cooperative bypass.
For New Entrants and Emerging Players: Establish a beachhead in carbon-neutral dairy certification by aggregating DEFRA Sustainable Farming Incentive payment streams into voluntary carbon credit monetization. Target Welsh organic conversion clusters where Welsh Government payment rates exceed DEFRA equivalents. Deploy precision fermentation licensing as the go-to-market angle to access established creamery processing capacity without capital-heavy infrastructure buildout.
For Investors and Strategic Acquirers: DEFRA's 2027 nitrate-vulnerable zone deadline reshapes the acquisition landscape toward mid-tier creameries with shared anaerobic digestion cooperative membership. Long-term viability favors operations with pasture-based production systems and export channel access to Middle Eastern provenance-seeking buyers. Monitor Irish Sea trade friction resolution as the signal to watch for cross-border pooling valuation normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anaerobic Digestion | Spreads Environment Agency compliance costs across consolidated Southwestern processing clusters. |
| Red Tractor Certification Investment | Unlocks EU retail buyer access requiring third-country equivalence documentation post-Brexit. |
| Direct-to-Restaurant Distribution Launch | Bypasses wholesale market decline through chef-owned cooperative partnerships in Manchester and Edinburgh. |
| Precision Fermentation Licensing Agreement | Partners cellular agriculture startups with traditional creameries for lactose-free fat replication. |
| Carbon Credit Program Development | Monetizes DEFRA methane-reduction payments through voluntary offset scheme participation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dairy cooperative board members, DEFRA policy officers, Food Standards Agency compliance leads, and chef-owned supply cooperative procurement managers; and secondary validation through customs records, Red Tractor assurance scheme filings, Environment Agency discharge permits, and SEC disclosures from listed processors. Bottom-up volume aggregation triangulated against top-down value estimates derived from export trade flows.
Forecast inputs considered pasture-based production capacity expansion, supermarket private-label concentration trajectories, and foodservice channel normalization patterns across the projection horizon. Segmentation modeling captured product type, distribution channel, consumer segment, and packaging format dimensions with regional regulatory cluster overlays. CAGRs were derived from volume growth trajectories adjusted for pricing tier migration effects and input cost pass-through assumptions.
Stress conditions across Black Sea grain flow disruption severity, Irish Sea inspection friction duration, and Environment Agency enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy scheme continuity and trade arrangement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Spreads Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Butter Powder Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
United States Dairy Market
Dairy Products
Cheese Packaging Market
Dairy Products
Table Butter Market
Dairy Products
India Dairy Market
Dairy Products
A2 Milk Market
Dairy Products
Organic Milk Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Dairy Protein Market
Dairy Products
North America Cheese Market
Dairy Products
Global Yogurt Market
Dairy Products
Evaporated Filled Milk Market