
 Serrata Extract Market | 2026-2036
Serrata Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Serrata Extract Market Analysis
Supercritical CO2 extraction technology is reshaping how Boswellia serrata resin is refined into pharmaceutical-grade extracts, replacing solvent-based methods with tunable-pressure systems that preserve acid ratios. Arjuna Natural leverages its Kerala-based extraction infrastructure to supply standardized AKBA fractions to European pharmaceutical customers. Sabinsa Corporation anchors North American demand through its vertically integrated supply chain from Indian raw material to New Jersey formulation facilities. Indena S.p.A. specializes in micronized delivery systems that improve bioavailability for nutraceutical applications.
Serrata extract denotes a botanical concentrate derived from Boswellia serrata gum resin, typically standardized to 30-70% boswellic acids including the marker compound 3-acetyl-11-keto-β-boswellic acid (AKBA) through chromatographic purification. The extract functions primarily as an anti-inflammatory and anti-arthritic agent in oral dosage forms, with emerging applications in topical cosmeceuticals targeting skin aging mechanisms. Capsule and tablet formats dominate value capture due to higher dosing precision and pharmacy channel acceptance, while liquid extract forms occupy faster-growing positions in functional beverage formulations where rapid dispersion matters. Pharmaceutical applications sustain the steepest margin pools owing to documentation requirements and clinical validation thresholds that limit supplier entry.
The US FDA maintains botanical drug development guidance that demands standardized extract characterization for investigational new drug submissions, while India's CDSCO enforces Schedule T of the Drugs and Cosmetics Rules for Good Manufacturing Practices in Ayurvedic medicine production. The European Medicines Agency's Committee on Herbal Medicinal Products issues monographs for Boswellia serrata that define minimum quality benchmarks for traditional use registrations in EU member states. Stakeholders must monitor evolving pharmacopeial standards for heavy metal and pesticide residue limits, as these specifications increasingly determine which processors retain market access versus face exclusion from regulated channels.
Market Dynamics
Supercritical CO2 extraction is virtualizing solvent-based refining capacity across Boswellia serrata processing clusters, compressing capital requirements for pharmaceutical-grade standardization while fragmenting legacy processor margins in Karnataka and Kerala.
Growth Catalysts
- EU Novel Food Pathway:The European Union's streamlined botanical extract approval framework is accelerating functional food applications for standardized boswellic acid fractions, opening shelf-space expansion in German and French retail channels.
- Osteoarthritis Therapeutics:Pharmaceutical formulators in Germany are expanding procurement of AKBA-standardized extracts for anti-inflammatory drug pipelines targeting joint health indications.
- Karnataka-Kerala Cluster Density:Resin collection and primary processing concentration across India's southern states creates upstream supply security for refiners serving three continents.
Market Restraints
- Wild Harvest Dependency:Boswellia serrata gum resin supply concentrates on wild tree populations in Rajasthan and Gujarat, exposing processors to climate-induced yield volatility and collection labor shortages.
- Chromatographic Purification Costs:AKBA enrichment to 30-70% standardized fractions requires high-performance liquid chromatography infrastructure that locks out smaller processors from pharmaceutical-grade supply contracts.
- Synthetic NSAID Substitution:Ibuprofen and diclofenac formulations maintain pharmacy channel dominance for acute inflammation management, constraining serrata extract penetration in reimbursed prescription markets.
Strategic Opportunities
- Topical Cosmeceuticals:Skin aging applications for boswellic acid fractions remain underdeveloped relative to oral dosage forms, creating whitespace for micronized delivery system innovation in Korean and Japanese beauty markets.
- US FDA Botanical Drug Guidance:The agency's pathway for standardized extract characterization in investigational new drug submissions offers regulatory tailwind for clinical validation investments targeting osteoarthritis endpoints.
- Functional Beverage Dispersion:Liquid extract formats with rapid solubility profiles are capturing shelf space in European functional beverage channels where capsule compliance barriers exclude traditional dosage forms.
Industry Challenges
- Pharmacopeial Compliance Timeline:Heavy metal and pesticide residue limit revisions by USP and EP certification bodies are extending batch release cycles for exporters targeting regulated pharmaceutical channels.
- Supercritical CO2 Technical Talent:Tunable-pressure system operation and maintenance expertise concentrates with equipment vendors, forcing processors to absorb premium service contracts or risk extraction parameter drift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serrata Extract Market |
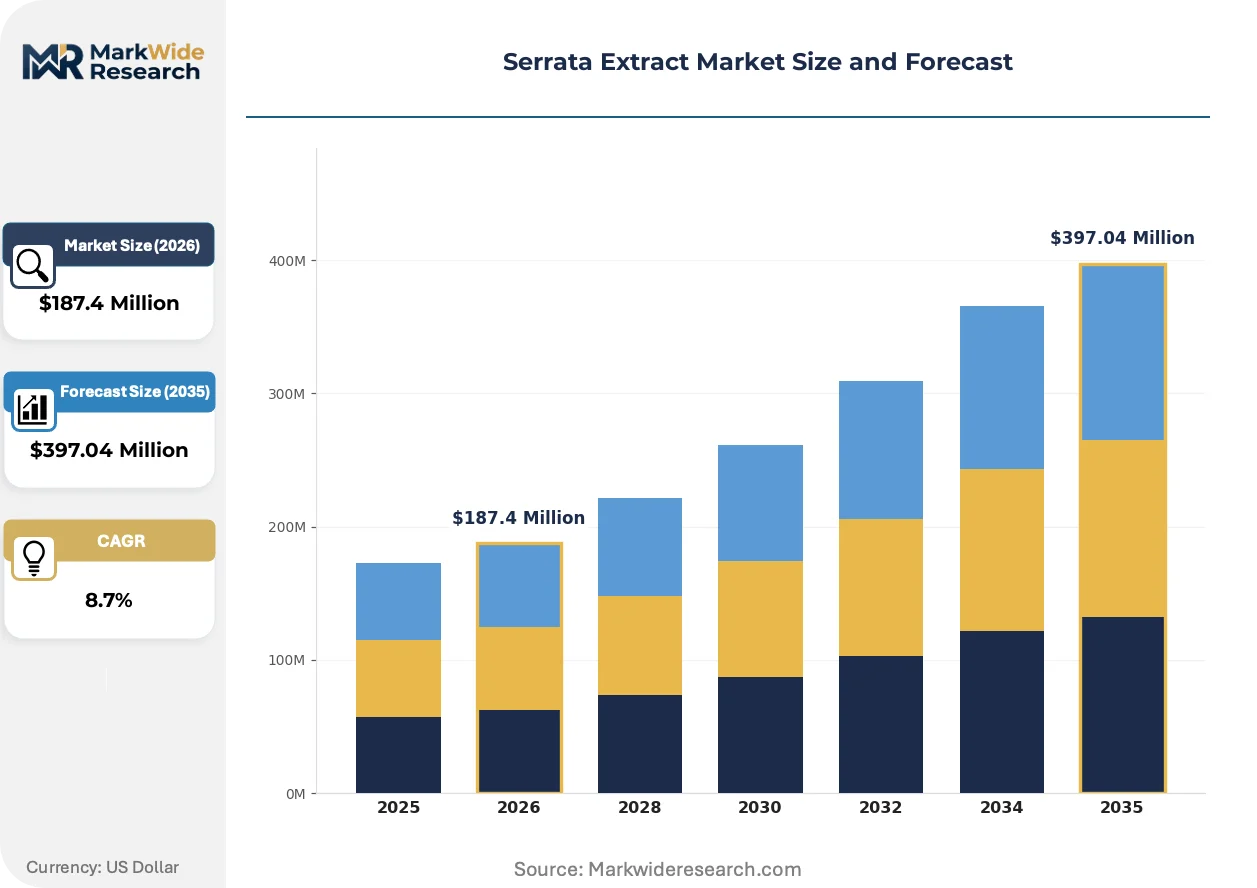
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powder, Liquid Extract Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods End User: Retail Consumers, Healthcare Providers, Wellness Centers, Nutraceutical Companies Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Health Food Stores |
| Companies Covered | Arjuna Natural, Alchem International, Marven Bio Chem, Herbal BioActives LLP, Sabinsa Corporation, Indena S.p.A., Jayshree Nath Herbals, Alps Pure, Manus Aktteva biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serrata Extract Market Emerging Trajectories
Extraction technology convergence with pharmaceutical quality standards is compressing the traditional gap between Ayurvedic raw material supply and regulated drug development requirements.
Supercritical CO2 extraction systems with tunable pressure parameters are virtualizing traditional solvent-based capacity. Pharmaceutical-grade refiners in India and Europe are adopting these units at replacement-cycle pace. This technology is virtualizing the capital barrier that previously segregated food-grade from pharmaceutical-grade processors, enabling mid-scale entrants to achieve AKBA ratio precision previously requiring chromatographic infrastructure investments.
REACH registration requirements for botanical substances entering European Union industrial supply chains are tightening substance characterization documentation. Extract importers must now submit full analytical profiles for boswellic acid fractions above 10-ton annual thresholds. German and Swiss pharmaceutical customers are responding by consolidating supplier relationships with processors holding certified EU-REACH dossiers, compressing vendor qualification timelines.
Pharmacy channel buyers are consolidating procurement around suppliers offering integrated quality documentation packages. This behavior is displacing spot-market resin purchasing among European and North American formulators. The shift is most visible in Germany, where CDMOs serving anti-inflammatory drug developers now require batch-specific HPLC chromatograms and heavy metal certificates as standard contract terms.
Serrata Extract Market Segmentation
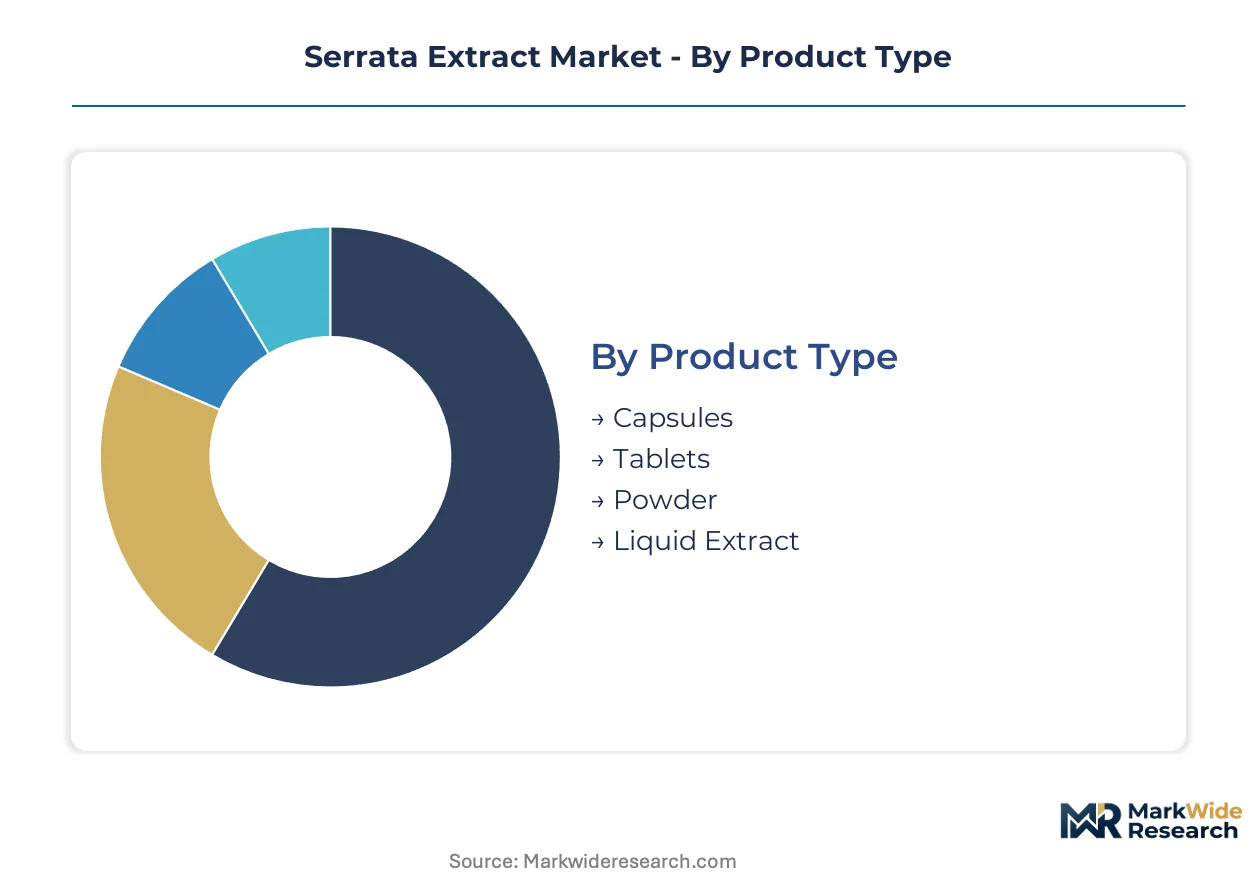
Serrata extract segmentation reflects divergent technical requirements across pharmaceutical, nutraceutical, and cosmetic channels. Each segment demands distinct standardization levels, bioavailability specifications, and regulatory documentation that reshape supplier capabilities and margin structures.
Product Type:
After-sales service intensity varies sharply across dosage formats, with pharmaceutical-grade capsules requiring batch traceability support and liquid extracts demanding solubility troubleshooting for beverage formulators.
- Capsules:Hard-shell gelatin and vegetable-based encapsulation systems deliver precise AKBA dosing for anti-inflammatory protocols. German pharmaceutical CDMOs specify enteric-coated variants to protect boswellic acids from gastric degradation, locking in multi-year supply contracts with certified processors.
- Tablets:Compressed dosage forms with controlled-release matrices extend absorption windows for sustained therapeutic effect. Direct compression and wet granulation methods dominate production, with Karnataka-based contract manufacturers supplying European nutraceutical private label programs.
- Powder:Bulk standardized fractions serve functional food and cosmeceutical compounding. Blending uniformity challenges limit adoption in pharmacy channels where dose precision carries liability weight.
- Liquid Extract:Rapid-dispersion formulations capture functional beverage applications across German and French retail. Cold-water solubility specifications and taste masking requirements concentrate formulation expertise with specialized extractors.
Capsules hold the largest share; momentum sits with liquid extract formats.
Application:
Application segmentation tracks divergent regulatory thresholds, with pharmaceutical pipelines demanding clinical validation investments that exclude commodity-grade suppliers.
- Dietary Supplements:Standardized boswellic acid capsules and tablets dominate retail shelf presence for joint health positioning. US and German consumers drive procurement of 30-70% standardized fractions through pharmacy and online channels.
- Pharmaceuticals:Investigational new drug submissions require HPLC-characterized AKBA fractions with heavy metal and pesticide documentation. The US FDA botanical drug pathway attracts German and Swiss developers targeting osteoarthritis endpoints.
- Cosmetics:Micronized boswellic acid fractions target skin aging mechanisms in Korean and Japanese beauty formulations. Topical bioavailability limitations constrain penetration relative to oral delivery systems.
- Functional Foods:EU Novel Food approvals enable shelf-stable beverage applications for rapid-dispersion liquid extracts. German and French retail channels show fastest adoption for anti-inflammatory positioning.
Pharmaceuticals command the steepest margins; functional foods are climbing the fastest.
End User:
End user concentration shapes procurement behavior, with nutraceutical companies consolidating supplier relationships around integrated quality documentation.
- Nutraceutical Companies:Vertically integrated formulators from raw material through finished dosage drive volume procurement of standardized extracts. New Jersey and German facilities specify batch-specific chromatograms and stability data.
- Healthcare Providers:Integrative medicine practitioners and Ayurvedic clinics specify traditional resin preparations alongside standardized extracts. Kerala and Karnataka clinical networks anchor institutional demand.
- Retail Consumers:Direct-to-purchaser channels through online retail and health food stores favor capsule and tablet convenience. Label comprehension gaps create vulnerability to adulterated products.
- Wellness Centers:Spa and preventive health facilities incorporate topical and oral applications into service protocols. Custom compounding requirements fragment order sizes.
Nutraceutical companies dominate volume; healthcare providers are gaining share fastest.
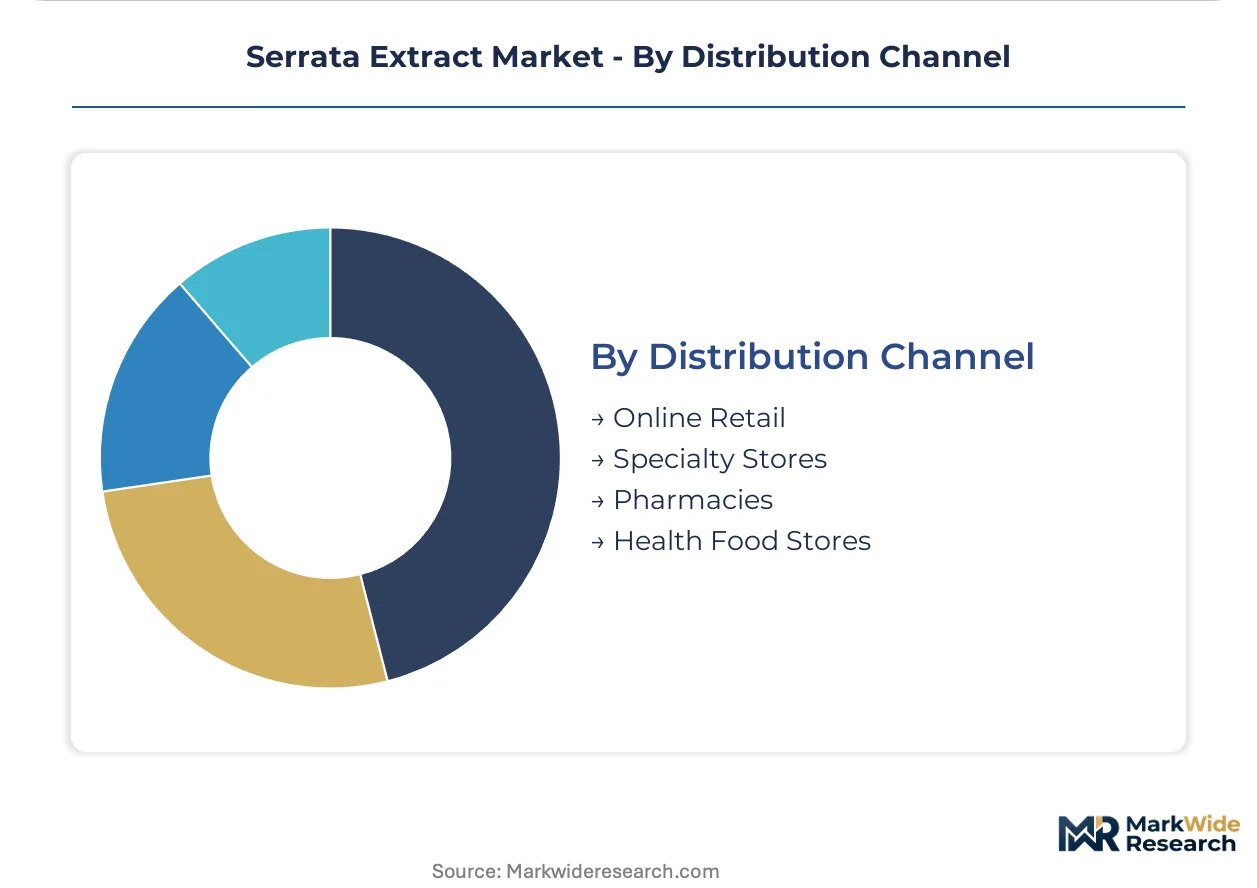
Distribution Channel:
Channel segmentation tracks compliance differentiation, with pharmacy access requiring pharmacopeial certification that online retail bypasses.
- Pharmacies:Regulated channels in Germany, France, and Switzerland enforce USP and EP compliance for reimbursed or pharmacist-recommended products. Documentation requirements compress vendor pools to certified processors.
- Online Retail:Direct-to-consumer platforms enable global reach for standardized and non-standardized products alike. Amazon and specialized botanical retailers concentrate price transparency pressure.
- Specialty Stores:Health food and organic retail chains in Germany and France curate premium-positioned extracts with sustainability credentials. Shelf placement fees favor established brands.
- Health Food Stores:Independent and cooperative retailers serve enthusiast consumers seeking traditional Ayurvedic preparations. Inventory depth limitations constrain SKU proliferation.
Pharmacies capture the highest value per unit; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports refined Boswellia serrata extracts to pharmaceutical formulators in Germany, nutraceutical distributors in the United States, and cosmeceutical manufacturers in Japan. These three trade corridors anchor procurement patterns for standardized boswellic acid fractions.
United States
Dietary supplement manufacturers in New Jersey and California drive procurement of AKBA-standardized capsules for joint health retail positioning. The US FDA botanical drug development guidance shapes investigational new drug submission requirements for osteoarthritis therapeutic pipelines. Sabinsa Corporation's vertically integrated supply chain from Indian raw material to New Jersey formulation facilities exemplifies this procurement concentration.
Germany
Pharmaceutical contract development and manufacturing organizations in Bavaria and North Rhine-Westphalia expand procurement for anti-inflammatory drug development targeting joint health indications. The European Medicines Agency's Committee on Herbal Medicinal Products issues monographs defining minimum quality benchmarks for traditional use registrations. Supercritical CO2 extraction technology adoption concentrates among refiners serving these CDMO quality documentation requirements.
India
Karnataka and Kerala states host resin collection clusters and primary processing infrastructure supplying upstream refiners across three continents. The Central Drugs Standard Control Organization enforces Schedule T of the Drugs and Cosmetics Rules for Good Manufacturing Practices in Ayurvedic medicine production. Arjuna Natural leverages Kerala-based extraction infrastructure to supply standardized AKBA fractions to European pharmaceutical customers from this cluster.
Japan
Micronized delivery system demand from Korean and Japanese beauty manufacturers creates pull for topical cosmeceutical applications targeting skin aging mechanisms. The Ministry of Economy, Trade and Industry oversees industrial standards for botanical extract imports entering functional cosmetic supply chains. Osaka-based formulators specialize in bioavailability-enhanced boswellic acid fractions for premium skincare positioning.
Switzerland
Swiss pharmaceutical developers target osteoarthritis endpoints through standardized extract characterization investments aligned with US FDA botanical drug pathways. Swissmedic regulates therapeutic product quality documentation requirements for clinical validation pipelines. Geneva and Basel clusters concentrate contract research organizations facilitating EU-REACH dossier preparation for botanical substance characterization.
Serrata Extract Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Vertically integrated processors with captive Indian raw material supply and European or North American formulation facilities occupy the premium documentation tier. Mid-scale refiners leveraging supercritical CO2 technology fragmentation compete on AKBA ratio precision without chromatographic infrastructure investments. Spot-market resin purchasers serving non-pharmaceutical channels occupy the commodity tier with minimal regulatory compliance overhead. Strategic moves concentrate on supplier consolidation around integrated quality documentation packages and technology licensing for tunable-pressure extraction systems.
Within the vertically integrated tier, Arjuna Natural and Sabinsa Corporation exemplify archetypes combining Indian upstream control with destination-market formulation capabilities. Indena S.p.A. occupies a position representing European specialist refinement and micronized delivery system expertise. These three anchors illustrate how geographic origin and company structure map to competitive positioning across pharmaceutical-grade, nutraceutical, and cosmeceutical application vectors.
| Leading Market Players |
|---|
| Arjuna Natural |
| Alchem International |
| Marven Bio Chem |
| Herbal BioActives LLP |
| Sabinsa Corporation |
| Indena S.p.A. |
| Jayshree Nath Herbals |
| Alps Pure |
| Manus Aktteva biopharma |
| Others |
Supply Flow & Price Mechanics
Undercapacity in supercritical CO2 extraction infrastructure across Karnataka and Kerala is compressing spot-market resin availability while elevating contract premiums for pharmaceutical-grade AKBA fractions. German CDMOs now absorb extended batch release cycles to secure supply, passing documentation costs downstream through tiered contract structures.
Pricing Analysis
Supercritical CO2 extraction capacity commands a 40-60% premium over solvent-based refining, with next-generation tunable-pressure systems widening the gap against legacy processors. Pricing stratifies across pharmaceutical-grade, nutraceutical-grade, and commodity resin tiers, with EU-REACH dossier certification and USP-compliant heavy metal documentation as primary differentiation drivers. Cost compression in the commodity tier intensifies as smaller Karnataka processors adopt second-hand CO2 units, fragmenting margins. Nutraceutical private label buyers exhibit highest price sensitivity, while Swiss and German pharmaceutical developers prioritize batch traceability over unit economics.
Supply Chain Analysis
Wild Boswellia serrata resin harvests in Rajasthan and Gujarat feed primary processing clusters in Karnataka and Kerala, with downstream refinement concentrated in India, Germany, and the United States. Chromatographic AKBA enrichment equipment, supercritical CO2 extraction vessels, and HPLC analytical infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in wild collection labor pools, where climate-induced yield volatility and migration patterns disrupt upstream flow. Distribution runs through certified processor networks to pharmaceutical CDMOs, with spot-market resin trading persisting in non-pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
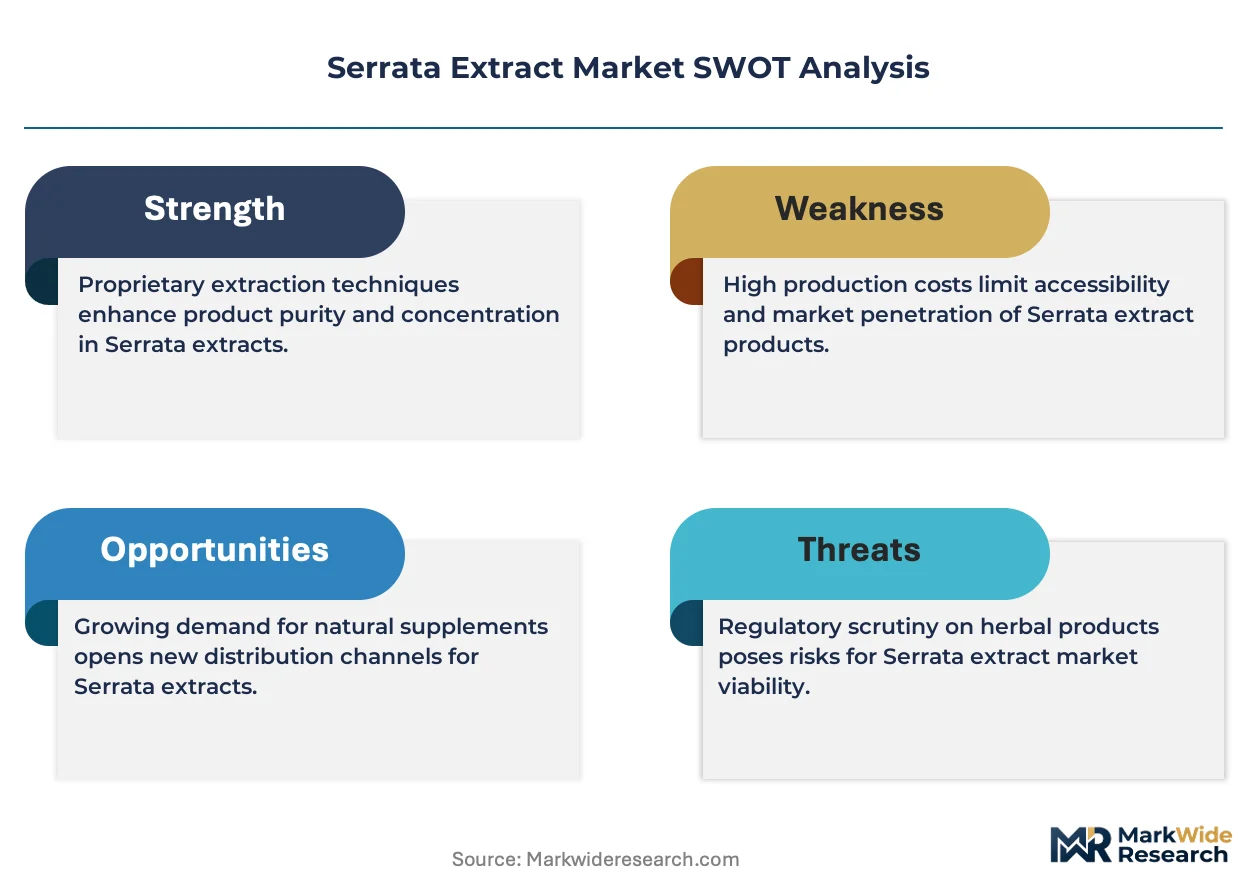
This market functions as a regulatory-entrenchment story, where EU-REACH dossier preparation and US FDA botanical drug pathway navigation erect switching costs that lock in qualified suppliers and marginalize uncertified competitors.
For Market Incumbents: Build documentation moats through integrated quality packages spanning batch-specific HPLC chromatograms, heavy metal certificates, and stability data. Consolidate supplier relationships around multi-year offtake agreements with Karnataka-based processors holding certified EU-REACH dossiers. Capacity addition in Kerala supercritical CO2 infrastructure defends against emerging mid-scale entrants leveraging technology fragmentation. For New Entrants and Emerging Players: Pursue functional beverage applications in German and French retail channels, where rapid-dispersion liquid extract formats face lower pharmacy compliance barriers. Micronized delivery systems for Korean and Japanese cosmeceutical markets offer whitespace with reduced AKBA standardization requirements. Partner with established Kerala processors for toll manufacturing to bypass chromatographic infrastructure investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated processors combining Indian upstream resin control with European or North American formulation capabilities. Long-term viability centers on regulatory entrenchment depth rather than volume scale. Acquisition targets should demonstrate certified EU-REACH dossiers and active US FDA botanical drug pathway engagements. The signal to watch is CDSCO Schedule T enforcement tightening, which would accelerate consolidation among uncertified Ayurvedic processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wild Resin Collection | Karnataka processors securing Rajasthan harvest contracts stabilize feedstock against climate volatility. |
| Supercritical CO2 Capacity Expansion | Kerala-based infrastructure investments compress pharmaceutical-grade standardization timelines for European CDMOs. |
| EU-REACH Dossier Certification | German and Swiss pharmaceutical customers consolidate procurement around REACH-registered suppliers exclusively. |
| US FDA Botanical Drug Pathway Engagement | Investigational new drug submissions for osteoarthritis endpoints attract venture funding for clinical validation. |
| Micronized Delivery System Development | Osaka-based formulators license bioavailability-enhanced fractions for premium Korean skincare positioning. |
Methodological Framework
Operator-level perspectives from extraction facility managers, pharmaceutical CDMO procurement leads, Ayurvedic medicine production directors, and EU regulatory affairs specialists anchored the qualitative base. These primary interviews combined with secondary validation from CDSCO Schedule T enforcement records, EMA Committee on Herbal Medicinal Products monographs, US FDA botanical drug guidance documents, and EU-REACH registration databases. Bottom-up resin collection volume estimates from Rajasthan and Gujarat forestry departments triangulated against top-down pharmaceutical formulation demand from German and Swiss CDMOs.
Scenario-bracketing framed demand projections across the analysis window, modeling osteoarthritis therapeutic pipeline advancement, EU Novel Food approval velocity, and functional beverage dispersion adoption as primary demand drivers. Segmentation dimensions included product type, application, and end user, with AKBA standardization level and regulatory certification tier as industry-specific cross-cuts. CAGRs derived from volume-price elasticity modeling calibrated to historical supercritical CO2 capacity expansion patterns and chromatographic purification cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private equity-backed mid-scale processors would shift outcomes. Material shifts in CDSCO Schedule T enforcement stringency, EMA heavy metal limit revisions, or US FDA botanical drug pathway approval velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Seasonings Market