
 Cutting Equipment, Accessories and Consumables Market | 2026-2036
Cutting Equipment, Accessories and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Equipment, Accessories and Consumables Market Intelligence
The proliferation of high-power fiber laser sources is narrowing the performance gap between dedicated cutting technologies and multi-process systems. Hypertherm Inc. specializes in plasma and waterjet systems, offering solutions for heavy industry. Illinois Tool Works Inc. leverages its diversified portfolio to integrate cutting solutions within broader welding and fabrication workflows, while Kennametal Inc. differentiates through its advanced material science in consumables like cutting tips and nozzles.
Cutting equipment encompasses machinery designed to shape materials through thermal, abrasive, or mechanical force. These systems are defined by parameters like cutting speed, kerf width, and the extent of the heat-affected zone on the workpiece. Within product types, laser cutters are gaining share for high-precision tasks in aerospace manufacturing. Plasma cutters, however, maintain a strong position in heavy-duty metal fabrication due to their cost-effectiveness on thick materials.
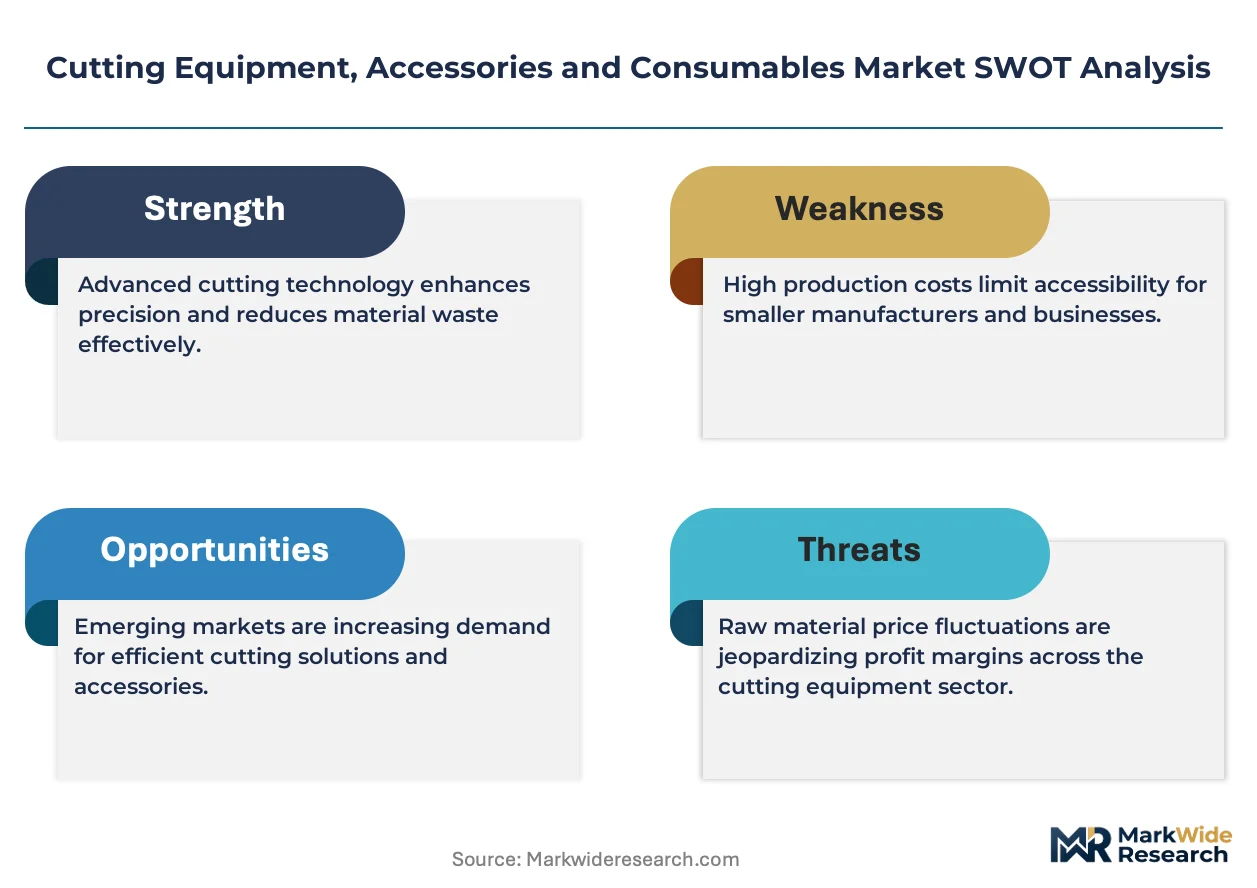
Regulatory frameworks impose strict safety and performance standards on equipment manufacturers. In the United States, OSHA regulations mandate operator safety features. Equipment sold in Europe must adhere to CE marking requirements for machinery safety, while China’s GB standards govern product compliance. The key decision for end-users centers on balancing the high capital cost of robotic automation against the flexibility of manual operation.
Market Dynamics
The central dynamic shaping the market is the escalating requirement for precision and material versatility driven by advanced manufacturing sectors. This demand pressures equipment makers to move beyond incremental hardware improvements and innovate on software, automation, and process control.
Growth Catalysts
- Fiber Laser Proliferation:The ongoing replacement of CO2 lasers with more efficient and precise fiber laser technology accelerates equipment upgrade cycles, particularly in sheet metal fabrication for the automotive and electronics industries.
- Aerospace Material Evolution:Demand from the aerospace sector for cutting complex composites and high-strength nickel alloys requires advanced waterjet and multi-axis laser systems, supporting growth in high-performance equipment categories.
- Advanced Manufacturing Policies:National industrial strategies, such as China's promotion of advanced manufacturing clusters, stimulate domestic investment in high-end automated cutting solutions to enhance global competitiveness and supply chain resilience.
Market Restraints
- High Capital Investment:The significant upfront cost of automated robotic cutting cells and high-power laser systems creates a substantial barrier to adoption for small and medium-sized enterprises in metalworking and fabrication.
- Process-Specific Limitations:Thermal cutting methods like plasma and laser create a heat-affected zone (HAZ) that can alter the metallurgy of the workpiece, making them unsuitable for certain sensitive aerospace and medical applications.
- Critical Component Dependency:The supply of essential components, such as high-power fiber laser sources and sophisticated CNC controllers, is concentrated among a small number of specialized manufacturers, creating potential price volatility and supply bottlenecks.
Strategic Opportunities
- Medical Device Manufacturing:The need for micro-cutting of biocompatible materials like titanium and nitinol for medical implants and surgical instruments presents an opportunity for specialized, high-precision laser and waterjet systems.
- Software and AI Integration:Developing intelligent software that uses artificial intelligence to optimize nesting patterns, predict maintenance needs, and automatically adjust cutting parameters for different materials offers a new value stream.
- Southeast Asian Industrialization:Expanding into rapidly industrializing markets like Vietnam and Indonesia, where manufacturing investment is rising, provides a new geographic frontier for both entry-level and automated cutting equipment.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of technicians qualified to program, operate, and maintain complex multi-axis CNC cutting machinery constrains productivity and limits the effective deployment of advanced systems.
- System Integration Complexity:Integrating new automated cutting equipment with a company's existing enterprise resource planning (ERP) and manufacturing execution systems (MES) is often a complex, costly, and time-consuming process.
- Fragmented Regulatory Compliance:Manufacturers face the challenge of navigating and complying with a diverse set of regional safety and performance standards, including CE marking in Europe and GB standards in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Equipment, Accessories and Consumables Market |
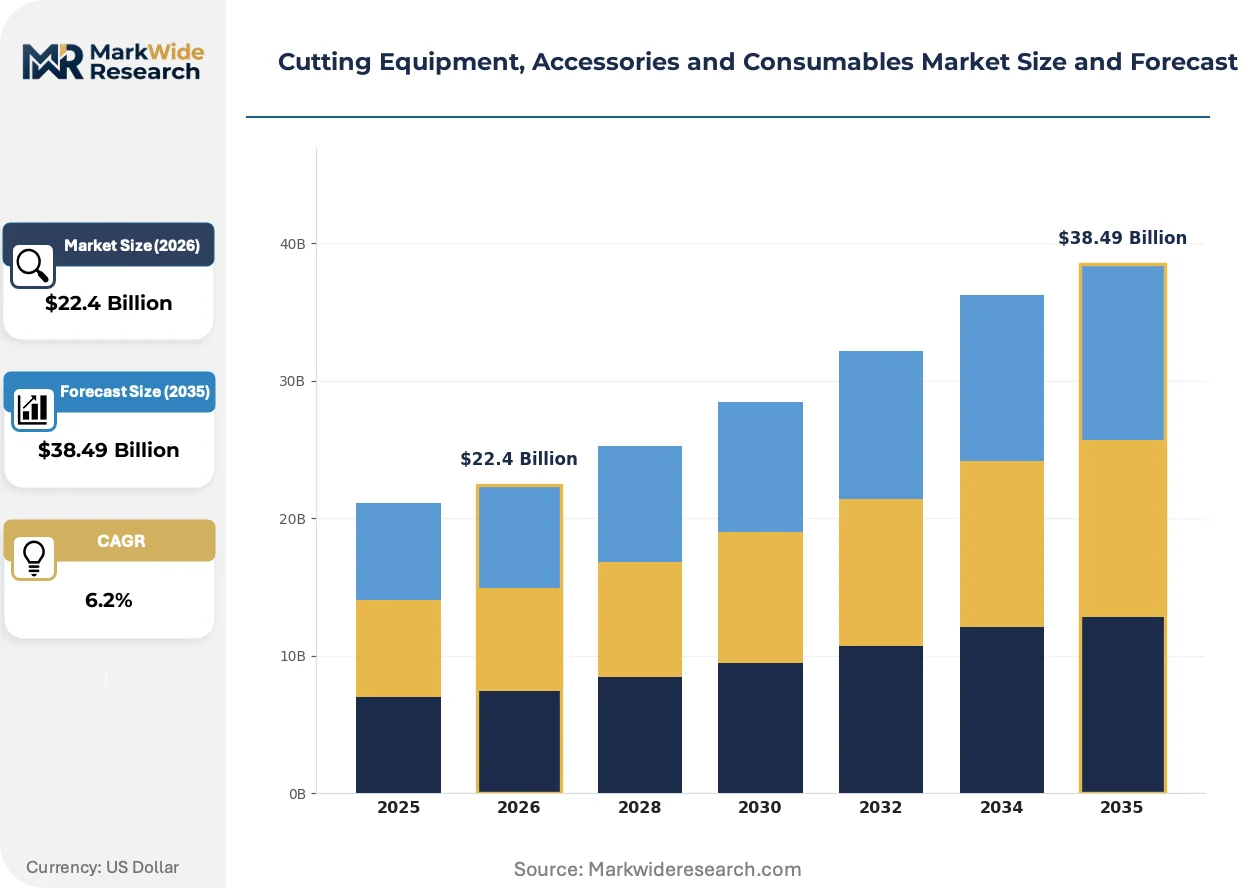
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutters, Plasma Cutters, Water Jet Cutters, Oxy-Fuel Torches, Shears Technology: CNC Machining, Manual Operation, Robotic Automation, Thermal Cutting, Abrasive Cutting Application: Metal Fabrication, Aerospace Manufacturing, Shipbuilding, Packaging Production, Electronics Assembly End User: Fabrication Workshops, Automotive Suppliers, Construction Firms, Electronics Manufacturers, Custom Job Shops |
| Companies Covered | Hypertherm Inc., Illinois Tool Works Inc., Lincoln Electric Co., Koike Aronson Inc., Colfax Corp, Kennametal Inc., Jet Edge Inc., Fronius International GmbH, ESAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Equipment, Accessories and Consumables Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from standalone hardware to integrated, software-driven systems. This transition emphasizes process optimization, automation, and data connectivity as primary sources of competitive differentiation, moving beyond traditional metrics like cutting speed alone.
Digital twin technology provides a virtual model of the physical cutting machine and its operational process. Aerospace and automotive firms are the primary adopters, using these models to simulate cutting paths and test parameters without consuming physical material or machine time. This technology is virtualizing the entire job setup and validation process, significantly reducing scrap rates and shortening product development cycles.
Europe's Machinery Directive establishes rigorous safety requirements for industrial equipment, enforced via the mandatory CE marking. This regulation compels manufacturers to incorporate integrated safety systems, such as light curtains, enclosed cutting areas, and advanced fume extraction, directly into the equipment design. The high-power laser and plasma cutting segments are most impacted, with product development now balancing performance with enhanced operator safety standards.
A notable behavioral shift is occurring as end-users pivot from one-off consumable purchases to service-based agreements for managing their inventories of nozzles, electrodes, and lenses. This model sees equipment OEMs and specialized service firms offering automated replenishment and inventory management, disrupting traditional distribution channels. The trend is most prominent within North American and European fabrication shops aiming to reduce working capital and prevent production stoppages.
Cutting Equipment, Accessories and Consumables Market Segmentation
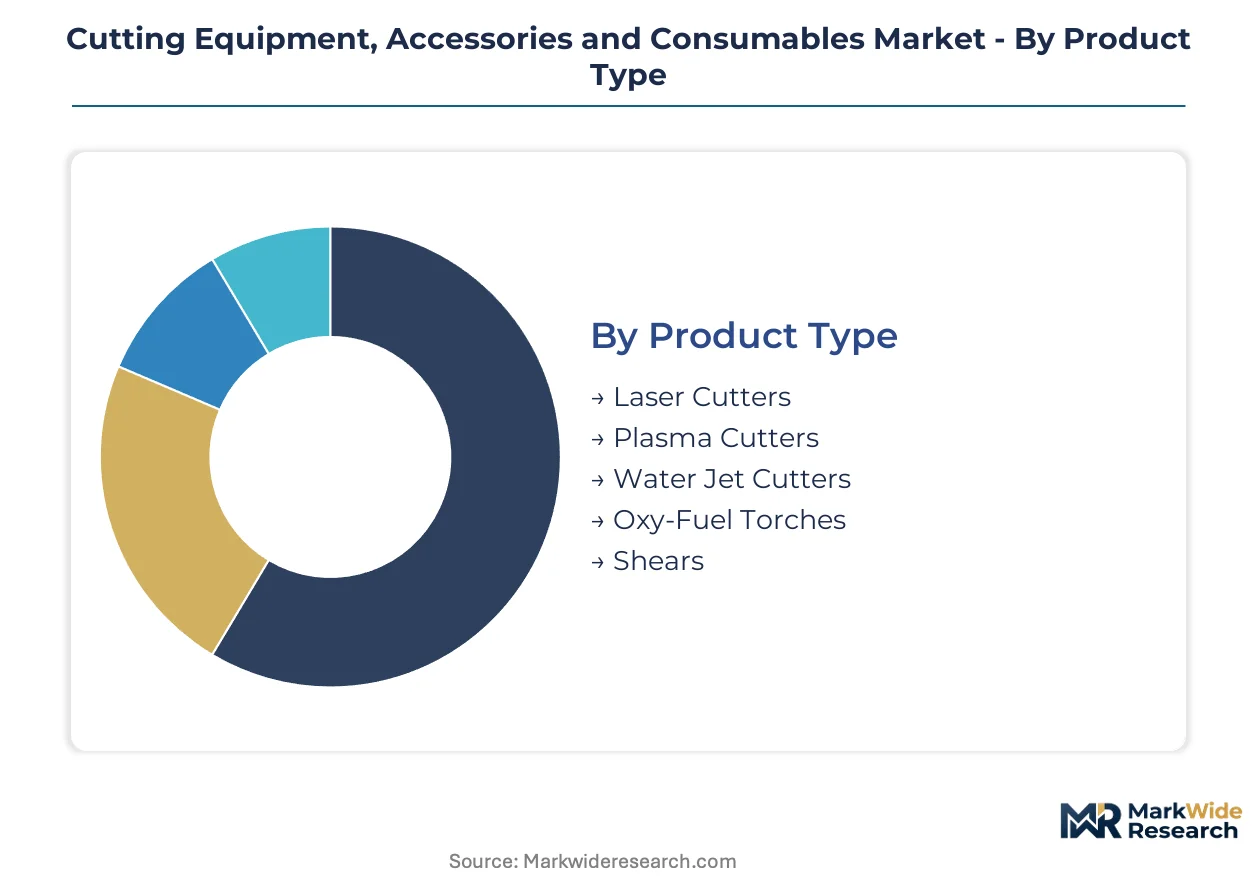
Market segmentation provides a granular view of the cutting equipment, accessories, and consumables sector, revealing the interplay of technological advancements and diverse end-user requirements. This detailed breakdown helps stakeholders understand where value is created and how specific product types and technologies address distinct industrial challenges.
Product Type:
The functional capabilities of cutting equipment are delineated by specific product types, each optimized for different materials and precision levels.
- Laser Cutters:These systems utilize focused light beams for high-precision material removal, offering minimal heat-affected zones and intricate cutting capabilities. Demand concentrates in aerospace manufacturing, where the transition to fiber laser technology drives equipment upgrades.
- Plasma Cutters:Employing an accelerated jet of hot plasma, these machines efficiently cut electrically conductive materials, particularly thick metals, with high speed. Their cost-effectiveness sustains strong demand in heavy-duty metal fabrication across various industrial sectors.
- Water Jet Cutters:These tools use a high-pressure stream of water, often mixed with abrasive particles, to cut a wide range of materials without thermal distortion. They are critical for processing sensitive composites and biocompatible materials in medical device manufacturing.
- Oxy-Fuel Torches:Relying on a chemical reaction between oxygen and fuel gas, these torches cut thick ferrous metals through oxidation. Construction firms and demolition operations utilize them for their robust performance and lower capital investment.
- Shears:Mechanical shearing devices perform straight-line cuts on sheet metal and plates using opposing blades. Fabrication workshops employ shears for rapid, clean cuts in high-volume, less complex applications.
Plasma Cutters hold substantial installed capacity. Laser Cutters are rotating up the share rankings.
Technology:
Technological sophistication defines operational efficiency and material processing capabilities, influencing system integration and automation levels.
- Robotic Automation:Integrated robotic arms enhance cutting precision, repeatability, and speed across multi-axis applications, reducing manual labor requirements. Advanced manufacturing clusters in China are investing heavily in robotic solutions to boost productivity and competitiveness.
- CNC Machining:Computer Numerical Control systems provide programmable, automated control over cutting tool paths, enabling complex geometries and consistent part quality. Aerospace manufacturing relies on CNC for precision component production from high-strength alloys.
- Manual Operation:This category encompasses handheld or manually guided cutting tools that require direct human intervention and skill for material processing. Custom job shops and smaller fabrication workshops frequently utilize manual operations for their flexibility and lower upfront investment.
- Thermal Cutting:Technologies such as plasma and laser cutting use heat to melt or vaporize material, offering high speed and versatility for metal processing. The automotive industry employs thermal cutting extensively for chassis and body component fabrication.
- Abrasive Cutting:Methods like waterjet cutting utilize abrasive particles suspended in a high-velocity fluid stream to erode material, avoiding heat-affected zones. Medical device manufacturers use abrasive cutting for delicate, heat-sensitive materials.
The shift towards automation is evident across advanced manufacturing clusters. Manual operations provide essential flexibility for specialized tasks.
Application:
End-use applications dictate the required precision, material handling, and throughput of cutting systems across diverse industrial sectors.
- Aerospace Manufacturing:This sector demands ultra-high precision cutting for advanced composites and high-strength nickel alloys used in aircraft components. Multi-axis laser and waterjet systems are critical for meeting stringent quality and performance standards.
- Metal Fabrication:Encompassing a broad range of industries from automotive to construction, metal fabrication requires efficient cutting of various metal sheets, plates, and structural forms. Plasma and fiber laser cutters are workhorses in this high-volume production environment.
- Shipbuilding:Large-scale metal cutting for ship hulls, decks, and superstructures characterizes this application. Plasma cutters are favored for their ability to process thick steel plates quickly and cost-effectively in shipyards globally.
- Packaging Production:Precision cutting of paper, cardboard, plastics, and foils is essential for creating packaging materials and designs. Laser cutting systems offer high speed and intricate detail for custom packaging solutions.
- Electronics Assembly:Micro-cutting and dicing of delicate electronic components, circuit boards, and semiconductor wafers are crucial for this industry. Specialized fiber lasers and ultra-short pulse lasers provide the necessary precision without damaging sensitive materials.
Aerospace manufacturing consistently demands the highest performance. Metal fabrication remains the largest volume consumer of cutting solutions.
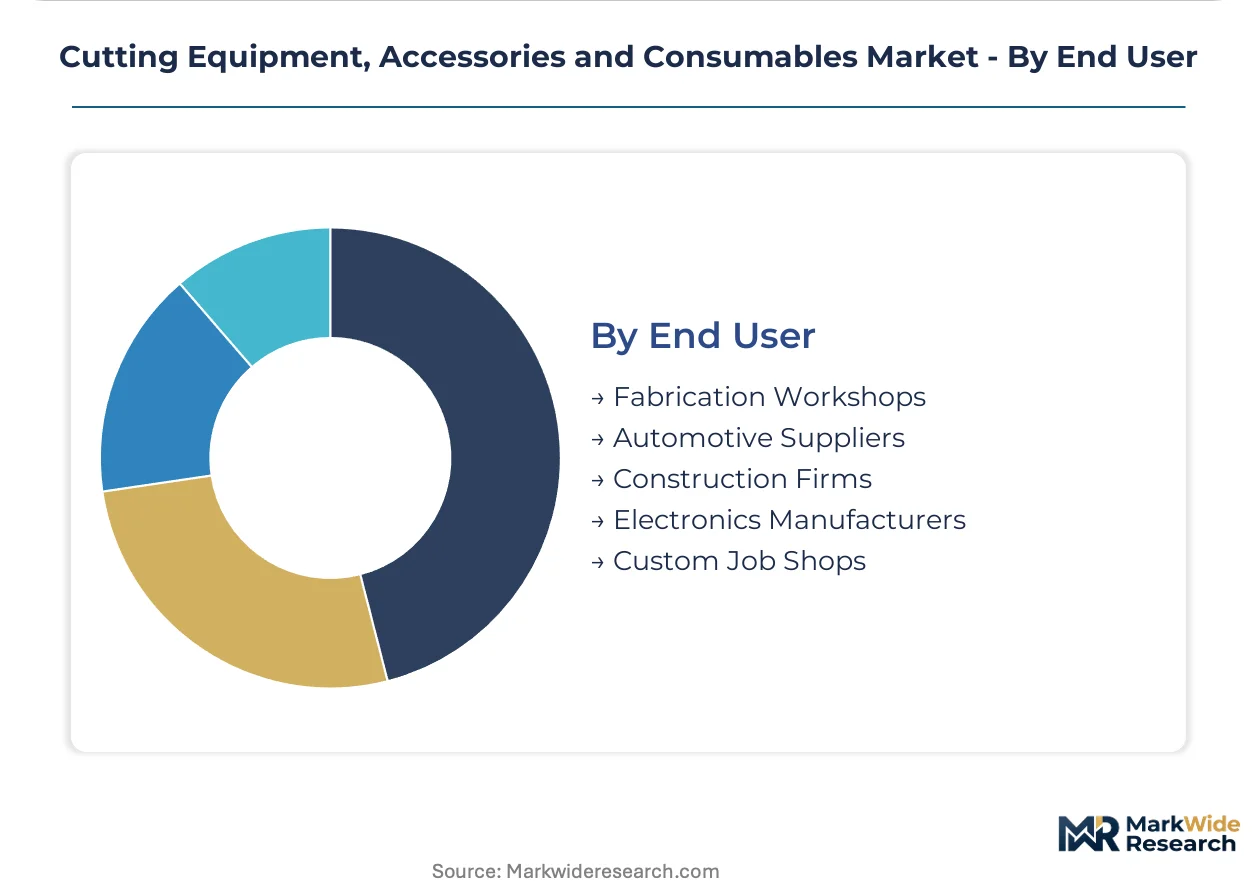
End User:
The diverse landscape of end-users reflects varying operational scales and material processing needs, from small workshops to large industrial complexes.
- Fabrication Workshops:These entities perform custom metalwork, prototyping, and small-batch production for a variety of clients. They often seek versatile cutting equipment that balances cost-effectiveness with a range of material capabilities.
- Automotive Suppliers:Producing components for vehicle manufacturing, these suppliers require high-volume, automated cutting solutions with stringent quality control. They frequently invest in integrated laser and plasma cutting cells for efficiency.
- Construction Firms:Engaged in building infrastructure and structures, construction firms use cutting equipment for processing steel beams, rebar, and other construction materials. Portable oxy-fuel and plasma cutters are common for on-site applications.
- Electronics Manufacturers:These companies specialize in the production of electronic devices and components, demanding ultra-precise micro-cutting capabilities. Cleanroom-compatible laser systems are essential for their delicate manufacturing processes.
- Custom Job Shops:Offering specialized fabrication services tailored to unique client specifications, custom job shops prioritize equipment flexibility to handle diverse materials and complex designs. Waterjet and multi-axis laser cutters support their varied project requirements.
Automotive suppliers prioritize high throughput and integration. Custom job shops value adaptability for specialized projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial manufacturing prowess drives significant exports of cutting equipment to rapidly industrializing nations across Southeast Asia and Africa. This global trade flow supports diverse end-user requirements, from heavy fabrication to precision micro-cutting. Regional demand for advanced cutting solutions is influenced by domestic industrial policies.
China
Demand for automated cutting solutions in China stems from its advanced manufacturing clusters, particularly in automotive and electronics production. The country's GB standards ensure product compliance and safety for equipment deployed within its vast industrial base. Major manufacturing hubs in the Yangtze River Delta invest heavily in high-power fiber laser systems.
United States
The United States aerospace sector fuels demand for ultra-high precision waterjet and multi-axis laser systems for complex materials. OSHA regulations mandate strict operator safety features, influencing equipment design. Aerospace manufacturing concentrations in Wichita and Seattle require sophisticated cutting machinery.
Germany
Germany's robust automotive and industrial machinery sectors drive demand for efficient and precise thermal cutting technologies. Equipment sold in Europe must adhere to CE marking requirements for machinery safety. Advanced manufacturing regions like Baden-Württemberg adopt integrated robotic cutting cells for enhanced productivity.
India
Infrastructure development and a growing automotive component manufacturing base create demand for cost-effective plasma and fiber laser cutters in India. The PLI scheme encourages domestic production and adoption of advanced manufacturing technologies. Industrial corridors in Gujarat and Maharashtra expand their metal fabrication capabilities.
Vietnam
Vietnam's rising manufacturing investment, particularly in electronics and automotive assembly, increases its need for both entry-level and automated cutting equipment. National industrial policies support the modernization of manufacturing capabilities. Industrial parks near Ho Chi Minh City see increased installation of automated cutting systems.
Cutting Equipment, Accessories and Consumables Market Key Industry Players
Channel-controlling players compete with product-specialist players across the cutting equipment market. The market structure exhibits a blend of highly diversified industrial conglomerates and specialized technology providers. Strategic archetypes include full-service integrators offering complete fabrication solutions, niche technology innovators focusing on specific cutting methods, and consumables specialists. Dominant competitive moves involve portfolio diversification into adjacent manufacturing processes and strategic partnerships to offer integrated solutions.
Specialists in plasma and waterjet systems, Hypertherm Inc. represents a significant player focusing on core cutting technologies and advanced software. Illinois Tool Works Inc., a diversified industrial manufacturer, occupies a position within broader welding and fabrication workflows, leveraging its extensive global footprint. Lincoln Electric Co. further anchors the market with its comprehensive range of cutting and welding solutions, serving a wide array of industrial end-users globally. These companies exemplify the strategic approaches of deep specialization and broad industrial integration across diverse manufacturing segments.
| Leading Market Players |
|---|
| Hypertherm Inc. |
| Illinois Tool Works Inc. |
| Lincoln Electric Co. |
| Koike Aronson Inc. |
| Colfax Corp |
| Kennametal Inc. |
| Jet Edge Inc. |
| Fronius International GmbH |
| ESAB |
| Others |
Cost & Logistics Intelligence
Single-source dependency on high-power fiber laser sources determines both pricing tier spreads for advanced systems and the concentrated supply chain shape. This reliance impacts equipment manufacturers' cost structures and market entry points.
Pricing Analysis
The technology-generation pricing gap between CO2 and fiber laser systems establishes distinct market entry points. Equipment sales primarily follow a per-unit transactional model, often bundled with long-term service agreements for consumables. Price differentiation stems from cutting precision capabilities and automation levels, with advanced robotic systems commanding premiums. Pricing softness reflects rapid technological advancements, making small and medium-sized enterprises highly price-sensitive.
Supply Chain Analysis
Export-control regimes on advanced technologies, particularly high-power laser components, limit flows to certain markets. The supply chain for critical cutting equipment components concentrates in China, Germany, and Japan, sourcing high-power fiber laser sources and sophisticated CNC controllers. Raw material dependencies include rare earth elements for lasers and specialized alloys for consumables, creating single-source vulnerabilities and potential supply bottlenecks. Distribution runs through a mix of direct OEM sales and specialized regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a robust substitution defense as multi-process manufacturing systems increasingly narrow the performance gap with dedicated cutting technologies. Incumbents must navigate this threat by enhancing specialized capabilities and software integration.
For Market Incumbents:Pre-empt the performance creep from multi-process systems by deepening software integration and offering outcome-based service agreements. Strengthen vertical integration into critical component manufacturing to mitigate supply chain risks and control costs. Invest in advanced material science for consumables, extending performance life and reducing heat-affected zones. Pursue strategic partnerships to integrate cutting solutions into broader fabrication workflows, enhancing customer stickiness.
For New Entrants and Emerging Players:Build out specialized capabilities for micro-cutting in medical device manufacturing, targeting biocompatible materials like titanium and nitinol. Penetrate rapidly industrializing markets such as Vietnam and Indonesia with cost-effective, entry-level automated cutting solutions. Offer intelligent software platforms that optimize nesting patterns and predict maintenance, providing a differentiated value proposition. Focus on niche applications requiring ultra-high precision where established players have less flexibility.
For Investors and Strategic Acquirers:CE marking requirements and GB standards reshape the acquisition landscape, favoring companies with robust safety and compliance portfolios. Long-term viability hinges on the continued demand for high-precision manufacturing across aerospace and medical sectors. Target niche technology innovators specializing in advanced laser or waterjet systems, or software firms focused on AI-driven process optimization. The signal to watch is the increasing integration of intelligent software into cutting equipment platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Software and AI Integration | Enhances process optimization and predictive maintenance for complex cutting operations. |
| Advanced Consumables R&D | Improves cutting performance and extends tool life in high-precision applications. |
| Geographic Expansion (Southeast Asia) | Captures rising manufacturing investment in emerging industrial hubs. |
| Service-Based Consumable Agreements | Disrupts traditional distribution channels and reduces end-user working capital. |
| Multi-Process System Development | Narrows the performance gap with dedicated cutting technologies, broadening application scope. |
Research Approach
The analysis maps laser cutters, plasma cutters, waterjet systems, and consumables, each validated through plant engineers, R&D directors, and procurement managers. Primary interviews with manufacturing executives and technical specialists informed market dynamics. Secondary validation drew from industry association reports, company financial filings, and government industrial policy documents. This approach employed both bottom-up market sizing and top-down validation.
Assumptions regarding technological advancements and global manufacturing investment were held fixed across the analysis window. The analytical framework modeled market volumes and values across product type, technology, application, end-user, and regional manufacturing clusters. Compound annual growth rates were derived from historical trends and projected adoption curves. Key forecast inputs included fiber laser adoption rates and aerospace material evolution.
Stress conditions across geopolitical trade tensions and critical component supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect a specific set of macroeconomic and technological assumptions. Material shifts in component supply chain stability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Log Splitters Market
Tools
Vise-Grip Pliers Market
Tools
Mortiser Market
Tools
Hacksaw Blades Market
Tools
Tool Boxes Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Floor Saw Market
Tools
Press Machine Market
Tools
Power Tool Accessories Market
Tools
Metal Cutting Tools Market
Tools
Drywall Tool Market
Tools
Cordless Impact Wrench Market
Tools
Yard Scraper Market
Tools
US Chalk Reel and Line Market
Tools
Riveting Tools Market
Tools
Cordless Long Neck Grinder Market