
 Plasma Cutting Equipment Market | 2026-2036
Plasma Cutting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Cutting Equipment Market Analytics
Shipbuilding demand is pivoting toward automated plasma cutting lines for thick-section hull plates. Hypertherm dominates consumables technology through its intensified R&D spend on precision nozzle engineering. Lincoln Electric anchors North American distribution through its welding-equipment dealer network. ESAB competes in Europe with integrated cutting-automation bundles that combine CNC tables with proprietary gas-delivery systems.
Plasma cutting equipment generates an electrically conductive gas jet—typically compressed air, oxygen, or nitrogen ionized to temperatures exceeding 20,000°C—to melt and expel metal from a kerf. The process handles conductive materials from gauge thickness to several inches, serving fabrication shops, shipyards, and structural steel operations that require speed over laser-grade edge quality. CNC Plasma Cutters capture the largest installed base as job shops automate repetitive cutting patterns across multi-shift operations. High Definition Plasma Systems represent the fastest-expanding product class, narrowing the edge-quality gap with laser systems at substantially lower capital cost per kilowatt. Transferred Arc technology leads in industrial duty cycles above 100 amperes, where electrode longevity and cut consistency determine operating economics.
FDA oversight applies to plasma-cut surgical instruments and implant-grade titanium blanks, forcing equipment vendors to document traceability and surface-integrity protocols. EPA emissions rules in the United States restrict hexavalent chromium exposure from plasma cutting stainless steel, pushing fabricators toward downdraft tables and fume-extraction retrofits. OSHA lockout-tagout standards govern high-voltage plasma power-supply maintenance, shaping service-contract structures and technician-certification requirements. Stakeholders must weigh gas-cost volatility against capital commitments to next-generation hybrid plasma systems that promise nitrogen-oxygen blending flexibility.
Market Dynamics
High-definition plasma systems are compressing the cost-quality gap with laser cutting, forcing capital equipment buyers to recalculate their technology upgrade cycles and supplier relationships.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in transferred-arc systems accelerates manufacturer investment in alternative gas chemistries, creating retrofit demand across European metal fabrication.
- South Korean shipbuilding automation:Hyundai Heavy Industries and DSME deploy automated plasma lines for thick-plate hull sections, standardizing high-definition specifications in maritime newbuild contracts.
- China's metal fabrication clusters:Concentrated demand around Shanghai and Guangdong province drives localized supply chain density, reducing lead times for CNC plasma table procurement.
Market Restraints
- Gas cost volatility:Nitrogen and oxygen price swings compress operating margins for high-volume job shops running multi-shift plasma operations.
- Electrode supply concentration:Precision-machined hafnium-tipped electrodes depend on a narrow supplier base in Germany and Japan, creating single-source vulnerability.
- Laser substitution in thin-gauge:Fiber laser systems below 6kW now match plasma speed on aluminum and mild steel below 6mm, eroding plasma's traditional sweet spot.
Strategic Opportunities
- India's infrastructure buildout:National highway and rail expansion creates underpenetrated demand for portable plasma systems in structural steel field fabrication.
- Hybrid plasma-laser integration:Combined cutting heads that switch between plasma roughing and laser finishing are expanding into premium job shop segments.
- US CHIPS Act reshoring:Semiconductor equipment fabrication incentives pull precision plasma cutting into titanium and nickel-alloy component production for vacuum chambers.
Industry Challenges
- CNC programming talent scarcity:Job shops struggle to hire operators proficient in nesting software and kerf-compensation algorithms for high-definition systems.
- EPA hexavalent chromium compliance:Stainless steel cutting operations face capital-intensive downdraft table retrofits and fume-extraction system upgrades.
- Legacy power supply integration:Older transformer-based plasma systems lack the digital interfaces required for modern factory automation networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Cutting Equipment Market |
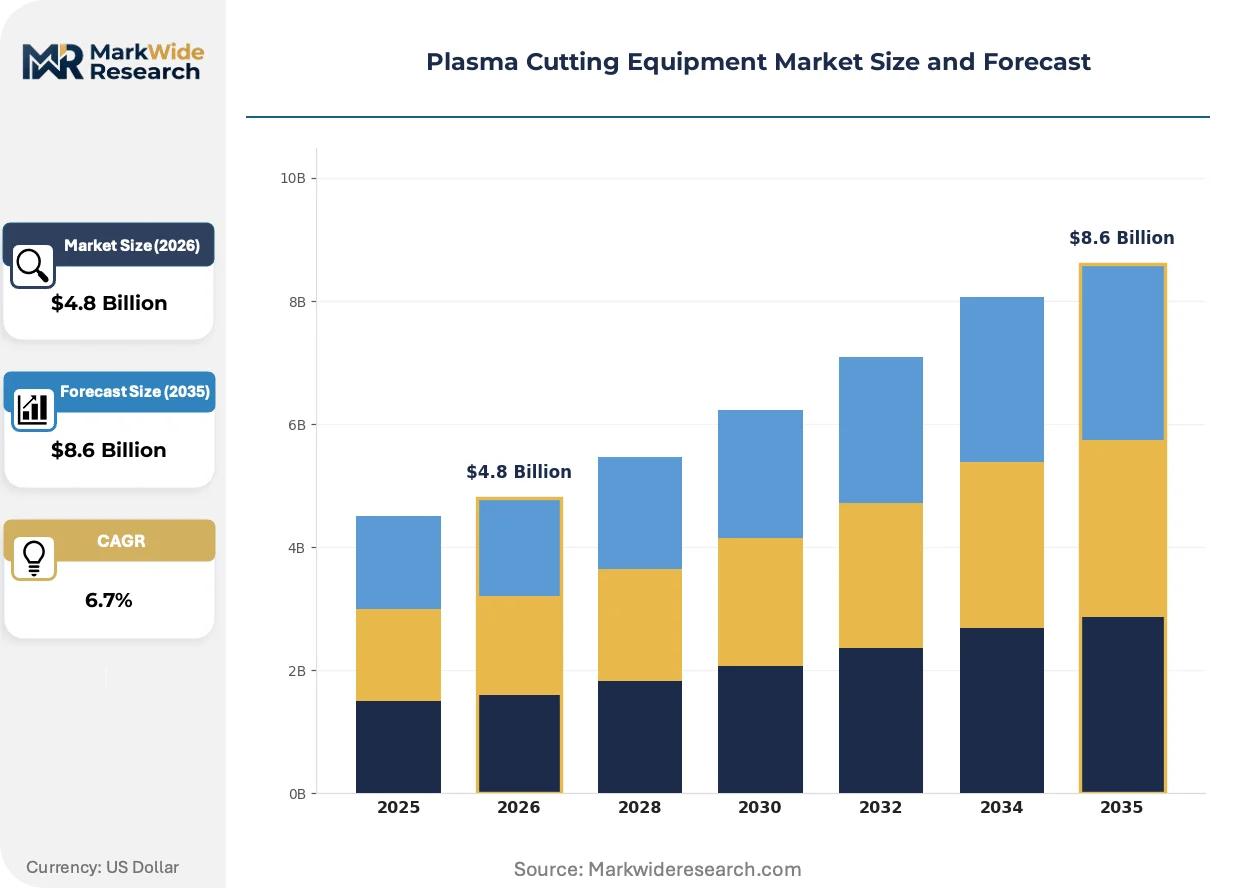
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Cutters, Handheld Cutters, CNC Plasma Cutters, High Definition Plasma Systems Technology: Transferred Arc, Non-Transferred Arc, Dual Gas Technology, Hybrid Plasma Technology End User: Manufacturing, Automotive, Aerospace, Metal Fabrication Application: Sheet Metal Cutting, Pipe Cutting, Plate Cutting, Surface Treatment |
| Companies Covered | Hypertherm, Lincoln Electric, ESAB, Messer Cutting Systems, Thermal Dynamics, Victor Technologies, Celtic, Shandong Buluoer Intelligent Technology, Hubei Meisar CNC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Cutting Equipment Market Evolving Landscape
Plasma cutting equipment is undergoing a convergence of gas chemistry innovation, automation integration, and regulatory-driven equipment refresh cycles that reshape buyer evaluation criteria.
High-definition plasma systems are expanding into precision applications previously reserved for laser cutting. These systems use oxygen-nitrogen gas blending and refined nozzle geometries to achieve square-edge cuts within 2 degrees on carbon steel up to 50mm thick. Automotive stamping die manufacturers in Germany now specify high-definition plasma for rough-machining operations, compressing the capital cost differential against 4kW fiber lasers by approximately 40 percent.
REACH chemical restrictions and the EU F-Gas Regulation are forcing gas delivery system redesigns. Manufacturers must eliminate sulfur hexafluoride and perfluorocarbon tracer gases from plasma arc starting circuits, substituting compressed air ignition sequences. Italian and Spanish fabricators operating transferred-arc systems above 200 amperes face the steepest compliance timelines, with equipment replacement demand concentrated in 2024-2027.
Equipment-as-a-service models are displacing outright purchase in North American job shops. Lincoln Electric and regional distributors now bundle plasma power supplies with consumables subscriptions and predictive maintenance telemetry, unbundling the traditional capital expenditure into operational budgets. This shift is most visible in Texas and Ohio metal fabrication clusters where private-equity-backed rollups standardize fleet procurement across acquired shops.
Plasma Cutting Equipment Market Segmentation
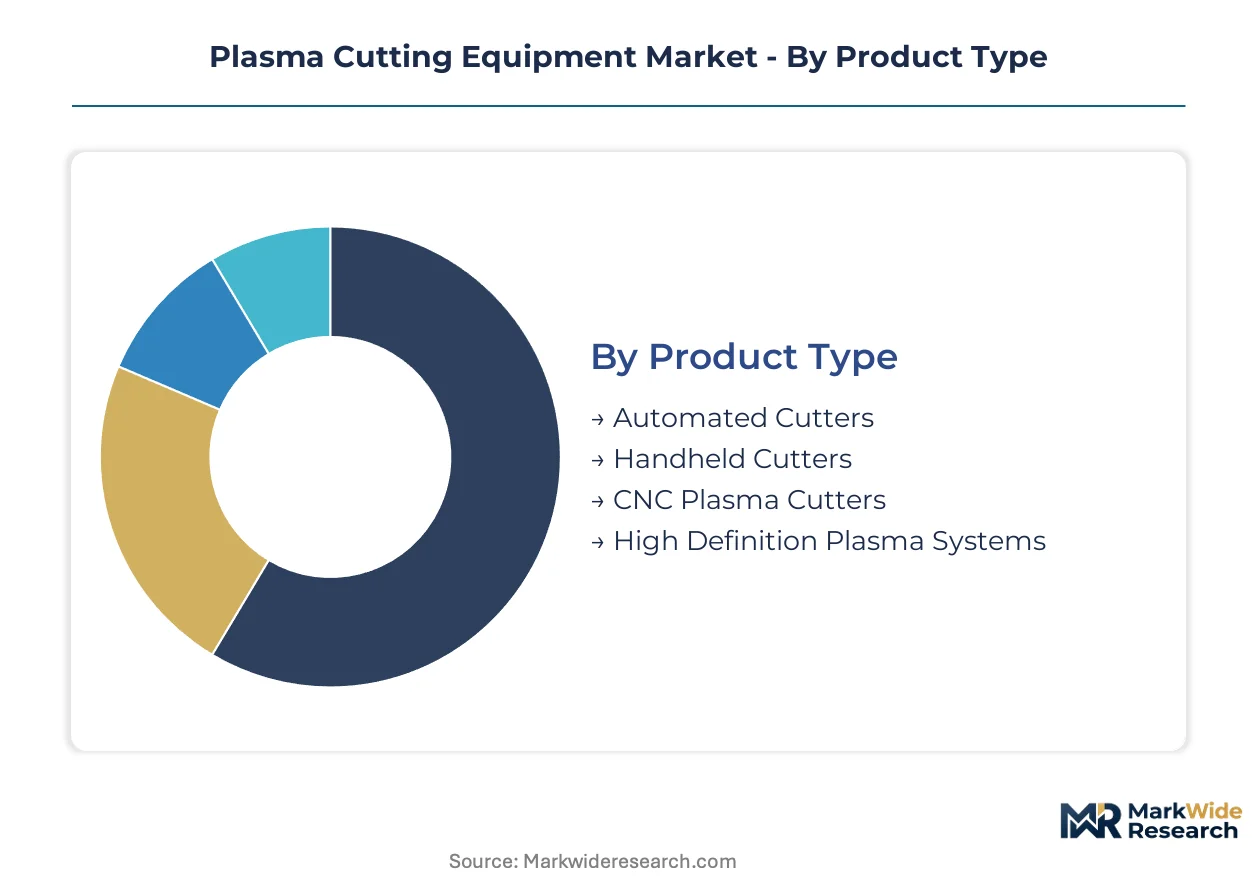
Plasma cutting equipment buyers diverge sharply by automation requirements, material thickness, and integration with factory networks. Segmentation reveals how capital intensity and edge-quality demands split the addressable market across four structural dimensions.
Product Type:
Cost tier separates job shops from integrated manufacturers, with automation level determining payback period and operator skill requirements.
- CNC Plasma Cutters:Computer-numerical control tables automate repetitive cutting patterns across multi-shift operations. Demand concentrates in China's metal fabrication clusters around Shanghai and Guangdong province, where localized supply chain density reduces procurement lead times for mid-sized job shops.
- High Definition Plasma Systems:Oxygen-nitrogen gas blending and refined nozzle geometries achieve square-edge cuts within 2 degrees on carbon steel up to 50mm thick. Automotive stamping die manufacturers in Germany specify these systems for rough-machining operations, compressing capital cost differential against fiber lasers.
- Automated Cutters:Robotic integration serves high-volume production lines with minimal operator intervention.
- Handheld Cutters:Portable units target field fabrication and maintenance operations with lower capital barriers.
CNC Plasma Cutters lead volumes today; High Definition Plasma Systems are climbing the fastest.
Technology:
Application severity—duty cycle, amperage range, and gas chemistry flexibility—drives technology selection in heavy fabrication versus light-gauge operations.
- Transferred Arc:Industrial duty cycles above 100 amperes demand electrode longevity and cut consistency. South Korean shipbuilders at Hyundai Heavy Industries and DSME deploy transferred-arc systems for thick-plate hull sections, standardizing high-definition specifications in maritime newbuild contracts.
- Hybrid Plasma Technology:Combined cutting heads switch between plasma roughing and laser finishing, expanding into premium job shop segments. US semiconductor equipment fabrication under the CHIPS Act pulls hybrid systems into titanium and nickel-alloy component production for vacuum chambers.
- Non-Transferred Arc:Lower-amperage plasma generation suits light-gauge cutting and surface treatment applications.
- Dual Gas Technology:Nitrogen-oxygen blending flexibility helps fabricators hedge against gas cost volatility in multi-shift operations.
Transferred Arc dominates installed base; Hybrid Plasma Technology shows steepest expansion trajectory.
End User:
Volume scale and material mix differentiate buyers, with aerospace and automotive imposing traceability requirements absent in general fabrication.
- Metal Fabrication:Job shops process mixed material portfolios from gauge thickness to several inches, prioritizing speed over laser-grade edge quality. Texas and Ohio clusters see equipment-as-a-service models displacing outright purchase as private-equity-backed rollups standardize fleet procurement.
- Automotive:Stamping die manufacturers and frame producers balance capital cost against edge quality for downstream welding operations.
- Manufacturing:General industrial applications span machinery frames, material handling equipment, and agricultural implements.
- Aerospace:Titanium and nickel-alloy cutting for structural components demands documented traceability and surface-integrity protocols under FDA oversight for surgical instruments and implant-grade blanks.
Metal Fabrication anchors volume; Aerospace commands premium pricing tiers.
Application:
Geometry complexity—flat sheet versus cylindrical pipe versus thick plate—determines table configuration and gas delivery system design.
- Plate Cutting:Thick-section processing from 25mm to 150mm dominates shipyard and structural steel operations. EU F-Gas Regulation compliance timelines concentrate equipment replacement demand in Italian and Spanish fabricators running transferred-arc systems above 200 amperes.
- Sheet Metal Cutting:Thin-gauge operations below 6mm face fiber laser substitution on aluminum and mild steel, eroding plasma's traditional speed advantage.
- Pipe Cutting:Cylindrical geometry requires rotary axis integration and specialized nesting software.
- Surface Treatment:Plasma arc gouging and texturing serve repair and coating preparation applications.
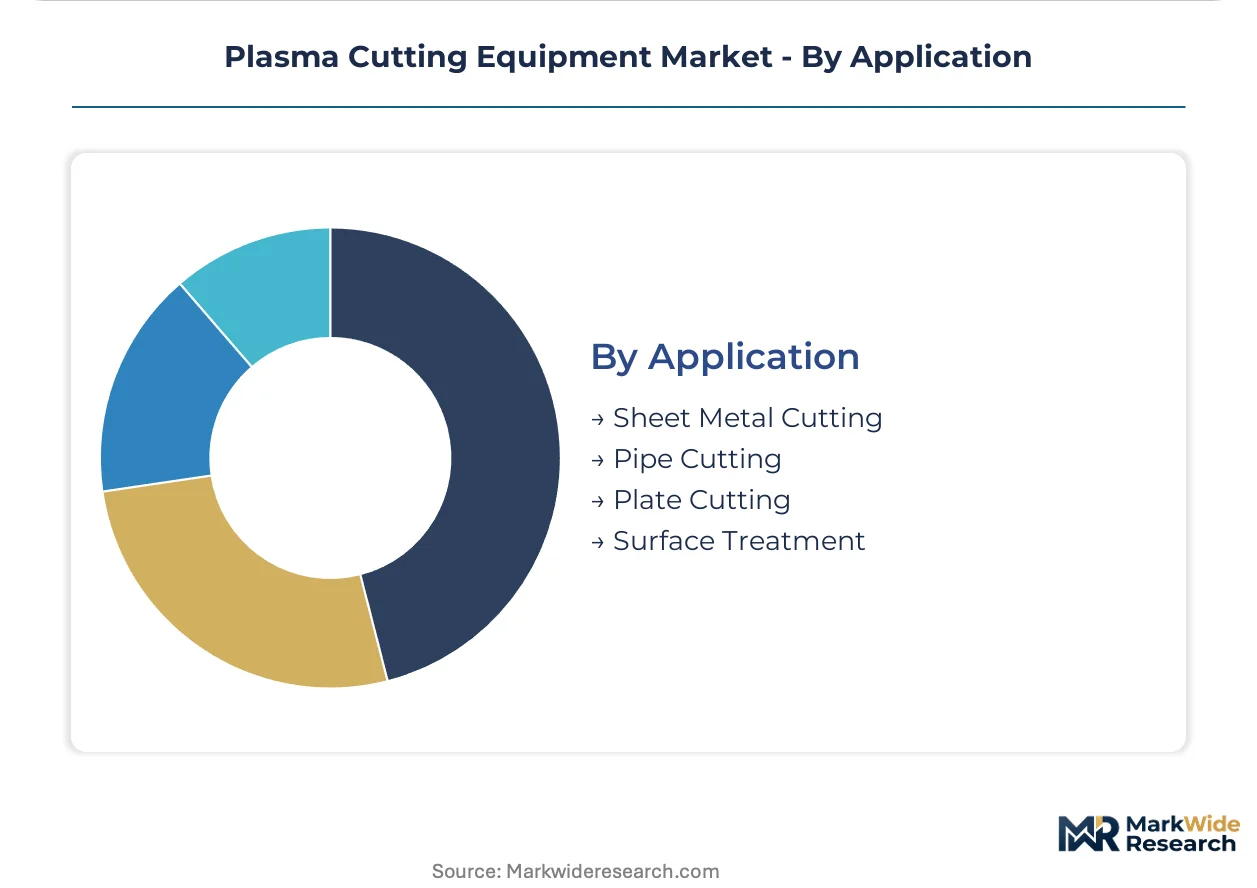
Plate Cutting holds largest share; Pipe Cutting gains from infrastructure buildout in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting plasma equipment procurement toward jurisdictions with lower compliance costs for transferred-arc systems. Fabricators in South Korea and China exploit cost-of-compliance gaps against European rivals facing accelerated F-Gas phaseout timelines.
South Korea
Hyundai Heavy Industries and DSME drive demand for automated high-definition plasma lines in thick-plate hull construction. The Ministry of Trade, Industry and Energy supports smart shipbuilding initiatives that standardize precision cutting specifications. Busan-Ulsan shipyards concentrate procurement of transferred-arc systems above 200 amperes for maritime newbuild contracts.
China
Metal fabrication clusters around Shanghai and Guangdong province generate concentrated CNC plasma table demand. The Ministry of Ecology and Environment enforces dual carbon goals that push fabricators toward energy-efficient power supplies. Localized supply chain density in Jiangsu and Zhejiang provinces reduces procurement lead times for mid-sized job shops.
Germany
Automotive stamping die manufacturers specify high-definition plasma for rough-machining operations. The ECHA REACH framework restricts chemical inputs in gas delivery systems, forcing equipment redesigns. Bavarian and Baden-Württemberg industrial zones anchor precision cutting demand from machinery and automotive tier-one suppliers.
United States
CHIPS Act reshoring incentives pull precision plasma cutting into titanium component production for semiconductor vacuum chambers. EPA hexavalent chromium rules mandate downdraft table retrofits for stainless steel fabricators. Texas and Ohio metal fabrication clusters see equipment-as-a-service models displace outright capital purchases.
India
National highway and rail expansion creates underpenetrated demand for portable plasma systems in structural steel field fabrication. The Bureau of Indian Standards enforces equipment certification for infrastructure project eligibility. Maharashtra and Gujarat infrastructure corridors concentrate procurement of handheld cutters for on-site fabrication.
Plasma Cutting Equipment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents bundle consumables subscriptions with power supply hardware. The vendor base splits between integrated welding-equipment conglomerates and specialized plasma technology houses. Three archetypes emerge: precision consumables engineers, full-line welding distributors, and automation-integrated cutting specialists. M&A activity and geographic expansion through dealer network acquisitions represent the primary competitive vectors.
Among North American welding-equipment conglomerates, Lincoln Electric anchors distribution density through captive dealer networks. Hypertherm occupies a position as the precision consumables archetype, intensifying R&D focus on nozzle engineering. ESAB exemplifies the European automation-integrated model, bundling CNC tables with proprietary gas-delivery systems. These three represent distinct strategic postures without overlapping competitive territory.
| Leading Market Players |
|---|
| Hypertherm |
| Lincoln Electric |
| ESAB |
| Messer Cutting Systems |
| Thermal Dynamics |
| Victor Technologies |
| Celtic |
| Shandong Buluoer Intelligent Technology |
| Hubei Meisar CNC Technology |
| Others |
Value Network & Pricing Analysis
South Korean shipbuilders at Hyundai Heavy Industries and DSME anchor procurement volumes for transferred-arc systems above 200 amperes, compressing vendor pricing power into long-term service contracts that bundle consumables with predictive maintenance telemetry.
Pricing Analysis
Distributor margins in North American job shops absorb 12-18 points before equipment-as-a-service models reach end buyers. Three-tier pricing structure across premium high-definition systems, standard CNC tables, and economy portable units separates automation-integrated bundles from bare power supplies. Cost compression in consumables subscriptions is intensifying because Lincoln Electric and regional distributors unbundle capital expenditure into operational budgets. Metal fabrication job shops running multi-shift operations exhibit highest price sensitivity; aerospace titanium processors show lowest.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang provinces limit expansion of precision nozzle machining capacity for hafnium-tipped electrodes. Manufacturing concentrates in China, Germany, and Japan for CNC table fabrication, power supply assembly, and consumables production respectively. Electrode supply draws from a narrow supplier base in Germany and Japan, creating single-source vulnerability. Distribution runs through captive welding-equipment dealer networks in North America and direct OEM relationships in Asian shipbuilding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
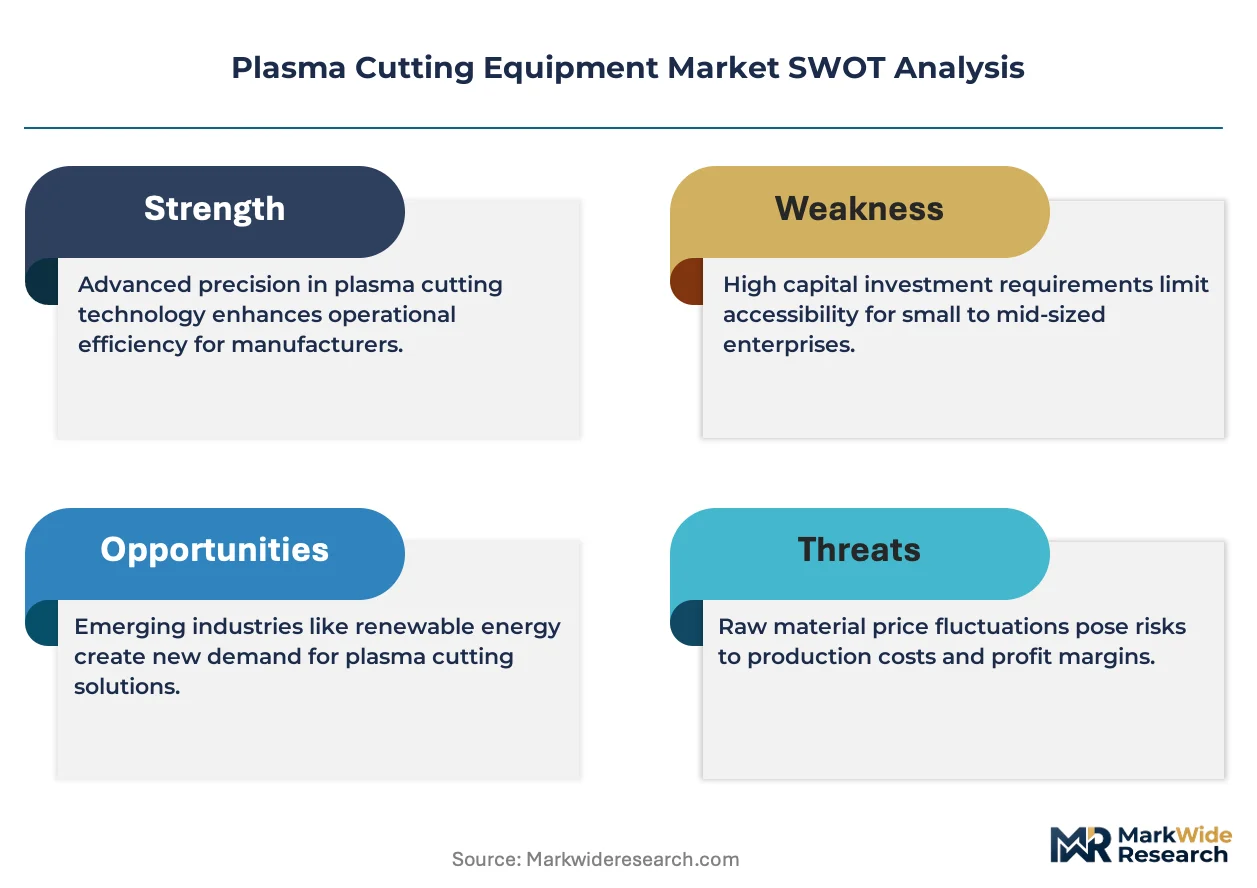
The plasma cutting equipment market represents a late-cycle quality story as automotive stamping die manufacturers in Germany pivot rough-machining operations toward high-definition specifications that narrow the edge-quality gap with fiber lasers.
For Market Incumbents: To counter fiber laser substitution below 6kW on aluminum and mild steel under 6mm, deepen consumables engineering capabilities through intensified R&D spend on precision nozzle geometries and secure captive electrode supply through backward integration into hafnium sourcing channels. For New Entrants and Emerging Players: Begin with India's national highway and rail expansion corridors, where underpenetrated demand for portable plasma systems in structural steel field fabrication offers white-space access without competing against entrenched equipment-as-a-service bundles. Target handheld cutter procurement through Bureau of Indian Standards certification pathways. For Investors and Strategic Acquirers: Welding-equipment conglomerates are the most active acquirer in this space, seeking consumables technology houses that complement captive distribution density. Five-to-ten year viability hinges on hybrid plasma-laser integration capabilities. Watch for inflection when semiconductor equipment fabricators under CHIPS Act incentives specify titanium cutting tolerances that force precision plasma specification.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Subscription Bundling | Lincoln Electric unbundles capital expenditure into operational budgets across Texas and Ohio fabrication clusters. |
| Hybrid Plasma-Laser Integration | Combined cutting heads capture premium job shop segments and CHIPS Act semiconductor equipment fabrication. |
| Alternative Gas Chemistry R&D | EU F-Gas Regulation compliance drives redesign of transferred-arc starting circuits in Italian and Spanish fabricators. |
| Predictive Maintenance Telemetry | Equipment-as-a-service models standardize fleet procurement across private-equity-backed job shop rollups. |
| Precision Nozzle Engineering Investment | Hypertherm intensifies R&D focus to defend edge-quality positioning against fiber laser encroachment. |
Research Methodology
Direct dialogue with plant engineers at metal fabrication job shops, procurement leads at South Korean shipbuilders, aftermarket service heads at welding-equipment distributors, and CNC programming specialists grounded qualitative findings in operational reality. Secondary validation drew from customs trade data on plasma power supply imports, SEC 10-K filings of welding-equipment conglomerates, and shipyard newbuild contract specifications. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmented outputs reflect equipment type, technology architecture, end-use vertical, and application geometry modeled throughout the forecast period. CAGRs derived from historical procurement patterns, replacement cycle analysis, and regulatory-driven equipment refresh timelines. Forecast inputs incorporated EU F-Gas Regulation compliance schedules, CHIPS Act reshoring incentives, and gas cost volatility indices.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting hafnium electrode trade flows, breakthrough fiber laser cost curves below 4kW, and unanticipated EPA enforcement escalations on hexavalent chromium exposure. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Press Brakes Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Spray Washer Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market