

Cordless Long Neck Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Long Neck Grinder Market Insights
Metal fabrication shops is collapsing the historical dominance of generalist construction contractors in cordless long neck grinder procurement. Bosch leverages its brushless motor R&D pipeline to sustain technology leadership in extended-reach applications. Makita anchors Asia-Pacific manufacturing scale with integrated battery platform compatibility across its grinder portfolio. Milwaukee Tool differentiates through proprietary battery architecture that controls channel positioning in North American vehicle maintenance centers.
A cordless long neck grinder is a handheld, battery-powered abrasive finishing tool with an elongated spindle housing that permits access to recessed cavities, internal weld seams, and confined structural geometries. These tools typically operate at 8,000–12,000 RPM with disc diameters of 50–125 mm, serving primary industrial purpose in deburring, surface preparation, and precision material removal where conventional angle grinders cannot reach. Brushless motor configurations now lead the technology dimension by eliminating commutator wear and extending runtime per charge, while lithium-ion battery platforms represent the fastest-growing power source category as cell energy density improves and nickel-cadmium inventories phase out. Metal fabrication remains the mature, high-volume application segment, whereas marine maintenance and HVAC servicing concentrate margin pools due to specialized access requirements and lower price sensitivity among maintenance contractors.
OSHA respiratory protection standards and EPA hazardous waste disposal rules shape product design requirements for dust extraction integration and sealed battery compartments in the US market. CE marking under the EU Machinery Directive and REACH substance restrictions govern motor insulation materials and abrasive disc bonding agents for European market access. Stakeholders must monitor evolving lithium-ion transport regulations and battery passport traceability mandates as these frameworks increasingly determine cross-border market eligibility and aftermarket service economics.
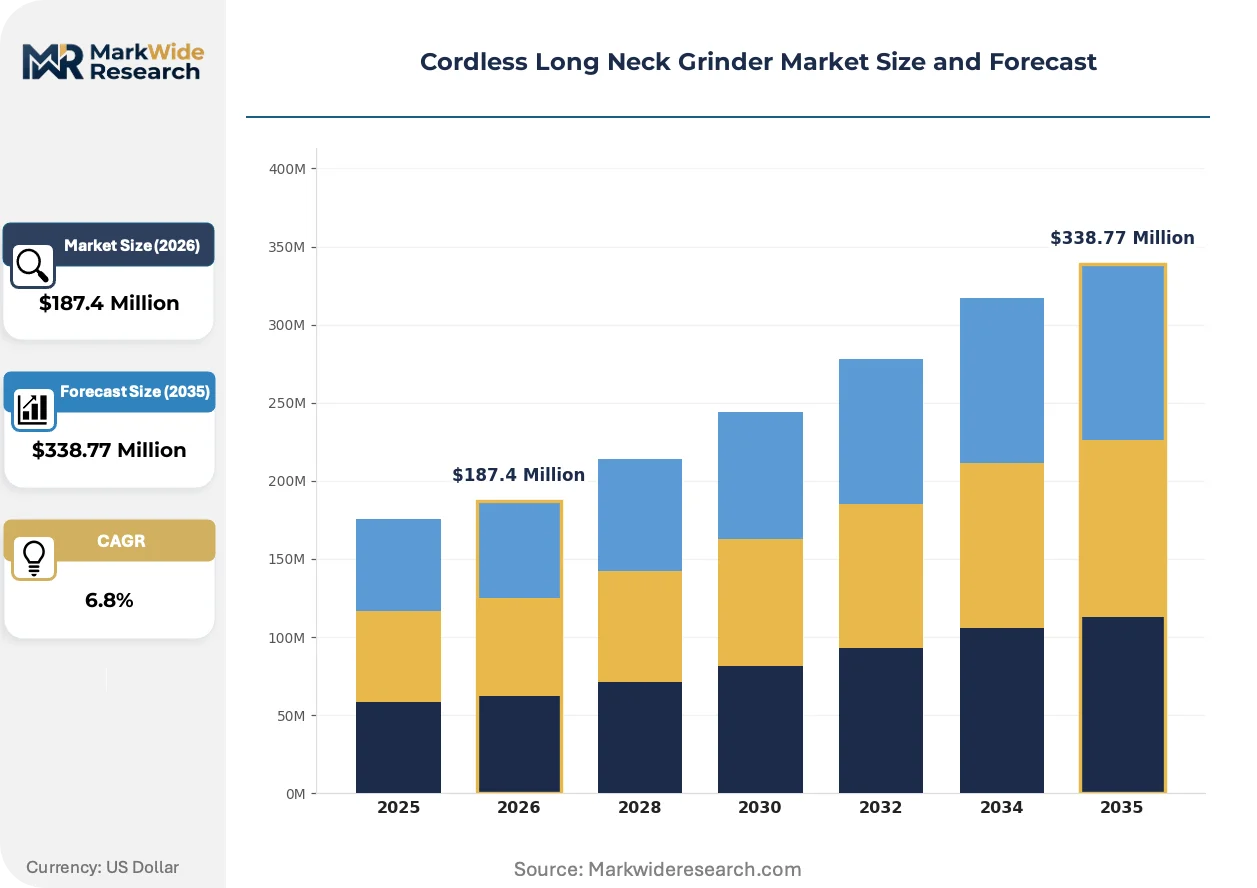
Market Dynamics
Brushless motor architectures are compressing replacement cycles across professional-grade cordless long neck grinders, forcing incumbents to accelerate R&D spend while eroding margins on legacy brushed-motor inventories still held by distributors.
Growth Catalysts
- OSHA silica exposure limits:Fabrication shops in the US face mandatory dust extraction integration, driving replacement of unventilated pneumatic tools with sealed battery-powered alternatives that support onboard vacuum connectivity.
- Lithium-ion cell energy density improvements:Automotive repair chains now specify cordless long neck grinders for underbody work previously reserved for corded equipment, eliminating trip hazards and power access constraints.
- German metalworking cluster concentration:Stuttgart and Dortmund host dense networks of automotive Tier-1 suppliers where compact grinding tools dominate preventive maintenance protocols.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack costs fluctuate with commodity markets, constraining OEM pricing flexibility and compressing gross margins on entry-level grinder SKUs.
- Single-source dependency for rare-earth magnets:Neodymium supply concentrates in Chinese processing facilities, exposing brushless motor production to export restriction risks and forced stockpiling costs.
- Compressed air infrastructure persistence:Legacy pneumatic tool investments in established fabrication shops create switching friction against full cordless conversion, particularly in high-volume grinding stations.
Strategic Opportunities
- Marine maintenance yards in Hamburg and Rotterdam:Specialized access requirements for hull repair and tank cleaning drive premium pricing tolerance for extended-reach cordless tools with sealed housings.
- EU battery passport traceability mandates:Early compliance creates service revenue streams through certified refurbishment programs and second-life battery diagnostics.
- Brushless motor and IoT sensor convergence:Real-time vibration monitoring and predictive maintenance alerts differentiate professional-grade offerings in fleet-managed workshop environments.
Industry Challenges
- Certified repair technician scarcity:Complex brushless motor diagnostics and sealed battery compartment servicing require specialized training that vocational programs have not yet standardized.
- Multi-platform battery incompatibility:Proprietary cell architectures across major OEMs fragment fleet standardization efforts, forcing maintenance contractors to maintain redundant charging infrastructure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Long Neck Grinder Market Trends and Innovations
Product architecture is fragmenting into modular subsystems that permit field-swappable components, reshaping how distributors inventory and service professional-grade grinding equipment.
Brushless motor technology is decomposing the traditional trade-off between runtime and tool weight in extended-reach applications. Marine maintenance contractors in Northern European ports now specify these configurations for confined-space hull preparation, eliminating the performance gap that previously favored corded alternatives. The elimination of commutator wear is compressing total cost-of-ownership calculations and accelerating replacement of brushed-motor inventories in high-utilization settings.
REACH substance restrictions on hexavalent chromium in abrasive disc bonding agents are forcing reformulation of consumables supplied into EU markets. German metal fabrication shops face compliance deadlines that require documented supply chain audits of grinding media. Tool OEMs responding fastest with pre-certified abrasive partnerships are capturing specification authority in automotive repair chain procurement.
Buyer preference is consolidating around integrated battery platforms that span multiple tool categories, compressing standalone grinder purchasing decisions. Fleet managers in US vehicle maintenance centers now specify grinder procurement only where existing battery ecosystems permit interoperability, marginalizing single-tool battery formats. This platform logic is most visible in North American automotive service chains where standardization across wrench, drill, and grinder categories dominates capital planning.
Cordless Long Neck Grinder Market Segmentation
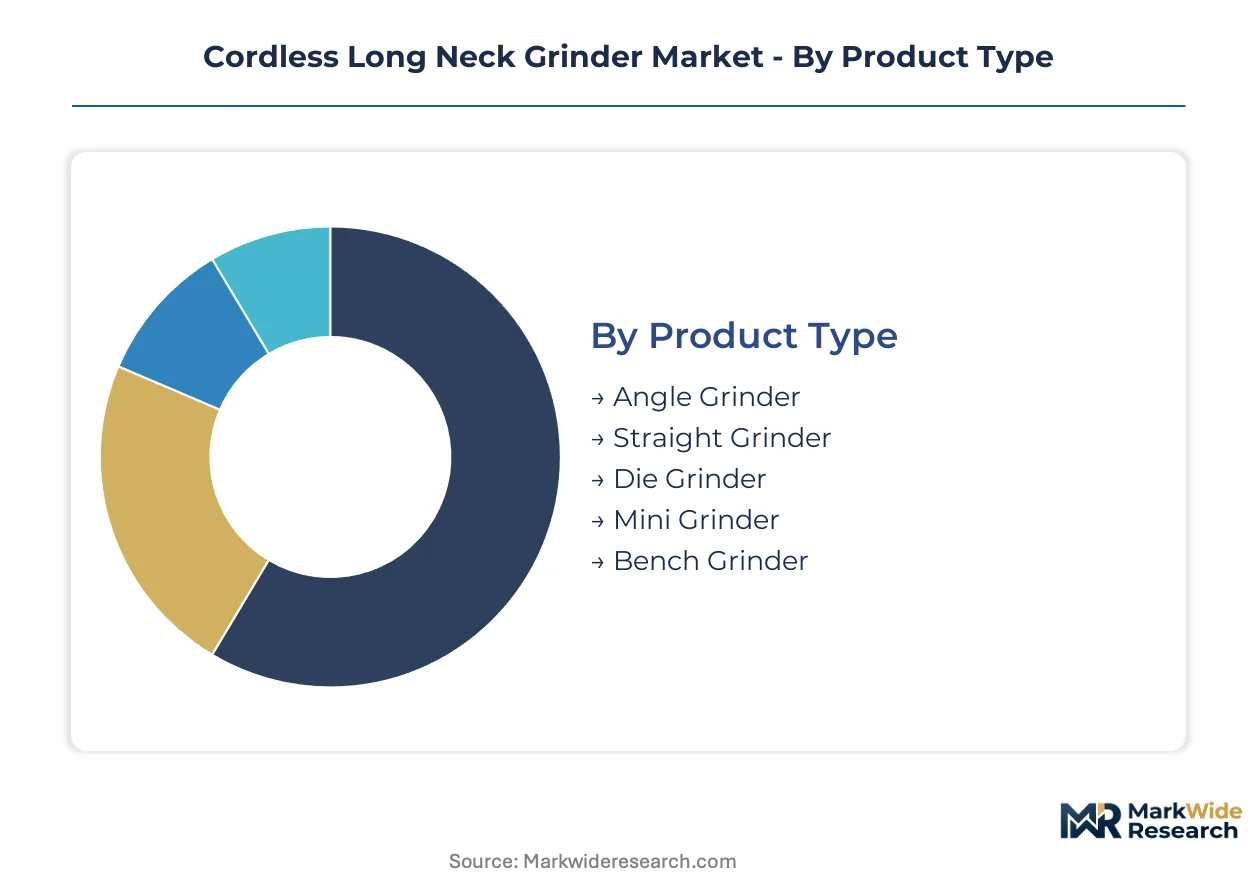
Channel configuration varies sharply across cordless long neck grinder segments. Professional distributors stock brushless configurations for fleet buyers, while retail channels move brushed-motor units to price-sensitive independent contractors.
Product Type:
Industrial supply houses and direct OEM channels dominate volume for extended-reach configurations, with rental fleets absorbing compact variants for seasonal maintenance spikes.
- Angle Grinder:Extended-reach angle configurations with 50–125 mm disc compatibility serve recessed cavity access in automotive underbody work. Stuttgart metal workshops specify these for Tier-1 supplier preventive maintenance protocols where maneuverability constraints eliminate standard angle grinder alternatives.
- Straight Grinder:Inline spindle housings permit deep bore penetration for internal weld seam finishing. Marine maintenance yards in Hamburg and Rotterdam source sealed straight grinder variants for hull tank cleaning operations where confined geometries and corrosion exposure demand extended-reach solutions.
- Die Grinder:Compact collet-based designs target precision deburring in tool and die applications.
- Mini Grinder:Reduced form factor serves HVAC servicing contractors for ductwork access in commercial building retrofits.
- Bench Grinder:Stationary cordless configurations remain niche for mobile fabrication units lacking permanent power infrastructure.
Angle grinder configurations dominate installed base. Straight grinder variants are where expansion concentrates.
Technology:
Cost tier stratification separates professional-grade brushless platforms from entry-level brushed alternatives, with battery chemistry acting as the secondary price discriminator.
- Brushless Motor:Electronically commutated architectures eliminate mechanical wear components and extend runtime per charge. German automotive repair chains now specify brushless long neck grinders exclusively for high-utilization grinding stations where total cost-of-ownership calculations favor upfront premium pricing.
- Lithium-Ion Battery:High energy density cells enable cord-equivalent performance in extended-reach applications. US vehicle maintenance centers are converting underbody work stations to lithium-ion platforms as OSHA silica compliance mandates drive sealed battery-powered alternatives with onboard vacuum connectivity.
- Brushed Motor:Commutator-based designs persist in price-sensitive hobbyist and light-duty segments.
- Nickel-Cadmium Battery:Legacy chemistry inventories phase out across EU markets under REACH substance restrictions.
- Cordless:Battery-powered mobility defines the addressable market for this study.
- Corded:Tethered alternatives retain share in fixed-station high-volume grinding operations.
Brushed motor units retain volume in legacy installed base. Brushless motor configurations are climbing the fastest.
Application:
Margin concentration follows access difficulty, with specialized maintenance segments commanding pricing premiums over standardized fabrication volumes.
- Metal Fabrication:High-volume deburring and surface preparation in structural steel and component manufacturing. Dortmund metalworking clusters drive replacement cycles for compact grinding tools where dense supplier networks standardize on interoperable battery platforms.
- Marine Maintenance:Hull repair and tank cleaning operations in Northern European ports. Specialized access requirements and corrosion-resistant housing specifications create pricing tolerance that compresses price elasticity among maintenance contractors.
- Automotive Repair:Underbody and frame rail work in vehicle service centers.
- Woodworking:Sculpting and finishing applications in carpentry shops.
- HVAC Servicing:Ductwork modification and sheet metal fitting in commercial building systems.
Metal fabrication anchors volume scale. Marine maintenance concentrates margin expansion.
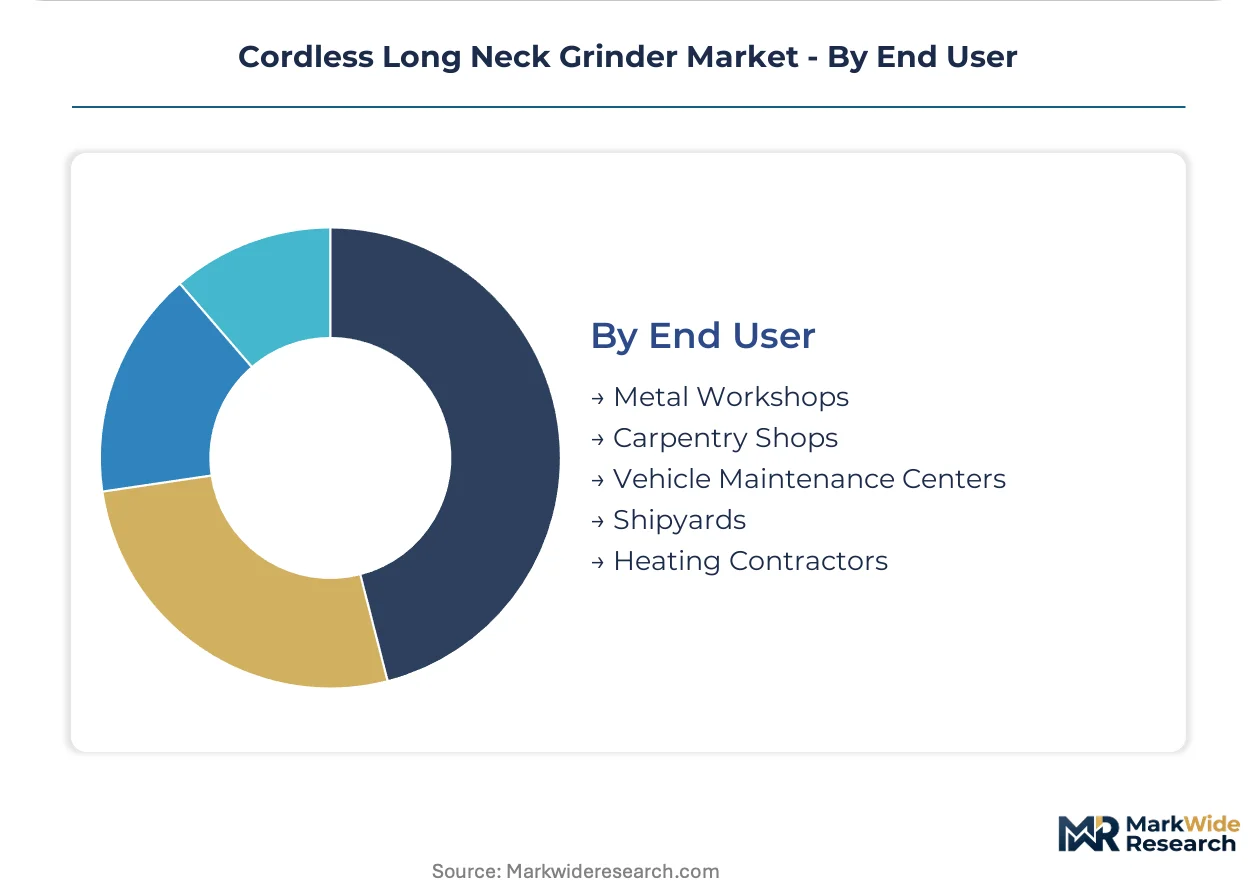
End User:
Customer type determines procurement modality, with fleet-managed workshops consolidating purchasing through integrated battery platform decisions.
- Metal Workshops:Independent and chain-affiliated fabrication operations with high tool utilization rates. German automotive Tier-1 supplier networks in Stuttgart standardize cordless long neck grinder procurement through centralized fleet management protocols that prioritize battery interoperability across grinder, drill, and wrench categories.
- Vehicle Maintenance Centers:US automotive service chains specify grinder procurement contingent on existing battery ecosystem compatibility, marginalizing standalone tool purchases that would fragment charging infrastructure.
- Shipyards:Marine construction and repair facilities with specialized corrosion and access requirements.
- Carpentry Shops:Wood-focused operations with intermittent grinding needs.
- Heating Contractors:HVAC installation and service providers with seasonal demand patterns.
Metal workshops hold the deepest installed base. Vehicle maintenance centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Northern European marine maintenance demand for sealed cordless grinding equipment. Germany's dense autobahn network connects Stuttgart metalworking clusters to Dortmund fabrication hubs. The US Interstate highway system enables just-in-time tool distribution to vehicle maintenance centers across the Midwest and Southeast.
Germany
Automotive Tier-1 supplier networks in Stuttgart drive specification authority for brushless cordless long neck grinders in preventive maintenance protocols. CE marking under the EU Machinery Directive and REACH substance restrictions govern motor insulation materials and abrasive disc bonding agents for market access. Dortmund metalworking clusters standardize procurement through centralized fleet management prioritizing battery interoperability.
United States
OSHA silica exposure limits mandate dust extraction integration, forcing replacement of unventilated pneumatic tools with sealed battery-powered alternatives. Vehicle maintenance centers in Michigan and Ohio convert underbody work stations to lithium-ion platforms as compliance deadlines approach. The Southeast automotive corridor from Tennessee to South Carolina concentrates demand from regional repair chain consolidation.
China
Shanghai port infrastructure supports export manufacturing of brushless motor components for global OEM supply chains. MIIT industrial equipment standards and GB certification requirements shape domestic product specifications. Pearl River Delta fabrication clusters absorb compact grinder volumes for electronics manufacturing and precision metalworking applications.
Japan
Shipbuilding maintenance yards in Nagasaki and Kure specify corrosion-resistant extended-reach tools for hull tank cleaning operations. METI energy efficiency guidelines influence brushless motor adoption in professional-grade equipment. Osaka-Kobe manufacturing belt concentrates precision grinding demand from tool and die workshops serving automotive component suppliers.
Netherlands
Rotterdam marine maintenance contractors command premium pricing for sealed housings in confined-space hull preparation. ECHA chemical substance regulations under REACH compliance frameworks determine abrasive consumable formulations. Amsterdam-Schiphol logistics hub enables rapid spare parts distribution across Benelux fabrication networks.
Cordless Long Neck Grinder Market Competitive Landscape
Concentration sits with diversified power tool conglomerates holding integrated battery platform ecosystems. The vendor base spans three tiers: premium professional-grade specialists, mid-market platform players, and entry-level price competitors. German and Japanese engineering-intensive archetypes dominate brushless motor technology leadership. North American brands anchor fleet standardization through proprietary battery architectures. Competitive moves center on platform interoperability battles and certified refurbishment program expansion.
Among diversified industrial equipment manufacturers, Bosch, Makita, and Milwaukee Tool exemplify distinct strategic positioning archetypes. Bosch represents German engineering-intensive R&D leadership in extended-reach applications. Makita anchors Asia-Pacific manufacturing scale with integrated battery platform compatibility. Milwaukee Tool occupies the proprietary ecosystem tier controlling channel positioning in North American vehicle maintenance centers.
| Leading Market Players |
|---|
| Bosch |
| Makita |
| Milwaukee Tool |
| DeWalt |
| Metabo |
| Hilti |
| Festool |
| Einhell |
| PROXXON |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Machinery Directive gates both supply qualification and price differentiation in European cordless long neck grinder markets, forcing OEMs to absorb certification costs for motor insulation materials while capturing premium positioning through documented REACH compliance for abrasive disc bonding agents. Battery passport traceability mandates now layer additional qualification barriers that simultaneously compress margin pools on entry-level SKUs and expand service revenue opportunities for certified refurbishment programs.
Pricing Analysis
Volume-discount tiering structures separate fleet-managed automotive repair chains from independent metal fabrication shops, with German Tier-1 supplier networks commanding 15-20% unit price reductions on brushless platform commitments above 500 units annually. Price differentiation centers on battery platform interoperability and dust extraction certification grade, with OSHA-compliant sealed housings carrying measurable premiums over unventilated alternatives. Pricing pressure stems from cobalt and lithium carbonate commodity volatility, which constrains OEM flexibility on entry-level grinder SKUs. Independent contractors exhibit highest price sensitivity, while marine maintenance contractors in Rotterdam and Hamburg demonstrate lowest elasticity due to specialized access requirements.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and Red Sea container rerouting are elevating landed costs for brushless motor components sourced from Pearl River Delta manufacturing clusters. Neodymium rare-earth magnet processing concentrates in Chinese facilities, while lithium-ion cell production clusters in South Korea and Japan. Raw material dependencies include cobalt cathode formulations, copper motor windings, and aluminum housing extrusions. Single-source vulnerability in rare-earth magnet supply exposes brushless motor production to export restriction risks. Distribution runs through industrial supply houses and direct OEM channels for professional-grade configurations, with retail channels absorbing price-sensitive hobbyist volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless long neck grinder markets defend through regulatory entrenchment, where CE marking and OSHA silica compliance create switching costs that lock fleet buyers into certified platform ecosystems and marginalize unqualified competitors.
For Market Incumbents: Compound platform interoperability advantages by deepening backward integration into brushless motor R&D and securing exclusive abrasive disc partnerships with REACH-certified suppliers. Battery passport compliance investments will preempt service revenue capture as EU mandates phase in. Prioritize channel control in Stuttgart and Dortmund metalworking clusters where centralized fleet management standardizes procurement across grinder, drill, and wrench categories. For New Entrants and Emerging Players: Lead with modular field-swappable subsystems targeting marine maintenance yards in Hamburg and Rotterdam, where specialized corrosion-resistant housing requirements and confined-space access needs create specification windows outside incumbent platform dominance. HVAC servicing contractors represent the most penetrable segment due to seasonal demand patterns and lower utilization rates that reduce total-cost-of-ownership sensitivity. Pursue direct rental fleet partnerships to bypass established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across brushless motor manufacturing as neodymium magnet stockpiling and lithium-ion cell certification requirements elevate working capital needs. Long-term viability favors vertically integrated specialists with captive battery platform ecosystems and certified refurbishment infrastructure. Acquisition targets should demonstrate established CE marking pathways and REACH-compliant abrasive supply chain audits. Monitor EU battery passport implementation timelines as the critical inflection signal for service revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor R&D Expansion | Eliminates commutator wear and extends runtime per charge in high-utilization grinding stations. |
| REACH-Compliant Abrasive Partnerships | Captures specification authority in German automotive repair chain procurement ahead of compliance deadlines. |
| Battery Passport Compliance Investment | Creates certified refurbishment revenue streams and second-life battery diagnostics capabilities. |
| Marine Maintenance Channel Development | Accesses premium pricing tolerance in Rotterdam and Hamburg hull repair operations. |
| IoT Sensor Integration for Predictive Maintenance | Differentiates professional-grade offerings in fleet-managed workshop environments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from diversified industrial equipment manufacturers, and EU regulatory submission databases. Primary interviews encompassed maintenance directors at German automotive Tier-1 suppliers, procurement leads at US vehicle maintenance chains, aftermarket service heads at marine maintenance yards, and plant engineers at Dortmund metal fabrication clusters. Secondary validation drew from OSHA enforcement records, ECHA REACH substance restriction updates, and lithium-ion transport regulation bulletins. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include product architecture (angle, straight, die, mini, bench grinder configurations), motor technology (brushless versus brushed), battery chemistry (lithium-ion versus legacy nickel-cadmium), application vertical (metal fabrication, marine maintenance, automotive repair, HVAC servicing), and end-user procurement modality (fleet-managed versus independent). CAGRs derived from regression analysis of historical replacement cycle data and penetration rate assumptions across the projection horizon. Industry-specific forecast inputs incorporated lithium-ion cell energy density improvement curves and OSHA silica compliance deadline impacts on pneumatic tool replacement demand.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and OSHA respiratory protection standards; material policy shifts would require re-modeling. Commodity price volatility in cobalt and lithium carbonate markets, rare-earth magnet export restriction events, or accelerated battery passport traceability mandates constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.