
 Hacksaw Blades Market | 2026-2036
Hacksaw Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Hacksaw Blades Market Outlook
ISO 9001 quality management certification is redrawing competitive boundaries among hacksaw blade suppliers. Stanley Black & Decker leverages its captive distribution network across North American home-improvement retail to sustain shelf dominance. Bosch competes through in-house metallurgy R&D for bi-metal tooth geometry. Starrett Company anchors its position via precision-ground blade manufacturing for aerospace maintenance depots.
A hacksaw blade is a narrow, toothed metal strip—typically manufactured from high-carbon steel, bi-metal laminates, or carbide-tipped substrates—designed for linear reciprocating cuts in metal, wood, or plastic stock. Tooth pitch ranges from 14 to 32 teeth per inch determine chip clearance and finish quality for specific workpiece materials. Bi-metal blades command the widest application footprint across metal-cutting workshops due to their fatigue resistance. Carbide-tipped variants occupy premium price tiers in aerospace maintenance where superalloy sectioning demands extended edge retention. Carbon steel segments face margin compression from substitution in light-duty home-improvement channels.
OSHA workplace safety standards in the United States mandate blade guard specifications and breakage containment for industrial cutting operations. REACH substance restrictions in Europe limit cobalt and nickel leaching from blade coatings, forcing reformulation of high-speed steel variants. China's SAMR enforces GB hardness testing protocols for imported cutting tools. Stakeholders must monitor evolving alloy substitution timelines and certification lag between regional compliance regimes to align production footprints with diverging material standards.
Market Dynamics
Bi-metal blade fatigue resistance is displacing carbon steel across maintenance-intensive sectors, compressing legacy supplier margins while ISO 9001 certification becomes the non-negotiable threshold for industrial procurement tenders.
Growth Catalysts
- Automotive aftermarket maintenance cycles:Fleet operators in Germany's precision manufacturing belt mandate scheduled blade replacement, creating predictable demand pulses for bi-metal inventory.
- REACH substance compliance:European ECHA reformulation requirements for cobalt-reduced coatings are accelerating alloy substitution R&D in high-speed steel variants.
- Aerospace superalloy sectioning:Carbide-tipped blade adoption in MRO depots is expanding addressable market for premium edge-retention products.
Market Restraints
- Tungsten carbide powder cost volatility:Raw material price swings compress margin stability for carbide-tipped blade producers.
- Carbon steel substitution pressure:Light-duty home-improvement channels are migrating toward bi-metal, stranding legacy production assets.
- GB hardness testing protocol lag:China's SAMR certification timelines delay market entry for imported cutting tools by 4-6 months.
Strategic Opportunities
- India's BIS standardization gap:Domestic blade manufacturers face limited competition from certified imports, creating first-mover advantage for ISO-compliant entrants.
- Online industrial distribution:Specialized MRO platforms are disintermediating traditional wholesale channels for workshop-grade consumables.
- EU Green Deal circularity mandates:Blade take-back and remanufacturing requirements favor suppliers with closed-loop metallurgy capabilities.
Industry Challenges
- Bi-metal lamination technician scarcity:Precision welding expertise for tooth-edge substrates is concentrating among aging workforce cohorts in Solingen and Sheffield.
- Cross-regional certification divergence:OSHA guard specifications, REACH coating limits, and GB hardness protocols create fragmented compliance engineering requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hacksaw Blades Market |
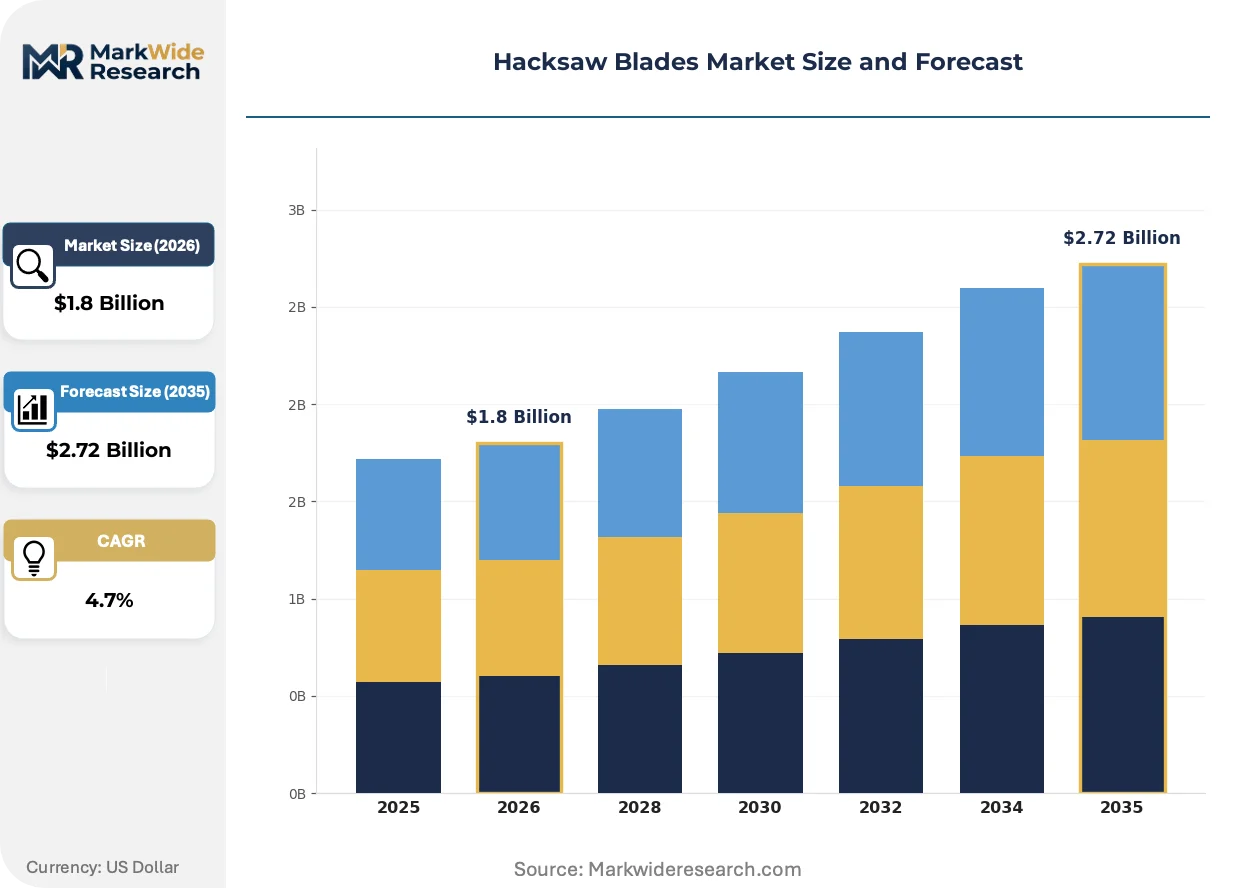
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bi-metal, High-Speed Steel, Carbide-Tipped, Carbon Steel Application: Metal Cutting, Woodworking, Plastic Fabrication, Construction Size: 12 inch, 14 inch, 18 inch, 24 inch End User: Manufacturing, Home Improvement, Automotive, Aerospace |
| Companies Covered | Stanley Black & Decker, Bosch, Irwin Tools, Bahco, Lenox Tools, Makita Corporation, Starrett Company, Techtronic Industries, Apex Tool Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hacksaw Blades Market Strategic Shifts
Material science advances and regulatory stringency are fragmenting blade performance tiers while digital procurement platforms compress traditional distribution hierarchies.
Carbide-tipped tooth geometry is bifurcating the aerospace maintenance segment from general metalworking workshops. Superalloy MRO depots in Toulouse and Wichita demand 40-hour edge retention that bi-metal cannot deliver. This performance gap is compressing mid-tier blade suppliers into commodity positioning.
REACH substance restrictions on cobalt and nickel leaching are forcing reformulation of high-speed steel blade coatings across European supply chains. ECHA enforcement timelines are compressing product development cycles for coating chemistries. German precision manufacturers are responding by qualifying alternative carbide substrates ahead of 2025 compliance deadlines.
Industrial buyers are consolidating blade procurement through integrated MRO platforms that bundle cutting tool categories under single-source contracts. Traditional specialty distributors in the US Midwest are losing share to Amazon Business and Grainger's digital interfaces. This channel shift is most visible among mid-sized job shops in Ohio and Michigan seeking procurement cost transparency.
Hacksaw Blades Market Segmentation
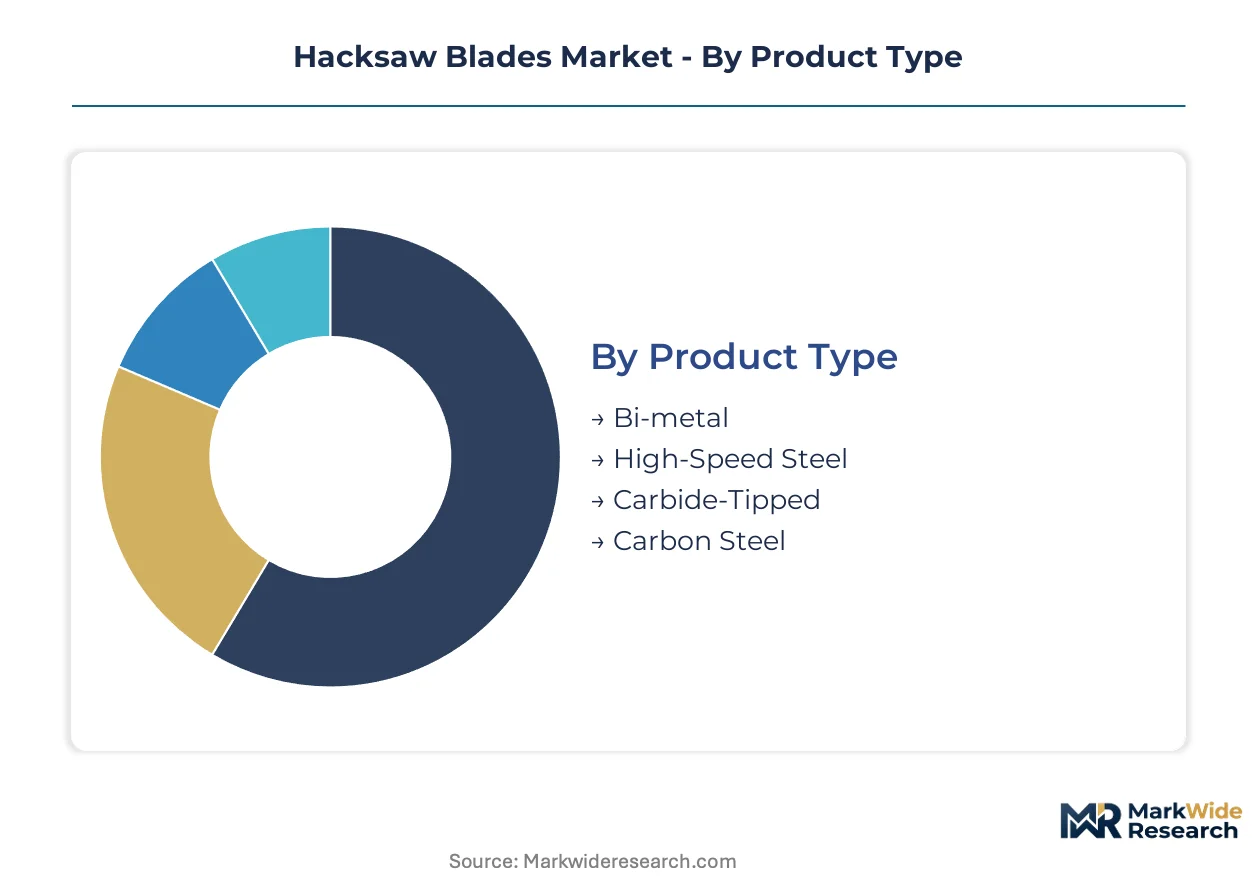
Blade specification tiers determine procurement economics across divergent end-use environments. Material composition and dimensional standards create distinct competitive arenas where certification requirements and performance thresholds reshape supplier positioning.
Product Type:
Bi-metal and carbide-tipped variants dominate export flows into aerospace and precision manufacturing clusters, while carbon steel serves price-sensitive domestic maintenance channels.
- Bi-metal:Laminated high-speed steel teeth bonded to flexible alloy backing deliver fatigue resistance for reciprocating metal-cutting operations. Fleet operators in Germany's precision manufacturing belt mandate scheduled replacement cycles, creating predictable inventory demand for maintenance depots.
- Carbide-Tipped:Tungsten carbide particles sintered onto tooth edges extend edge retention for superalloy sectioning. Aerospace MRO facilities in Wichita and Toulouse specify 40-hour cutting life that bi-metal cannot satisfy, commanding premium positioning.
- High-Speed Steel:Monolithic cobalt-alloy substrates face REACH reformulation pressure for coating chemistry adjustments.
- Carbon Steel:Legacy production for light-duty home-improvement channels experiences margin compression from bi-metal substitution.
Bi-metal holds the largest share; momentum sits with carbide-tipped for premium aerospace applications.
Application:
Metal-cutting specifications concentrate procurement volume, while construction and plastic fabrication segments fragment across regional supplier bases.
- Metal Cutting:Ferrous and non-ferrous stock sectioning demands tooth pitch calibration from 14 to 32 teeth per inch for chip clearance optimization. China's Yangtze River Delta industrial corridor consumes high volumes for machinery fabrication, with SAMR GB hardness protocols filtering import qualification.
- Woodworking:Coarser tooth geometries prioritize material removal speed over finish quality in carpentry workshops.
- Plastic Fabrication:Thermoplastic and composite cutting requires reduced friction coatings to prevent material welding on tooth surfaces.
- Construction:Field-deployed cutting of structural metals and PVC piping channels demand durability under abrasive jobsite conditions.
Metal Cutting commands procurement volume leadership; Plastic Fabrication is climbing the fastest as composite adoption expands.
Size:
Standardized frame compatibility drives specification concentration, with extended lengths serving specialized industrial sectioning requirements.
- 12 inch:Compact frames for confined-space maintenance in automotive underbody repair and HVAC ductwork modification.
- 14 inch:Intermediate length balances reach and rigidity for general metalworking shop floors.
- 18 inch:Extended cutting stroke for structural steel and pipe fabrication in construction environments.
- 24 inch:Maximum reach configurations for deep-section cutting in heavy equipment remanufacturing facilities.
12 inch and 14 inch dimensions dominate unit volume; 24 inch configurations gain share in heavy industrial retrofitting.
End User:
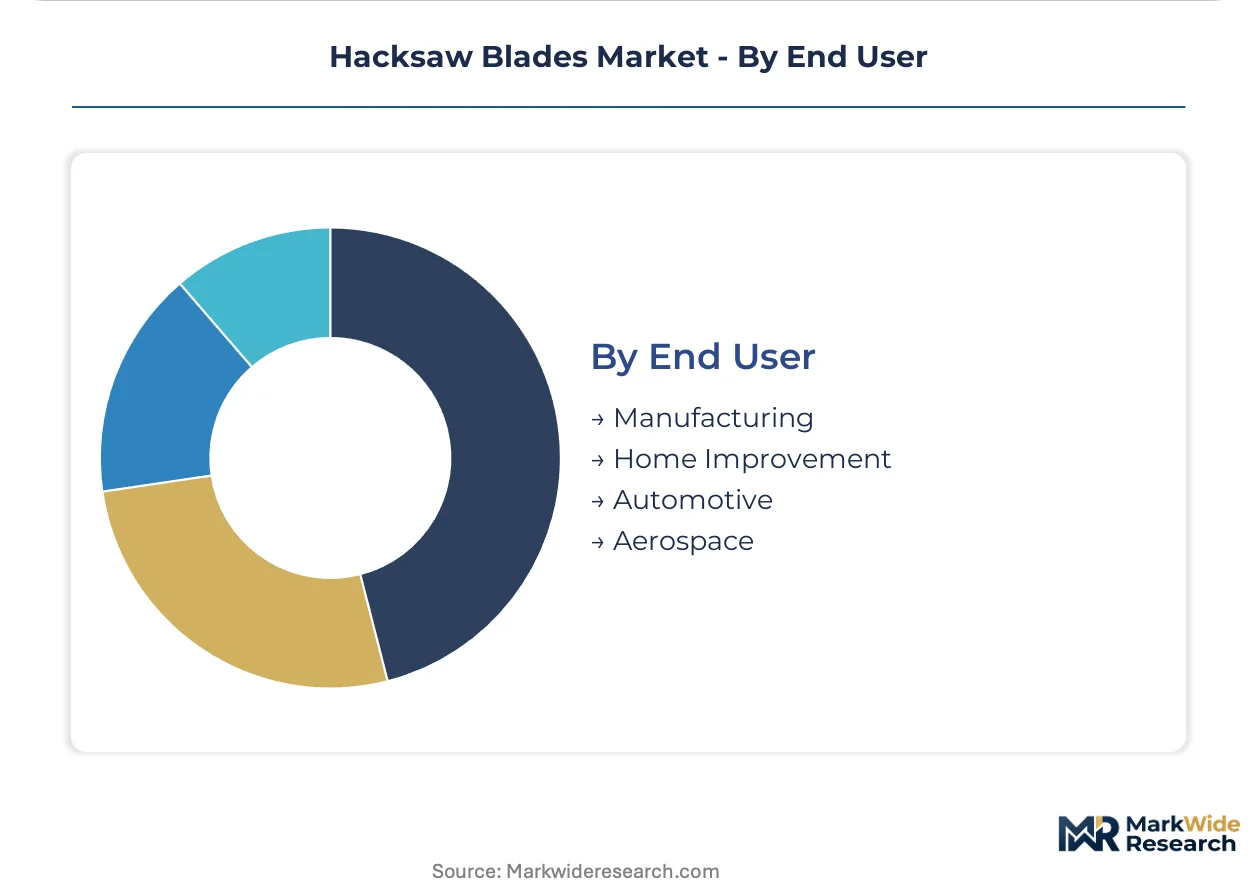
Manufacturing and aerospace procurement consolidates under ISO 9001-qualified suppliers, while home improvement channels fragment across retail distribution tiers.
- Manufacturing:Precision machinery builders and metal fabrication shops specify tooth geometry for production-line reliability. OSHA workplace safety standards in the United States mandate blade guard specifications and breakage containment protocols for industrial cutting floors.
- Aerospace:Superalloy MRO operations in maintenance depots demand carbide-tipped edge retention for titanium and Inconel sectioning. REACH substance restrictions on cobalt leaching force coating reformulation timelines for European-qualified suppliers.
- Automotive:Aftermarket maintenance cycles and OEM assembly line tooling create dual demand streams for blade inventory.
- Home Improvement:Retail shelf positioning through North American home-improvement chains emphasizes price-point accessibility over performance specifications.
Manufacturing absorbs the greatest blade volume; Aerospace exhibits the steepest expansion trajectory as superalloy MRO activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions and SAMR certification protocols are redrawing procurement requirements across major manufacturing economies. Industrial clusters in Germany, China, the United States, Japan, and India concentrate blade demand from automotive aftermarket maintenance and precision metalworking operations.
Germany
Fleet operators in the precision manufacturing belt mandate scheduled blade replacement cycles for bi-metal inventory. ECHA enforcement of cobalt-reduced coating reformulations accelerates alloy substitution R&D timelines ahead of 2025 compliance deadlines. Solingen's heritage metalworking cluster concentrates precision-ground blade production for aerospace maintenance depots.
China
The Yangtze River Delta industrial corridor consumes high volumes for machinery fabrication and metal-cutting operations. SAMR enforces GB hardness testing protocols that delay market entry for imported cutting tools by 4-6 months. Shanghai and Suzhou manufacturing zones filter procurement through domestic certification requirements.
United States
OSHA workplace safety standards mandate blade guard specifications and breakage containment for industrial cutting floors. Home-improvement retail chains sustain shelf dominance through captive distribution networks across North American markets. Ohio and Michigan job shops consolidate procurement through integrated MRO platforms.
Japan
METI industrial standards and JIS certification requirements shape quality thresholds for cutting tool imports. Automotive OEM assembly lines and aftermarket maintenance create dual demand streams for blade inventory. Nagoya's Chubu industrial region concentrates precision machinery builders specifying tooth geometry for production-line reliability.
India
BIS standardization gaps create limited competition from certified imports for domestic blade manufacturers. Maharashtra and Gujarat industrial corridors seek ISO 9001-qualified suppliers for manufacturing procurement tenders. First-mover advantage accrues to ISO-compliant entrants addressing unmet demand in precision metalworking channels.
Hacksaw Blades Market Competitive Environment
Player mix skews toward diversified tool conglomerates with captive distribution networks and specialized metallurgy developers with in-house R&D capabilities. Market structure concentrates around three strategic archetypes: premium-tier precision manufacturers serving aerospace MRO, mid-market bi-metal specialists supplying automotive fleet operators, and mass-market suppliers competing through retail shelf presence. Dominant competitive moves include portfolio diversification into carbide-tipped variants and geographic expansion through digital MRO platform partnerships.
Among diversified tool conglomerates, Stanley Black & Decker and Bosch exemplify contrasting competitive positions. Stanley Black & Decker occupies a position anchored in North American home-improvement retail shelf dominance. Bosch represents the in-house metallurgy R&D archetype with emphasis on bi-metal tooth geometry development. Starrett Company sits within the precision-ground manufacturing tier serving aerospace maintenance specifications.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Bosch |
| Irwin Tools |
| Bahco |
| Lenox Tools |
| Makita Corporation |
| Starrett Company |
| Techtronic Industries |
| Apex Tool Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates at Solingen and Sheffield metallurgy clusters shape both supply concentration and bi-metal blade price floors. High-carbon steel producers in China's Hebei province face margin compression as bi-metal substitution accelerates, forcing legacy capacity into idleness or distressed pricing.
Pricing Analysis
Certification level creates the primary spread across blade procurement tiers. ISO 9001-qualified bi-metal products command substantial premiums from aerospace MRO depots in Wichita and Toulouse, while uncertified carbon steel competes on unit economics in home-improvement retail. REACH cobalt-reduced coating reformulations are intensifying cost compression in European-qualified high-speed steel variants. Fleet operators in Germany's precision manufacturing belt exhibit lowest price sensitivity due to scheduled replacement mandates, whereas Ohio and Michigan job shops consolidating through Amazon Business demonstrate acute procurement cost transparency demands.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion are elevating landed costs for tungsten carbide powder shipments from Chinese suppliers. Bi-metal lamination capacity concentrates in Germany's Solingen heritage cluster, Sheffield's metalworking district, and select Yangtze River Delta facilities near Shanghai. Raw material dependencies span cobalt-alloy substrates from Finnish refiners, high-speed steel billets from Austrian specialty mills, and tungsten carbide particles from Chinese powder metallurgy plants. Single-source vulnerability sits with precision welding technicians for tooth-edge substrate bonding. Distribution runs through Grainger and Amazon Business platforms disintermediating traditional Midwest wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as digital MRO procurement disintermediates legacy distribution hierarchies, creating niche entry points for specialized metallurgy developers and certified regional producers.
For Market Incumbents: Secure captive supply of cobalt-reduced coating chemistries ahead of ECHA enforcement timelines. Backward integration into high-speed steel billet sourcing from Austrian specialty mills mitigates raw material cost volatility. Defend shelf positioning through exclusive home-improvement retail partnerships against bi-metal specialists encroaching from automotive fleet channels. For New Entrants and Emerging Players: Aftermarket blade remanufacturing services represent an underserved layer where incumbents lack closed-loop metallurgy capabilities. India's Maharashtra and Gujarat industrial corridors offer the most penetrable geography given BIS standardization gaps limiting certified import competition. Digital MRO platform partnerships provide the strongest go-to-market angle for ISO-qualified entrants seeking procurement consolidation tailwinds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bi-metal specialists serving automotive fleet operators with scheduled replacement contracts. Five-to-ten year viability favors precision-ground manufacturers with aerospace MRO qualifications over carbon steel legacy producers facing substitution pressure. Watch carbide-tipped blade adoption rates in superalloy sectioning applications as the inflection signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bi-Metal Lamination Capacity Expansion | Captures automotive fleet replacement cycles in Germany's precision manufacturing belt. |
| Cobalt-Reduced Coating Reformulation | Ensures REACH compliance ahead of ECHA enforcement timelines for European supply chains. |
| Digital MRO Platform Partnership | Disintermediates traditional wholesale channels serving Ohio and Michigan job shops. |
| Precision Grinding Capability Investment | Qualifies supplier positioning for aerospace MRO depots in Wichita and Toulouse. |
| Closed-Loop Blade Remanufacturing | Aligns with EU Green Deal circularity mandates favoring metallurgy recovery systems. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with maintenance directors at aerospace MRO facilities, procurement leads at German automotive fleet operators, plant engineers in China's Yangtze River Delta, and aftermarket service heads at North American distribution networks; alongside secondary validation through customs trade data, SEC filings from diversified tool conglomerates, SAMR GB standard documentation, and ECHA substance restriction databases. Bottom-up volume triangulation across blade specification tiers reconciled with top-down market sizing from industrial production indices.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning material composition tiers, tooth pitch specifications, end-use application environments, and regional regulatory clusters. CAGRs derived from elasticity-adjusted demand curves incorporating automotive aftermarket maintenance cycle frequencies and aerospace superalloy sectioning intensity. Forecast inputs included alloy substitution timelines for REACH-compliant coatings and digital procurement platform penetration rates among mid-sized job shops.
Forecasts assume regulatory continuity in REACH substance restrictions, SAMR GB hardness protocols, and OSHA workplace safety standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cutting Equipment Market
Tools
CNC Leather Cutting Machine Market
Tools
Collated Screws Market
Tools
Cutting Tool Inserts Market
Tools
Woodworking Sanders Market
Tools
2D Laser Cutting Machine Market
Tools
Pipe Alignment Clamps Market
Tools
Oxy-Fuel Torches Market
Tools
Ripper Market
Tools
Global Construction Camera Market
Tools
Pneumatic Tools Market
Tools
Cordless Multi Rotary Tools Market
Tools
Bottle Jack Market
Tools
Industrial Ladder Market
Tools
Post Drivers Market
Tools
Key Cutting Machine Market