
 Europe Stump Cutter/Grinder Market | 2026-2036
Europe Stump Cutter/Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stump Cutter/Grinder Market Foresight
European forestry equipment manufacturing capacity is hardening around specialized stump reduction systems. Morbark leverages its Wisconsin-based production footprint to serve Nordic export channels with high-torque hydraulic platforms. FAE Group anchors Italian engineering strength in mulching attachments that integrate with existing carrier vehicles. Vermeer competes through dedicated R&D on compact self-propelled units tailored to narrow European woodland access.
A stump cutter/grinder is a powered machine employing a rotating cutting disc or wheel with carbide-tipped teeth to fracture tree stumps below grade level, typically achieving grinding depths of 30-46 centimeters and producing wood chip residue suitable for site remediation. Its primary commercial purpose is land clearing for construction, agriculture, and reforestation where complete stump extraction prevents regrowth and enables soil preparation. Trailer-mounted units dominate rental fleet deployments across European contractors due to transport flexibility and lower capital commitment. Electric technology segments are gaining fastest among municipalities in urban noise-restricted zones across the Netherlands and Denmark. Diesel platforms still sustain margin pools in remote forestry applications where grid connectivity remains absent.
CE marking requirements under the EU Machinery Directive shape product safety standards for stump grinder guarding systems and operator protection. The EU Green Deal's reforestation targets and national sustainable forest management codes in France and Germany are accelerating replacement of manual stump removal with mechanized solutions. ECHA scrutiny of hydraulic fluid formulations is pressuring manufacturers toward bio-based alternatives. Stakeholders must monitor how evolving EU battery regulations and local noise ordinances reshape powertrain choices across municipal procurement tenders.
Market Dynamics
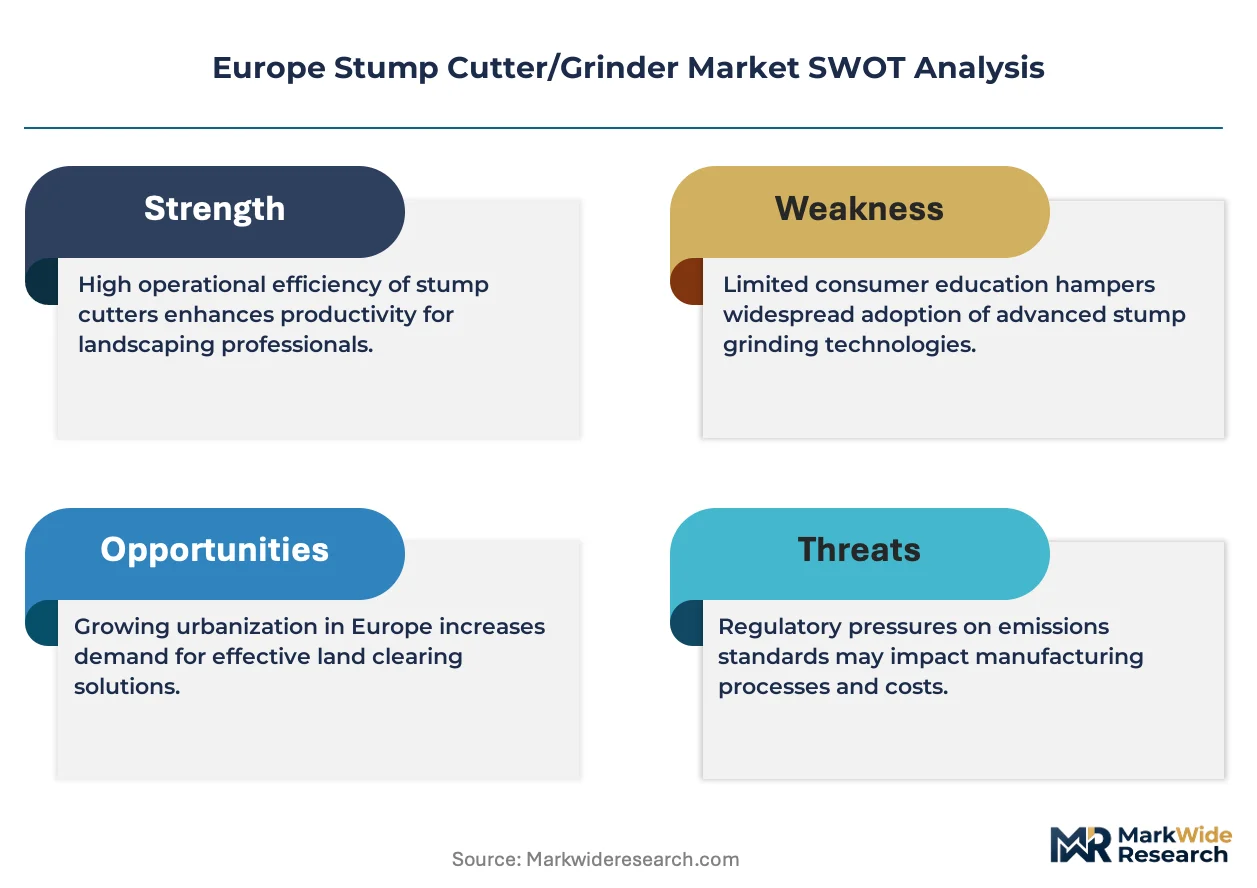
Forestry contractors across Germany and France are accelerating fleet modernization to comply with EU Green Deal reforestation mandates, while electric-drive platforms reshape municipal procurement patterns in Scandinavia's noise-restricted zones.
Growth Catalysts
- EU Green Deal reforestation mandates:National sustainable forest management codes in France and Germany require mechanized stump removal for soil preparation, driving replacement of manual methods across commercial forestry operations.
- Electric-drive technology maturation:Battery-powered platforms now deliver torque outputs matching diesel equivalents, enabling municipal buyers in the Netherlands and Denmark to meet urban noise ordinances without performance sacrifice.
- Commercial landscaping corridor concentration:Western Europe's dense network of arborist contractors and rental fleets sustains recurring demand for trailer-mounted units with transport flexibility.
Market Restraints
- Carbide-tipped tooth supply concentration:Specialized cutting consumables rely on limited tungsten carbide processing capacity, exposing contractors to input cost volatility and extended lead times.
- Grid connectivity gaps in remote forestry:Diesel platforms remain the only viable option across vast woodland areas in Sweden and Finland, fragmenting manufacturer powertrain development priorities.
- ECHA hydraulic fluid scrutiny:Pressure toward bio-based alternatives increases formulation complexity and cold-weather performance uncertainty for Nordic operators.
Strategic Opportunities
- Poland and Baltic states underpenetration:Mechanized stump removal adoption lags Western Europe, creating whitespace for rental fleet expansion and contractor education programs.
- CE marking harmonization:Unified EU Machinery Directive compliance enables single-product certification across 27 member states, reducing market entry friction for specialized manufacturers.
- Mulching attachment convergence:Integration of stump reduction heads with existing carrier vehicles allows forestry contractors to diversify fleet utilization without dedicated capital deployment.
Industry Challenges
- Certified technician scarcity:Complex hydraulic diagnostics and electric powertrain maintenance require specialized training programs that regional vocational institutions have not yet scaled.
- CE marking timeline compression:Evolving guarding system standards and operator protection requirements extend product development cycles for compact self-propelled unit launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stump Cutter/Grinder Market |
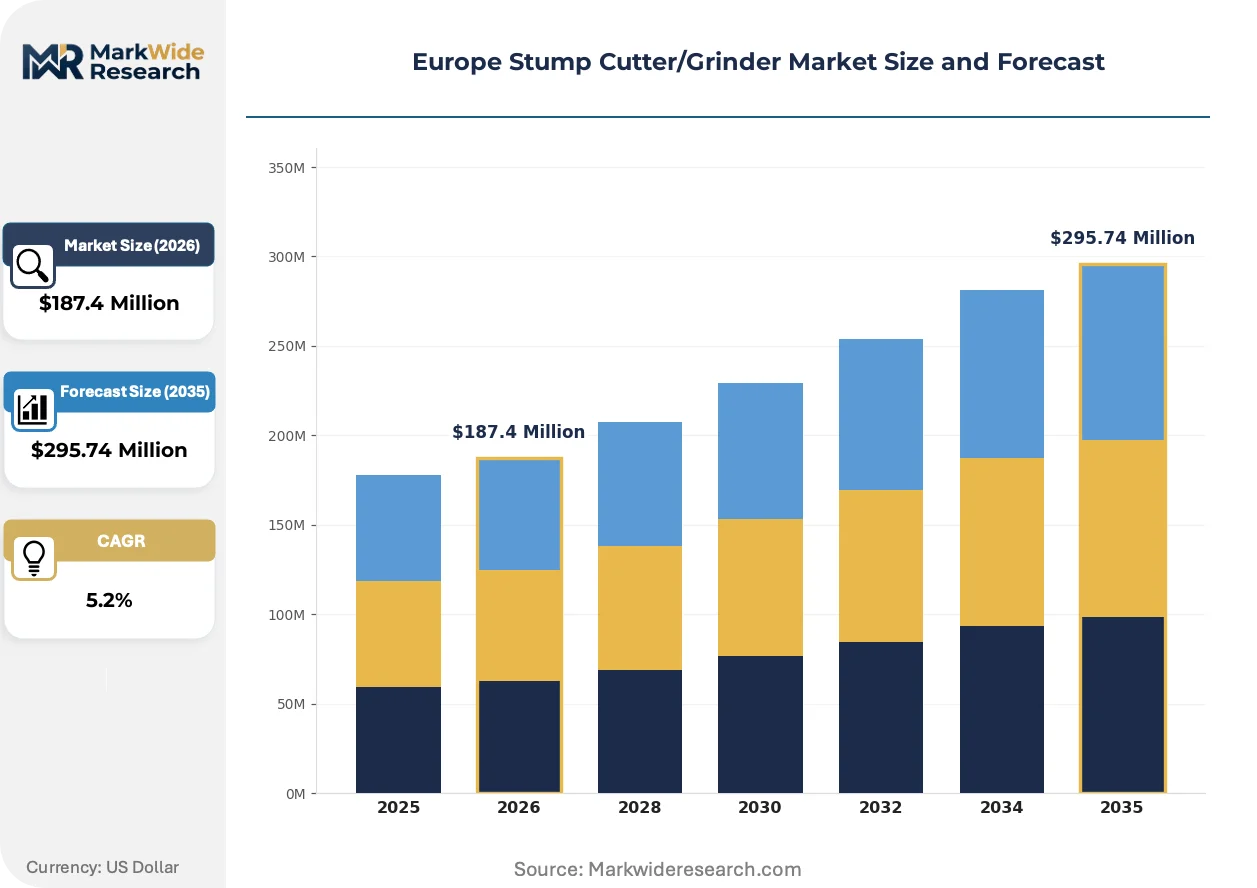
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $295.74 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Trailer-Mounted, Self-Propelled, Mini End User: Landscapers, Municipalities, Contractors, Homeowners Technology: Hydraulic, Electric, Gasoline, Diesel Application: Residential, Commercial, Agricultural, Forestry |
| Companies Covered | Morbark, FAE Group, Bandit Industries, Tracmaster Ltd., FSI, Vermeer, The Toro Company, Wacker Neuson SE, JO BEAU, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stump Cutter/Grinder Market Shifts & Advancements
Electrification and automation are rewriting equipment specifications, while regulatory pressure on emissions and noise accelerates technology substitution timelines across municipal and commercial buyer segments.
High-torque electric drivetrains are consolidating market position in urban and peri-urban applications where grid access permits sustained operation. Municipal buyers in Copenhagen and Amsterdam have standardized battery-powered platforms for park maintenance contracts, compressing demand for sub-50 horsepower diesel alternatives. This shift is consolidating procurement specifications around unified voltage architectures and fast-charging infrastructure requirements.
EU battery regulations are reshaping powertrain supply chain obligations for manufacturers serving European markets. Extended producer responsibility mandates for battery collection and recycling increase operational overhead, particularly for Italian and German engineering firms with integrated powertrain strategies. Municipal tender documents in Denmark and the Netherlands now incorporate end-of-life cost provisions, favoring suppliers with established reverse logistics networks.
Rental channel dominance is restructuring buyer-seller relationships across European contractor markets. Independent arborists in France and Germany increasingly access stump grinders through short-term rental rather than fleet ownership, shifting capital burden to distributors and national rental chains. This pattern concentrates volume with multi-location rental providers capable of offering maintenance-inclusive terms and rapid equipment rotation across job sites.
Europe Stump Cutter/Grinder Market Segmentation
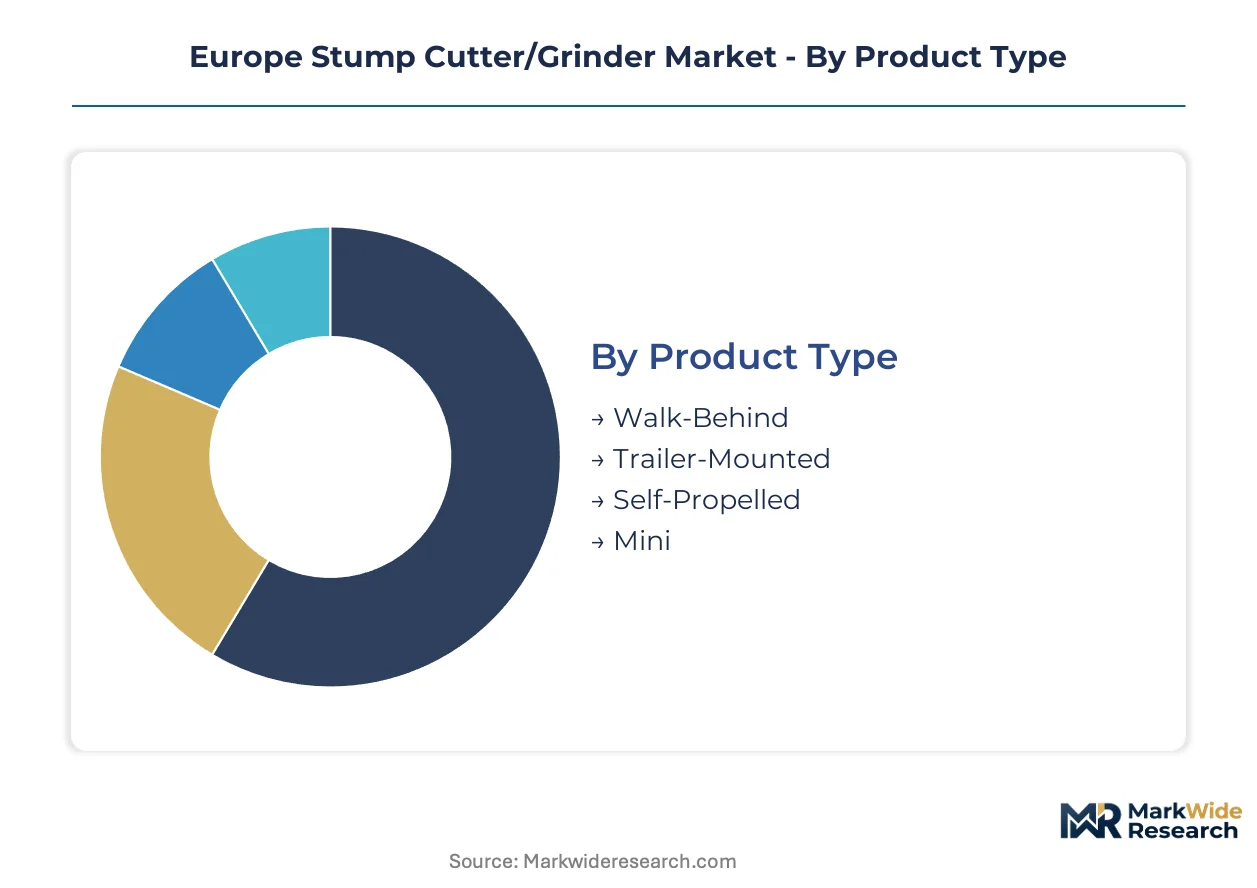
Stump grinder procurement patterns diverge sharply between capital-intensive commercial forestry operations and intermittent-use residential segments. Equipment specification, powertrain selection, and financing structures all pivot on these dividing lines.
Product Type:
The customization-to-standardization spectrum spans purpose-built industrial units versus mass-produced rental fleet staples.
- Trailer-Mounted:These units combine highway mobility with independent engine power, enabling rapid deployment across dispersed job sites. French and German rental chains concentrate procurement here, driven by contractor preference for operational flexibility without fleet ownership burdens.
- Self-Propelled:Dedicated undercarriage systems with integrated hydrostatic drives navigate narrow woodland access routes. Scandinavian forestry contractors prioritize these for steep terrain and remote clearing contracts where tow vehicles cannot reach.
- Walk-Behind:Compact pedestrian-controlled units serve residential landscapers with limited transport capacity.
- Mini:Ultra-compact designs access confined spaces in urban gardens and peri-urban maintenance zones.
Most installed capacity flows through Trailer-Mounted. Expansion is steepest in Self-Propelled.
End User:
Volume concentration sits with professional operators, while margin pools concentrate where technical specification requirements are most stringent.
- Contractors:Commercial arborists and land clearing specialists operate the highest-utilization fleets across Europe. German forestry contractors are modernizing equipment lines to satisfy EU Green Deal mechanization mandates, driving replacement cycles for diesel and emerging electric platforms.
- Municipalities:Urban park departments and roadside maintenance crews in the Netherlands and Denmark specify noise-compliant electric drivetrains. Copenhagen and Amsterdam procurement tenders now mandate battery-powered platforms for inner-city contracts.
- Landscapers:Smaller-scale operators serving residential and commercial property maintenance.
- Homeowners:Occasional-use buyers accessing equipment through rental channels or entry-level purchase.
Contractors absorb the majority of unit volume. Municipalities are climbing the fastest as electrification mandates harden.
Technology:
Powertrain selection hinges on grid proximity, duty cycle intensity, and regulatory pressure gradients across operating environments.
- Diesel:High-torque compression-ignition engines dominate remote forestry applications in Sweden and Finland where electrical infrastructure remains absent. Cold-weather starting reliability and field refueling independence sustain this segment's position in Nordic commercial clearing.
- Electric:Battery-powered platforms now match diesel torque outputs in sub-50 horsepower classes. Dutch and Danish municipalities have standardized these for urban noise-restricted zones, compressing demand for small diesel alternatives.
- Hydraulic:Power take-off systems integrated with carrier vehicles serve attachment-based operations.
- Gasoline:Spark-ignition engines persist in occasional-use residential and light commercial segments.
Diesel retains the largest installed base. Electric is gaining share fastest where grid access permits sustained operation.
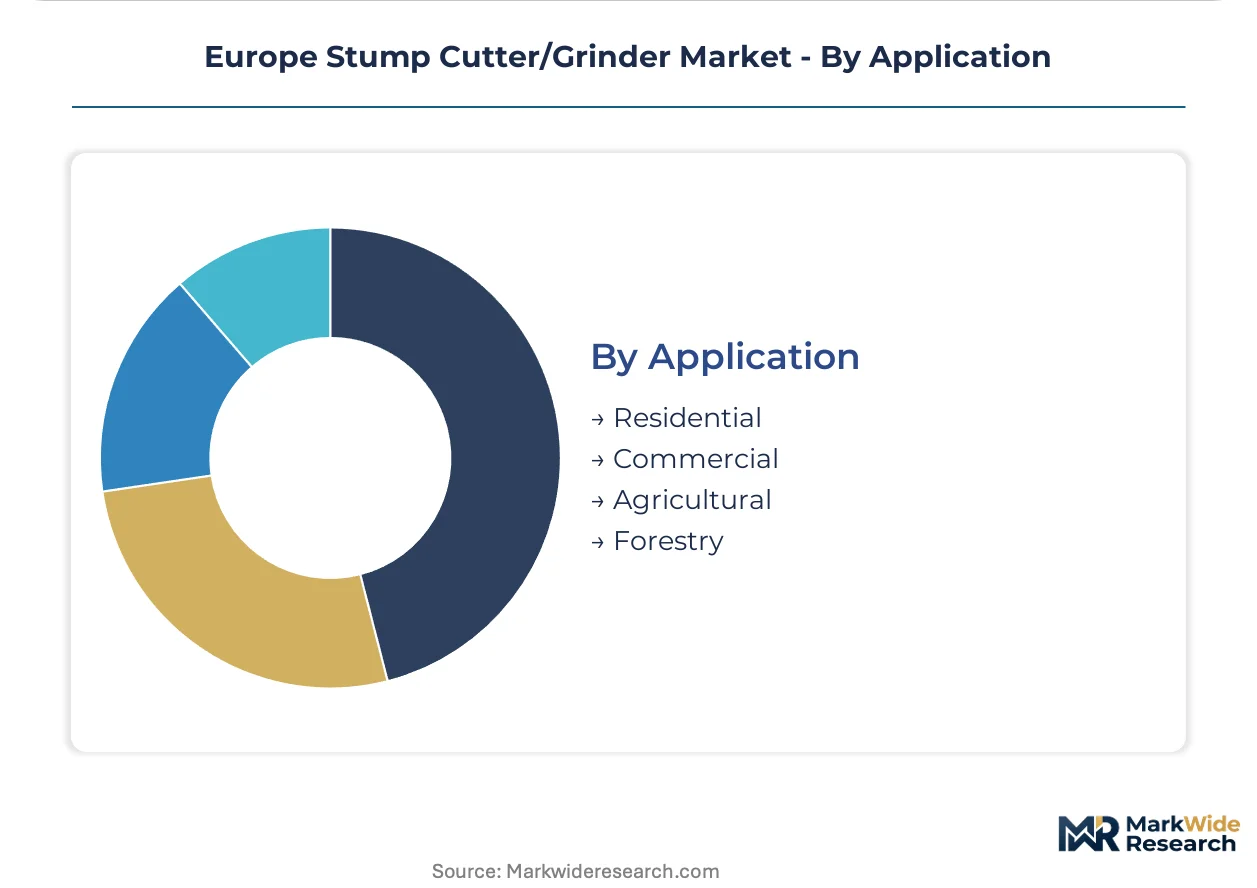
Application:
Site preparation requirements vary from aesthetic residential finishing to industrial-scale soil remediation for reforestation.
- Forestry:Commercial timber operations and reforestation site preparation demand maximum grinding depth and throughput. French and German sustainable forest management codes now require mechanized stump removal, displacing manual extraction methods across certified woodland operations.
- Commercial:Property development, infrastructure expansion, and utility right-of-way maintenance create recurring demand. Western Europe's dense construction corridor sustains rental fleet rotations and contractor equipment turnover.
- Residential:Single-property clearing for construction or garden renovation.
- Agricultural:Field preparation and pasture reclamation in farming operations.
Forestry commands the heaviest equipment specifications. Commercial applications drive the highest unit velocity through rental channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking harmonization under the EU Machinery Directive creates regulatory-arbitrage incentives for manufacturers to consolidate production in jurisdictions with established conformity assessment infrastructure. Germany and Italy leverage notified body density to anchor fabrication capacity, while Nordic markets pull specialized electric platforms through municipal procurement mandates.
Germany
Forestry contractors in Bavaria and Baden-Württemberg are modernizing stump removal fleets to satisfy sustainable forest management codes under the EU Green Deal. KBA oversight of mobile machinery safety standards shapes guarding system specifications for domestic manufacturers. The Stuttgart engineering corridor concentrates R&D activity for high-torque hydraulic platforms serving commercial clearing operations.
France
ANSM and national environmental regulators enforce reforestation site preparation mandates that displace manual stump extraction methods across certified woodland. Île-de-France and Auvergne-Rhône-Alpes anchor rental fleet distribution networks serving arborist contractors. Paris-region procurement offices specify noise-compliant equipment for peri-urban park maintenance contracts.
Sweden
Grid connectivity gaps across Västerbotten and Norrbotten counties sustain diesel platform demand in remote commercial forestry zones. Municipal buyers in Stockholm and Gothenburg have standardized battery-powered stump grinders for urban noise-restricted maintenance. The EU battery regulations' extended producer responsibility mandates reshape procurement tender evaluation criteria for park departments.
Italy
FAE Group anchors Emilia-Romagna's engineering strength in mulching attachments that integrate with carrier vehicles for diversified fleet utilization. CE marking conformity assessment bodies in Bologna and Modena reduce certification timelines for export-oriented manufacturers. The Po Valley industrial corridor concentrates fabrication capacity for attachment-based stump reduction systems.
Netherlands
Amsterdam and Rotterdam municipal procurement tenders now mandate battery-powered platforms for inner-city contracts, compressing demand for small diesel alternatives. ECHA scrutiny of hydraulic fluid formulations pressures contractors toward bio-based alternatives in lowland agricultural zones. The Randstad urban corridor drives fastest electric technology adoption among European municipal buyer segments.
Europe Stump Cutter/Grinder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and attachment-based convergence. The vendor base stratifies across three tiers: integrated forestry equipment manufacturers with full-line portfolios, specialized stump grinder fabricators focused on narrow application segments, and regional rental fleet suppliers capturing intermittent-use demand. Dominant competitive moves include portfolio diversification into electric platforms and strategic partnerships with carrier vehicle OEMs for attachment integration.
Among North American-headquartered manufacturers, Morbark and Vermeer exemplify the integrated tier with Wisconsin-based production footprints serving Nordic export channels. FAE Group represents the specialized attachment archetype, anchoring Italian engineering strength in mulching systems. Wacker Neuson SE occupies a position bridging compact equipment scale with European regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Morbark |
| FAE Group |
| Bandit Industries |
| Tracmaster Ltd. |
| FSI |
| Vermeer |
| The Toro Company |
| Wacker Neuson SE |
| JO BEAU |
| Others |
Supply & Pricing Matrix
Electric drivetrain maturation across municipal procurement channels is compressing cost structures for sub-50 horsepower platforms while concentrating manufacturing scale among Italian and German engineering clusters with integrated battery system capabilities. This technology transition simultaneously enables premium pricing for noise-compliant equipment and forces margin discipline on diesel-dependent fabricators serving remote forestry zones.
Pricing Analysis
Distributor margin layers of 18-25 percent separate factory gate from contractor fleet pricing across French and German rental channels. Pricing stratifies across premium, standard, and economy tiers based on CE marking compliance level and after-sales service bundling. Cost compression in economy-tier diesel units is intensifying because of carbide-tipped tooth supply bottlenecks. Municipal buyers in Copenhagen and Amsterdam exhibit lowest price sensitivity due to electrification mandates, while independent Polish contractors remain most sensitive to capital outlay.
Supply Chain Analysis
Reverse-logistics networks for battery collection and recycling are becoming mandatory cost centers under EU extended producer responsibility rules, favoring manufacturers with established Nordic service infrastructure. Tungsten carbide processing capacity concentrates in Germany, Austria, and China, creating single-source vulnerability for cutting consumables. Hydraulic system components draw from Italian and German industrial corridors. Distribution runs through national rental chains and specialized forestry equipment dealers rather than direct OEM-to-contractor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on electric platform premiumization and the displacement of manual stump removal methods under EU Green Deal compliance deadlines.
For Market Incumbents: Acquire battery system integration capabilities to defend municipal procurement share against emerging electric specialists. Strengthen backward integration into tungsten carbide tooth manufacturing to insulate margins from supply volatility. CE marking timeline compression for revised guarding standards threatens compact self-propelled launch schedules. For New Entrants and Emerging Players: Direct-to-rental-channel digital platforms offer the lowest-friction entry path for Polish and Baltic state market penetration. Target underpenetrated forestry contractor segments in Estonia and Latvia with attachment-based mulching systems that leverage existing carrier vehicle fleets. Education-heavy sales models outperform specification-based competition where mechanized stump removal adoption lags. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet operators because fragmented contractor demand concentrates volume with multi-location providers capable of maintenance-inclusive terms. Five-to-ten year viability hinges on electrification capex conversion rates and bio-based hydraulic fluid formulation stability. Monitor ECHA regulatory announcements on fluid composition as inflection signals for Nordic operator cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform R&D Investment | Battery-powered torque matching enables Copenhagen and Amsterdam procurement standardization. |
| Attachment System Integration | Mulching head convergence with carrier vehicles diversifies fleet utilization for French contractors. |
| Reverse Logistics Network Buildout | EU battery regulations mandate collection infrastructure for Danish municipal tender compliance. |
| Bio-Based Hydraulic Fluid Transition | ECHA scrutiny pressures Nordic operators toward cold-weather performance alternatives. |
| Rental Channel Partnership Expansion | Short-term access models shift capital burden from German arborists to distributor balance sheets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged forestry equipment procurement managers at German and French rental chains, municipal park maintenance directors in Denmark and the Netherlands, and aftermarket service heads at Italian attachment manufacturers. Secondary validation drew from EU Machinery Directive compliance databases, ECHA substance restriction filings, and national sustainable forest management code implementations. Bottom-up unit shipment estimates triangulated against top-down equipment replacement cycle modeling.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included product type, powertrain technology, end-user category, and application intensity. CAGRs were derived from equipment replacement cycle compression under EU Green Deal mandates and electric platform adoption curves in grid-connected urban zones. Forecast inputs incorporated carbide tooth supply lead times and battery cell cost trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for diesel displacement timelines. Forecasts reflect underlying assumptions about municipal electrification mandate enforcement consistency and Nordic grid extension rates. Practitioners should monitor ECHA regulatory consultations and national reforestation subsidy allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Allen Key Market
Tools
Total Station Market
Tools
Grease Gun Market
Tools
Rotary Knife Cutters Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Taps and Dies Market
Tools
Manual Cutting Equipment Market
Tools
Global Metal Forming Machine Tools Market
Tools
Pipe Alignment Clamps Market
Tools
Floor Polishing Machine Market
Tools
Fiber Laser Cutting Machines Market
Tools
Tool Boxes Market
Tools
Metal Forming Tools Market
Tools
Metal Cutting Tools Market
Tools
Global Tools Storage Products Market
Tools
2D Laser Cutting Machine Market