
 Power Tool Accessories Market | 2026-2036
Power Tool Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tool Accessories Market Intelligence
The capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in power tool accessories. Robert Bosch leverages captive carbide production to control input costs across European and Asian plants. Stanley Black & Decker sustains brand pull through retail channel density in North American home improvement chains. Hilti Corporation anchors premium positioning via direct-to-contractor distribution and fleet management services.
Power tool accessories comprise interchangeable consumables and attachments engineered to specific torque, RPM, and material-removal parameters for cordless and corded tool platforms. Carbide-tipped drill bits tolerate higher thermal loads in masonry applications than high-speed steel equivalents, while diamond-edged saw blades extend cutting life in concrete and tile work. Drill bits occupy the largest volume share among product types due to universal use across construction, manufacturing, and residential repair. Carbide material grades command margin premiums over standard steel formulations as end users prioritize durability in high-cycle commercial environments. Online retail channels are gaining share from specialty stores among DIY enthusiasts seeking compatibility verification through digital product selectors.
FCC certification governs radio-frequency emissions from cordless tool battery systems, while EPA REACH compliance restricts hazardous substances in surface coatings and composite binders. OSHA silica rules mandate wet-cutting accessories and dust-collection attachments for concrete and masonry operations, directly shaping blade and guard design requirements. Stakeholders must monitor battery platform consolidation among tool OEMs, as proprietary chuck and interface standards determine accessory addressable market boundaries.
Market Dynamics
OSHA silica exposure mandates and cordless battery platform consolidation are forcing simultaneous redesign of dust-collection accessories and interface standards, compressing product development cycles while fragmenting addressable markets by OEM ecosystem.
Growth Catalysts
- Residential Construction Surge:Single-family housing starts in the United States and Germany are amplifying replacement demand for drill bits and saw blades among professional contractors and DIY renovators.
- REACH Compliance-Driven Material Upgrades:European coating restrictions are accelerating substitution of solvent-based surface treatments with water-based and powder-coat alternatives in accessory manufacturing.
- Carbide-Tip Proliferation:Tungsten carbide grade innovations are extending tool life in masonry applications, justifying premium pricing in commercial construction environments.
Market Restraints
- Tungsten Supply Concentration:Over 80 percent of global tungsten ore processing resides in Chinese state-controlled refineries, exposing carbide input costs to export quota volatility.
- Battery Platform Lock-In:Proprietary chuck interfaces from DeWalt, Milwaukee, and Makita partition the cordless accessory market into non-interoperable ecosystem silos.
- Raw Material Price Volatility:Cobalt and nickel price swings in London Metal Exchange trading directly impact high-speed steel alloy formulations and diamond segment bonding agents.
Strategic Opportunities
- Indian Infrastructure Build-Out:National highway and metro rail expansion under the PM Gati Shakti framework is creating bulk procurement channels for carbide-tipped concrete cutting accessories.
- Wet-Cutting Accessory Mandates:OSHA silica rules are generating replacement demand for integrated water-delivery guards and vacuum shrouds on existing blade inventories.
- Direct-to-Contractor Digital Platforms:Fleet management apps and QR-code compatibility verification are disintermediating traditional distributor markups in North American commercial construction procurement.
Industry Challenges
- Multi-Platform Certification Burden:FCC Part 15 radio testing for smart battery systems, combined with CE marking and UL safety validation, extends new product introduction timelines by 8-14 months.
- Carbide Insert Bonding Expertise Gap:Vacuum brazing and laser cladding technicians command wage premiums exceeding 40 percent above standard tool-and-die rates, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tool Accessories Market |
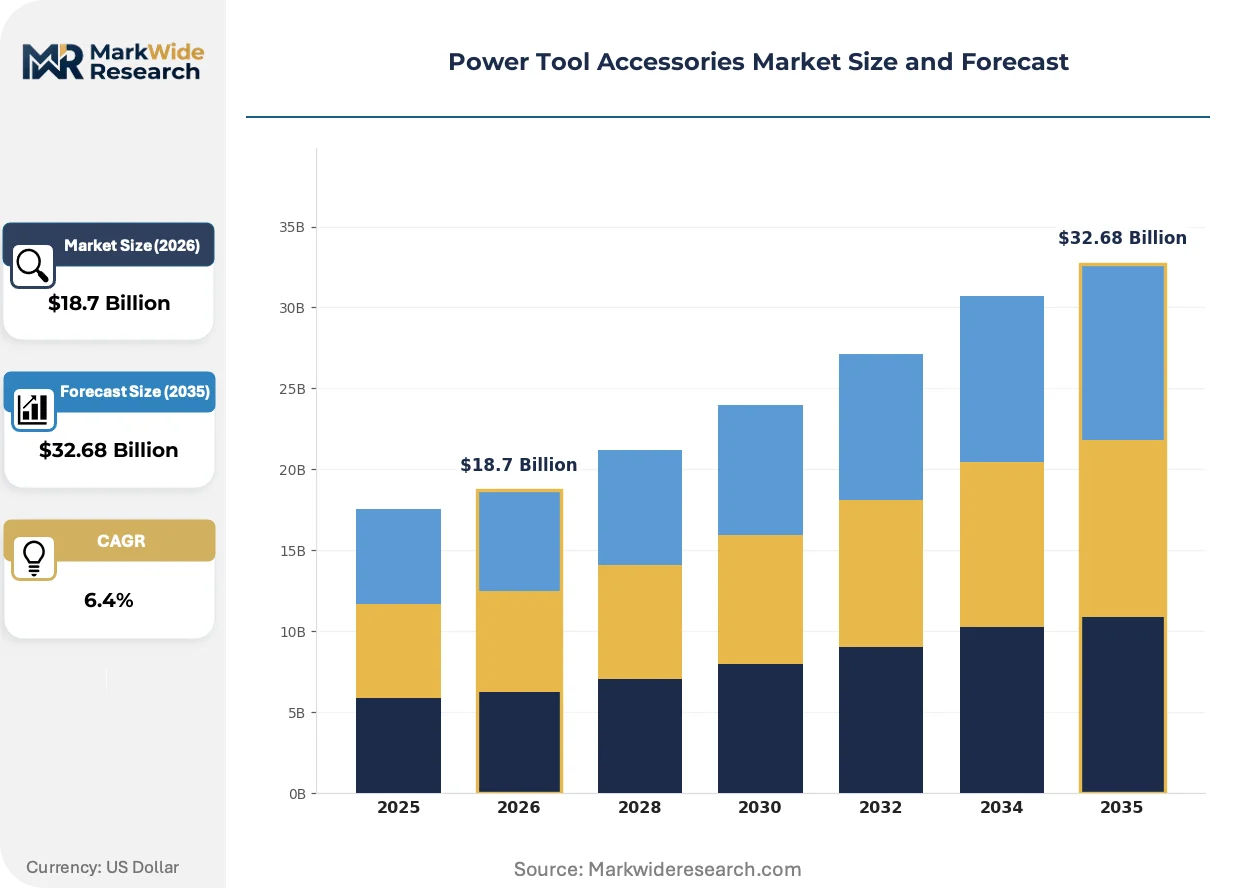
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Bits, Saws, Sandpaper, Attachments Material: Steel, Carbide, Plastic, Composite End User: DIY Enthusiasts, Contractors, Manufacturers, Construction Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Makita Corporation, Apex Tool Group, Stanley Black & Decker, Snap-on Incorporated, Emerson Electric, Robert Bosch, Hilti Corporation, Ingersoll Rand, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tool Accessories Market Strategic Shifts & Innovations
Cordless battery chemistry advances and digital compatibility tools are compressing replacement cycles while elevating performance expectations for thermal tolerance and precision fit across accessory categories.
Carbide matrix composites with cobalt-reduced binders are decomposing the traditional trade-off between fracture toughness and heat resistance in masonry drill bits. Commercial contractors in Germany and Australia are specifying these formulations for continuous rotary hammer use exceeding 500 holes per day. The technology is decomposing market segmentation between premium professional and standard trade-grade product tiers by delivering extended life at mid-tier price points.
EPA REACH restrictions on hexavalent chromium in electroplated coatings are forcing conversion to trivalent chrome and nickel-tungsten alloy alternatives for corrosion protection. Surface treatment suppliers in Italy and Poland are retooling electrolytic lines to meet the December 2024 compliance deadline. Diamond saw blade manufacturers serving European concrete cutting markets are absorbing 12-18 percent coating cost increases while reformulating segment bonds to maintain adhesion performance.
QR-code scanning and augmented reality compatibility verification are displacing physical chuck testing in retail and distributor environments. Home improvement chains in the United States and United Kingdom are deploying shelf-edge digital selectors that match battery platform, torque rating, and material specification. This behavioral shift is most visible among millennial DIY purchasers who prioritize return-avoidance over tactile evaluation, compressing the consideration phase from multiple store visits to single-session mobile transactions.
Power Tool Accessories Market Segmentation
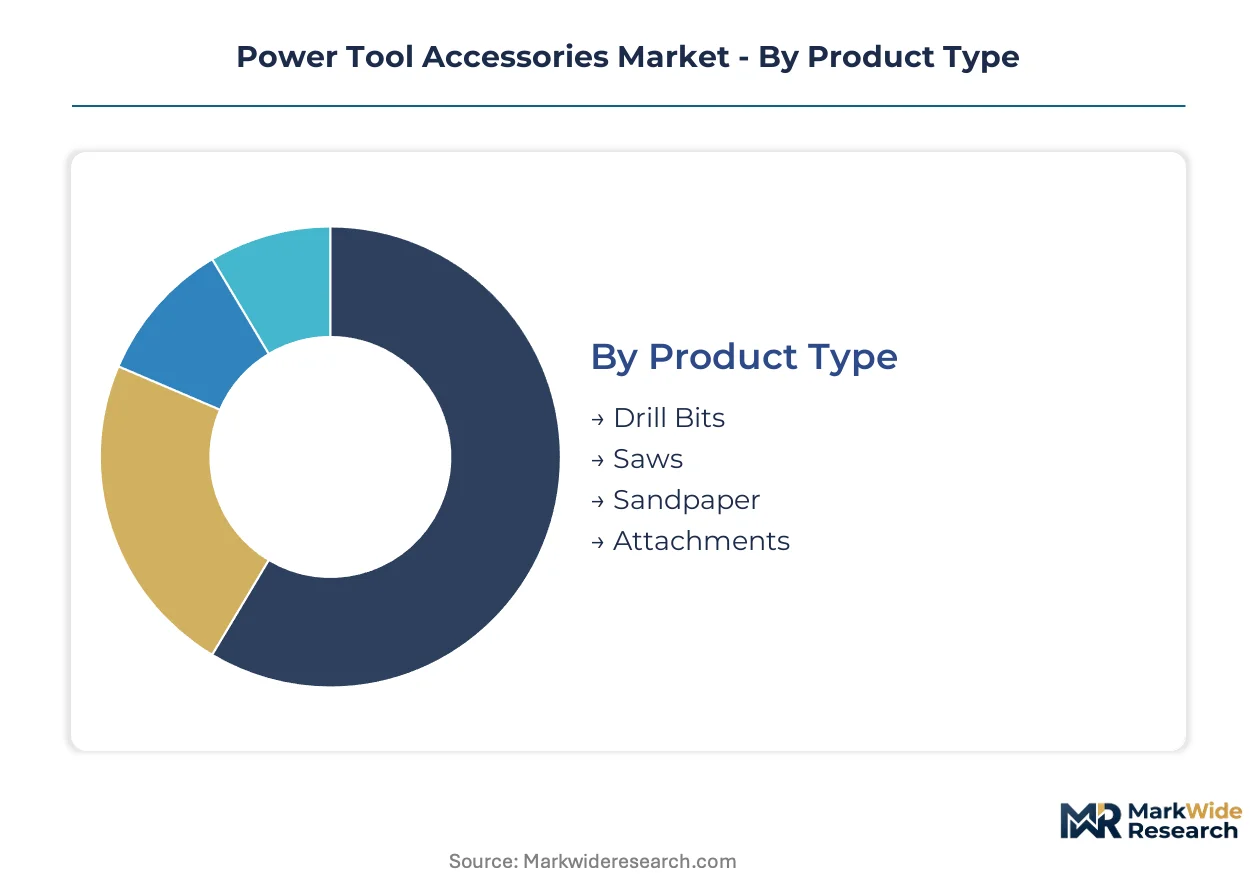
Power tool accessories fragment across material grades, user sophistication, and procurement channels. Each axis carries distinct margin structures and certification burdens that reshape competitive positioning.
Product Type:
Domestic replacement cycles dominate drill bit and saw blade volumes in the United States and Germany, while export-led bulk procurement concentrates attachments and specialty abrasives in Chinese manufacturing clusters.
- Drill Bits:Carbide-tipped and high-speed steel formulations tolerate thermal loads in masonry and metalworking. German commercial contractors specify cobalt-reduced carbide matrices for rotary hammer applications exceeding 500 holes per day. OSHA silica compliance is accelerating wet-cutting guard attachments on existing bit inventories.
- Saws:Circular, reciprocating, and diamond-edged blades extend cutting life in concrete and tile work. Australian infrastructure contractors are driving specification upgrades for continuous concrete cutting under dust-exposure mandates.
- Sandpaper:Aluminum oxide and silicon carbide abrasives serve finishing applications across woodworking and automotive repair. Italian surface treatment suppliers are retooling electrolytic lines to meet REACH coating restrictions.
- Attachments:Router bases, jigsaw guides, and dust-collection shrouds expand tool platform versatility. Chinese OEMs dominate injection-molded plastic attachment production for cordless platform ecosystem lock-in.
Drill bits command the established base. The steepest expansion runs through dust-integrated attachments.
Material:
Cost tier stratification separates commodity steel from performance-grade carbide, with composite formulations capturing mid-tier positioning through weight reduction.
- Steel:High-speed and carbon steel alloys serve low-cycle residential repair. Cobalt and nickel price swings in London Metal Exchange trading directly impact alloy formulation costs.
- Carbide:Tungsten carbide grades with cobalt binders deliver fracture toughness for masonry drilling. Over 80 percent of global tungsten ore processing resides in Chinese state-controlled refineries, exposing input costs to export quota volatility.
- Plastic:Glass-reinforced nylon and ABS housings reduce weight in cordless tool attachments. Injection molding capacity concentrates in Zhejiang province for battery platform ecosystem suppliers.
- Composite:Carbon fiber and ceramic matrix hybrids balance stiffness with thermal dissipation. Aerospace-derived formulations are penetrating premium rotary tool segments in Japanese manufacturing.
Steel retains volume leadership across replacement markets. Carbide is climbing the fastest through commercial specification upgrades.
End User:
Customer type determines price sensitivity, with fleet-managed contractors absorbing premium pricing for durability guarantees while DIY purchasers prioritize compatibility verification.
- DIY Enthusiasts:Home renovators prioritize QR-code compatibility tools and digital selectors over tactile evaluation. Millennial purchasers in the United States and United Kingdom compress consideration phases through mobile transactions.
- Contractors:Commercial construction professionals specify carbide grades for high-cycle environments. Direct-to-contractor digital platforms are disintermediating traditional distributor markups in North American procurement.
- Manufacturers:Industrial assembly operations demand precision-ground bits for automated fastening systems. German automotive suppliers drive specification for ISO-certified dimensional tolerance.
- Construction:Infrastructure and residential builders generate bulk replacement demand. Indian national highway expansion under PM Gati Shakti is creating procurement channels for carbide-tipped concrete cutting accessories.
Contractors anchor professional-grade revenue. DIY digital adoption is gaining share fastest through retail channel transformation.
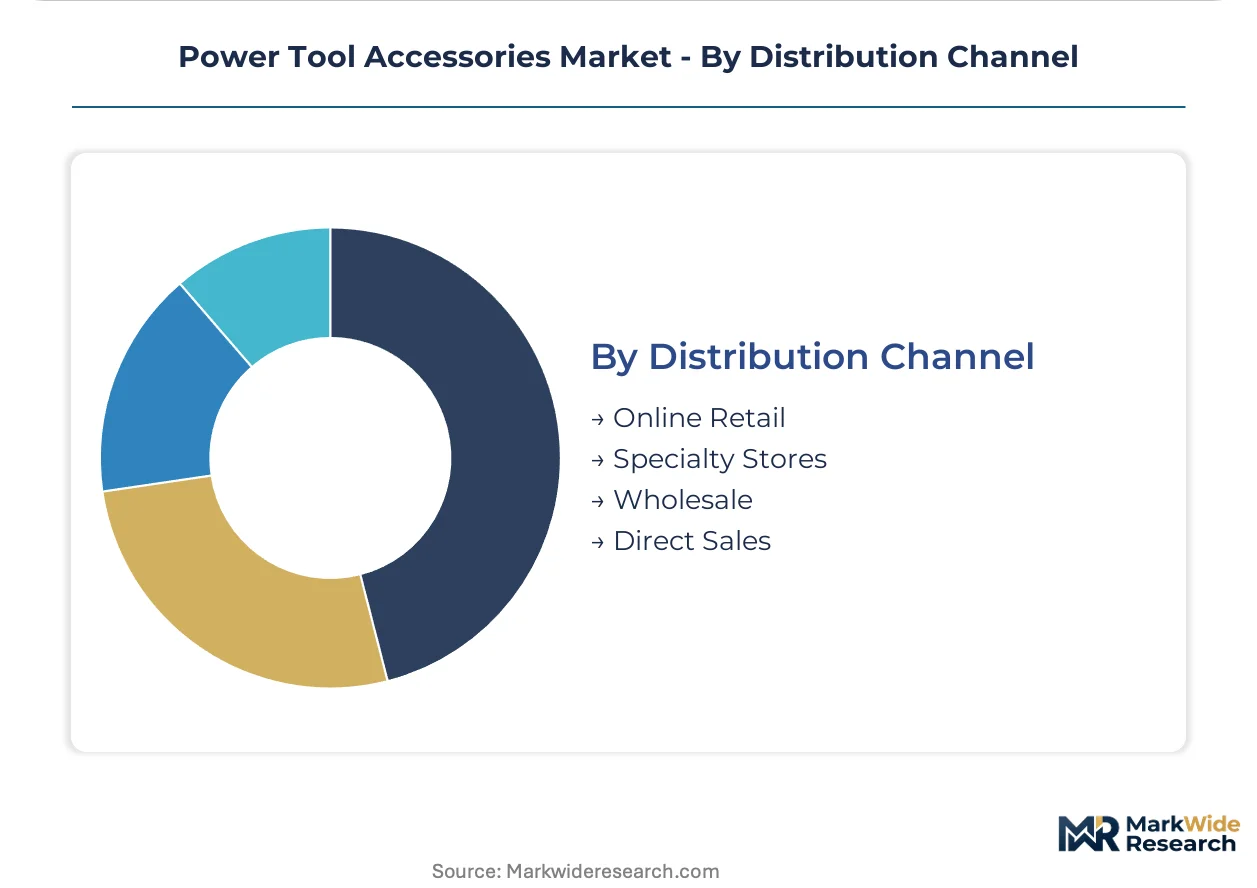
Distribution Channel:
Channel margin structures diverge sharply, with wholesale retaining volume concentration while online platforms capture specification transparency advantages.
- Online Retail:Digital product selectors and augmented reality compatibility verification displace physical chuck testing. Home improvement chains deploy shelf-edge matching systems for battery platform alignment.
- Specialty Stores:Independent distributors retain influence in professional contractor relationships through technical consultation. Vacuum brazing expertise gaps constrain their private-label expansion.
- Wholesale:Bulk procurement channels serve national construction accounts and manufacturing OEMs. Chinese manufacturing clusters sustain volume concentration for export markets.
- Direct Sales:Fleet management services and QR-code verification tools lock in contractor loyalty. Hilti Corporation anchors premium positioning through captive distribution networks.
Wholesale maintains the volume foundation. Online retail is expanding most quickly through millennial DIY penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in power tool accessories tilt toward net surplus in manufacturing-intensive economies while deficit markets absorb finished goods through retail and distribution networks. China dominates outbound carbide-tipped volumes. Germany and the United States anchor high-value replacement demand. India emerges as a bulk procurement growth corridor.
China
Infrastructure build-out and manufacturing cluster density sustain bulk procurement of carbide-tipped drill bits and diamond saw blades. MIIT industrial standards govern cordless battery interface compatibility across domestic OEM platforms. Zhejiang province concentrates injection-molded plastic attachment production for battery ecosystem suppliers serving Southeast Asian export markets.
United States
Single-family housing starts amplify replacement demand for drill bits and saw blades among professional contractors and DIY renovators. OSHA silica exposure mandates accelerate wet-cutting guard attachments and dust-collection shroud retrofits on existing blade inventories. Home improvement chains in the Midwest and Southeast deploy shelf-edge digital selectors matching battery platform specifications.
Germany
Commercial contractors specify cobalt-reduced carbide matrices for rotary hammer applications exceeding 500 holes per day. ECHA REACH restrictions on hexavalent chromium force conversion to trivalent chrome and nickel-tungsten alloy surface treatments by December 2024. Bavarian surface treatment suppliers retool electrolytic lines to maintain adhesion performance in diamond segment bonding.
India
National highway and metro rail expansion under the PM Gati Shakti framework creates bulk procurement channels for carbide-tipped concrete cutting accessories. BIS certification requirements for power tool safety standards shape import compliance protocols. Manufacturing clusters in Gujarat and Maharashtra scale vacuum brazing capacity for domestic carbide insert bonding.
Australia
Infrastructure contractors drive specification upgrades for continuous concrete cutting under dust-exposure mandates aligned with occupational health regulations. The country's national workplace safety regulator enforces silica control measures paralleling OSHA frameworks. Queensland and New South Wales mining operations sustain demand for diamond-edged saw blades in extraction and processing applications.
Power Tool Accessories Market Key Industry Players
Concentration sits with diversified industrial conglomerates controlling captive carbide production and direct distribution networks. The vendor base spans three functional tiers: integrated manufacturers with upstream material control, brand-anchored assemblers leveraging retail channel density, and specialized component suppliers serving ecosystem lock-in strategies. Strategic moves center on backward integration into tungsten carbide processing and fleet management service deployment to capture contractor loyalty.
Among diversified industrial conglomerates, Robert Bosch and Stanley Black & Decker exemplify contrasting archetypes. Bosch represents vertical control through captive carbide production across European and Asian manufacturing footprints. Stanley Black & Decker occupies a position anchored by retail channel density in North American home improvement chains. Hilti Corporation sits within the premium-tier vector through direct-to-contractor distribution and fleet management services, illustrating how captive distribution networks defend margin position against price-competitive retail channels.
| Leading Market Players |
|---|
| Makita Corporation |
| Apex Tool Group |
| Stanley Black & Decker |
| Snap-on Incorporated |
| Emerson Electric |
| Robert Bosch |
| Hilti Corporation |
| Ingersoll Rand |
| Techtronic Industries |
| Others |
Cost & Logistics Intelligence
Carbide insert bonding capacity utilization above 85 percent in German and Chinese plants is compressing marginal cost curves for premium drill bit tiers while elevating price floors for mid-grade formulations. Scale advantages at integrated manufacturers translate into 15-20 point margin spreads over component assemblers, reshaping competitive entry thresholds across cordless platform ecosystems.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on carbide grade certification and fleet management bundling. Price differentiation rests on REACH compliance tier and cobalt-reduced binder technology, with European contractors absorbing premium positioning for silica-compliant wet-cutting configurations. Cost compression in standard-grade steel bits is intensifying because of nickel price volatility on London Metal Exchange trading. DIY enthusiasts exhibit highest price sensitivity through digital channel price transparency, while fleet-managed contractors demonstrate lowest sensitivity due to durability guarantee absorption.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shenzhen-Long Beach trade lanes are extending inbound logistics cycles for carbide powder shipments and diamond segment raw materials. Geographic supply concentration centers on China for tungsten ore processing and injection-molded attachments, Germany for precision grinding equipment, and Vietnam for secondary steel alloy forming. Raw material dependencies draw from tungsten carbide powders, cobalt binders, and glass-reinforced nylon resins. Single-source vulnerability in Chinese state-controlled tungsten refineries exposes input costs to export quota volatility. Distribution runs through wholesale bulk channels for national construction accounts, with direct-to-contractor digital platforms gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum brazing technician shortages exceeding 40 percent wage premiums over standard tool-and-die rates signal acute capability scarcity constraining capacity expansion at non-integrated manufacturers. Carbide matrix formulation expertise and captive tungsten processing assets represent the critical skill and asset gaps determining competitive sustainability.
For Market Incumbents: Shield margin position through backward integration into tungsten carbide powder production and captive vacuum brazing capacity in Zhejiang or Bavarian manufacturing clusters. Battery platform lock-in from DeWalt, Milwaukee, and Makita ecosystems threatens addressable market fragmentation, requiring certification investment across multiple proprietary chuck interfaces to defend shelf presence. For New Entrants and Emerging Players: Differentiate on wet-cutting silica compliance accessories for OSHA-mandated concrete cutting retrofits, where established inventories lack integrated water-delivery guards. The Indian infrastructure build-out under PM Gati Shakti presents the most penetrable geography for bulk carbide-tipped concrete cutting procurement. A direct-to-contractor digital platform with QR-code compatibility verification offers the clearest go-to-market angle to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management service providers with captive distribution networks, offering superior cash flow predictability over transactional retail channel exposure. Long-term viability over the next decade hinges on tungsten supply security and battery platform consolidation outcomes. Acquisition targets should prioritize mid-tier carbide formulators with cobalt-reduced binder patents. The signal to watch is MIIT battery interface standardization announcements in China, which would reshape ecosystem addressability and trigger revaluation of multi-platform certification burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Processing | Captive carbide powder production insulates margin from Chinese export quota volatility and secures input cost control. |
| Wet-Cutting Accessory Portfolio Expansion | OSHA silica compliance mandates generate replacement demand for integrated water-delivery guards on existing blade inventories. |
| Fleet Management Platform Deployment | Direct-to-contractor digital tools with QR-code verification disintermediate traditional distributor markups and lock in loyalty. |
| Multi-Platform Certification Investment | Proprietary chuck interfaces from DeWalt, Milwaukee, and Makita partition addressable markets, requiring cross-ecosystem compatibility. |
| Cobalt-Reduced Binder Technology Scale-Up | Carbide matrix innovations decompose the toughness-heat resistance trade-off, enabling mid-tier pricing with premium performance. |
Research Approach
Operator-level perspectives from maintenance directors at commercial construction firms, plant engineers at automotive assembly operations, aftermarket service heads at power tool OEMs, and procurement leads at national home improvement chains anchored the qualitative base. Primary interview findings combined with secondary validation from SEC 10-K filings, customs and trade data, OSHA regulatory dockets, and MIIT industrial standard publications. Bottom-up demand modeling across drill bit, saw blade, sandpaper, and attachment categories triangulated against top-down macro construction spending indicators.
Sensitivity analysis tested forecast robustness across tungsten price volatility scenarios, battery platform consolidation timelines, and REACH compliance cost pass-through assumptions. Segmentation dimensions modeled encompass product type, material grade, end-user sophistication tier, and distribution channel structure, with additional cross-cutting analysis by cordless battery platform ecosystem. CAGRs derived from regression analysis of historical replacement cycle data and forward projection of construction activity indices, incorporating carbide grade innovation adoption curves and silica compliance retrofit demand.
Forecasts assume regulatory continuity in OSHA silica exposure enforcement and ECHA REACH coating restrictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Powder Compacting Pressers Market
Tools
Europe Woodworking Power Tools Market
Tools
Set Screw Market
Tools
Telescopic Tool Boxes Market
Tools
Mechanical Springs Market
Tools
Impact Wrenches Market
Tools
Edge Banders Market
Tools
Woodworking Power Tools Market
Tools
2D Laser Cutting Machine Market
Tools
Crimping Tool Market
Tools
L Allen Wrench Market
Tools
End Milling Machine Market
Tools
Leather Cutting Machine Market
Tools
Portable Heat Press Machine Market
Tools
Bottle Jack Market
Tools
Europe Paint Spray Guns Market