
 Log Splitters Market | 2026-2036
Log Splitters Market Size, Share, and Industry Trends Forecast 2026-2036
Log Splitters Market Analysis
Landscaping services is pivoting toward higher-capacity equipment as commercial groundskeeping contracts expand across municipal parks and corporate campuses. Champion Power Equipment leverages broad retail distribution to capture residential buyers seeking mid-range electric models. Boss Industrial anchors its position through specialized hydraulic systems designed for professional forestry applications. Oregon differentiates via integrated cutting-system expertise that extends from chainsaws through splitting attachments.
Log splitters are mechanical devices that apply concentrated force through hydraulic rams, screw drives, or kinetic flywheels to fracture wood along grain lines, typically processing rounds with diameters between six and thirty inches into burnable sections. Electric splitters operate at approximately three to five tons of ram pressure, while gas-powered and hydraulic commercial units generate twenty to thirty tons for dense hardwood species. Gas-powered splitters still occupy the largest installed base among commercial users despite accelerating interest in electric alternatives for noise-restricted zones. Hydraulic splitters command premium positioning among forestry services where cycle speed and tonnage ratings determine operational throughput. Manual splitters retain residual demand from off-grid residential users prioritizing portability and zero fuel dependence.
EPA small-engine emission regulations constrain gasoline-powered model specifications, compelling manufacturers to invest in catalytic converter integration or battery-electric platforms. OSHA logging and forestry safety standards influence operator-guard design and two-hand activation requirements across commercial-grade equipment sold in the United States. Buyers must weigh total cost of ownership trajectories as electricity infrastructure improves against residual performance advantages of internal-combustion systems in remote deployment scenarios.
Market Dynamics
EPA emission standards for small gasoline engines are forcing manufacturers to accelerate electric powertrain development while maintaining hydraulic performance benchmarks that commercial forestry services demand.
Growth Catalysts
- OSHA Logging Safety Standards:Two-hand activation mandates and operator-guard requirements drive replacement cycles among commercial-grade equipment buyers in the United States.
- Electric Infrastructure Expansion:Rural electrification improvements and battery cost curves enable corded and battery-powered splitters to penetrate noise-restricted municipal parks and residential zones.
- Forestry Service Contracts:Municipal and corporate groundskeeping procurement volumes expand as outdoor property maintenance gains priority among institutional buyers.
Market Restraints
- Steel Input Volatility:Ram cylinders and structural frames face cost pressure from fluctuating alloy steel prices, compressing margins on mid-range hydraulic units.
- Gasoline Engine Supply Concentration:Small-engine manufacturing concentrates among a limited supplier base, creating vulnerability for gas-powered splitter assemblers.
- Battery Energy Density Limits:Lithium-ion cell performance constraints restrict electric splitter tonnage ratings below the threshold required for dense hardwood species.
Strategic Opportunities
- India Rural Electrification:Uneven grid access creates demand for manual and low-power electric splitters among off-grid agricultural communities processing fuelwood.
- Kinetic Flywheel Convergence:Mechanical energy storage systems combine with compact electric motors to deliver high-cycle-speed splitting without hydraulic fluid maintenance.
- Equipment-as-Service Models:Landscape contractors shift from ownership to rental platforms, opening recurring revenue streams for fleet operators.
Industry Challenges
- Hydraulic Technician Scarcity:Specialized repair skills for high-pressure ram systems limit service network expansion in remote deployment regions.
- EPA Certification Timelines:Catalytic converter integration and emission testing protocols extend product development cycles for gasoline-powered models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Log Splitters Market |
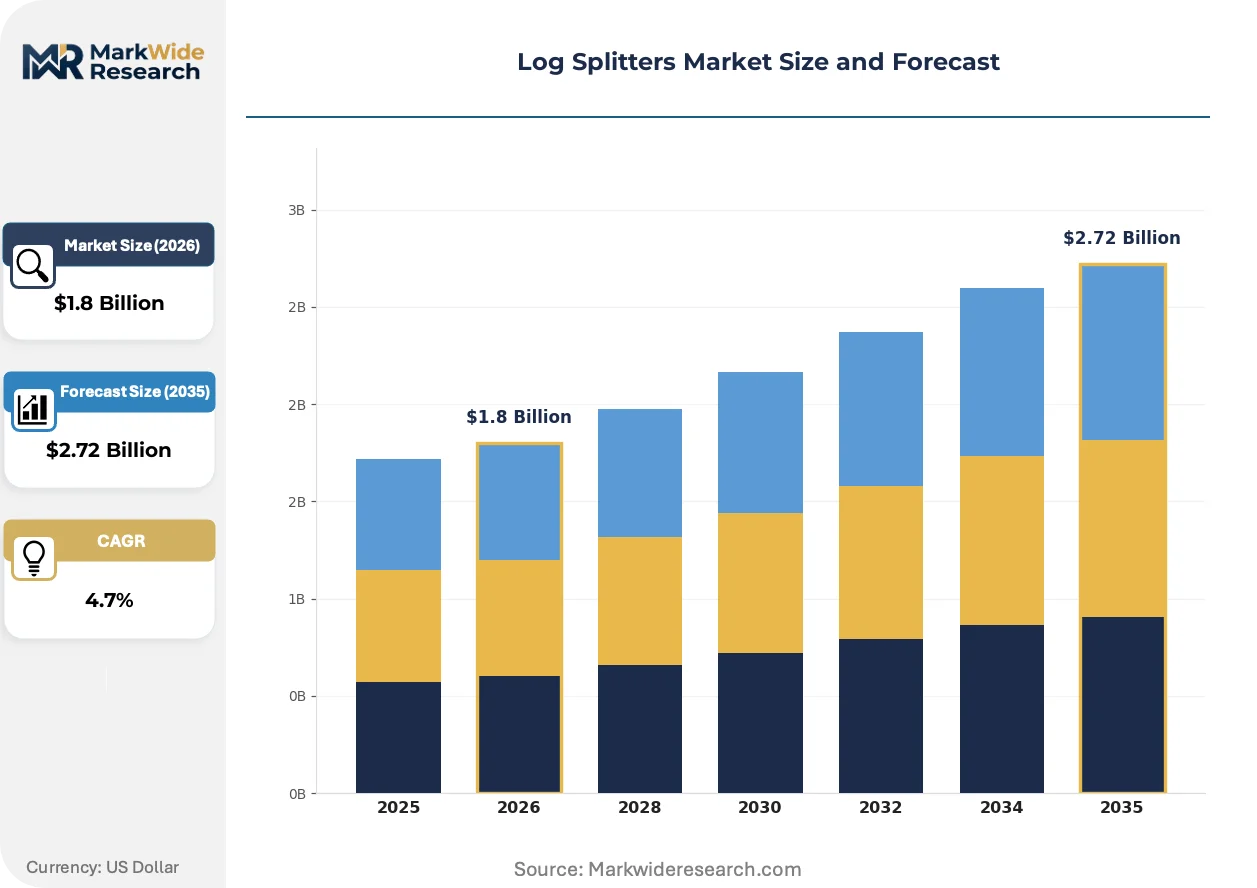
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Splitters, Electric Splitters, Gas-Powered Splitters, Hydraulic Splitters End User: Residential Users, Commercial Users, Forestry Services, Landscaping Services Power Source: Electric, Gasoline, Diesel, Manual Capacity: 5 Tons, 10 Tons, 20 Tons, 30 Tons |
| Companies Covered | Iron & Oak, PowerKing, Boss Industrial, TimberOX, Champion Power Equipment, Oregon, Brave, BruteForce USA, Detail K2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Log Splitters Market Emerging Trajectories
Automation and electrification are converging to reshape equipment specifications, while regulatory pressure and procurement model evolution compress traditional product lifecycles across residential and commercial segments.
Kinetic flywheel systems are automating cycle operations by storing rotational energy in weighted discs that release instantaneous splitting force without hydraulic pumps or engines. Commercial landscaping fleets in the United States are adopting these units for their reduced maintenance intervals and elimination of hydraulic fluid contamination risks. The technology is automating throughput optimization by enabling sub-three-second cycle times that match or exceed conventional hydraulic benchmarks.
REACH chemical substance restrictions in Europe constrain hydraulic fluid formulations and surface coating chemistries used in splitter manufacturing. Manufacturers must reformulate seal compounds and paint systems to maintain CE marking compliance for export markets. Forestry equipment distributors in Germany and France are prioritizing electric and kinetic models to sidestep ongoing regulatory friction with small-engine emission categories.
Rental platform penetration is altering ownership patterns among residential users who process firewood seasonally rather than maintaining year-round equipment. Big-box retailers and independent hardware cooperatives are expanding fleet availability, displacing traditional purchase decisions for occasional-use buyers. This shift concentrates most visibly in the United States, where rural property owners balance acquisition cost against utilization rates across heating seasons.
Log Splitters Market Segmentation
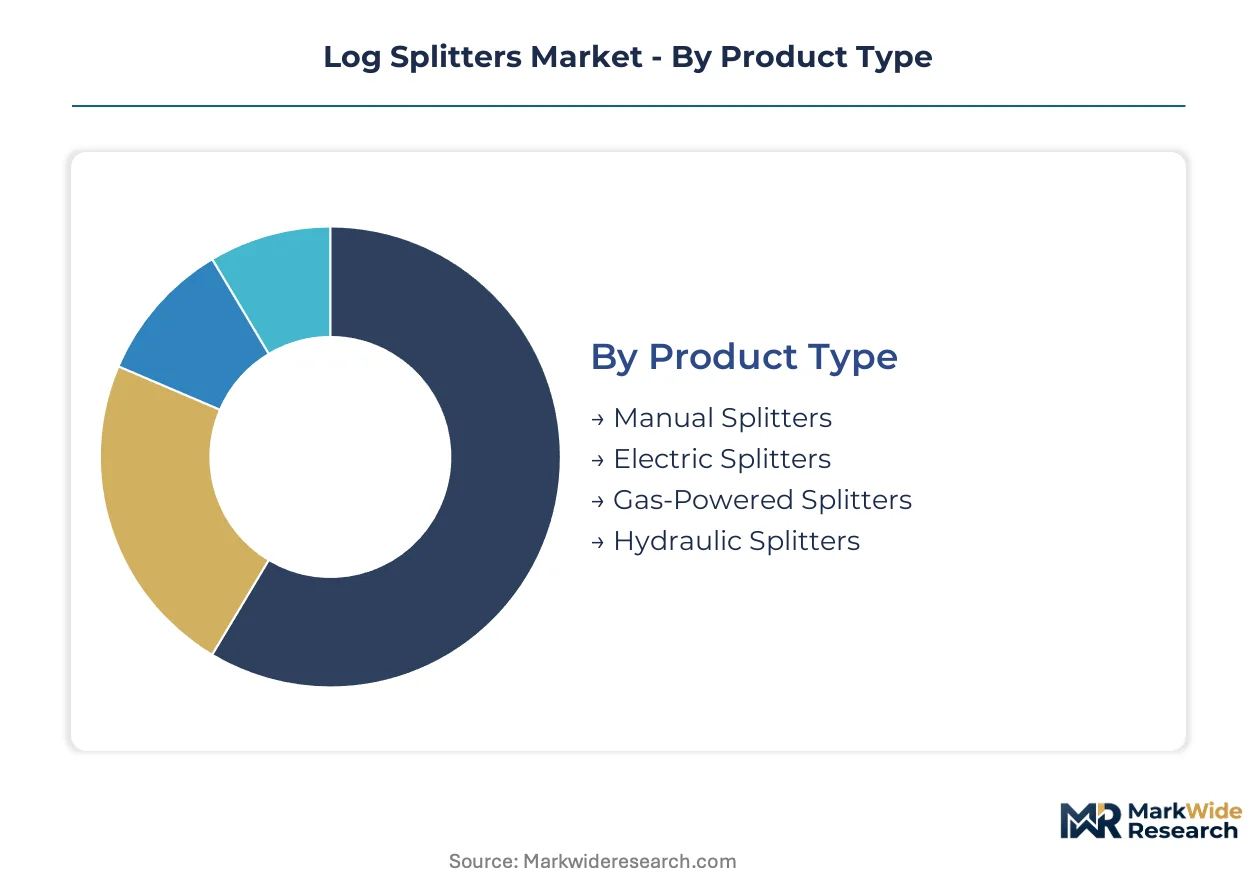
Equipment procurement patterns in the log splitter market diverge sharply across user types and power configurations. Replacement cycles accelerate where emission regulations tighten and commercial fleet operators prioritize throughput metrics over acquisition cost.
Product Type:
Upgrade trajectories vary by installed-base age and regional emission enforcement intensity, with electric models displacing gasoline units fastest in noise-restricted zones.
- Gas-Powered Splitters:Internal-combustion engines deliver twenty to thirty tons of ram pressure for dense hardwood processing. Demand concentrates among forestry services in the United States where remote deployment limits grid access and OSHA safety mandates drive replacement of pre-2010 equipment.
- Hydraulic Splitters:High-pressure fluid systems command premium positioning through cycle speed and tonnage ratings that determine commercial operational throughput. Landscaping services in municipal parks specify these units for sustained daily use despite higher maintenance intervals.
- Electric Splitters:Corded and battery-powered units operate at three to five tons for residential firewood preparation.
- Manual Splitters:Hand-operated wedges and screw drives serve off-grid users prioritizing portability.
Gas-Powered Splitters sits at the top of the volume ranking, with Electric Splitters climbing the fastest.
End User:
Cost tier separation between occasional residential use and intensive commercial deployment shapes specification requirements and ownership models.
- Landscaping Services:Municipal and corporate groundskeeping contracts specify mid-range electric and kinetic units for noise compliance. Procurement volumes expand as outdoor property maintenance gains priority among institutional buyers in the United States.
- Forestry Services:Professional timber operations demand thirty-ton hydraulic systems with sub-ten-second cycle times. Equipment replacement accelerates where EPA emission standards phase out non-catalytic gasoline engines.
- Commercial Users:Rental fleets and small contractors balance utilization rates against seasonal demand fluctuation.
- Residential Users:Homeowners processing heating fuel favor electric splitters for lower maintenance and reduced noise.
Landscaping Services dominates procurement volume, with Forestry Services expanding most quickly on contract awards.
Power Source:
Application context determines fuel choice, with grid availability and hardwood species density driving divergence between electric and combustion platforms.
- Gasoline:Small engines power the largest installed base despite EPA emission constraints forcing catalytic converter integration. Forestry services in rural United States counties specify these units where battery energy density limits electric alternatives.
- Electric:Corded and battery platforms penetrate municipal parks and residential zones where noise ordinances restrict combustion equipment. Infrastructure improvements in United States suburbs enable specification of higher-tonnage electric models previously limited to manual or gas options.
- Diesel:Compression-ignition engines serve commercial fleets requiring torque density for all-day operation.
- Manual:Human-powered systems retain residual demand among off-grid agricultural communities.
Gasoline retains the largest installed base, with Electric gaining share fastest on regulatory pressure and battery cost curves.
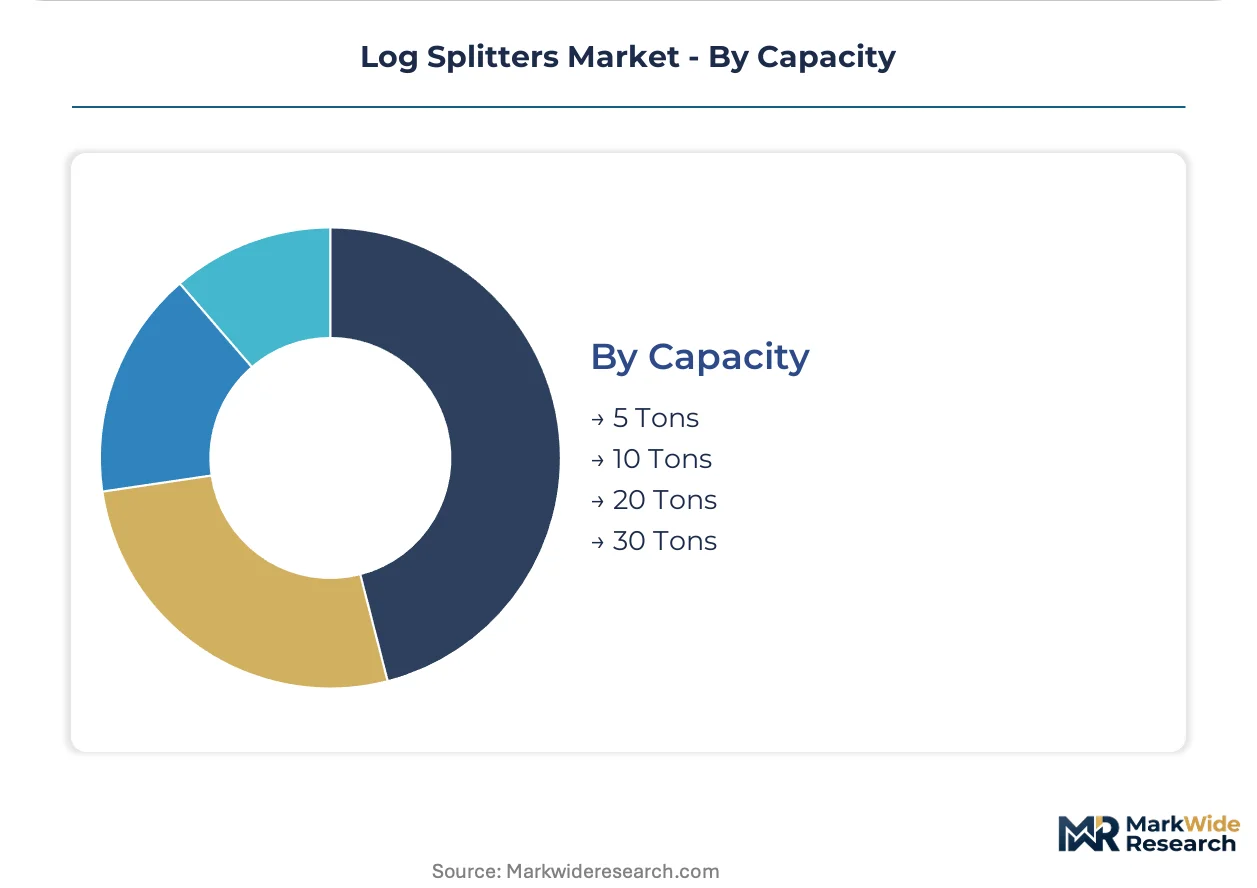
Capacity:
Volume tier alignment with wood species hardness and batch size determines specification, with commercial users oversizing to handle variable feedstock.
- 30 Tons:Maximum-pressure hydraulic systems fracture dense oak and hickory rounds exceeding twenty-four inches diameter. Forestry services in hardwood-dominated United States regions specify this tier for single-pass splitting efficiency.
- 20 Tons:Mid-commercial grade handles mixed hardwoods and softwoods for landscaping fleets with variable contract specifications. Demand concentrates among United States equipment rental platforms serving seasonal residential users upgrading from manual methods.
- 10 Tons:Light-commercial electric units process standard firewood dimensions for residential users with moderate hardwood requirements.
- 5 Tons:Entry-level electric splitters handle softwood and small-diameter rounds for occasional-use homeowners.
20 Tons sits at the top of the volume ranking, with 30 Tons climbing the fastest on commercial fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors log splitter fabrication and distribution networks, with foundries and hydraulic component suppliers clustering around industrial cities that serve both domestic and export demand.
United States
Rural property ownership and firewood heating traditions sustain consistent replacement cycles across the Midwest and Northeast. EPA small-engine emission standards are compelling manufacturers to integrate catalytic converters or pivot toward battery-electric platforms. Wisconsin and Ohio host concentrated fabrication facilities supplying commercial forestry contractors and municipal landscaping fleets.
Germany
Professional forestry services and stringent noise ordinances in municipal parks drive specification of kinetic flywheel and electric models. REACH chemical substance restrictions constrain hydraulic fluid formulations and surface coating chemistries for CE marking compliance. Equipment distributors in Bavaria and Baden-Württemberg prioritize electric alternatives to sidestep regulatory friction with small-engine emission categories.
Canada
Off-grid residential users and remote forestry operations create bifurcated demand between manual portability and high-tonnage hydraulic systems. Environment Canada emission guidelines parallel EPA frameworks, pressuring gas-powered model specifications. Ontario and Quebec manufacturing clusters supply both domestic seasonal heating markets and export channels into northern United States regions.
China
Export-oriented fabrication serves global price-sensitive segments while domestic rural electrification unevenness sustains manual splitter demand. MIIT industrial standards and GB certification requirements shape export-bound product specifications. Zhejiang and Shandong provinces concentrate component manufacturing for hydraulic rams and structural frames.
Australia
Hardwood species density and remote property scales necessitate high-capacity hydraulic systems for commercial timber operations. State-level environmental protection agencies enforce noise restrictions in peri-urban zones, accelerating electric model interest. Equipment distribution networks concentrate in New South Wales and Victoria, serving both agricultural fuelwood processors and professional forestry contractors.
Log Splitters Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance gasoline legacy platforms against electric powertrain development. The vendor base separates into three functional tiers: mass-market retailers with broad distribution networks, specialized hydraulic system fabricators serving commercial forestry, and integrated cutting-equipment specialists leveraging chainsaw expertise. Strategic archetypes include emission-compliant gasoline assemblers, battery-electric pioneers, and kinetic flywheel innovators. M&A activity and technology licensing agreements represent the primary competitive vectors as firms secure access to motor and battery supply chains.
Among North American equipment specialists, Champion Power Equipment and Boss Industrial exemplify divergent positioning strategies, with the former representing retail-channel scale and the latter anchoring professional-grade hydraulic engineering. Oregon occupies a distinctive position as an integrated cutting-system specialist extending expertise from chainsaws through splitting attachments. These three companies illustrate how competitive positioning fragments across distribution reach, technical specialization, and vertical integration into cutting-tool ecosystems.
| Leading Market Players |
|---|
| Iron & Oak |
| PowerKing |
| Boss Industrial |
| TimberOX |
| Champion Power Equipment |
| Oregon |
| Brave |
| BruteForce USA |
| Detail K2 |
| Others |
Supply Flow & Price Mechanics
Alloy steel price indices cascade through hydraulic ram cylinder fabrication into tiered equipment pricing, with spot volatility in structural-grade alloys compressing margins on mid-range units while premium hydraulic systems absorb cost pass-through via forestry service contract pricing.
Pricing Analysis
Input-cost pass-through from alloy steel and lithium-ion cells stratifies pricing across three performance tiers. Premium-mid-economy pricing differentiation separates thirty-ton hydraulic forestry systems from ten-ton electric residential units, with certification grade and after-sales service bundling as secondary drivers. Pricing pressure stems from steel input volatility that manufacturers cannot fully recover in competitive bid situations for municipal landscaping contracts. Residential buyers exhibit highest price sensitivity, while commercial forestry services prioritize tonnage ratings and cycle speed over acquisition cost.
Supply Chain Analysis
CE marking and EPA certification requirements gate supplier qualification, with hydraulic component manufacturing clustering in Wisconsin, Ohio, and Zhejiang province. Ram cylinders, structural frames, and small gasoline engines constitute critical input dependencies. Single-source vulnerability concentrates in small-engine supply bases limited by emission compliance capabilities. Distribution runs through big-box retail networks and independent equipment cooperatives serving seasonal residential demand alongside direct channels for commercial forestry procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Log splitters function as a stable compounder anchored by replacement-cycle predictability in rural heating markets and regulatory-forced equipment turnover under tightening emission standards.
For Market Incumbents: Cement market position through captive supply of hydraulic ram systems and emission-compliant powertrain engineering. Champion Power Equipment and Boss Industrial must defend against kinetic flywheel substitution by locking in municipal fleet service contracts. Backward integration into alloy steel sourcing hedges margin compression from commodity volatility. For New Entrants and Emerging Players: EPA small-engine emission standards in the United States open a window for battery-electric and kinetic flywheel specialists to capture landscaping services procurement. Target noise-restricted municipal parks in Germany and peri-urban Australia where combustion equipment faces de facto bans. Partner with rental platform operators for fleet placement rather than competing through retail channel buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where hydraulic technician scarcity limits service network expansion and emission compliance costs favor scaled R&D spending. Acquire specialists with kinetic flywheel IP or certified electric powertrain platforms. Monitor battery energy density breakthroughs as the inflection signal for electric models penetrating thirty-ton forestry applications.| Strategic Initiative | Industry Significance |
|---|---|
| Kinetic Flywheel Platform Launch | Sub-three-second cycle times displace hydraulic maintenance burdens in commercial landscaping fleets. |
| Battery Supply Agreement | Cell chemistry partnerships secure energy density improvements for twenty-ton electric model development. |
| CE Marking Pathway Investment | REACH-compliant fluid formulations and coatings unlock German and French forestry equipment distribution. |
| Equipment-as-Service Partnership | Rental platform alliances convert seasonal residential demand into recurring revenue streams. |
| Emission Certification Acceleration | EPA catalytic converter integration preserves gasoline model viability in remote United States deployment. |
Methodological Framework
Direct dialogue with forestry equipment distributors, municipal procurement officers, hydraulic component suppliers, and aftermarket service technicians grounded qualitative findings. Secondary validation drew from EPA emission certification databases, OSHA safety standard filings, customs trade records for alloy steel imports, and equipment rental platform utilization disclosures. Bottom-up unit economics triangulated against top-down market sizing across power source and capacity segmentations.
Installed base projections and replacement cycle modeling produced volume and value trajectories across the projection horizon. Segmentation dimensions included product type, end-user category, power source architecture, and tonnage capacity tier. CAGRs derived from regression analysis of historical procurement patterns against regulatory phase-in schedules and battery cost curve assumptions. Forestry service contract awards and rural electrification infrastructure buildout served as industry-specific forecast inputs.
Revisions become necessary when EPA emission standard timelines accelerate, lithium-ion energy density achieves commercial thirty-ton thresholds, or alloy steel price volatility exceeds historical bands. A model refresh is warranted upon material change in municipal landscaping procurement prioritization or kinetic flywheel reliability certification at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Indexable Inserts Market
Tools
Stationary Wood Planer Market
Tools
Global Protractor Market
Tools
Welding Guns Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Garden Digging Tools Market
Tools
Chainsaw Market
Tools
Crimping Tool Market
Tools
Trim Press Market
Tools
Fiber Laser Cutting Machines Market
Tools
Wire Cutters Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Broaching Tools Market
Tools
Machine Bench Vices Market
Tools
Turning Centers Market
Tools
Hand Tools Market