
 Cummene Derivatives Market | 2026-2036
Cummene Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Cummene Derivatives Market Analytics
Modular formulation bundling is restructuring how buyers procure cumene derivative grades, with integrated phenol-acetone packages displacing single-product contracts. INEOS Group Limited leverages its European phenol capacity to anchor long-term supply agreements with automotive resin makers. BASF SE sustains technology leadership through specialized high-purity grades for pharmaceutical synthesis. ExxonMobil Corporation competes on feedstock integration, controlling propylene supply chains that determine derivative cost structures.
Cumene derivatives comprise organic compounds manufactured through Friedel-Crafts alkylation of benzene with propylene, yielding primarily phenol and acetone via the Hock cumene peroxidation process with typical phenol-to-acetone molar ratios near 1:0.6. These intermediates serve as essential building blocks for bisphenol-A, polycarbonate resins, and solvent applications across industrial manufacturing. Phenol derivatives occupy the largest volume position due to entrenched demand from epoxy and polycarbonate value chains, while pharmaceutical-grade acetone extracts premium margins from stringent purity specifications. Plastics applications lead end-use consumption, though coatings demand accelerates fastest as waterborne formulations replace solvent-based systems in automotive and construction markets.
REACH registration requirements in Europe compel detailed substance dossiers for cumene and phenol imports, while EPA Toxic Substances Control Act reporting governs US manufacturing thresholds and emission controls. China's GB standards for chemical purity and MIIT industrial guidance on dual carbon goals reshape production technology choices for domestic cumene oxidation facilities. Stakeholders must monitor regulatory divergence between jurisdictions to optimize plant certification strategies and avoid supply disqualification in premium segments.
Market Dynamics
REACH compliance in Europe is forcing producers to restructure certification dossiers for phenol and acetone imports, while automotive resin makers in Asia-Pacific accelerate specification upgrades for polycarbonate feedstocks. This dual regulatory-demand pressure is compressing supplier qualification timelines and reshaping contract structures across derivative value chains.
Growth Catalysts
- Automotive lightweighting mandates:Polycarbonate resin specifications for electric vehicle battery housings are tightening across German and Japanese OEM supply chains, pulling high-purity bisphenol-A demand upward.
- REACH substance registration:ECHA's updated dossier requirements for cumene oxidation intermediates are standardizing purity benchmarks, enabling qualified European producers to capture premium pharmaceutical-grade acetone contracts.
- Waterborne coating conversions:Solvent replacement programs in automotive refinishing and construction applications are redirecting acetone demand toward low-VOC formulation systems.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker operating rates in Northeast Asia determine regional propylene spot pricing, transmitting cost instability directly into cumene oxidation economics.
- Concentrated phenol capacity:Three integrated petrochemical complexes control over half of European merchant phenol supply, creating bottleneck risk during unplanned maintenance events.
- Polycarbonate substitution:Bio-based polyamide compounds and recycled PET blends are capturing interior automotive panel applications previously served by bisphenol-A polycarbonate.
Strategic Opportunities
- Pharmaceutical-grade acetone expansion:Stringent USP and EP monograph compliance creates margin premiums for producers capable of sub-ppm impurity control in active pharmaceutical ingredient synthesis.
- India specialty chemical manufacturing:PLI scheme incentives for chemical intermediates are attracting cumene derivative investments serving domestic agrochemical and pharmaceutical formulation growth.
- Dual carbon alignment in China:MIIT industrial guidance on energy intensity reduction is rewarding cumene oxidation facilities with carbon capture integration and renewable power sourcing.
Industry Challenges
- Process safety engineering scarcity:Hock cumene peroxidation unit design and hazard analysis expertise concentrates among retiring specialists in European and North American engineering firms.
- Multi-jurisdiction certification lag:Parallel REACH, EPA TSCA, and China GB standard compliance timelines extend product qualification cycles by 18-24 months for new derivative grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cummene Derivatives Market |
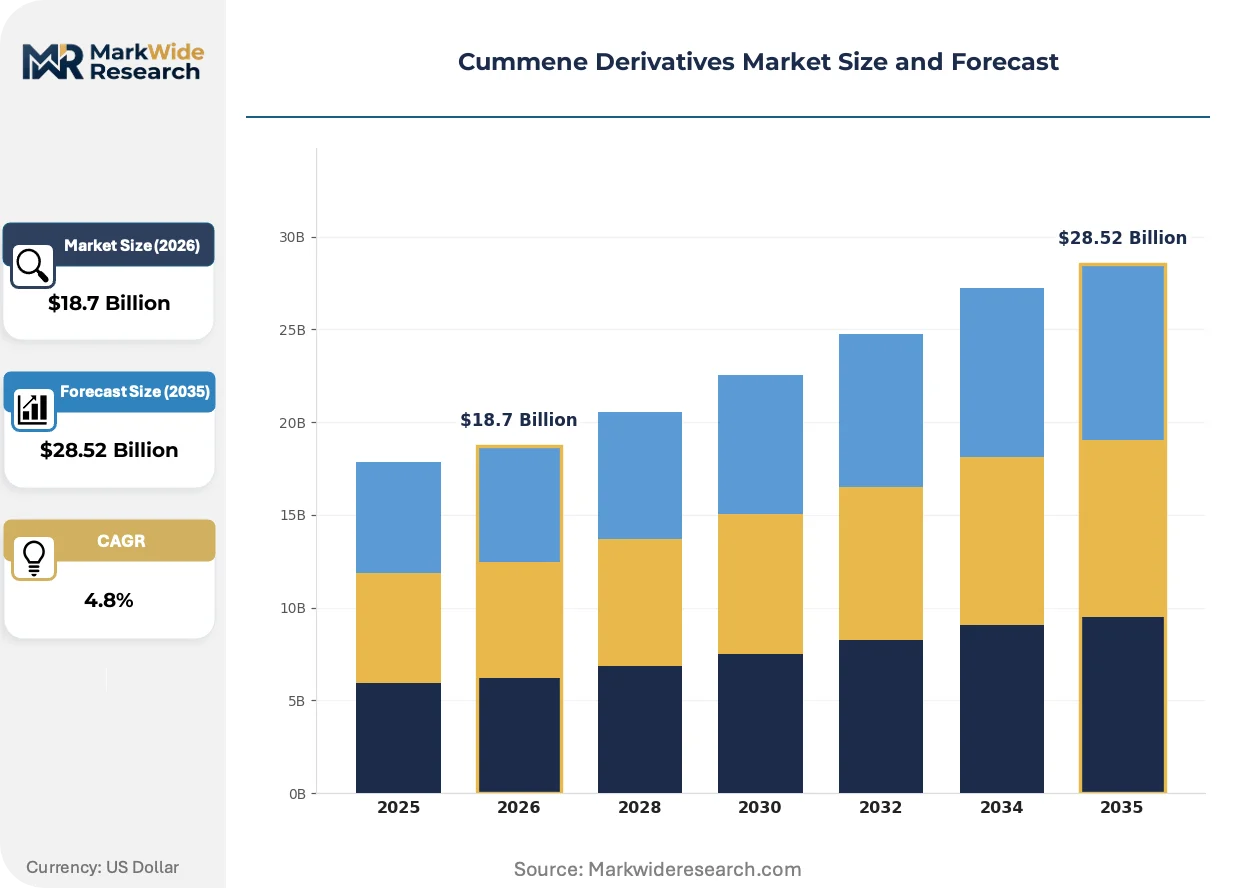
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenol, Acetone, Cumenes, Others Application: Plastics, Adhesives, Coatings, Pharmaceuticals End User: Manufacturing, Automotive, Construction, Healthcare Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | Eastman Chemical Company, Merck KGaA, Tokyo Chemical Industry, INEOS Group Limited, BASF SE, ExxonMobil Corporation, Royal Dutch Shell plc, SABIC, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cummene Derivatives Market Evolving Landscape
Process intensification and digital control systems are compressing cumene oxidation unit footprints while regulatory data automation is reshaping how producers manage multi-jurisdiction compliance obligations. These forces are converging to separate capital-efficient operators from legacy asset holders.
Advanced process control software is automating temperature and pressure management across cumene peroxidation reactors, reducing off-specification batches and catalyst consumption. European and Northeast Asian producers with integrated refining-petrochemical complexes are deploying these systems fastest. This automation is compressing the operating cost gap between world-scale integrated facilities and smaller merchant producers.
ECHA's SCIP database requirements for articles containing substances of very high concern are extending downstream into polycarbonate and epoxy resin supply chains. Manufacturers must now disclose phenol derivative content in finished goods imported into the European Union. Automotive and electronics OEMs are responding by tightening supplier certification protocols and demanding batch-level traceability documentation.
Integrated phenol-acetone procurement contracts are displacing single-product spot purchases among large polycarbonate and bisphenol-A manufacturers. This bundling concentrates purchasing power with buyers capable of absorbing volume minimums across both derivative streams. The shift is most visible in German and Chinese automotive resin supply chains, where long-term offtake agreements now lock in three-to-five-year pricing structures.
Cummene Derivatives Market Segmentation
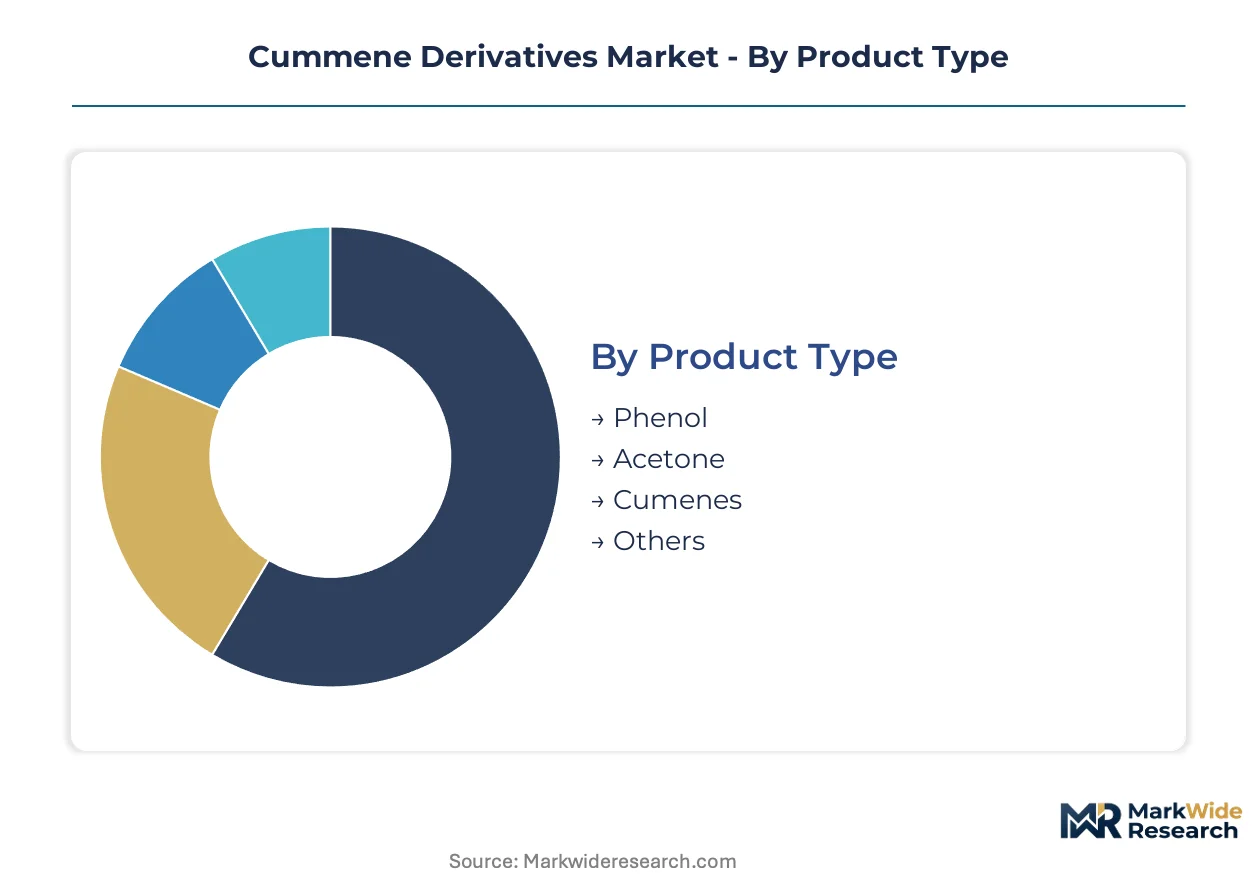
Cumene derivative procurement patterns diverge sharply across product grades and end-use specifications. Automotive resin makers, pharmaceutical formulators, and construction chemical distributors each impose distinct purity, volume, and delivery requirements that reshape supplier positioning.
Product Type:
Purity thresholds and oxidation process economics separate commodity grades from specialty offerings.
- Phenol:Industrial-grade phenol serves as the primary feedstock for bisphenol-A and epoxy resin synthesis, with specifications tightening for polycarbonate-grade material in German and Japanese automotive supply chains. Merchant phenol availability concentrates around integrated refinery-petrochemical complexes in Belgium, the Netherlands, and Singapore.
- Acetone:Pharmaceutical-grade acetone commands specification premiums for USP and EP monograph compliance in active pharmaceutical ingredient synthesis, while technical-grade material saturates solvent and methyl methacrylate feedstock markets. Purity differentiation separates contract pricing tiers by an order of magnitude.
- Cumenes:Unoxidized cumene functions as a solvent in specialty coatings and as an intermediate for detergent-grade alkylates, with demand anchored in US Gulf Coast refining corridors.
- Others:Minor oxidation byproducts including alpha-methylstyrene and acetophenone find niche application in polymer modifiers and fragrance intermediates.
Mature deployment sits with phenol. Newer deployment is concentrated in pharmaceutical-grade acetone.
Application:
End-use performance requirements determine formulation specifications and certification burdens.
- Plastics:Polycarbonate resin production consumes the largest phenol derivative volumes, with bisphenol-A specifications tightening for electric vehicle battery housing applications across German OEM supply chains.
- Coatings:Waterborne formulation conversions in automotive refinishing and construction are redirecting acetone demand toward low-VOC systems, with regulatory pressure from EPA and ECHA accelerating specification changes.
- Adhesives:Epoxy and phenolic resin systems for structural bonding rely on consistent phenol quality for cure kinetics control in aerospace and wind turbine manufacturing.
- Pharmaceuticals:Acetone extraction and crystallization processes for active pharmaceutical ingredients impose sub-ppm impurity limits, with batch-level traceability documentation now mandatory for EU market access under ECHA SCIP database requirements.
Volume concentration rests with plastics. Steepest specification evolution is occurring in coatings.
End User:
Procurement scale and technical integration depth vary systematically across customer categories.
- Automotive:Tier-1 resin suppliers to German and Japanese OEMs negotiate integrated phenol-acetone offtake agreements with three-to-five-year pricing structures, locking in volume commitments across both derivative streams.
- Manufacturing:Diversified chemical processors including bisphenol-A and methyl methacrylate producers absorb merchant phenol and acetone in proportion to downstream operating rates.
- Construction:Epoxy flooring and coating formulators purchase technical-grade phenol and acetone through distributors, with demand cyclicality tied to residential and commercial building permits.
- Healthcare:Pharmaceutical manufacturers impose the most stringent supplier qualification protocols, with multi-jurisdiction certification cycles extending 18-24 months for new acetone grades.
Contract sophistication peaks with automotive. Qualification burden is heaviest in healthcare.
Distribution Channel:
Supply chain configuration reflects order scale, specification complexity, and geographic concentration.
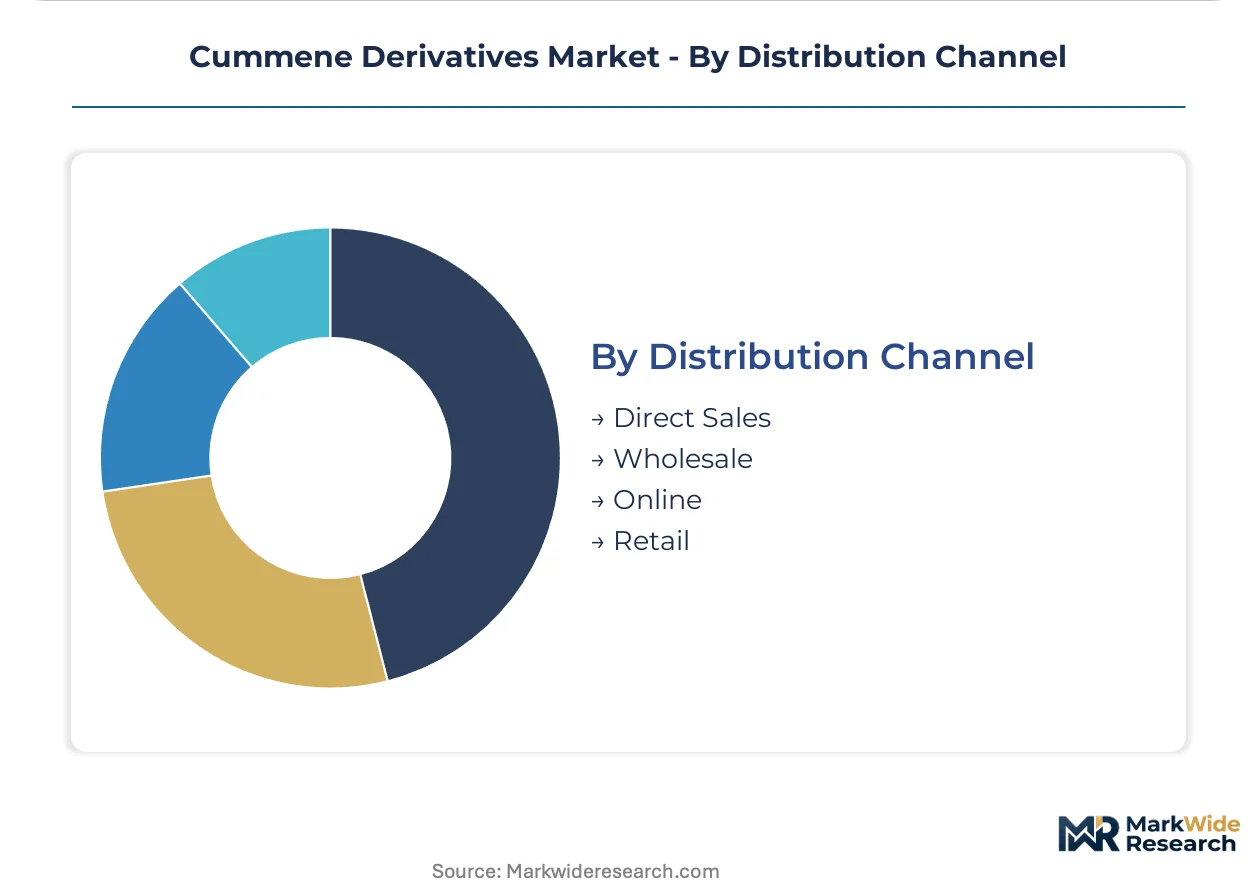
- Direct Sales:World-scale polycarbonate and bisphenol-A producers source phenol-acetone bundles through direct negotiations with integrated cumene oxidation operators, bypassing intermediaries for volume commitments exceeding 50,000 metric tons annually.
- Wholesale:Regional distributors maintain inventory positions for construction chemical and coating formulators requiring smaller lot sizes and flexible delivery scheduling.
- Online:Digital procurement platforms are emerging for standardized technical-grade acetone and phenol in North American and European spot markets, though pharmaceutical-grade material remains offline due to documentation requirements.
- Retail:Packaged solvents for laboratory and small-scale industrial use move through specialty chemical retailers with limited relevance to bulk derivative economics.
Volume concentration aligns with direct sales. Channel experimentation is advancing fastest online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces drive cumene derivative concentration, with bonded chemical parks offering duty exemptions on propylene feedstock imports. This incentive architecture pulls phenol-acetone capacity toward integrated refining corridors.
China
Polycarbonate production for electric vehicle battery housings consumes expanding phenol volumes across Jiangsu and Zhejiang provinces. MIIT industrial guidance on dual carbon goals rewards cumene oxidation facilities with carbon capture integration. The Yangtze River Delta chemical cluster anchors domestic acetone supply chains serving pharmaceutical formulation growth.
Germany
Automotive resin makers in Bavaria and Baden-Württemberg negotiate integrated phenol-acetone offtake agreements with three-to-five-year pricing structures. ECHA's updated REACH dossier requirements for cumene oxidation intermediates standardize purity benchmarks. The Antwerp-Rotterdam chemical corridor supplies merchant phenol to German polycarbonate compounders.
United States
Gulf Coast refineries control propylene supply chains determining cumene oxidation economics across Texas and Louisiana. EPA Toxic Substances Control Act reporting governs manufacturing thresholds and emission controls for phenol and acetone production. The Houston Ship Channel concentration enables backward integration into feedstock sources.
India
PLI scheme incentives for chemical intermediates attract cumene derivative investments serving domestic agrochemical and pharmaceutical formulation expansion. BIS standards for chemical purity reshape product certification requirements for imports. Gujarat's Dahej and Mundra port zones concentrate new phenol-acetone capacity serving specialty chemical manufacturing.
Japan
Polycarbonate resin specifications for automotive lightweighting tighten across Toyota and Honda supply chains, pulling high-purity bisphenol-A demand upward. METI industrial standards govern energy intensity benchmarks for cumene oxidation facilities. The Keiyo coastal industrial zone maintains integrated phenol-acetone production for electronics-grade polycarbonate.
Cummene Derivatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market structure concentrates around integrated petrochemical operators controlling propylene feedstock and merchant phenol distribution. Three strategic archetypes dominate: integrated refinery-petrochemical complexes, specialty chemical pure-plays, and diversified multinational chemical conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements to lock in volume commitments.
Among European-based integrated operators, INEOS Group Limited and BASF SE exemplify the refinery-petrochemical archetype with captive phenol-acetone production. ExxonMobil Corporation anchors the diversified energy-chemical conglomerate tier, leveraging upstream control over propylene supply chains. These three companies occupy positions spanning feedstock integration through derivative distribution, representing the scale-driven end of competitive positioning.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Merck KGaA |
| Tokyo Chemical Industry |
| INEOS Group Limited |
| BASF SE |
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| SABIC |
| Sumitomo Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Tier-1 automotive resin suppliers in Germany and Japan anchor contract negotiations for integrated phenol-acetone bundles, locking in three-to-five-year pricing structures that compress spot market liquidity for merchant producers. This buyer concentration rewards backward-integrated operators with captive propylene supply while squeezing standalone oxidation facilities.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade acetone separate emergency procurement pricing from standard contract tiers in active pharmaceutical ingredient supply chains. Three-tier pricing structure across pharmaceutical, technical, and solvent grades separates contract pricing by an order of magnitude based on USP and EP monograph compliance. Cost compression in technical-grade acetone is intensifying because polycarbonate compounders in China are consolidating purchasing power through bundled offtake agreements. Construction chemical distributors show highest price sensitivity due to cyclical demand tied to building permits, while healthcare formulators accept premium pricing for batch-level traceability documentation.
Supply Chain Analysis
Regional distribution centers in Belgium, the Netherlands, and Singapore concentrate merchant phenol inventory positions for European and Asia-Pacific compounders. Manufacturing gravity centers on China, Germany, and the United States, with cumene oxidation facilities clustering around integrated refining-petrochemical complexes. Propylene feedstock draws from naphtha cracker operating rates in Northeast Asia, benzene supply from aromatics extraction units, and hydrogen peroxide for the Hock process. Single-source vulnerability concentrates around three European petrochemical complexes controlling over half of merchant phenol supply. Distribution runs through direct sales for volume buyers exceeding fifty thousand metric tons annually, with wholesale channels serving smaller construction chemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around feedstock-integrated operators as propylene volatility and REACH compliance costs force merchant producers toward joint ventures or exit. Margin compression in technical-grade derivatives is accelerating the winnowing of standalone oxidation facilities lacking captive raw material supply.
For Market Incumbents: Hedge against polycarbonate substitution by deepening pharmaceutical-grade acetone certification investments and securing long-term propylene supply agreements with Northeast Asian naphtha crackers. Carbon capture integration at European facilities addresses MIIT dual carbon alignment requirements while defending premium positioning against Chinese imports. Backward integration into propylene supply remains the critical lever for cost structure defense. For New Entrants and Emerging Players: Capture white-space opportunity in India's pharmaceutical-grade acetone market under PLI scheme incentives for chemical intermediates, where domestic agrochemical and API formulation growth outpaces local supply. Gujarat's Dahej and Mundra port zones offer infrastructure for import-substitution plays with lower qualification burdens than European REACH markets. Partner with established distribution networks rather than building direct sales capabilities from inception. For Investors and Strategic Acquirers: The window for entry favors mid-scale cumene oxidation facilities with partial backward integration and existing pharmaceutical-grade certification infrastructure. Long-term viability hinges on feedstock security and regulatory compliance automation rather than scale alone. Watch for carbon border adjustment mechanism implementation in Europe as the signal for accelerated asset stranding in high-emission oxidation facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene supply from Gulf Coast refineries insulates margin volatility from naphtha cracker rate fluctuations. |
| Pharmaceutical-Grade Certification | USP and EP monograph compliance unlocks tenfold pricing premiums in active pharmaceutical ingredient synthesis. |
| Carbon Capture Integration | MIIT dual carbon guidance rewards cumene oxidation facilities with renewable power sourcing and emissions reduction. |
| Long-term Supply Agreement | Three-to-five-year phenol-acetone bundles with German automotive resin makers lock in volume commitments across derivative streams. |
| Joint Venture Formation | Partnerships with Northeast Asian propylene producers share capital burden for new oxidation capacity in bonded chemical parks. |
Research Methodology
Trade databases, SEC 10-K filings, and ECHA registration dossiers formed the secondary backbone, supplemented by customs records from major phenol-acetone importing jurisdictions. Primary interviews with plant managers at integrated cumene oxidation facilities, procurement leads at polycarbonate compounders, and distribution channel partners in construction chemicals validated operational assumptions. Bottom-up capacity modeling triangulated against top-down consumption estimates from end-use industry associations across the analysis window.
Historical trendline analysis of phenol-acetone operating rates, feedstock cost correlations, and regulatory implementation timelines informed the projection framework. Segmentation modeling incorporated product grade tier, end-use industry concentration, and regional production hub dynamics. CAGRs derived from slope analysis of volume trajectories adjusted for capacity addition schedules and demand elasticity in plastics versus pharmaceutical applications. Forecast inputs included electric vehicle battery housing specification evolution and waterborne coating conversion rates in automotive refinishing.
The model holds under stable propylene feedstock availability and gradual REACH dossier implementation; deviation in naphtha cracker operating rates or accelerated carbon border adjustments would shift derivative economics substantially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Tartaric Acid Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Potassium Fluoride Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
United Kingdom Methanol Market
Chemicals
RDX and HMX Market
Chemicals
Calcium Carbide Market
Chemicals
Phenylethyl Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Para Cresol Market
Chemicals
Sodium Ethylate Market
Chemicals
Sodium Azide Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
P-Ethylphenol Market