
 Non-Halogenated Flame Retardant Chemicals Market | 2026-2036
Non-Halogenated Flame Retardant Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Halogenated Flame Retardant Chemicals Market Outlook
A capital-intensity divergence between integrated alumina hydrate producers and specialty phosphorus compound developers is reorganizing competitive tiers in flame retardant supply. Huber Engineered Materials leverages captive bauxite refining and precipitated hydrate capacity to anchor North American construction and electrical demand. Albemarle Corporation competes through mineral-based product breadth and positions its downstream flame retardant portfolio for automotive and aerospace qualification pathways.
Non-halogenated flame retardant chemicals comprise phosphorus, nitrogen, mineral, and polymeric compounds formulated to suppress combustion without releasing corrosive halogenated gases, typically achieving UL 94 V-0 ratings at loadings between 30 and 65 percent by weight in thermoplastic matrices. These materials serve primarily to meet fire safety codes in electrical enclosures, transportation interiors, and structural building components while preserving mechanical properties and recyclability. Phosphorus-based systems command the widest formulation flexibility across engineering polymers, though mineral-based grades dominate volume in commodity wire and cable applications where cost thresholds are stringent. Polymeric flame retardants attract premium positioning in electronics and aerospace end users where migration resistance and thermal stability justify higher unit economics.
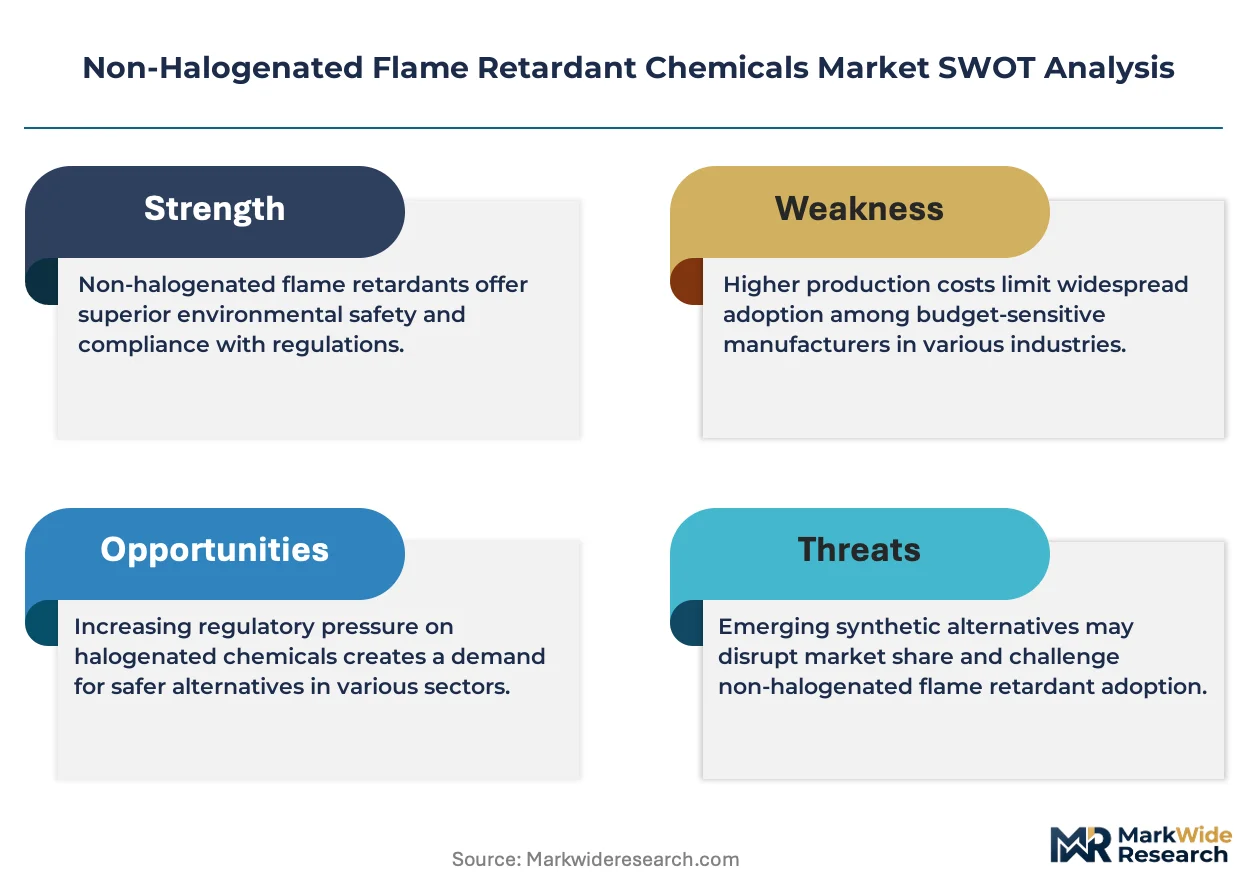
REACH restrictions in Europe and EPA assessments under the Toxic Substances Control Act in the United States constrain legacy halogenated chemistries and redirect certification investments toward non-halogenated alternatives. China's GB standards for building fire safety and MIIT directives on electronic product environmental requirements accelerate domestic qualification timelines for phosphorus and mineral formulations. Stakeholders must monitor regulatory convergence between EU Green Deal implementation and emerging state-level restrictions in the United States to anticipate specification lock-ins that will determine long-term formulation commitments and capital allocation priorities.
Market Dynamics
REACH restrictions on halogenated compounds and EPA assessments under the Toxic Substances Control Act are redirecting formulation investments toward phosphorus-based and mineral-based alternatives, compressing qualification timelines and reorganizing supply chain commitments across electrical and construction end uses.
Growth Catalysts
- REACH Phase-Out Directives:European ECHA restrictions on brominated and chlorinated flame retardants are mandating reformulation in wire and cable sheathing, pulling mineral hydrate and phosphorus ester volumes upward.
- China GB Fire Safety Standards:Domestic building codes tightening flame spread requirements in high-rise construction are absorbing expanded alumina hydrate and magnesium hydroxide tonnage from regional suppliers.
- Electric Vehicle Battery Enclosures:Thermal runaway protection specifications in automotive OEM supply chains are specifying intumescent phosphorus coatings for polypropylene battery housings.
Market Restraints
- Alumina Hydrate Loading Thresholds:Mineral-based systems require 50-65 weight percent loadings to achieve UL 94 V-0 ratings, degrading mechanical properties in thin-wall electrical enclosures.
- Bauxite Refining Concentration:Captive hydrate supply concentrates among integrated alumina producers, limiting formulation flexibility for specialty compounders without backward integration into bauxite processing.
- Phosphorus Raw Material Volatility:Yellow phosphorus and phosphoric acid feedstock costs fluctuate with Chinese energy policy and export quota adjustments, compressing margin stability for phosphorus ester manufacturers.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for domestic mobile and IT hardware manufacturing are accelerating local qualification of non-halogenated compounds for enclosure applications.
- Polymeric Flame Retardant Migration Resistance:Reactive oligomeric systems covalently bound to polymer matrices are opening specification pathways in aerospace interiors where volatility and leaching are disqualifying.
- EU Green Deal Circular Economy Requirements:Recyclability mandates for automotive and electronics plastics are favoring non-halogenated systems that preserve polymer recovery value versus legacy brominated chemistries.
Industry Challenges
- UL 94 V-0 Certification Timelines:Reformulation cycles for new polymer-flame retardant combinations require 12-18 month testing protocols, delaying commercialization and locking in incumbent supplier relationships.
- Compounding Equipment Retrofit Costs:High mineral loadings demand twin-screw extruder torque upgrades and downstream feeding system modifications, raising capital barriers for mid-volume compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Halogenated Flame Retardant Chemicals Market |
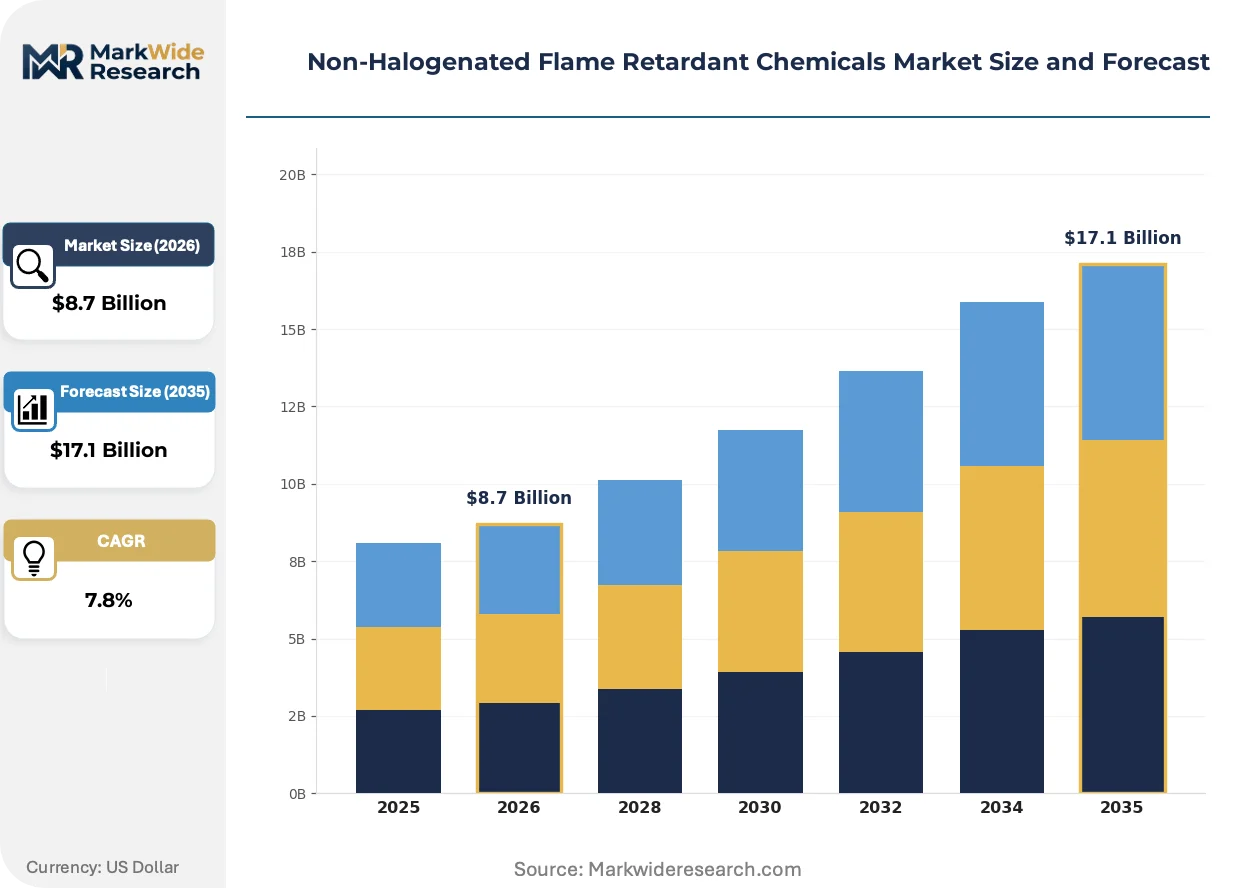
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphorus-Based, Nitrogen-Based, Mineral-Based, Polymeric Application: Automotive Interiors, Electronics, Textiles, Building Materials End User: Aerospace, Construction, Consumer Goods, Electrical Form: Granular, Liquid, Powder, Coating |
| Companies Covered | Nabaltec AG, Huber Engineered Materials, BASF SE, ICL, Clariant, Albemarle Corporation, Lanxess, Italmatch Chemicals, FRX Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Halogenated Flame Retardant Chemicals Market Strategic Shifts
Formulation science is pivoting toward synergistic mineral-phosphorus hybrids and reactive polymeric systems that resolve the mechanical-property tradeoffs of legacy loadings. These advances are compressing the performance gap between commodity mineral fillers and premium phosphorus compounds.
Intumescent phosphorus-nitrogen systems are displacing traditional halogenated additives in polyolefin wire and cable applications. European cable manufacturers are adopting these systems ahead of REACH deadlines. The displacement is compressing the addressable market for brominated alternatives in electrical infrastructure.
ECHA's restriction roadmap for medium-chain chlorinated paraffins and selected brominated diphenyl ethers is forcing reformulation in polyurethane foams and epoxy electrical laminates. German automotive suppliers are accelerating qualification of phosphorus-based reactive systems for interior foams. The regulatory pressure is shifting specification authority from compounders to OEM material engineering teams.
Specification-driven procurement now dominates flame retardant selection in electronics and automotive supply chains. Tier-1 enclosure manufacturers are consolidating supplier bases around compounders with pre-qualified UL and OEM platform certifications. The consolidation is most visible in South Korean and Taiwanese electronics manufacturing clusters where vendor reduction programs are eliminating non-certified regional suppliers.
Non-Halogenated Flame Retardant Chemicals Market Segmentation
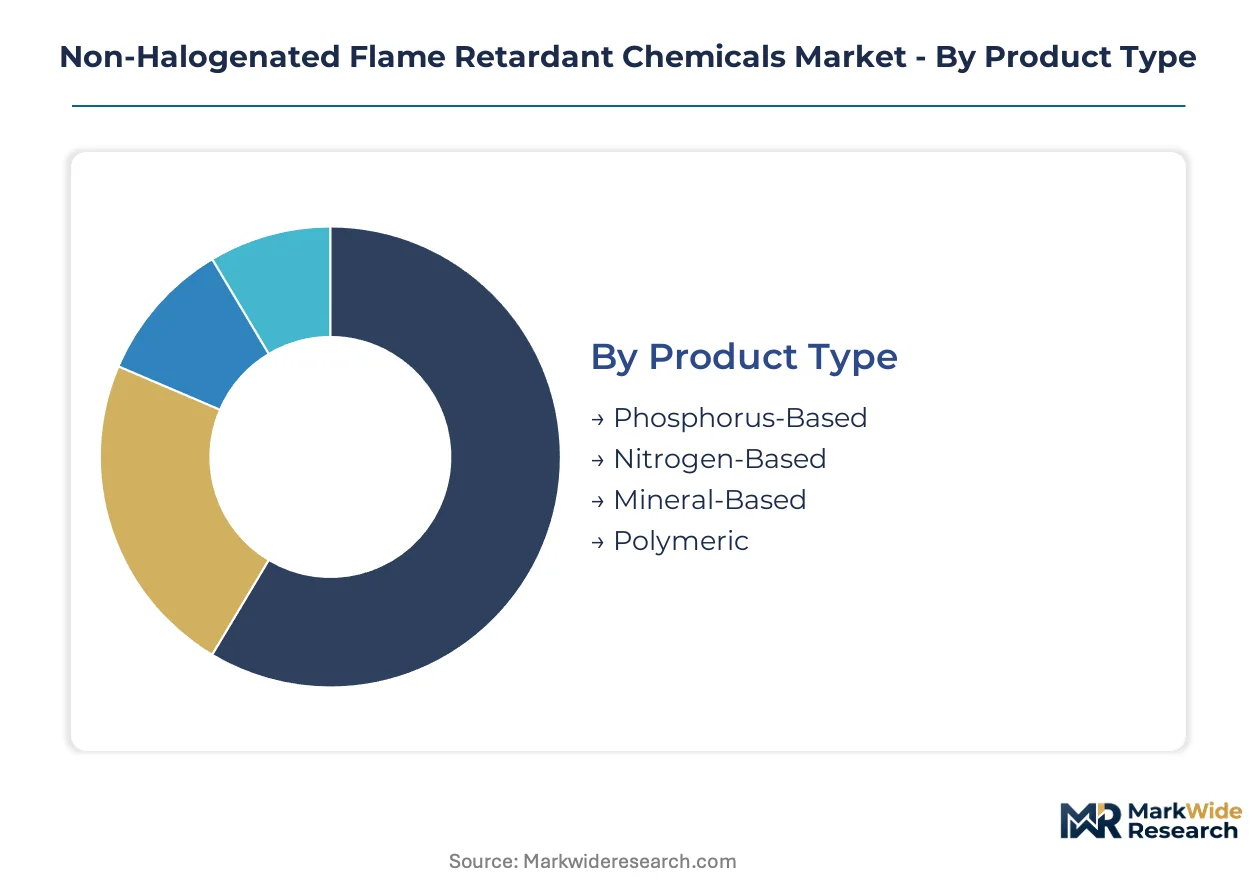
Segmentation in non-halogenated flame retardants reveals how substitution pressures and regulatory deadlines concentrate investment across chemistry classes and application tiers. Understanding these divisions clarifies where formulation flexibility commands premium positioning versus where mineral loadings dominate on cost.
Product Type:
Phosphorus-based and mineral-based systems face divergent substitution threats from emerging polymeric and hybrid chemistries, with mineral grades most vulnerable to mechanical-property limitations in thin-wall applications.
- Phosphorus-Based:Organophosphorus esters and phosphinates achieve UL 94 V-0 ratings at 15-25 percent loadings in engineering polymers like polycarbonate and polyamide. Electrical enclosure manufacturers in Germany and South Korea specify these systems for laptop housings and server chassis where thin-wall design tolerances exclude mineral alternatives.
- Mineral-Based:Alumina trihydrate and magnesium hydroxide release water vapor endothermically to suppress combustion, requiring 50-65 weight percent incorporation. Chinese wire and cable compounders absorb the largest mineral volumes for building infrastructure applications where cost thresholds override mechanical constraints.
- Nitrogen-Based:Melamine derivatives and guanidine compounds function through intumescent char formation in polyolefin matrices. Textile coating applications in Turkey and Vietnam drive modest nitrogen system volumes.
- Polymeric:Reactive oligomeric phosphorus compounds covalently bound to polymer backbones eliminate migration and leaching risks. Aerospace interior specifications from Boeing and Airbus qualification pathways pull polymeric adoption upward.
Mineral-Based anchors the volume base while Polymeric gains share at the steepest rate.
Application:
Cost tier stratification separates commodity building materials from specification-driven electronics and automotive segments, with certification burden determining margin capture.
- Electronics:Printed circuit board laminates, connector housings, and enclosure plastics require V-0 ratings with minimal impact on dielectric properties. Taiwan-based OEMs and South Korean contract manufacturers consolidate procurement around pre-qualified phosphorus compounders with established UL certifications.
- Automotive Interiors:Polyurethane foams, polypropylene panels, and epoxy composites must meet FMVSS 302 flammability standards while preserving low fogging characteristics. German automotive suppliers accelerate phosphorus-based reactive system qualifications ahead of ECHA restriction deadlines.
- Building Materials:Wire and cable sheathing, insulation boards, and structural panels absorb mineral hydrate volumes at the lowest per-kilogram pricing. Chinese GB standard compliance mandates drive regional procurement concentration.
- Textiles:Synthetic fiber treatments and technical fabric coatings employ nitrogen-phosphorus synergies for upholstery and protective apparel. Italian and Portuguese textile finishers represent concentrated demand nodes.
Building Materials commands the lowest unit economics while Electronics captures the steepest margin expansion trajectory.
End User:
Customer type diversity spans specification-heavy OEMs and price-sensitive commodity buyers, with procurement authority shifting toward material engineering teams at tier-1 suppliers.
- Electrical:Wire and cable manufacturers, switchgear producers, and transformer suppliers specify flame retardants across voltage classes and insulation ratings. Indian CEA wiring regulations and Chinese GB standards tighten simultaneously, compressing qualification windows.
- Construction:Insulation producers, roofing membrane fabricators, and structural composite manufacturers prioritize cost-efficient mineral systems. Turkish and Polish building material exporters absorb expanding hydrate tonnage for European project specifications.
- Aerospace:Cabin interior panels, cargo liners, and insulation blankets demand FAR 25.853 compliance with stringent smoke and toxicity limits. Montreal and Toulouse aerospace clusters specify polymeric systems exclusively.
- Consumer Goods:Appliance housings, furniture foams, and packaging materials face fragmented regulatory oversight with variable enforcement. Brazilian and Mexican appliance assemblers represent emerging qualification activity.
Construction anchors volume absorption while Aerospace climbs the fastest on value-per-kilogram metrics.
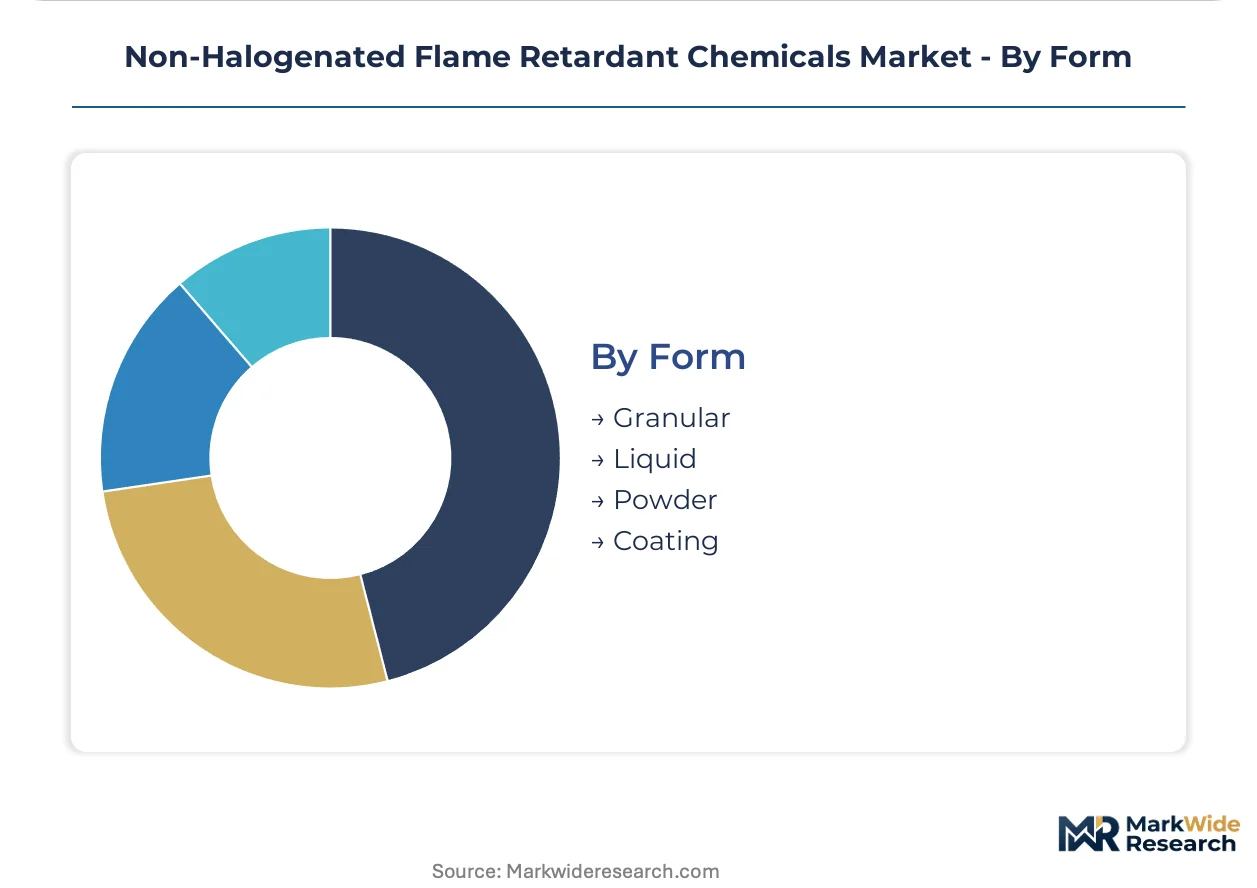
Form:
Supply concentration in powder processing equipment creates entry barriers for liquid and coating specialists, with granular form factors dominating compounding infrastructure.
- Powder:Dry-blended mineral hydrates and pulverized phosphorus compounds feed directly into single-screw and twin-screw extrusion lines. Huber Engineered Materials and Albemarle Corporation anchor North American powder supply.
- Liquid:Phosphorus ester solutions and emulsions enable spray application and reactive injection molding processes. German and Japanese automotive suppliers specify liquid intumescent coatings for battery enclosure manufacturing.
- Granular:Agglomerated formulations reduce dust generation and improve feeding consistency in high-throughput compounding operations. Chinese wire and cable compounders prefer granular mineral grades for automated handling systems.
- Coating:Film-forming intumescent systems applied as surface treatments to finished components. French and Italian steel fabricators adopt coating formulations for structural fire protection in commercial construction.
Powder retains the broadest installed base while Coating expands most quickly in battery and aerospace niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in wire and cable applications exhibit acute price sensitivity, absorbing mineral hydrate volumes at thin margins, while electronics and aerospace OEMs prioritize specification compliance over unit cost, creating a demand-elasticity divide that shapes regional investment patterns.
China
Domestic wire and cable manufacturers consume expanding alumina hydrate tonnage for building infrastructure under tightening GB fire safety standards. MIIT directives on electronic product environmental requirements compress qualification timelines for phosphorus formulations. The Yangtze River Delta concentration of compounders pulls supply chain commitments toward regional mineral processors.
Germany
Automotive suppliers accelerate phosphorus-based reactive system qualifications for interior foams ahead of ECHA restriction deadlines. REACH Phase-Out Directives mandate reformulation in polyurethane foams and epoxy electrical laminates. The Cologne-Düsseldorf industrial corridor hosts concentrated material engineering teams shifting specification authority from compounders to OEMs.
United States
Construction and electrical demand anchors North American mineral hydrate consumption, with EPA assessments under the Toxic Substances Control Act constraining legacy halogenated chemistries. Huber Engineered Materials leverages captive bauxite refining capacity to serve regional building material specifications. The Gulf Coast petrochemical corridor feeds downstream flame retardant formulation infrastructure.
India
Production-linked incentives for domestic mobile and IT hardware manufacturing accelerate local qualification of non-halogenated compounds for enclosure applications. CEA wiring regulations tighten simultaneously with Chinese GB standards, compressing qualification windows. The Maharashtra-Gujarat industrial belt concentrates procurement for building materials and automotive interiors.
South Korea
Taiwan-based OEMs and South Korean contract manufacturers consolidate procurement around pre-qualified phosphorus compounders with established UL certifications. Electronics manufacturing clusters execute vendor reduction programs eliminating non-certified regional suppliers. The Seoul-Incheon metropolitan area anchors specification-driven procurement for server chassis and laptop housings.
Non-Halogenated Flame Retardant Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated mineral processors commanding volume economics and specialty phosphorus compounders capturing premium positioning through formulation flexibility. The market structure organizes around three tiers: backward-integrated hydrate producers with captive bauxite supply, diversified chemical conglomerates with broad product breadth, and focused phosphorus specialists with reactive oligomeric capabilities. Capacity expansion and strategic partnerships dominate competitive moves, as compounders seek to secure pre-qualified positions in OEM vendor reduction programs.
Within the integrated mineral tier, Huber Engineered Materials and Albemarle Corporation exemplify cost leadership through upstream control over bauxite refining and precipitated hydrate capacity. Among diversified chemical conglomerates, BASF SE and Lanxess occupy positions spanning multiple flame retardant chemistries and application segments. These named entities anchor the competitive structure without exhausting the participant base, as regional mineral processors and specialty phosphorus developers fill intermediate positioning.
| Leading Market Players |
|---|
| Nabaltec AG |
| Huber Engineered Materials |
| BASF SE |
| ICL |
| Clariant |
| Albemarle Corporation |
| Lanxess |
| Italmatch Chemicals |
| FRX Polymers |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between integrated alumina hydrate producers and Chinese wire and cable compounders lock in supply access and price visibility across volatile bauxite processing cycles. These arrangements insulate mineral-based flame retardant buyers from spot market swings in yellow phosphorus and phosphoric acid feedstocks while constraining formulation flexibility for specialty compounders lacking backward integration.
Pricing Analysis
After-sales technical service and UL certification support drive lifetime value for phosphorus-based compounders serving electronics OEMs. Three-tier pricing structure across premium polymeric systems, standard phosphorus esters, and economy mineral hydrates reflects certification burden and loading efficiency. Cost compression in commodity mineral grades intensifies because Chinese hydrate processors expand precipitated capacity. Wire and cable manufacturers in building materials exhibit acute price sensitivity, while aerospace interior specifiers prioritize migration-resistant polymeric systems regardless of unit cost.
Supply Chain Analysis
China and India anchor mineral hydrate production through integrated bauxite refining and regional precipitated capacity expansion. German and South Korean phosphorus compounders draw from Chinese yellow phosphorus and phosphoric acid feedstocks. Single-source vulnerability concentrates in Chinese energy policy adjustments affecting phosphorus export quotas. Distribution runs through direct mill-to-compounder arrangements for mineral grades and distributor networks for specialty phosphorus formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to ECHA restriction deadlines compressing reformulation timelines across European wire and cable applications.
For Market Incumbents: Fortify UL certification portfolios through accelerated testing protocols for phosphorus-polymer combinations, compressing 12-18 month qualification windows. Secure captive bauxite supply or long-term hydrate offtakes to defend against Chinese mineral processor expansion. Prioritize reactive oligomeric R&D to offset substitution threats from intumescent nitrogen-phosphorus hybrids.
For New Entrants and Emerging Players: Anchor in India's PLI-driven electronics manufacturing corridor where local qualification demand outpaces established compounder presence. Target polymeric flame retardant supply to South Korean and Taiwanese OEM vendor reduction programs. Pursue joint development agreements with Tier 1 automotive suppliers seeking ECHA-compliant interior foam formulations.
For Investors and Strategic Acquirers: Specialty phosphorus developers with reactive oligomeric capabilities and pre-qualified aerospace certifications represent the most defensible acquisition profile. Long-term viability rests on regulatory convergence between EU Green Deal implementation and emerging state-level restrictions in the United States. Watch for MIIT directive acceleration in China as the signal indicating specification lock-in momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Processing | Huber Engineered Materials leverages captive refining to anchor North American construction demand. |
| Reactive Oligomeric System Development | FRX Polymers targets Boeing and Airbus qualification pathways for aerospace interior specifications. |
| Long-term Supply Agreement | Chinese wire and cable compounders lock in mineral hydrate volumes under tightening GB standards. |
| Joint Venture | German automotive suppliers partner with phosphorus compounders to accelerate ECHA-compliant foam qualifications. |
| Green Manufacturing Transition | EU Green Deal circular economy requirements favor non-halogenated systems preserving polymer recovery value. |
Study Parameters
Desk research of customs trade data, ACC and Cefic industry reports, and SEC 10-K filings preceded structured interviews with plant managers at alumina hydrate processors, procurement leads at downstream wire and cable OEMs, distribution channel partners, and technical R&D directors at phosphorus compounders. Primary fieldwork combined with secondary validation enabled bottom-up and top-down triangulation across chemistry classes and application tiers.
Variance decomposition across product type, application, end user, and regional production hub shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-kilogram elasticity patterns incorporated Chinese GB standard implementation timelines and ECHA restriction roadmaps as industry-specific forecast inputs.
Material uncertainties — Chinese energy policy shifts affecting phosphorus export quotas, ECHA restriction scope expansion, and UL certification backlog fluctuations — sit outside the modeled envelope. Forecasts reflect assumptions documented in regulatory convergence scenarios and OEM platform standardization patterns. Recalibration cycles align with material shifts in REACH implementation and MIIT directive acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Calcium Peroxide Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Calcium Methoxide Market
Chemicals
Power Plant Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Industrial Odor Management Market
Chemicals
Ethyl Chloride Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Phenylethyl Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
South Korea Methanol Market