
 Alpha-Methylstyrene Market | 2026-2036
Alpha-Methylstyrene Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha-Methylstyrene Market Intelligence
European phenol-acetone co-product streams are restructuring the merchant supply landscape for alpha-methylstyrene. INEOS Styrolution leverages captive cumene-phenol integration to secure feedstock continuity across its European and North American positions. Mitsubishi Chemical Corporation anchors its Asian supply through dedicated phenol plant economics in Japan and Thailand. Kumho P&B Chemicals competes on scale from its Korean phenol derivative complexes, sustaining cost leadership in polymer-grade material.
Alpha-methylstyrene is an aromatic hydrocarbon co-produced during cumene oxidation to phenol and acetone, typically refined to 99 percent-plus purity for polymer applications. Its primary industrial purpose centers on modifying ABS and SAN resins to improve heat resistance and processability. The polymer modifier segment leads volume absorption as ABS compounding for automotive interiors and electronics housings commands premium specifications. Resin applications sustain steady offtake from construction sealants and coatings where thermal stability differentiates performance. Coating formulations represent the emerging margin pool as industrial powder coatings adopt higher-performance binder systems.
EPA emissions standards and OSHA workplace exposure limits govern U.S. handling protocols, while REACH registration and ECHA substance evaluation shape European market access and purity benchmarks. These frameworks elevate compliance costs for merchant producers without integrated phenol economics. Stakeholders must monitor cumene-phenol capacity cycles, as co-product supply fluctuations directly alter alpha-methylstyrene availability and contract pricing structures.
Market Dynamics
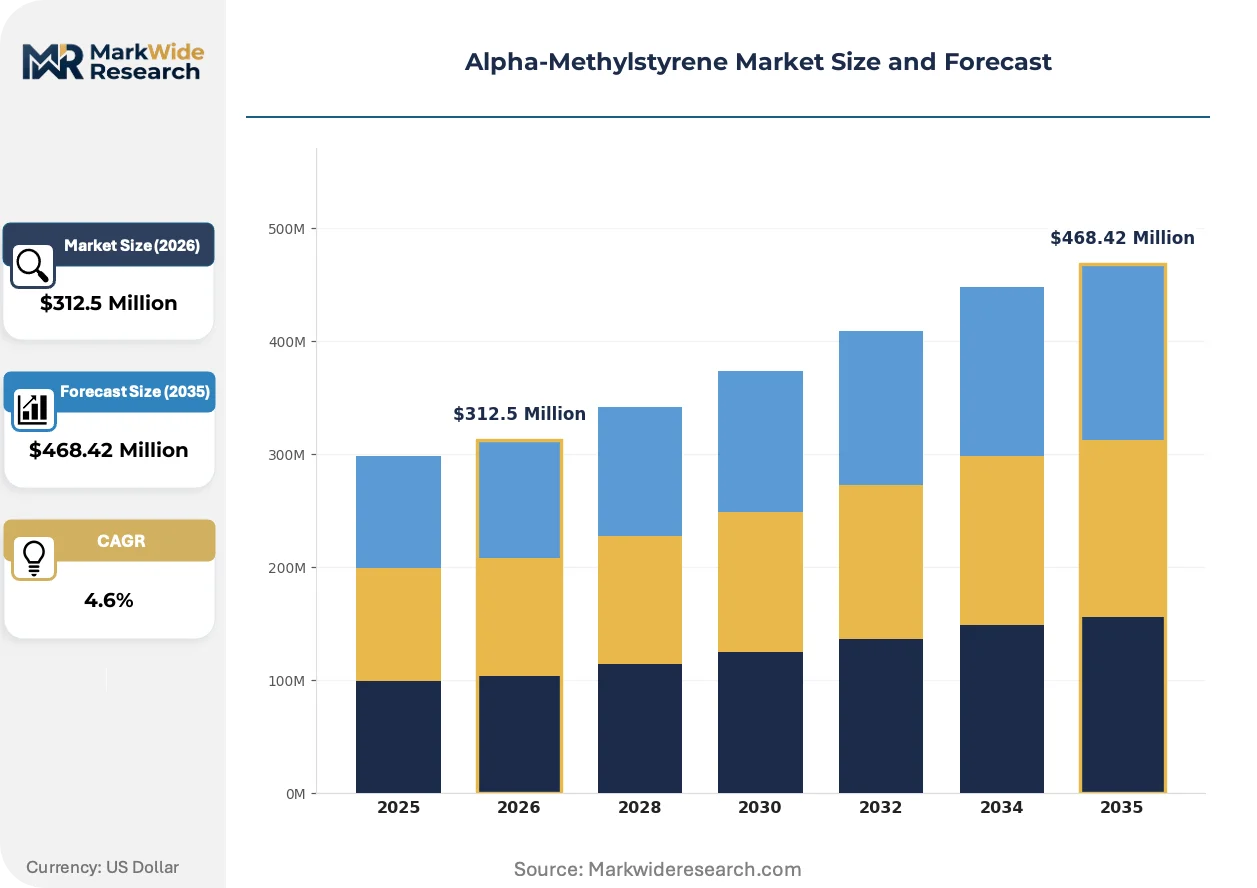
The alpha-methylstyrene market pivots on cumene-phenol co-product economics, where phenol plant operating rates directly determine merchant availability and contract pricing power for this aromatic modifier.
Growth Catalysts
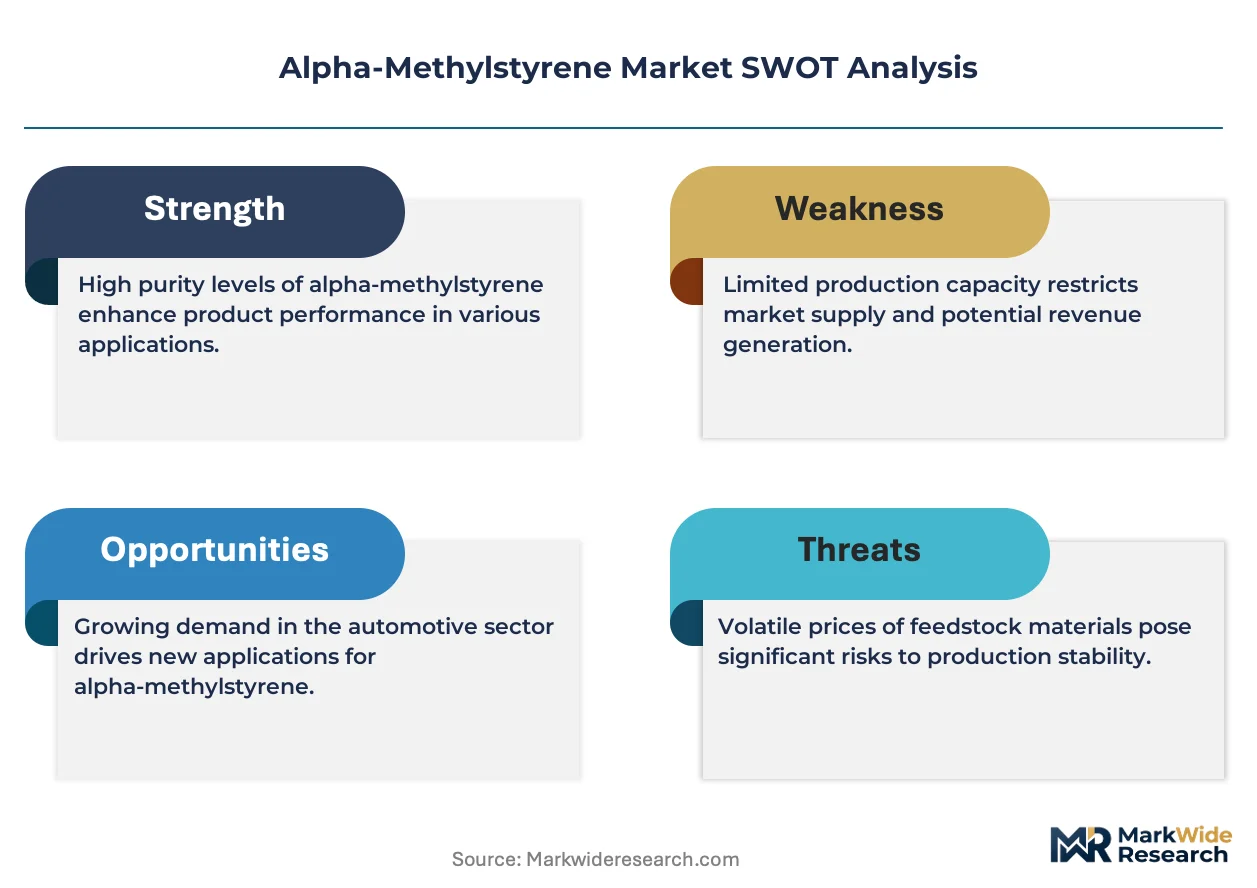
- Automotive lightweighting mandates:ABS resin specifications for interior panels and structural components now require elevated heat-distortion temperatures, pulling polymer-grade alpha-methylstyrene into compounded formulations.
- REACH purity benchmarks:European ECHA substance evaluation protocols are disqualifying lower-grade material, consolidating offtake among refiners with advanced separation capabilities.
- Electronics housing miniaturization:SAN resin applications for laptop and smartphone enclosures demand improved thermal stability, expanding specification windows for high-purity modifier incorporation.
Market Restraints
- Feedstock concentration:Korean and Thai phenol derivative complexes control disproportionate co-product volumes, exposing merchant buyers to single-source disruption risk.
- Acrylic copolymer substitution:Heat-resistant acrylic systems are displacing modified ABS in select appliance applications, compressing addressable volume for styrenic modifiers.
- OSHA exposure thresholds:U.S. workplace vapor limits tighten handling protocols, elevating capital requirements for storage and transfer infrastructure.
Strategic Opportunities
- Industrial powder coating binders:High-performance epoxy-amine systems for automotive underhood and agricultural equipment applications are specification-tolerant of alpha-methylstyrene-modified resin intermediates.
- China domestic ABS expansion:Regional phenol capacity additions are absorbing local co-product streams, creating import substitution openings for external refiners with logistics advantages.
- EU Green Deal chemical recycling:Mass-balance certification pathways for pyrolysis-derived aromatics may qualify recycled-content alpha-methylstyrene for premium polymer applications.
Industry Challenges
- Fractionation expertise scarcity:Distillation technicians capable of maintaining 99.5 percent-plus purity across variable cumene oxidation feedstocks command premium compensation, constraining operational expansion.
- REACH registration dossier maintenance:ECHA substance evaluation updates require toxicological data refreshes, absorbing technical resources and extending compliance timelines for merchant producers without dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha-Methylstyrene Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $468.42 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modifier, Resin, Coating, Adhesive Application: Automotive, Construction, Electronics, Packaging End User: Manufacturers, Distributors, Retailers, Suppliers Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | INEOS Styrolution, SI Group, AdvanSix Inc., Altivia, Mitsubishi Chemical Corporation, SABIC, Kumho P&B Chemicals, Cepsa Quimica, Domo Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha-Methylstyrene Market Strategic Shifts & Innovations
Reactive distillation and membrane separation technologies are reconfiguring purification economics for alpha-methylstyrene, while regulatory frameworks accelerate differentiation between polymer-grade and technical-grade material streams.
Membrane pervaporation systems for separating cumene and alpha-methylstyrene azeotropes are modularizing plant design, allowing phenol producers to retrofit purification trains without extended shutdowns. Mid-scale ABS compounders in Germany and Japan are adopting this technology to secure captive modifier supply. The approach is compressing minimum efficient scale thresholds for merchant entry.
EPA New Chemicals Program scrutiny under TSCA Section 5 is extending pre-manufacture notification timelines for novel styrenic copolymers containing alpha-methylstyrene. U.S. resin formulators now front-load regulatory strategy into product development cycles. The construction sealants segment is responding by reverting to established SAN modification protocols with existing EPA approvals.
Specification-driven procurement now dominates ABS compounding relationships, with automotive Tier-1 suppliers auditing refinery quality systems before contract award. Direct mill agreements are replacing distributor intermediation for volume accounts. This pattern is most pronounced in Michigan automotive clusters and Guangdong electronics manufacturing corridors.
Alpha-Methylstyrene Market Segmentation
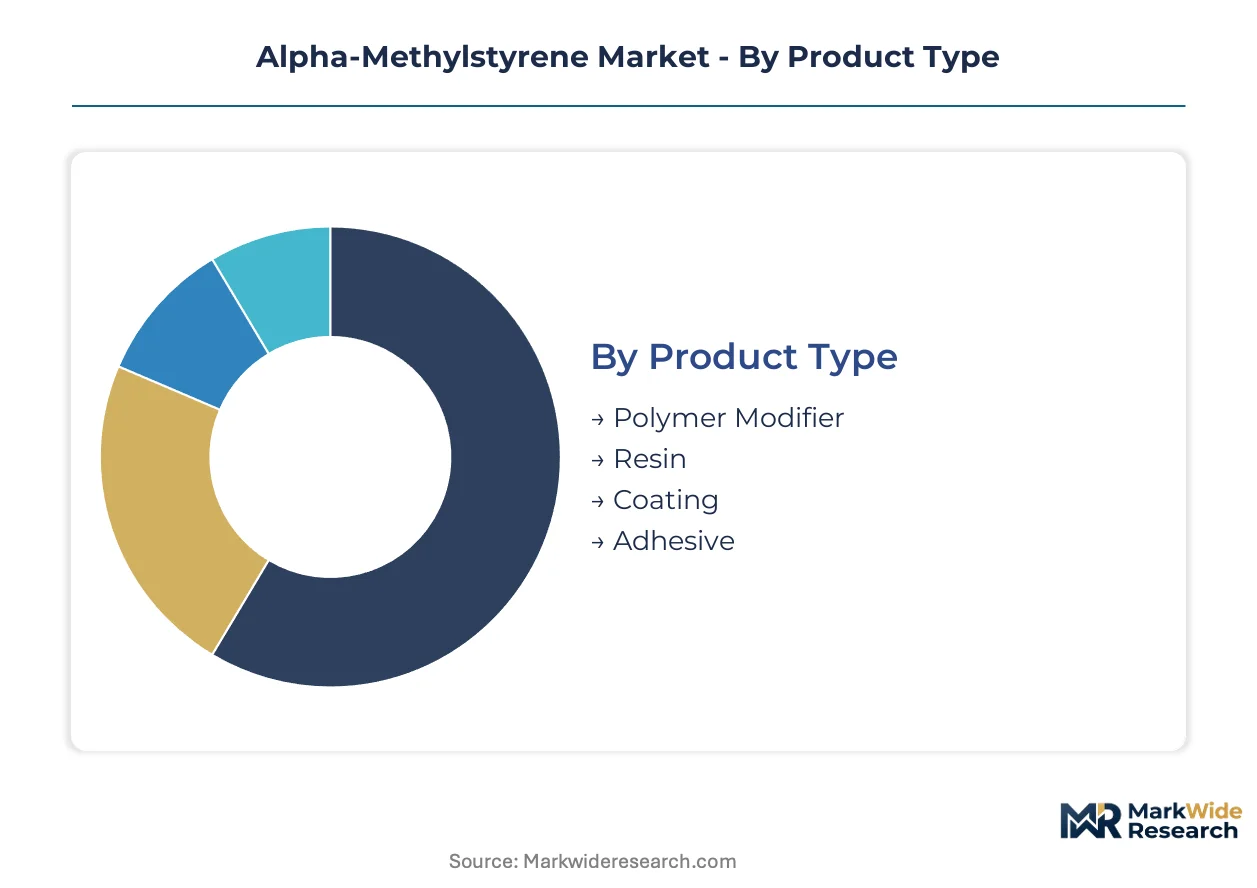
Alpha-methylstyrene procurement patterns diverge sharply between captive phenol-integrated consumers and merchant buyers exposed to co-product availability swings. Specification tiers for polymer-grade versus technical-grade material create distinct margin pools that reshape supplier qualification protocols across end-use verticals.
Product Type:
Volume absorption concentrates in polymer-grade streams where 99 percent-plus purity commands contract premiums, while technical-grade material serves price-sensitive coating and adhesive formulations.
- Polymer Modifier:High-purity streams refined through reactive distillation modify ABS and SAN resins to achieve elevated heat-distortion temperatures. Automotive interior specifications in Michigan and Guangdong manufacturing corridors now mandate this grade for structural component compliance.
- Resin:SAN copolymer applications for electronics housings absorb substantial volumes as laptop and smartphone enclosure miniaturization intensifies thermal stability requirements. Construction sealants in Germany and Japan specify established modification protocols with existing EPA and METI approvals.
- Coating:Industrial powder coating binders for automotive underhood applications tolerate broader purity windows.
- Adhesive:Construction and assembly formulations leverage cost-advantaged technical-grade material.
Today's leader: Polymer Modifier. Tomorrow's challenger: Coating.
Application:
End-use demand clusters around specification-intensive sectors where regulatory compliance and performance benchmarking override feedstock cost considerations.
- Automotive:ABS compounding for interior panels and lightweight structural components drives premium-grade absorption. Tier-1 suppliers in Michigan and Stuttgart now audit refinery quality systems before contract award, replacing distributor intermediation with direct mill agreements.
- Electronics:SAN resin demand for laptop and smartphone enclosures climbs fastest as device miniaturization elevates thermal management requirements. Japanese and South Korean electronics manufacturers specify mass-balance certification pathways under emerging EU Green Deal chemical recycling frameworks.
- Construction:Sealant and coating applications sustain steady offtake where thermal stability differentiates performance.
- Packaging:Limited penetration due to acrylic copolymer substitution in heat-resistant applications.
Automotive commands current volume. Electronics claims the steepest expansion trajectory.
End User:
Procurement authority concentrates among integrated compounders with backward phenol economics, while merchant distributors serve fragmented coating and adhesive formulators.
- Manufacturers:ABS and SAN resin compounders with captive phenol-phenol derivative integration dominate volume offtake. INEOS Styrolution and Mitsubishi Chemical Corporation leverage feedstock continuity to secure preferential contract terms.
- Distributors:Regional intermediaries serve mid-scale coating formulators lacking specification expertise for direct refinery negotiations.
- Retailers:Limited role given industrial nature of alpha-methylstyrene procurement.
- Suppliers:Merchant refiners without integrated cumene oxidation exposure face REACH registration and ECHA substance evaluation compliance burdens.
Manufacturers control pricing power. Distributors face margin compression from direct mill trends.
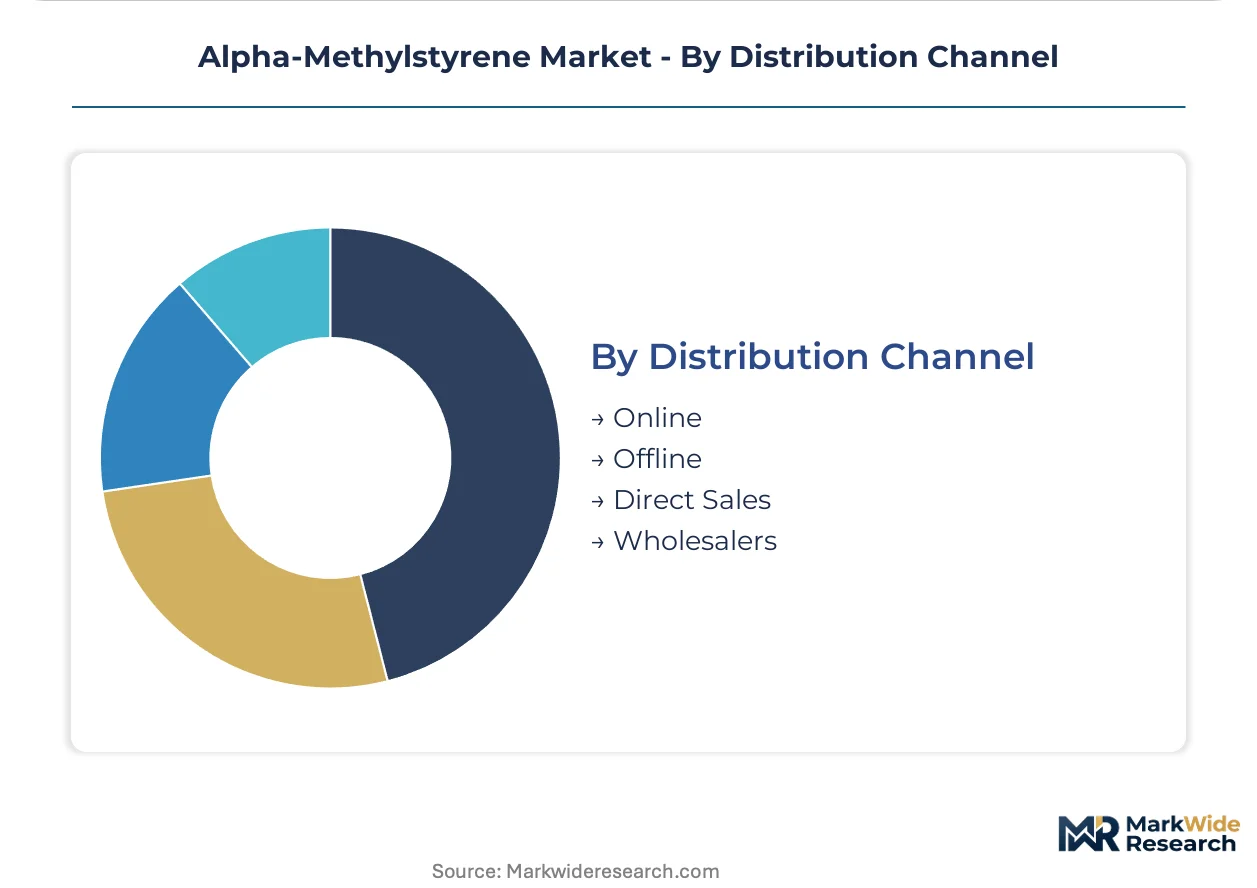
Distribution Channel:
Channel selection tracks customer scale and specification complexity, with direct relationships displacing traditional intermediation for volume accounts.
- Direct Sales:Automotive Tier-1 suppliers and major ABS compounders negotiate direct mill agreements. Audited quality systems and REACH-compliant documentation accompany contract awards in European and North American markets.
- Online:Emerging platform for technical-grade material spot purchasing among small-scale coating formulators.
- Offline:Traditional distributor relationships persist for construction sealant manufacturers with established supplier preferences.
- Wholesalers:Regional chemical distributors serve fragmented adhesive producers lacking procurement scale for refinery-direct negotiations.
Direct Sales captures premium volume. Online channels gain share in technical-grade spot markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting merchant supply flows as REACH compliance burdens in Europe push buyers toward Asian phenol-integrated sources with lower certification overhead.
United States
Automotive ABS compounding in Michigan and electronics housing manufacturing in Texas absorb the majority of domestic polymer-grade material. EPA emissions standards and OSHA workplace exposure limits govern handling protocols and storage infrastructure requirements. Gulf Coast phenol derivative complexes supply captive modifier streams to regional resin compounders.
China
Domestic ABS capacity expansion in Jiangsu and Zhejiang provinces is absorbing regional co-product output and reducing import dependence. GB standards and MIIT industrial policy shape purity specifications for local automotive and electronics applications. Yangtze River Delta manufacturing corridors concentrate demand from laptop and smartphone enclosure producers.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich mandate audited quality systems and REACH-compliant documentation before contract award. ECHA substance evaluation protocols disqualify lower-grade material and consolidate offtake among advanced refiners. Bavarian industrial clusters drive specification-intensive procurement for interior panel applications.
Japan
Electronics manufacturers in Tokyo and Osaka specify mass-balance certification pathways for SAN resin applications in miniaturized device housings. METI guidelines and JIS standards govern thermal stability benchmarks for polymer modifiers. Kanto and Kansai manufacturing belts concentrate demand from semiconductor packaging and consumer electronics producers.
South Korea
Kumho P&B Chemicals and domestic phenol derivative complexes control disproportionate co-product volumes, exposing merchant buyers to concentrated supply risk. MFDS chemical safety regulations and industrial standards shape handling requirements for polymer-grade material. Busan-Ulsan petrochemical corridors anchor regional production and export capacity.
Alpha-Methylstyrene Market Key Industry Players
European producers anchor one tier through REACH-registered, phenol-integrated positions; Asian specialists hold another through scale-driven co-product economics and regional ABS demand absorption. The market structures around three to four dominant suppliers with backward integration into cumene oxidation, while merchant refiners without captive phenol access face margin compression from compliance burdens. Strategic archetypes include phenol-integrated resin compounders, regional co-product refiners, and specification-focused specialty distributors. Capacity expansion in China and Korea and direct mill agreement trends displacing distributor intermediation define current competitive moves.
Within the phenol-integrated tier, INEOS Styrolution leverages European and North American cumene-phenol positions to secure feedstock continuity, while Mitsubishi Chemical Corporation anchors Asian supply through dedicated plant economics in Japan and Thailand. Kumho P&B Chemicals exemplifies the scale-driven Korean archetype, competing from phenol derivative complexes with cost leadership in polymer-grade material.
| Leading Market Players |
|---|
| INEOS Styrolution |
| SI Group |
| AdvanSix Inc. |
| Altivia |
| Mitsubishi Chemical Corporation |
| SABIC |
| Kumho P&B Chemicals |
| Cepsa Quimica |
| Domo Chemicals |
| Others |
Cost & Logistics Intelligence
Polymer-grade and technical-grade purity divergence creates parallel pricing architectures that propagate through distinct supply chain configurations. REACH-registered European refiners command contract premiums for 99.5 percent-plus material while Asian phenol-integrated sources supply cost-advantaged technical-grade streams to coating formulators. This bifurcation concentrates pricing power among backward-integrated compounders with captive cumene oxidation economics.
Pricing Analysis
Distributor margin compression is accelerating as automotive Tier-1 suppliers negotiate direct mill agreements for polymer-grade volumes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and geographic delivery cost. Pricing pressure stems from acrylic copolymer substitution in appliance applications. Coating formulators exhibit highest price sensitivity; ABS compounders with captive phenol integration show lowest.
Supply Chain Analysis
Fractionation technician scarcity in German and Japanese manufacturing geographies constrains operational expansion for high-purity refining. Supply concentrates in South Korea, China, and Thailand where phenol derivative complexes control co-product volumes. Raw material dependencies center on cumene feedstock, phenol plant operating rates, and membrane separation modules. Single-source vulnerability from Korean phenol complex concentration threatens merchant buyers. Distribution runs through direct mill agreements for volume accounts and regional distributors for fragmented coating producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH substance evaluation milestones and EPA emissions protocols continuously reshape supplier qualification requirements and demand specifications.
For Market Incumbents: Cement feedstock continuity through phenol-derivative capacity maintenance in European and North American positions. Defend against acrylic copolymer substitution by advancing reactive distillation capabilities for 99.5 percent-plus purity. Channel control through audited quality systems secures automotive Tier-1 direct agreements.
For New Entrants and Emerging Players: Enter via membrane pervaporation technology licensing to serve mid-scale ABS compounders seeking captive modifier supply. White-space targets include Chinese domestic ABS expansion corridors and EU Green Deal chemical recycling certification pathways. Technical-grade coating applications offer lowest barrier to entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration dossier maintenance burdens exceed technical resources of merchant refiners without dedicated regulatory functions. Long-term viability favors phenol-integrated positions with backward cumene oxidation control. Acquisition targets include regional co-product refiners with fractionation expertise. Signal to monitor: ECHA substance evaluation updates disqualifying lower-grade material.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene Oxidation | Captive phenol economics secure feedstock continuity across European and North American positions. |
| Membrane Pervaporation Technology Deployment | Modular purification trains allow retrofit without extended shutdowns at German and Japanese compounders. |
| REACH Registration Dossier Investment | ECHA compliance documentation enables contract access to automotive Tier-1 suppliers in Stuttgart. |
| Direct Mill Agreement Expansion | Audited quality systems displace distributor intermediation in Michigan and Guangdong manufacturing corridors. |
| Mass-Balance Certification Pathway Development | EU Green Deal chemical recycling qualification opens premium polymer applications for Japanese electronics manufacturers. |
Research Approach
Direct dialogue with phenol plant managers, ABS compounder procurement leads, distribution channel partners, and technical R&D directors grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up volume triangulation against top-down phenol co-product supply modeling ensured cross-verification.
Segmented projections across grade tier, end-use industry, and regional production hub fed analytical framework outputs over the projection horizon. CAGRs derived from phenol plant operating rate cycles, ABS capacity expansion trajectories, and regulatory compliance cost absorption curves. Modeled inputs included cumene oxidation yield variations and membrane separation technology adoption rates.
Inputs from ECHA evaluation timelines and MIIT industrial policy disclosures were available through the study window; gaps in real-time phenol plant operating data introduce uncertainty bands around co-product availability assumptions. Forecasts reflect documented assumptions regarding REACH registration maintenance burdens and acrylic substitution penetration. Material deviation in automotive lightweighting mandates or OSHA exposure threshold revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Dibutyl Ether Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Nitrobenzene Market
Solvents
Methyl Undecylenate Market
Solvents
Isopropylamine Market
Solvents
Benzene Market
Solvents
Fluorinated Solvents Market
Solvents
Triacetin Market
Solvents
Ionic Liquids Market
Solvents
Acetone Market
Solvents
Allyl Cyanide Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Pharmaceutical Solvent Market