
 P-Ethylphenol Market | 2026-2036
P-Ethylphenol Market Size, Share, and Industry Trends Forecast 2026-2036
P-Ethylphenol Market Analysis
Aftermarket technical support and custom synthesis services is narrowing as a margin pool as buyers consolidate procurement around certified direct suppliers. Sigma Aldrich leverages its analytical standards portfolio to dominate research-grade distribution across North American and European laboratories. Thermo Fisher Scientific anchors its position through integrated supply chain control from raw phenol feedstock to final certified containers. TCI Chemicals specializes in regional catalog depth across Asia-Pacific research markets, competing on localized regulatory documentation and faster customs clearance.
P-ethylphenol is a substituted phenol compound featuring an ethyl group at the para position of the aromatic ring, typically manufactured through catalytic alkylation of phenol with ethylene using acid or zeolite catalysts at elevated temperature and pressure. It functions primarily as a chemical intermediate for antioxidant synthesis, fragrance precursors, and specialized resin formulations where thermal stability and controlled reactivity matter. Pharmaceutical-grade material commands premium positioning due to stringent impurity profiling demands from FDA and EMA filing requirements, while industrial-grade volumes anchor revenue through aromatic chemicals and resin manufacturing applications. Research-grade SKUs generate disproportionate margin contribution despite smaller tonnage, reflecting documentation intensity and lot-specific certification overhead.
EPA industrial chemical oversight and REACH registration mandates in Europe are elevating analytical documentation burdens for importers and domestic manufacturers alike. China's NMPA and evolving GB standards for chemical intermediates are tightening residual solvent and heavy metal specifications, reshaping supplier qualification protocols for export-oriented producers. Buyers must monitor regulatory divergence across these jurisdictions to avoid formulation lockouts or costly re-qualification cycles.
Market Dynamics
REACH registration mandates and EPA industrial chemical oversight are elevating analytical documentation burdens, forcing suppliers to consolidate around certified direct distribution while squeezing aftermarket technical service margins.
Growth Catalysts
- Pharmaceutical synthesis expansion:FDA and EMA filing requirements for high-purity grades are pulling volume into certified supply chains for active pharmaceutical ingredient intermediates.
- Agrochemical intermediate demand:Production clusters in China and India are scaling consumption of aromatic chemical feedstocks for pesticide and herbicide synthesis.
- Zeolite catalysis advancement:Acid catalyst replacement with heterogeneous zeolite systems is improving para-selectivity and reducing by-product formation in phenol alkylation.
Market Restraints
- Phenol feedstock volatility:Benzene and propylene price swings transmit directly into p-ethylphenol cost structures, compressing margin predictability for non-integrated producers.
- Supplier concentration risk:Catalytic alkylation capacity clusters among a limited set of Chinese and Indian aromatic chemical specialists, creating geographic single-source exposure.
- REACH compliance friction:ECHA registration dossier requirements for tonnage band upgrades impose multi-year timelines and six-figure documentation costs on European importers.
Strategic Opportunities
- Research-grade channel expansion:North American and European laboratories are consolidating procurement around certified distributors with integrated analytical standards portfolios.
- Biobased phenol feedstock convergence:Lignin-derived phenol commercialization is creating dual-source raw material strategies for sustainability-positioned formulations.
- PLI scheme leverage in India:Chemical intermediate manufacturing incentives under the Production Linked Incentive scheme are attracting capacity investment for export-oriented production.
Industry Challenges
- Impurity profiling skill scarcity:Gas chromatography-mass spectrometry analysts with pharmaceutical-grade method validation experience command premium compensation and extended recruitment cycles.
- Lot-specific certification overhead:Research-grade SKUs require individualized CoA generation, traceability documentation, and cold-chain integrity verification that strains ERP system flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P-Ethylphenol Market |
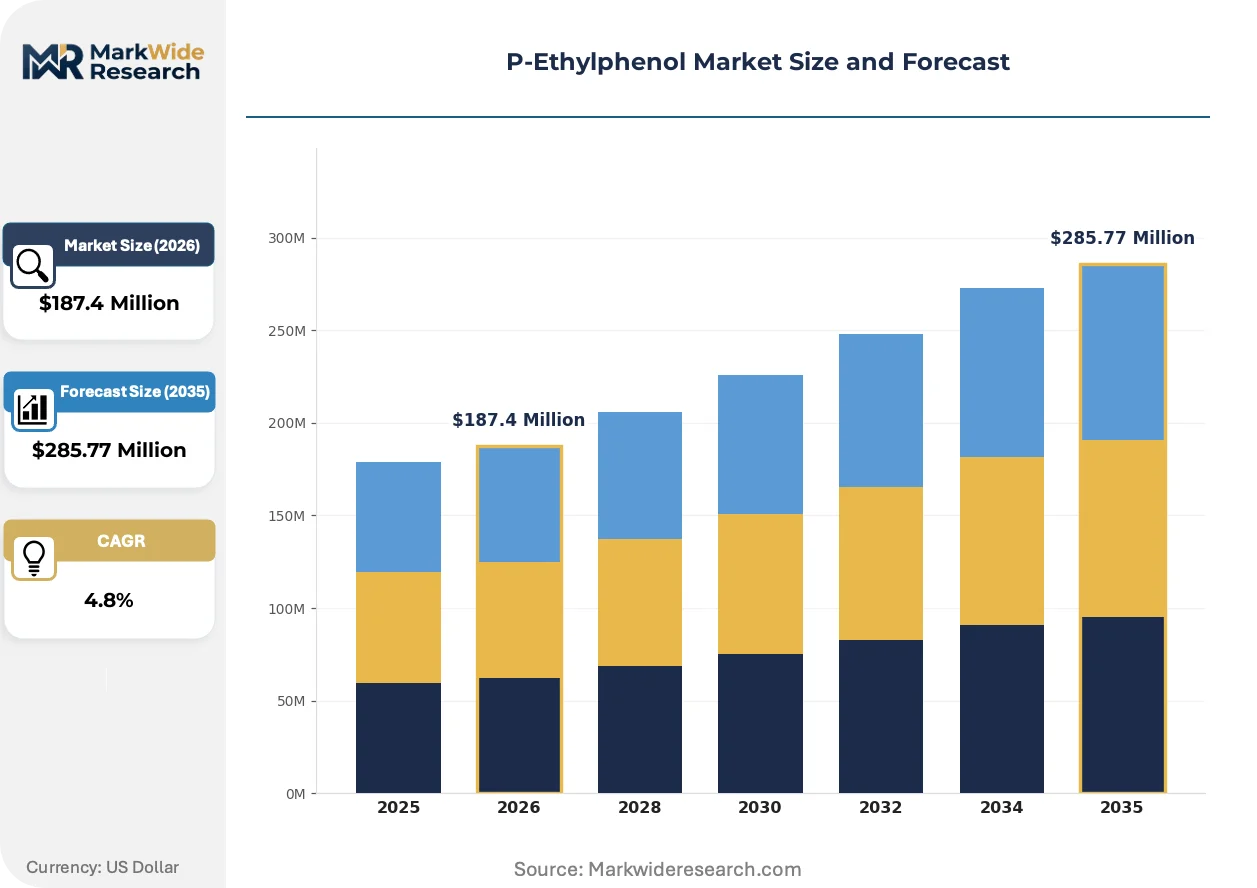
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Chemical Intermediate, Research Grade Application: Aromatic Chemicals, Resin Manufacturing, Pharmaceutical Synthesis, Agrochemicals End User: Pharmaceutical Companies, Chemical Manufacturers, Research Institutions, Agrochemical Producers Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Sigma Aldrich, Thermo Fisher Scientific, TCI Chemicals, Santa Cruz Biotech, Clearsynth, ABCR Gmbh, AK Scientific, Alfa Chemistry, 3B Scientific (Wuhan) Corporation Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P-Ethylphenol Market Emerging Trajectories
Zeolite catalysis systems and impurity profiling automation are compressing production economics while regulatory documentation digitization is reshaping supplier-buyer data exchange protocols across the value chain.
Fixed-bed zeolite catalyst technology is migrating from homogeneous acid alkylation in p-ethylphenol production. Specialty chemical manufacturers in Germany and Japan are adopting these systems to achieve higher para-selectivity and eliminate corrosive waste streams. The shift is enabling continuous-flow reactor designs that reduce solvent recovery costs and position producers for ISO 14001 environmental certification.
EMA's updated guideline on elemental impurities in drug products is forcing pharmaceutical-grade suppliers to implement inductively coupled plasma mass spectrometry screening. The industrial consequence is a bifurcation between certified producers with in-house metals testing capability and traders dependent on third-party laboratories. European API manufacturers are responding by qualifying only direct manufacturers with documented ICH Q3D compliance rather than distributor intermediaries.
Certificate-of-analysis standardization is consolidating procurement decisions around digital data exchange platforms. Research laboratories and formulation houses are replacing paper CoA reconciliation with blockchain-anchored verification systems that automate lot acceptance. This behavioral shift is most visible in North American pharmaceutical R&D clusters where FDA 21 CFR Part 11 electronic record requirements have normalized automated compliance documentation.
P-Ethylphenol Market Segmentation
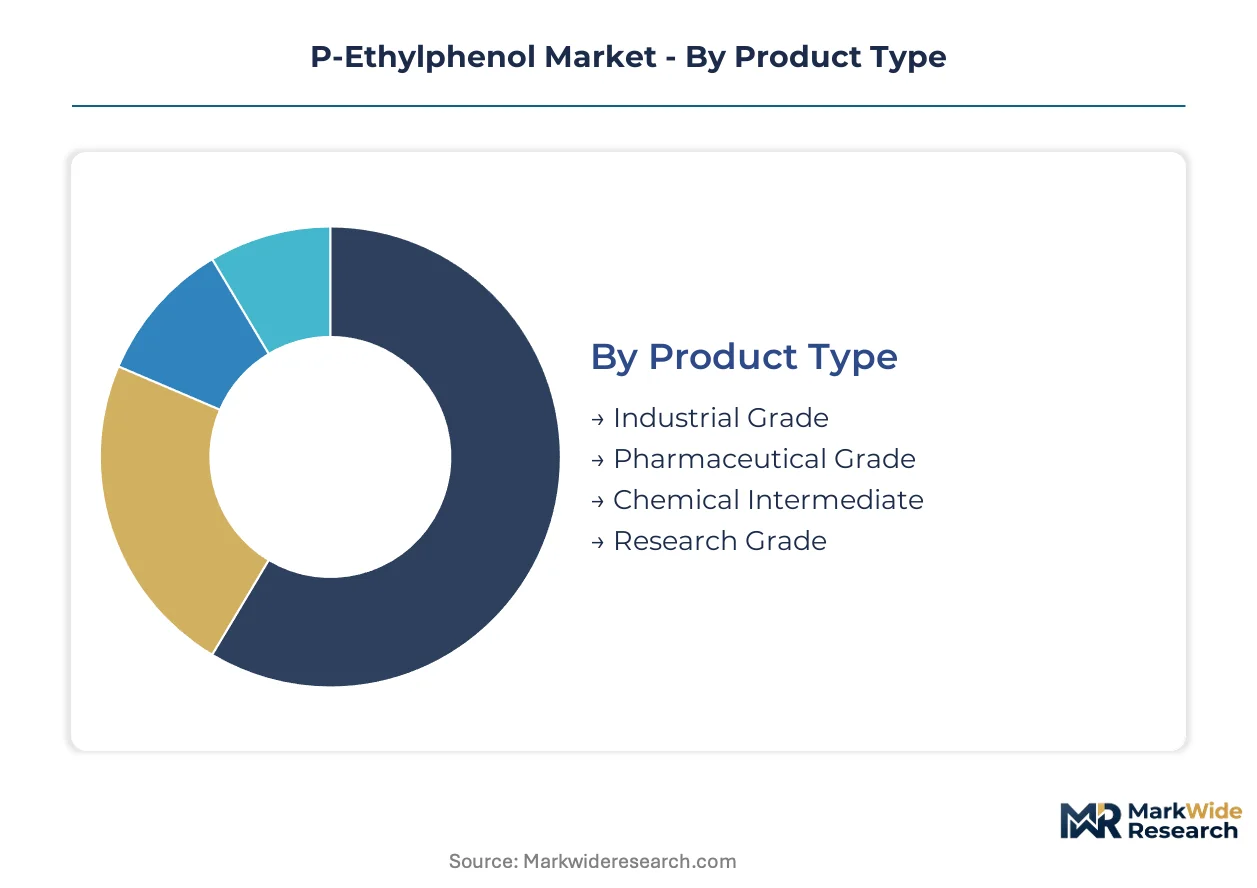
P-ethylphenol segmentation reflects a bifurcated value chain where certification intensity separates research and pharmaceutical grades from commodity industrial volumes. Grade-specific purity thresholds, documentation burdens, and end-use regulatory exposure create distinct margin pools that reward specialized positioning over scale alone.
Product Type:
Mature industrial grades anchor baseline revenue while emerging pharmaceutical specifications command premium positioning through FDA and EMA compliance overhead.
- Industrial Grade:Standard purity specifications (typically 98-99%) serve antioxidant synthesis and general aromatic chemical production where cost efficiency outweighs trace impurity control. Demand concentrates in Chinese and Indian resin manufacturing clusters scaling para-alkylated phenol consumption for thermal stabilizer formulations.
- Pharmaceutical Grade:Ultra-high purity (≥99.9%) with comprehensive impurity profiling and ICH Q3D elemental compliance supports active pharmaceutical ingredient intermediate synthesis. EMA filing requirements and FDA pre-approval inspection protocols pull volume into certified direct supply chains with documented batch traceability.
- Chemical Intermediate:Partially purified material (99-99.5%) bridges industrial and pharmaceutical applications, serving fragrance precursor and specialized polymer additive synthesis where intermediate purity tiers reduce downstream processing costs.
- Research Grade:Lot-specific certification with individualized CoA generation and cold-chain documentation supports analytical standards and method development in North American and European laboratories.
Industrial grade handles the majority of throughput; pharmaceutical grade is the fastest mover on share.
Application:
Cost tier stratification separates commodity aromatic chemical consumption from margin-rich pharmaceutical and agrochemical synthesis where specification precision determines supplier qualification.
- Aromatic Chemicals:Largest volume application encompassing fragrance precursors, polymer stabilizers, and general organic synthesis intermediates. Production clusters in China's Jiangsu and Shandong provinces drive consumption of standard-grade material for export-oriented fragrance compound manufacturing.
- Pharmaceutical Synthesis:High-purity p-ethylphenol serves as a building block for cardiovascular and central nervous system active pharmaceutical ingredients. CDSCO in India and NMPA in China are tightening residual solvent specifications, reshaping supplier qualification protocols for export-oriented API manufacturers.
- Resin Manufacturing:Thermal stabilizer and curing agent applications in epoxy and phenolic resin systems demand consistent para-selectivity and controlled reactivity profiles.
- Agrochemicals:Herbicide and pesticide intermediate synthesis in Indian Maharashtra and Gujarat production corridors scales consumption of technical-grade material under PLI scheme incentives.
Aromatic chemicals maintains volume dominance; pharmaceutical synthesis is climbing the fastest on value contribution.
End User:
Customer type fragmentation creates divergent procurement patterns where research institutions demand documentation intensity while chemical manufacturers prioritize supply security and feedstock integration.
- Pharmaceutical Companies:FDA and EMA filing requirements mandate certified suppliers with in-house ICP-MS metals testing and documented ICH Q3D compliance, disqualifying distributor intermediaries for API-grade material.
- Chemical Manufacturers:Integrated aromatic chemical producers in Germany and Japan leverage captive phenol feedstock and zeolite catalysis advancement to secure cost positions in antioxidant and fragrance precursor markets.
- Research Institutions:North American and European laboratories consolidate procurement around certified distributors with blockchain-anchored CoA verification and analytical standards portfolio depth.
- Agrochemical Producers:Indian and Chinese pesticide manufacturers scale intermediate consumption through production clusters benefiting from feedstock proximity and export logistics infrastructure.
Chemical manufacturers handle the majority of throughput; research institutions are expanding most quickly on per-unit margin.
Distribution Channel:
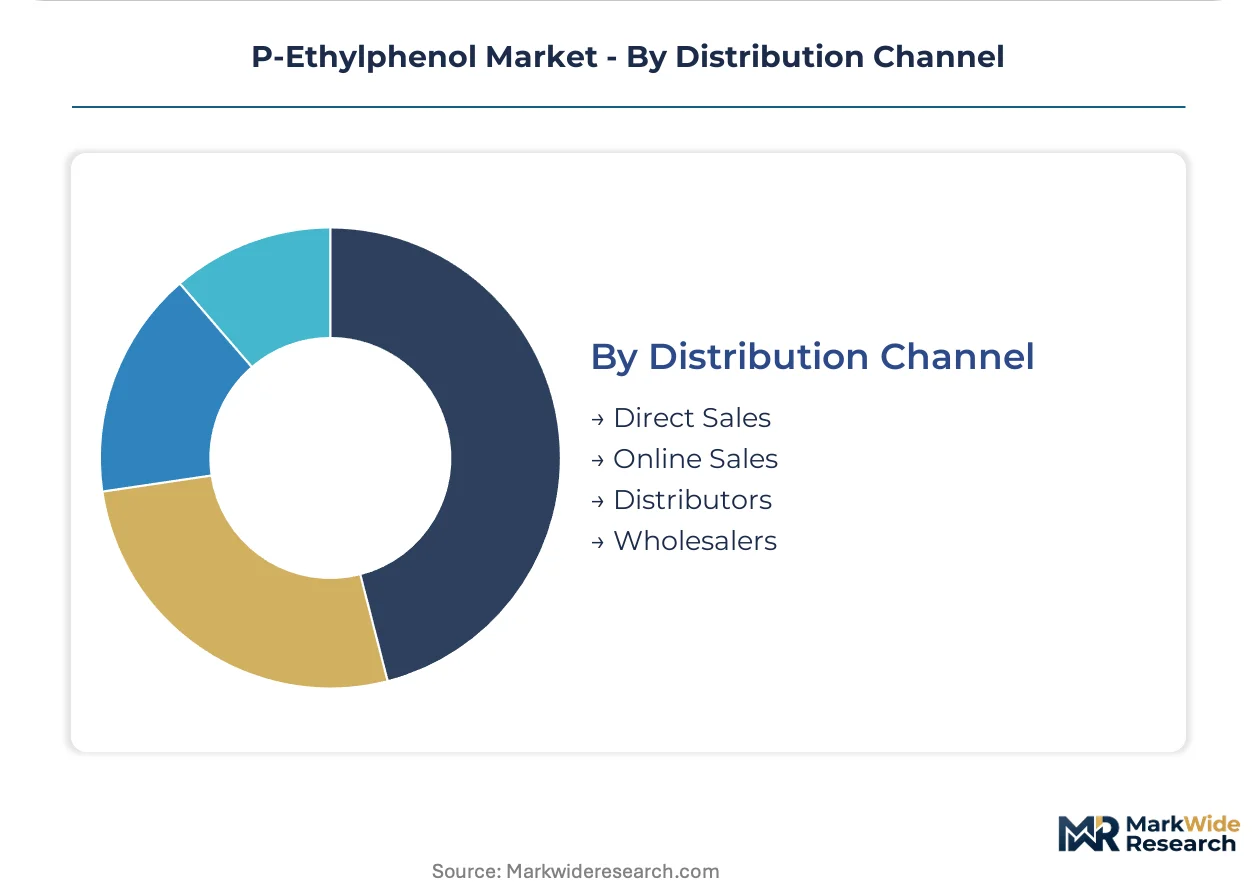
Supply concentration is compressing aftermarket technical service margins as buyers consolidate procurement around certified direct relationships with documented regulatory compliance.
- Direct Sales:Pharmaceutical-grade and large-volume industrial contracts flow through manufacturer-direct relationships enabling integrated supply chain control from phenol feedstock to certified containers.
- Distributors:Regional catalog depth and localized regulatory documentation support research-grade and mid-volume industrial sales across Asia-Pacific markets with faster customs clearance protocols.
- Online Sales:Digital platforms with blockchain-anchored CoA verification automate lot acceptance for North American pharmaceutical R&D clusters under FDA 21 CFR Part 11 electronic record requirements.
- Wholesalers:Bulk commodity volumes for standard industrial applications leverage inventory positioning and logistics networks serving fragmented downstream processors.
Direct sales commands the majority of pharmaceutical and large industrial volume; online sales is gaining share fastest on procurement automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalytic alkylation capacity clusters among aromatic chemical specialists in China, India, Germany, and the United States, with feedstock integration and regulatory compliance determining regional competitiveness. Each geography exhibits distinct demand drivers and qualification protocols that reshape supplier positioning.
China
Jiangsu and Shandong provinces drive consumption for fragrance precursor and resin stabilizer manufacturing. NMPA tightening of residual solvent specifications in GB standards is forcing export-oriented producers to upgrade impurity profiling capabilities. Yangtze River Delta chemical parks are consolidating phenol derivative capacity around integrated feedstock supply.
India
Maharashtra and Gujarat production corridors scale agrochemical intermediate consumption under PLI scheme incentives for chemical manufacturing. CDSCO filing requirements for API-grade material are pulling pharmaceutical synthesis demand toward certified direct suppliers. Mumbai-Pune industrial belt is attracting capacity investment for export-oriented aromatic chemical production.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia and Bavaria adopt fixed-bed zeolite catalysis to achieve higher para-selectivity. ECHA REACH registration dossier requirements for tonnage band upgrades impose multi-year compliance timelines on importers. BASF Ludwigshafen complex anchors captive phenol-to-derivative integration for antioxidant and fragrance markets.
United States
Gulf Coast petrochemical corridors leverage shale-advantaged benzene feedstock for phenol alkylation economics. EPA industrial chemical oversight and evolving purity standards are elevating analytical documentation burdens for domestic manufacturers and importers alike. Texas-Louisiana chemical manufacturing clusters serve North American pharmaceutical and resin formulation demand.
Japan
Chubu and Kanto regions maintain precision chemical manufacturing for pharmaceutical-grade material with documented ICH Q3D compliance. METI chemical management policies and PMDA filing requirements reinforce premium positioning for export-oriented API intermediate suppliers. Nagoya-Osaka industrial corridor specializes in high-purity grades for cardiovascular and central nervous system drug synthesis.
P-Ethylphenol Market Vendor Landscape
Integrated life science conglomerates and regional catalog specialists split the market between certified direct supply chains and documentation-intensive research distribution. Supplier concentration is compressing aftermarket technical service margins as buyers consolidate procurement around qualified manufacturers with in-house analytical capabilities. Two dominant strategic archetypes emerge: captive feedstock integrators controlling phenol-to-final-container supply chains, and regulatory documentation specialists competing on localized compliance depth. Capacity expansion in Indian chemical parks and technology licensing of zeolite catalysis systems represent the primary competitive moves reshaping cost positions.
Among research-grade distributors, Sigma Aldrich and TCI Chemicals exemplify the documentation-specialist archetype, with the former anchoring North American laboratory procurement through analytical standards portfolio depth and the latter competing across Asia-Pacific markets on localized regulatory documentation and customs clearance velocity. Thermo Fisher Scientific occupies a position representing integrated supply chain control, spanning raw phenol feedstock through certified final containers. These three entities collectively illustrate how certification intensity and geographic coverage determine competitive positioning in a market where regulatory compliance overhead increasingly outweighs scale economies.
| Leading Market Players |
|---|
| Sigma Aldrich |
| Thermo Fisher Scientific |
| TCI Chemicals |
| Santa Cruz Biotech |
| Clearsynth |
| ABCR Gmbh |
| AK Scientific |
| Alfa Chemistry |
| 3B Scientific (Wuhan) Corporation Ltd |
| Others |
Supply Flow & Price Mechanics
Chinese and Indian aromatic chemical specialists concentrate catalytic alkylation capacity, channeling margin pools toward certified direct suppliers with integrated phenol feedstock control and documented ICH Q3D compliance. REACH registration dossier costs and EPA documentation burdens squeeze aftermarket technical service margins while rewarding captive production economics.
Pricing Analysis
After-sales technical support and custom synthesis services drive lifetime value in research-grade distribution, where Sigma Aldrich and TCI Chemicals compete on documentation depth rather than unit economics. Three-tier pricing structure across pharmaceutical, industrial, and research grades reflects certification intensity and impurity profiling overhead. Pricing pressure stems from phenol feedstock volatility transmitting benzene and propylene cost swings into compressed margins for non-integrated producers. Chemical manufacturers exhibit highest price sensitivity due to volume scale and feedstock integration options, while pharmaceutical companies absorb premium positioning for FDA and EMA filing compliance.
Supply Chain Analysis
Phenol feedstock availability anchors supply chain configuration, with Germany, Japan, and the United States maintaining specialty chemical manufacturing through captive integration and zeolite catalysis advancement. Raw material dependencies center on benzene, propylene, and ethylene sourced from Gulf Coast petrochemical corridors and Yangtze River Delta chemical parks. Single-source vulnerability concentrates in Jiangsu and Shandong provinces where fragrance precursor and resin stabilizer clusters scale para-alkylated phenol consumption. Distribution runs through direct sales for pharmaceutical-grade and large-volume industrial contracts, with regional distributors handling research-grade and mid-volume Asia-Pacific sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs defensive moats in this market, as REACH compliance timelines and FDA pre-approval inspection protocols lock buyers into qualified supplier relationships with documented batch traceability.
For Market Incumbents: Pre-empt emerging zeolite catalysis licensing from German and Japanese specialty chemical manufacturers by securing backward integration into lignin-derived phenol feedstock and expanding fixed-bed reactor capacity in Indian chemical parks under PLI scheme incentives. Threat substitution from biobased phenol commercialization demands dual-source raw material strategies to defend cost positions. For New Entrants and Emerging Players: Pursue research-grade channel expansion in North American pharmaceutical R&D clusters where blockchain-anchored CoA verification and analytical standards portfolio depth command disproportionate margin contribution. The most penetrable white-space sits with mid-tier chemical intermediate supply to Indian agrochemical producers scaling under PLI incentives, accessed through localized regulatory documentation capabilities and faster customs clearance protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed catalog distributors lacking in-house ICP-MS metals testing capability, as EMA elemental impurity guidelines bifurcate certified producers from trader intermediaries. Long-term viability across a 5-10 year window favors direct manufacturers with REACH-registered tonnage bands and documented ICH Q3D compliance. The signal to watch is CDSCO and NMPA tightening of residual solvent specifications forcing re-qualification cycles and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Zeolite Catalysis Licensing | Specialty chemical manufacturers in Germany and Japan adopt fixed-bed systems to achieve higher para-selectivity and eliminate corrosive waste streams. |
| Backward Integration into Biobased Phenol | Lignin-derived phenol commercialization creates dual-source raw material strategies for sustainability-positioned formulations. |
| PLI Scheme Capacity Investment | Chemical intermediate manufacturing incentives under India's Production Linked Incentive scheme attract export-oriented production. |
| Blockchain-Anchored CoA Verification | North American pharmaceutical R&D clusters automate lot acceptance under FDA 21 CFR Part 11 electronic record requirements. |
| ICP-MS Metals Testing Capability | EMA's updated elemental impurity guideline forces pharmaceutical-grade suppliers to implement inductively coupled plasma mass spectrometry screening. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at aromatic chemical facilities, procurement leads at downstream API manufacturers, distribution channel partners, and technical R&D directors specializing in phenol alkylation, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated life science conglomerates, and REACH registration dossiers from ECHA. Bottom-up capacity modeling and top-down demand triangulation validated segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning grade tier, end-use industry, and regional production hub. CAGRs were derived from modeled volume trajectories and value-per-ton assumptions, incorporating zeolite catalysis adoption curves, pharmaceutical filing pipeline visibility, and agrochemical intermediate consumption scaling in Indian production corridors.
Macroeconomic conditions sit as an overlay; deviation in benzene and propylene price cycles, REACH compliance cost inflation, or CDSCO regulatory tightening would shift the trajectory. Forecasts reflect documented assumptions about capacity expansion timelines and technology adoption rates. Cross-checking against ECHA registration database updates and Indian chemical park investment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
North America Tartaric Acid Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Calcium Hydroxide Market
Chemicals
Pinoxaden Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Sodium Hydride Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global Lactate Salts Market