
 Peroxyacetic Acid Market | 2026-2036
Peroxyacetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Peroxyacetic Acid Market Outlook
Food-grade certification tiers above standard industrial grades is redrawing competitive boundaries in peroxyacetic acid supply. Solvay leverages its integrated hydrogen peroxide chain to command premium food-grade positions. Evonik Industries AG anchors European supply through specialized stabilized formulations for cold-chain sanitation. Kemira Oyj competes in Nordic water treatment segments with concentrated peroxyacetic acid blends engineered for pulp bleaching.
Peroxyacetic acid is an organic peroxide synthesized from acetic acid and hydrogen peroxide, typically supplied as an equilibrium mixture containing stabilizers to manage decomposition rates; its oxidative potency delivers broad-spectrum antimicrobial action at low temperatures. The compound serves as a terminal sanitizer in food processing, medical device disinfection, and agricultural equipment sterilization where thermal methods prove impractical. Liquid formulations dominate commercial supply due to easier dosing integration and established transport infrastructure, though concentrated variants command margin premiums from large-scale industrial buyers. Food Industry end users represent the most structurally defended demand pool, tied to FSMA-mandated sanitation protocols and processor liability exposure.
EPA registration requirements under FIFRA govern antimicrobial claims and label specifications for US-sold peroxyacetic acid products, while ECHA REACH obligations constrain stabilizer chemistries in European formulations. FDA food contact notifications shape permissible residual levels on processed surfaces, directly influencing formulation design for poultry and produce applications. Stakeholders must monitor evolving EPA re-registration timelines and emerging state-level restrictions on peracetic acid discharge limits that could reshape regional manufacturing footprints.
Market Dynamics
Chlorine-based sanitizer displacement by peroxyacetic acid formulations is the dominant structural force, driven by FSMA microbial reduction mandates and EPA Safer Choice compliance pressure on US poultry and produce processors. This substitution dynamic concentrates procurement power among large food processors while fragmenting regional supply capabilities.
Growth Catalysts
- FSMA Sanitation Rules:FDA-mandated sanitation protocols for poultry and produce processing create binding compliance demand for terminal sanitizers effective at low temperatures.
- EPA Safer Choice Program:The EPA's chemical safety certification accelerates institutional substitution away from chlorine-based formulations in food contact applications.
- Cold-Chain Expansion:Temperature-sensitive logistics infrastructure growth drives demand for antimicrobial agents that maintain efficacy without thermal activation.
Market Restraints
- Hydrogen Peroxide Feedstock Volatility:Concentrated peroxyacetic acid production depends on hydrogen peroxide supply, with pricing tied to energy-intensive anthraquinone process economics.
- European Stabilizer Constraints:ECHA REACH obligations restrict stabilizer chemistries in EU formulations, limiting product shelf-life and transport radius from manufacturing sites.
- Chlorine Dioxide Substitution:Lower-cost chlorine dioxide retains share in non-food-contact industrial water treatment where regulatory pressure remains minimal.
Strategic Opportunities
- Medical Device Sterilization:Low-temperature terminal sterilization demand for heat-sensitive surgical instruments and endoscopes represents an underpenetrated application vertical.
- India FSSAI Alignment:India's food safety modernization creates compliance-driven substitution potential as FSSAI standards converge with Codex Alimentarius microbial limits.
- On-Site Generation Systems:Electrolytic and equilibrium-based generation units enable captive production at large processor sites, reducing transport costs and stabilizer dependency.
Industry Challenges
- Food-Grade Certification Timelines:FDA food contact notification processes and EPA FIFRA registration cycles create 18-36 month product commercialization delays.
- Formulation Stability Expertise:Decomposition rate management requires specialized chemical engineering talent scarce outside established hydrogen peroxide producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peroxyacetic Acid Market |
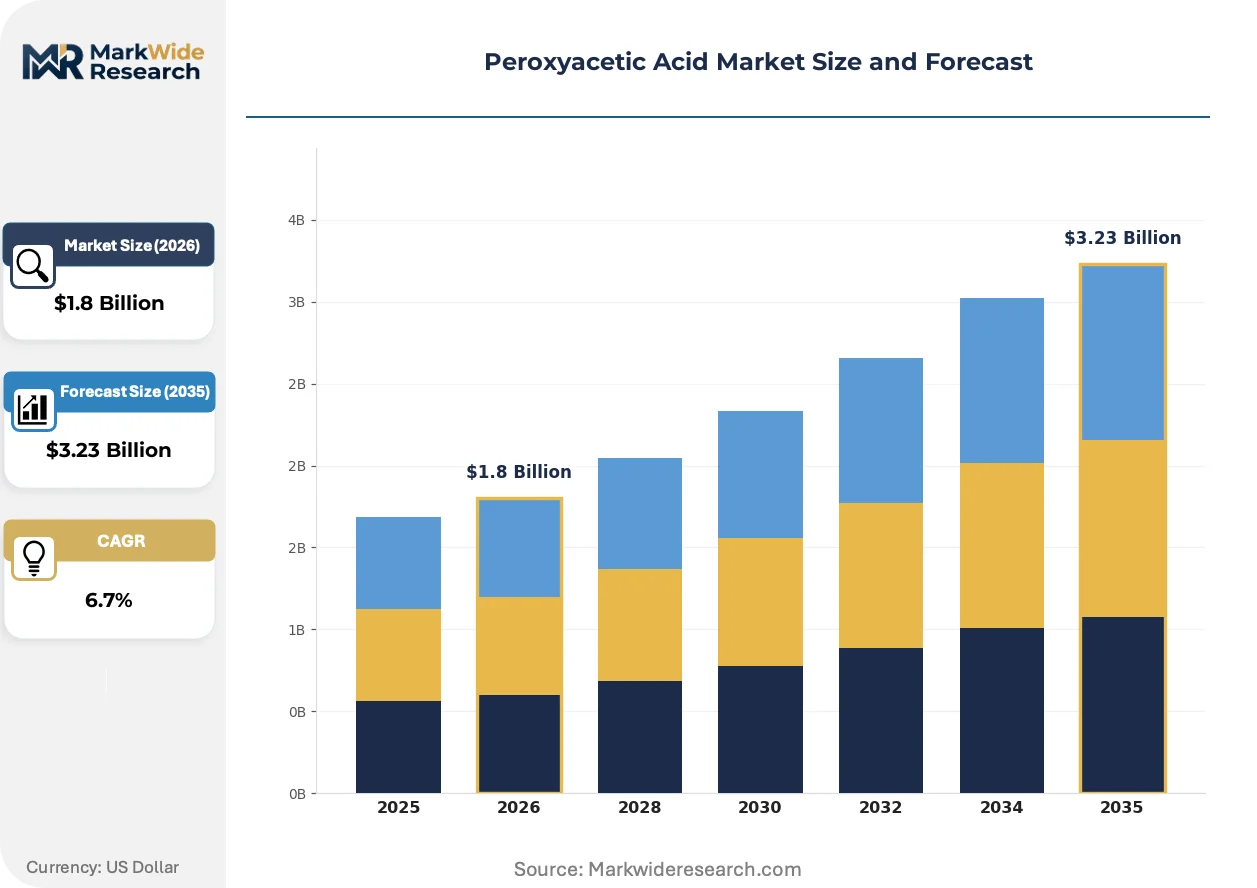
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Water Treatment, Food Processing, Medical Equipment, Agricultural Disinfection Form: Liquid, Solid, Concentrated, Diluted End User: Food Industry, Healthcare Facilities, Agricultural Sector, Industrial Cleaning Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Solvay, Evonik Industries AG, Ecolab Inc., Mitsubishi Gas Chemical Company, Inc., FMC Corporation, Kemira Oyj, Enviro Tech Chemical Services, Inc., PeroxyChem LLC, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peroxyacetic Acid Market Strategic Shifts
Stabilization chemistry advances and generation technology decentralization are compressing the traditional supply chain structure. Processor preference is shifting toward captive production and extended-shelf formulations that reduce inventory risk.
Encapsulated peroxyacetic acid delivery systems using polymer matrix technologies are displacing conventional liquid equilibrium mixtures in large-scale poultry processing operations. Tyson Foods and JBS USA pilot programs demonstrate 40% reduction in stabilizer costs through controlled-release dosing. This displacement pattern is compressing margins for traditional bulk liquid suppliers while rewarding formulation specialists with polymer chemistry capabilities.
REACH regulation evolution under the EU Green Deal is constraining quaternary ammonium stabilizers in favor of biodegradable alternatives. ECHA's 2024 restriction proposal on persistent organic pollutants forces reformulation of legacy peroxyacetic acid blends. Nordic pulp bleaching applications face the most acute compliance pressure, with Kemira Oyj and Solvay accelerating bio-based stabilizer development to maintain European manufacturing positions.
Processor procurement is consolidating terminal sanitizer purchasing through integrated chemical management contracts with hydrogen peroxide producers. Food industry buyers are bundling peroxyacetic acid with upstream peroxide supply under multi-year tolling agreements. This concentration pattern is most visible in the US Southeast poultry corridor, where Tyson, Pilgrim's Pride, and Sanderson Farms have shifted from spot purchasing to captive generation partnerships with peroxide suppliers.
Peroxyacetic Acid Market Segmentation
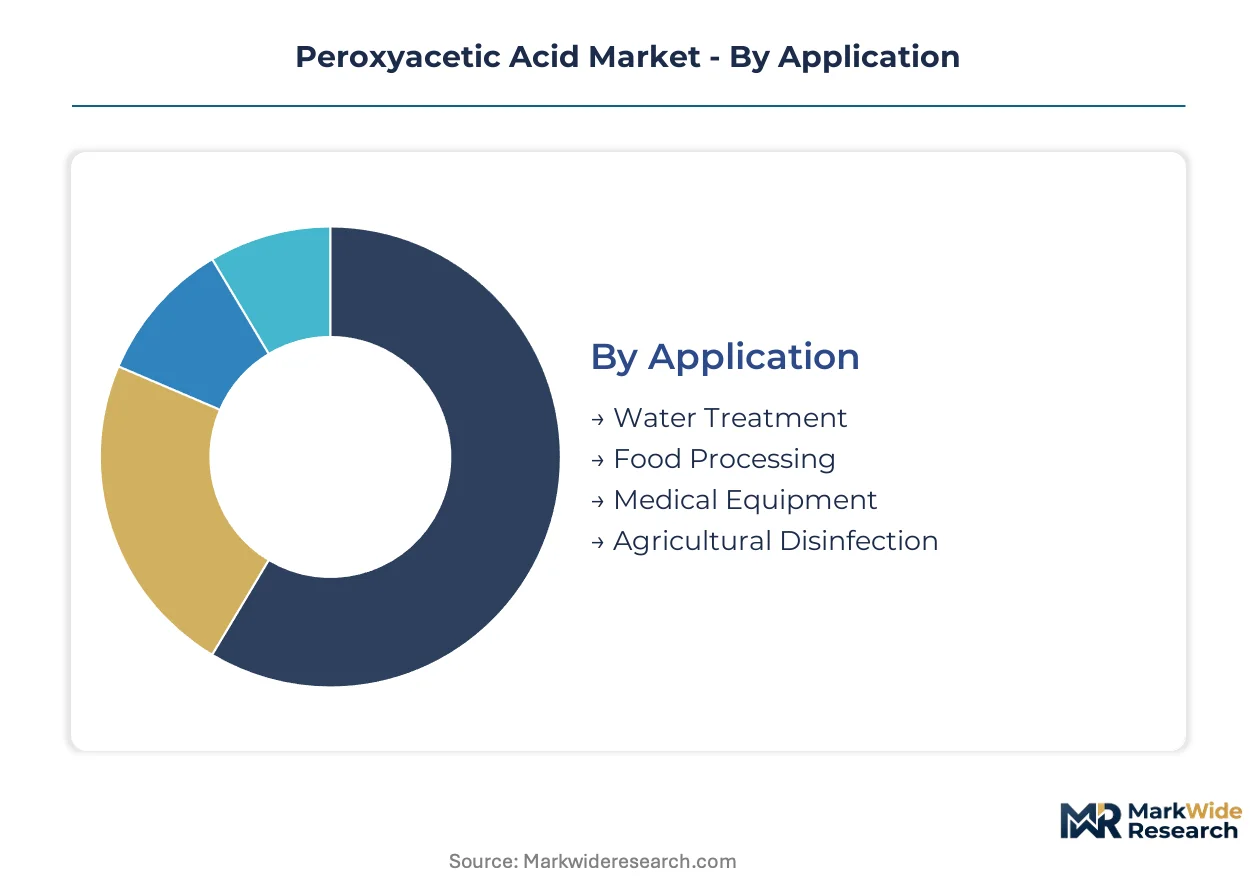
Peroxyacetic acid procurement patterns diverge sharply across application contexts, with regulatory pressure and thermal constraints dictating formulation requirements. Supply chain configuration varies dramatically by segment, from bulk tanker deliveries to food processors versus specialized packaging for healthcare sterilization.
Application:
Food Processing faces the most intense substitution pressure as chlorine-based sanitizers lose regulatory favor under FSMA and EPA Safer Choice mandates.
- Food Processing:Terminal sanitizer applications in poultry and produce operations dominate commercial volume. Demand concentrates in US Southeast processing corridors where microbial reduction mandates are binding and cold-chain sanitation requirements exclude thermal alternatives.
- Water Treatment:Industrial cooling towers and pulp bleaching operations consume concentrated formulations for biofilm control. Nordic pulp mills and US municipal utilities represent the primary demand nodes, though chlorine dioxide retains cost advantage in non-food-contact applications.
- Medical Equipment:Low-temperature sterilization for heat-sensitive surgical instruments and endoscopes drives specialized stabilized formulations. Hospital central sterile supply departments and third-party reprocessors constitute the concentrated buyer base.
- Agricultural Disinfection:Equipment sterilization and post-harvest treatment applications serve greenhouse operations and fresh produce packing. California's Central Valley vegetable processors and Dutch horticultural clusters anchor regional demand.
Food Processing retains volume leadership; Medical Equipment holds the steepest expansion curve.
Form:
Cost tier differentiation separates commodity bulk liquids from premium stabilized concentrates engineered for extended shelf life and reduced transport risk.
- Liquid:Equilibrium mixtures in standard concentrations dominate commercial supply due to established dosing infrastructure and tanker transport economics. Food processors and water treatment facilities prefer liquid for seamless integration with existing chemical feed systems.
- Concentrated:High-purity formulations command margin premiums from large-scale industrial buyers with on-site dilution capability. Pulp bleaching operations and major poultry processors leverage concentrated supply to minimize freight costs and stabilizer content per active unit.
- Solid:Tablet and powder presentations serve remote agricultural applications and emergency sanitation protocols where liquid storage proves impractical. Military field operations and developing-market healthcare facilities constitute niche demand.
- Diluted:Ready-to-use preparations target small-scale end users lacking chemical handling expertise. Restaurant chains and independent medical practices purchase diluted forms to bypass OSHA process safety management triggers.
Liquid formulations retain volume leadership; Concentrated variants gain share fastest through processor captive generation partnerships.
End User:
Customer type determines certification burden, with food-grade notification timelines and EPA FIFRA registration requirements creating structural barriers between segments.
- Food Industry:Poultry, produce, and beverage processors represent the most defended demand pool, tied to FSMA-mandated sanitation protocols and liability exposure from pathogen outbreaks. Tyson Foods, JBS USA, and Chiquita Brands International anchor North American procurement concentration.
- Healthcare Facilities:Hospital sterile processing departments and ambulatory surgery centers drive demand for low-temperature terminal sterilization. US acute care hospitals and German university medical centers lead adoption of peroxyacetic acid over ethylene oxide alternatives.
- Agricultural Sector:Greenhouse operators and post-harvest handlers utilize surface disinfection for equipment and packaging materials. Dutch greenhouse clusters and California strawberry processors exemplify regional adoption patterns.
- Industrial Cleaning:Non-food manufacturing and transportation equipment sanitation represents the most price-sensitive segment, with chlorine and quaternary ammonium compounds retaining substantial share.
Food Industry retains volume leadership; Healthcare Facilities demonstrate the steepest expansion trajectory.
Distribution Channel:
Supply concentration among hydrogen peroxide producers is compressing traditional distribution tiers through direct tolling arrangements with large processors.
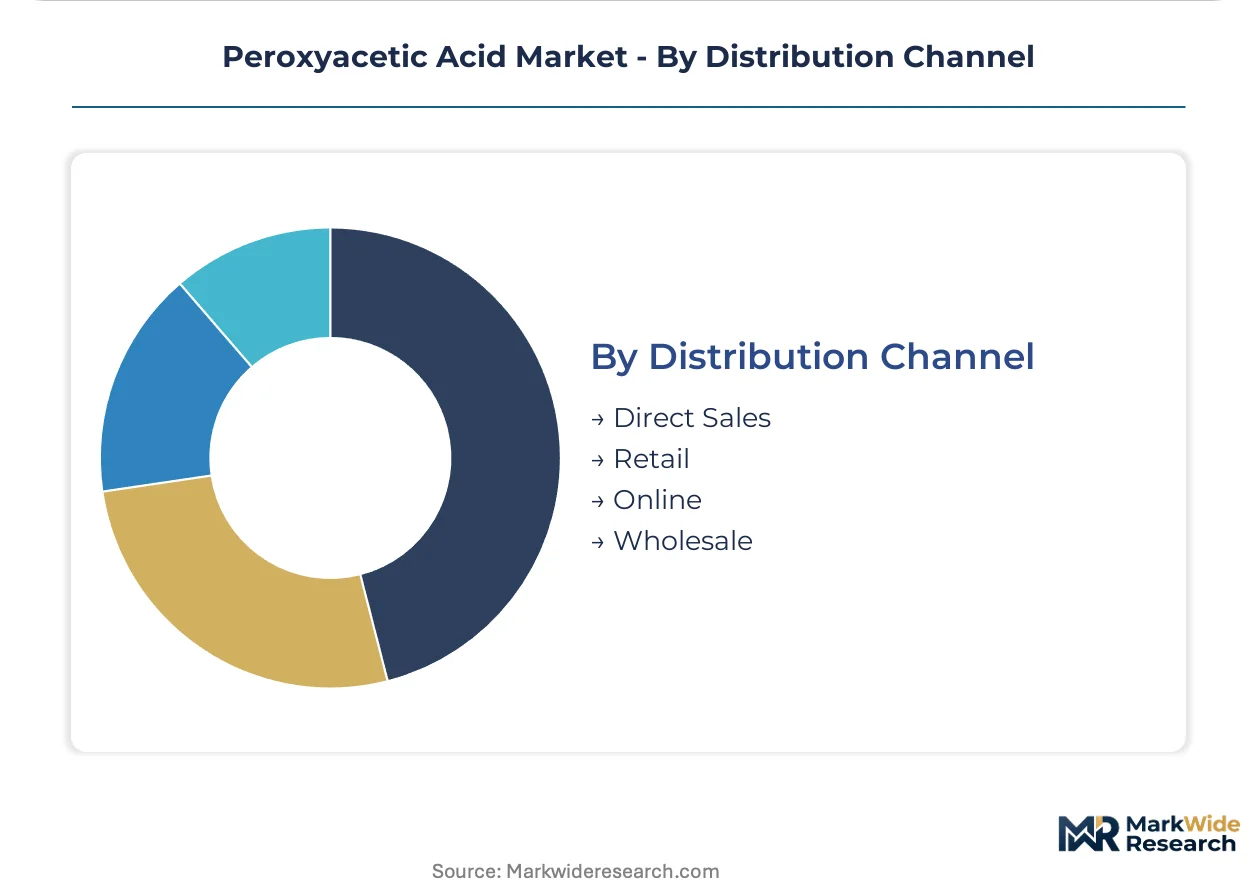
- Direct Sales:Bulk supply agreements between peroxide producers and major food processors eliminate intermediary margins. Tyson Foods' captive generation partnerships with Solvay and Evonik exemplify this channel's expansion.
- Wholesale:Regional chemical distributors serve mid-scale water treatment facilities and agricultural operations with consolidated peroxide and sanitizer portfolios. Univar Solutions and Brenntag maintain positions in this intermediated tier.
- Retail:Small-package sales through agricultural supply cooperatives and janitorial distributors target independent operators. Tractor Supply Company and Grainger stock diluted formulations for customer self-service.
- Online:E-commerce penetration remains limited due to hazardous material shipping restrictions and EPA FIFRA label compliance requirements for antimicrobial claims.
Direct Sales retains volume leadership; Wholesale channels face margin compression from producer forward integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports stabilized peroxyacetic acid formulations to Nordic pulp mills and Dutch food processors, anchoring European supply corridors. This trade pattern reflects ECHA REACH compliance specialization concentrated in German chemical engineering clusters.
United States
Poultry processors in Georgia and Arkansas drive terminal sanitizer consumption under FSMA microbial reduction mandates. EPA FIFRA registration requirements govern antimicrobial label claims for products entering interstate commerce. The US Southeast processing corridor from Gainesville to Springdale anchors captive generation partnerships between peroxide producers and Tyson Foods, Pilgrim's Pride, and Sanderson Farms.
Germany
Specialized stabilized formulations for medical device sterilization command premium positioning in European healthcare supply chains. ECHA REACH obligations constrain quaternary ammonium stabilizers, forcing bio-based alternative development. The Rhine-Ruhr chemical cluster houses Evonik Industries AG production assets serving hospital central sterile supply departments across Germany, France, and the Netherlands.
China
Pulp bleaching operations in Shandong and Jiangsu provinces consume concentrated peroxyacetic acid blends for biofilm control in industrial cooling systems. MIIT industrial chemical standards shape permissible formulation compositions for domestic manufacturing. The Yangtze River Delta chemical corridor from Shanghai to Nanjing concentrates hydrogen peroxide feedstock production supporting downstream peroxyacetic acid synthesis.
Brazil
Post-harvest produce treatment applications expand as FSSAI-aligned standards drive compliance substitution in export-oriented agriculture. ANVISA pharmaceutical and sanitizer registration timelines create 24-36 month product commercialization delays for imported formulations. São Paulo state fruit processors and Minas Gerais dairy cooperatives anchor regional demand concentration for cold-chain sanitation protocols.
Netherlands
Dutch greenhouse horticulture clusters in Westland and Aalsmeer utilize equipment sterilization formulations for hydroponic system maintenance. EU Green Deal REACH evolution restricts legacy stabilizer chemistries, compressing product shelf-life parameters. The Rotterdam-Antwerp chemical corridor enables bulk liquid import and redistribution to Belgian and German agricultural operations.
Peroxyacetic Acid Market Competitive Environment
Listed leaders compete with private specialists across integrated hydrogen peroxide supply chains, creating tiered competitive dynamics. The vendor base concentrates around hydrogen peroxide producers with backward integration into acetic acid sourcing, while formulation specialists occupy niche stabilized-product positions. Three archetypes dominate: integrated peroxide majors, regional tolling partners, and polymer-encapsulation specialists. Capacity expansion in US Southeast captive generation and ECHA-compliant stabilizer reformulation represent the dominant competitive vectors reshaping positioning.
Within the integrated peroxide major tier, Solvay and Evonik Industries AG exemplify European supply anchoring through specialized stabilized formulations. Solvay leverages its hydrogen peroxide chain integration to command premium food-grade certification positions. Evonik Industries AG occupies a parallel position in medical device sterilization applications. Kemira Oyj represents the Nordic pulp bleaching specialization archetype, with concentrated blend engineering for industrial water treatment segments. These three companies illustrate how feedstock control and regulatory compliance capabilities separate tier-one positioning from commodity supply.
| Leading Market Players |
|---|
| Solvay |
| Evonik Industries AG |
| Ecolab Inc. |
| Mitsubishi Gas Chemical Company, Inc. |
| FMC Corporation |
| Kemira Oyj |
| Enviro Tech Chemical Services, Inc. |
| PeroxyChem LLC |
| LANXESS AG |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-thirty-six month FDA food contact notification cycles compress inventory turns for food-grade formulations, concentrating pricing power with hydrogen peroxide producers who control captive generation partnerships and backward integration into acetic acid sourcing. This lead-time structure rewards integrated suppliers with Solvay and Evonik Industries AG commanding premium positions while fragmenting margin capture among non-integrated tolling partners.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the peroxyacetic acid market. Pricing stratifies across food-grade certified, industrial standard, and economy bulk tiers differentiated by FDA notification status and stabilizer sophistication. Cost compression in standard liquid formulations is intensifying because encapsulated delivery systems displace conventional equilibrium mixtures at Tyson Foods and JBS USA processing sites. Small-scale agricultural operators exhibit highest price sensitivity while medical device sterilization buyers accept substantial premiums for ECHA REACH-compliant stabilized grades.
Supply Chain Analysis
Anthraquinone-process hydrogen peroxide feedstock availability underwrites peroxyacetic acid manufacturing economics across Belgium, Germany, and the United States. Production draws from concentrated acetic acid supply centered on Gulf Coast petrochemical corridors and European chemical clusters. Single-source vulnerability in quaternary ammonium stabilizer chemistry threatens European formulation continuity as ECHA restrictions advance under EU Green Deal evolution. Distribution runs through direct tolling agreements with major poultry processors, compressing traditional wholesale chemical distributor margins in the US Southeast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Tyson Foods, JBS USA, and Pilgrim's Pride through captive generation partnerships that disintermediate traditional chemical distribution tiers. This procurement consolidation fragments margin capture upstream while rewarding backward-integrated hydrogen peroxide producers with volume commitments and formulation co-development rights.
For Market Incumbents: Fortify food-grade certification positions through accelerated FDA notification filings for next-generation bio-based stabilizer formulations. Chlorine dioxide substitution in non-food water treatment segments threatens volume retention in industrial grades; defend by expanding on-site generation equipment partnerships with major processors. Prioritize ECHA REACH pre-compliance investment to capture Nordic pulp bleaching share as legacy quaternary ammonium stabilizers face restriction.
For New Entrants and Emerging Players: Differentiate on polymer encapsulation chemistry capabilities that reduce stabilizer costs for large-scale poultry operations. Medical device sterilization applications in German and US hospital systems represent the most penetrable vertical given ethylene oxide displacement pressure and specialized formulation requirements. Pursue joint development agreements with hydrogen peroxide producers lacking in-house encapsulation expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across on-site generation system deployment as electrolytic units reduce transport and stabilizer dependency for large processors. Five-to-ten year viability favors acquisition targets with captive generation partnerships or bio-based stabilizer intellectual property. Monitor EPA FIFRA re-registration timelines and emerging state-level discharge restrictions as inflection indicators for regional manufacturing footprint shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Generation Partnership | Tyson Foods' tolling agreements with Solvay eliminate distributor margins and lock in volume. |
| Bio-Based Stabilizer Development | Kemira Oyj's REACH-compliant reformulation defends Nordic pulp bleaching market position. |
| Encapsulation Technology Licensing | Polymer matrix delivery systems reduce stabilizer costs 40% in JBS USA pilot programs. |
| Food-Grade Certification Investment | FDA notification timelines create 18-36 month barriers protecting incumbent positions. |
| Direct Sales Channel Expansion | Producer forward integration into US Southeast poultry corridor compresses wholesale margins. |
Study Parameters
Desk research of EPA FIFRA registration databases, FDA food contact notification filings, and ECHA REACH restriction proposals preceded structured interviews with hydrogen peroxide plant managers, poultry processor procurement leads, medical device sterilization engineers, and chemical distribution channel partners. Secondary validation drew from SEC 10-K filings of listed chemical producers, customs trade data for peroxyacetic acid formulations, and American Chemistry Council sector reports. Bottom-up volume modeling triangulated against top-down hydrogen peroxide feedstock consumption estimates.
Variance decomposition across application segments, formulation grades, and end-user categories shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include food processing, water treatment, medical equipment, and agricultural disinfection applications crossed with liquid, concentrated, solid, and diluted form factors. CAGRs derived from weighted average of historical feedstock demand elasticity and regulatory-driven substitution coefficients. Stabilizer chemistry evolution and captive generation adoption curves served as industry-specific forecast inputs.
Material uncertainties — hydrogen peroxide feedstock volatility, ECHA stabilizer restriction implementation timing, and FSMA enforcement intensity variation — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory continuity and substitution rate persistence. Practitioners should keep alternative scenarios live as EPA Safer Choice program expansion and chlorine dioxide cost positioning evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Permanganate Market
Chemicals
Methylamines Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Oxybenzone Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Stimulation Materials Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Calcium Carbide Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Sulfur Chemicals Market
Chemicals
Tributyl Phosphate Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Phenothiazine Market
Chemicals
Solder Flux Market