
 Europe Flame Retardant Chemicals Market | 2026-2036
Europe Flame Retardant Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flame Retardant Chemicals Market Foresight
Halogen-free specification tiers is reorganizing procurement priorities across European manufacturing supply chains. BASF SE leverages its integrated polymer additive platform to serve automotive OEMs seeking low-smoke formulations. LANXESS AG anchors its position through phosphorus-based product specialization for electrical housings and connector systems. Albemarle Corporation competes via mineral flame retardant scale, particularly aluminum hydroxide grades for wire and cable sheathing.
Flame retardant chemicals are functional additives formulated to inhibit ignition, suppress combustion, or reduce smoke density in polymer substrates, typically incorporated at loadings between 15% and 60% by weight depending on base resin and target UL 94 rating. Their primary purpose is to ensure compliance with fire safety codes in construction, transportation, and consumer electronics applications. Aluminum hydroxide dominates volume demand as a low-cost, non-toxic mineral option, though phosphorus compounds capture disproportionate margin pools due to stricter halogen restrictions in Germany and France. Brominated flame retardants retain niche positions in electrical connectors where performance thresholds exceed mineral capabilities, while masterbatch forms gain traction among compounders seeking processing efficiency and dust reduction.
REACH registration requirements and the EU Green Deal chemical sustainability framework are tightening market access for legacy halogenated products while accelerating ECHA-driven substitution timelines. The F-Gas Regulation and CE marking directives for construction materials enforce testing protocols that favor intumescent and phosphorus-based systems. Stakeholders must monitor evolving substance restriction proposals and align R&D portfolios with anticipated MDR-aligned material safety dossiers before compliance windows narrow.
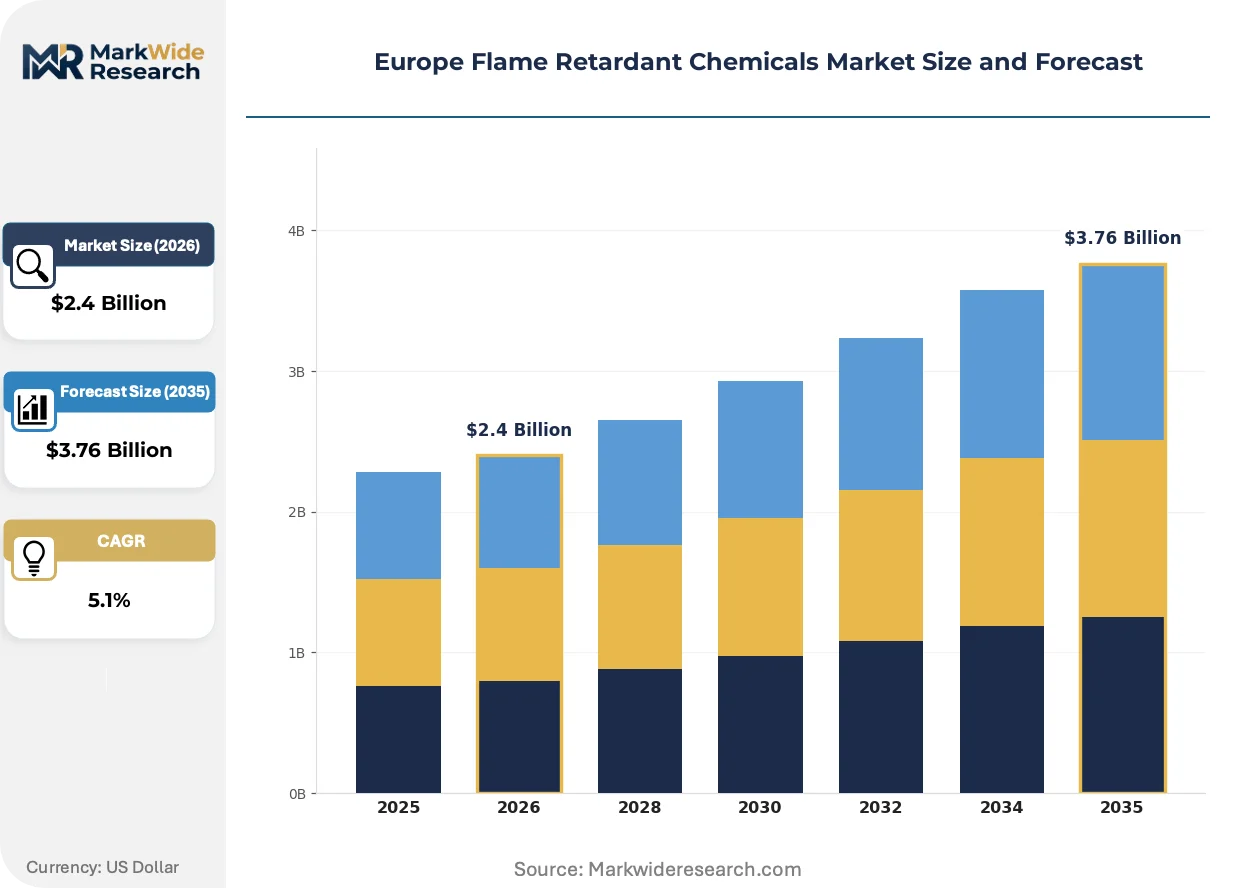
Market Dynamics
REACH restrictions on halogenated compounds and the EU Green Deal's material safety mandates are redirecting formulation investments toward phosphorus-based and mineral alternatives across European manufacturing supply chains.
Growth Catalysts
- Construction sector substitution:Builders across Germany and France are replacing legacy additives with phosphorus-based and mineral flame retardants to meet stricter building codes. Electrical housing and connector systems drive specification upgrades.
- ECHA-driven substitution timelines:REACH registration requirements are accelerating phase-outs of brominated compounds. Compounders reformulate wire and cable sheathing to maintain market access.
- Automotive OEM protocols:Stricter flammability standards from vehicle manufacturers in Germany's industrial corridor are pulling low-smoke formulations into interior and under-hood applications.
Market Restraints
- Mineral loading inefficiency:Aluminum hydroxide requires 15% to 60% by weight incorporation to achieve target UL 94 ratings, compressing compounder margins and limiting design flexibility.
- Phosphorus supply concentration:Specialized phosphorus-based intermediate production clusters in limited European locations create input vulnerability for formulators.
- Performance gaps in electrical connectors:Brominated flame retardants retain niche positions where mineral and phosphorus alternatives fail to meet threshold specifications, complicating full substitution.
Strategic Opportunities
- Masterbatch processing adoption:Compounders seeking dust reduction and processing efficiency are converting to concentrated additive forms, opening formulation service revenue streams.
- Intumescent system expansion:CE marking directives for construction materials favor intumescent coatings in French and German commercial building applications.
- F-Gas Regulation alignment:The regulatory framework for fluorinated gases creates parallel compliance pathways that flame retardant suppliers can leverage for cross-product certification.
Industry Challenges
- MDR-aligned dossier preparation:Medical device regulation material safety requirements demand expanded toxicological documentation that stretches SME technical resources.
- Legacy formulation integration:Compounders face technical friction retrofitting phosphorus systems into established halogenated production lines without process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flame Retardant Chemicals Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 5.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Hydroxide, Antimony Trioxide, Brominated Flame Retardants, Phosphorus Compounds End Use Industry: Building & Construction, Electrical & Electronics, Automotive, Textiles Form: Granules, Powders, Liquids, Masterbatches Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, LANXESS AG, Albemarle Corporation, ICL Group Ltd, Clariant AG, Italmatch Chemicals S.p.A, Nabaltec AG, J.M. Huber Corporation, Avient Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flame Retardant Chemicals Market Shifts & Advancements
Formulation chemistry is pivoting toward synergistic mineral-phosphorus blends as compounders balance cost, performance, and regulatory compliance in polymer additive selection.
Phosphorus-nitrogen intumescent systems are supplanting traditional halogenated approaches in polyolefin and engineering resin applications. German automotive suppliers and French construction material producers are adopting these systems at accelerated specification cycles. The transition is compressing demand for legacy brominated additive volumes while expanding technical service requirements for formulation optimization.
REACH substance restriction proposals are tightening market access windows for legacy chemistries. ECHA evaluation processes are extending registration timelines and elevating data requirements for halogenated compounds. Electrical and electronics segments in Germany are responding by front-loading reformulation investments to secure continuity of supply before restriction enforcement dates.
Specification authority is migrating from compounders to OEM material engineers who enforce proprietary flammability protocols beyond base regulatory minimums. Tier-1 automotive and appliance manufacturers in Germany's industrial corridor now direct additive selection through approved supplier lists. This concentration of buying influence is visible across Bavarian automotive clusters and Rhineland electronics manufacturing zones.
Europe Flame Retardant Chemicals Market Segmentation
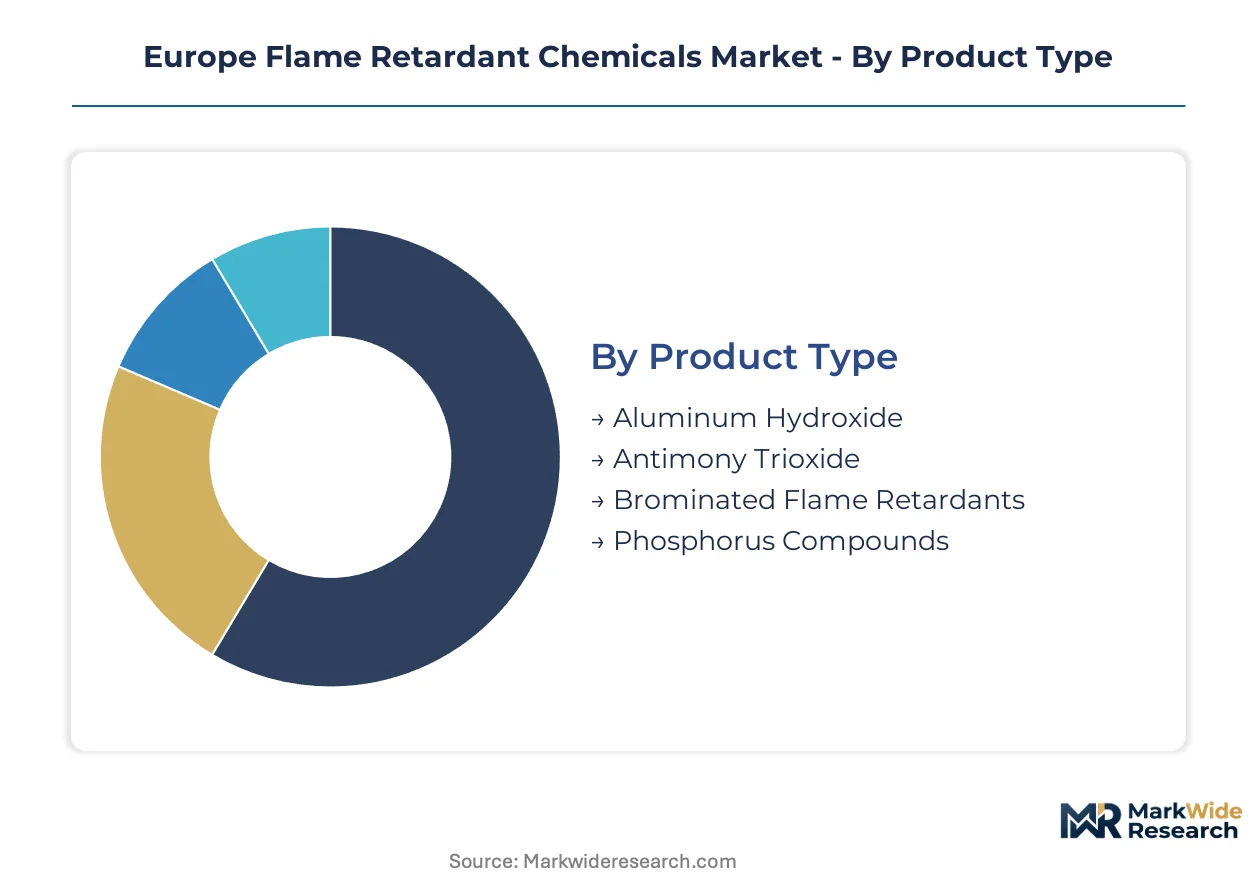
Flame retardant procurement patterns diverge sharply across product chemistries and end-use specifications. Formulators select additive platforms based on polymer compatibility, regulatory compliance windows, and processing economics rather than commodity pricing alone.
Product Type:
Domestic production clusters in Germany and France supply phosphorus compounds and mineral grades to regional compounders, while brominated specialties retain import dependency from Asian manufacturers.
- Aluminum Hydroxide:Mineral filler functioning through endothermic decomposition at 200°C, releasing water vapor to dilute combustible gases. German wire and cable sheathing producers consume substantial volumes despite high loading requirements that compress design flexibility.
- Phosphorus Compounds:Organophosphate and phosphonate chemistries operating through char formation and radical scavenging. French electrical housing manufacturers and Bavarian automotive suppliers are accelerating specification shifts toward these halogen-free alternatives as REACH restriction windows narrow.
- Brominated Flame Retardants:Legacy halogenated systems retained in high-performance electrical connectors where mineral and phosphorus alternatives fail threshold specifications.
- Antimony Trioxide:Synergist deployed primarily with brominated systems in flame-retardant masterbatches for engineering resins.
Aluminum Hydroxide commands the established base. The steepest expansion runs through Phosphorus Compounds.
End Use Industry:
Application-driven procurement concentrates in sectors facing the most stringent fire safety enforcement and OEM material qualification protocols.
- Building & Construction:CE marking directives and national building codes in Germany and France mandate intumescent and mineral systems for insulation, cladding, and structural components. Commercial retrofit activity in the Rhineland and Île-de-France regions sustains formulation demand.
- Electrical & Electronics:RoHS-aligned restrictions and ECHA substance evaluations are forcing reformulation of wire sheathing, connector housings, and printed circuit board laminates. German electronics manufacturing zones around Munich and Stuttgart enforce proprietary flammability protocols beyond base regulatory minimums.
- Automotive:Interior and under-hood applications in Germany's industrial corridor pull low-smoke formulations as OEMs tighten material safety dossier requirements.
- Textiles:Public venue upholstery and protective clothing specifications in France and Italy absorb phosphorus-nitrogen intumescent treatments.
Building & Construction anchors volume consumption. Electrical & Electronics is gaining share fastest as substitution timelines compress.
Form:
Processing efficiency preferences are reshaping physical delivery formats, with dust exposure regulations and compounding automation driving format selection.
- Masterbatches:Concentrated additive carriers reducing dust exposure and improving dispersion uniformity. German compounders serving automotive OEMs are converting to these forms to streamline production line integration.
- Powders:Conventional delivery format for mineral fillers, requiring dust control infrastructure that smaller compounders find capital-intensive.
- Granules:Intermediate dust-reduced format for phosphorus compounds and synergist blends.
- Liquids:Specialized organophosphate esters for textile finishing and coating applications in French industrial textile clusters.
Powders retain the volume base. Masterbatches are expanding most quickly as processing automation spreads.
Distribution Channel:
Supply route selection correlates with customer scale and technical service intensity requirements across the regional market.
- Direct Sales:Technical additive suppliers maintain direct relationships with tier-1 automotive and electronics OEMs in Germany's industrial corridor. These accounts demand formulation support and joint development programs that distributors cannot resource.
- Distributors:Regional chemical distributors serve mid-size compounders in France, Italy, and Benelux with stocked mineral fillers and standard phosphorus grades.
- Wholesalers:Bulk mineral filler movement for construction sector applications with lower technical complexity.
- Online Retail:Emerging channel for specialty additive samples and small-volume procurement by research compounders and prototype shops.
Direct Sales commands premium formulation accounts. Distributors are climbing the fastest as mid-tier compounder consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European flame retardant chemicals trade flows reflect a net importer position for specialty phosphorus compounds and brominated grades, while mineral fillers move intra-regionally from German and French production hubs. Regulatory divergence between REACH-aligned member states and emerging EU candidate markets creates friction in cross-border formulation standardization.
Germany
Automotive OEM material qualification protocols in Bavaria and Baden-Württemberg pull low-smoke phosphorus formulations into interior and under-hood applications. ECHA substance restriction evaluations accelerate reformulation timelines for wire and cable producers. The Rhineland industrial corridor hosts concentrated compounding capacity serving electrical housing manufacturers migrating from halogenated systems.
France
Commercial building retrofit activity in Île-de-France and Auvergne-Rhône-Alpes sustains intumescent coating demand for cladding and insulation compliance. CE marking directives for construction materials enforce testing protocols favoring mineral and phosphorus-based systems. Lyon-based textile finishers absorb phosphorus-nitrogen treatments for public venue upholstery specifications.
Italy
Emilia-Romagna and Lombardy machinery producers specify flame-retardant polymers for industrial equipment housings facing export market compliance. The national building code adaptation to EU energy efficiency standards drives insulation material upgrades. Domestic compounders source aluminum hydroxide from German suppliers while developing local phosphorus intermediate capabilities.
United Kingdom
Post-REACH regulatory divergence creates parallel compliance pathways for construction and electronics applications. The Midlands automotive cluster maintains material safety dossiers aligned with German OEM parent company standards. London commercial development sustains intumescent specification demand despite slower regulatory harmonization with EU Green Deal timelines.
Poland
Warsaw and Kraków manufacturing zones absorb standard-grade mineral fillers for construction and appliance applications. EU cohesion fund infrastructure investments expand building stock requiring fire safety compliance. Western Polish compounders serve as distribution nodes for German-produced phosphorus compounds entering Eastern European markets.
Europe Flame Retardant Chemicals Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling phosphorus intermediate supply chains and mineral extraction assets. German and Swiss-headquartered players anchor premium formulation tiers through direct OEM relationships, while mid-scale specialists occupy regional distribution channels. Strategic moves center on backward integration into phosphorus raw material sourcing and masterbatch processing capacity expansion to capture compounding efficiency premiums.
Among Germany-based integrated suppliers, BASF SE and LANXESS AG exemplify the conglomerate archetype with polymer additive platform breadth. Albemarle Corporation represents the mineral specialization vector with aluminum hydroxide scale. These three anchors illustrate how competitive positioning stratifies across integrated chemistry, mineral dominance, and phosphorus-based formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS AG |
| Albemarle Corporation |
| ICL Group Ltd |
| Clariant AG |
| Italmatch Chemicals S.p.A |
| Nabaltec AG |
| J.M. Huber Corporation |
| Avient Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day phosphorus intermediate lead times concentrate pricing power with German and Dutch integrated suppliers serving automotive OEMs, while mineral filler inventories at 45 days compress margins for smaller compounders lacking backward integration into aluminum hydroxide sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the European market. Pricing stratifies across REACH-certified premium grades, standard phosphorus compounds, and economy mineral fillers differentiated by purity level and technical service bundling. Cost compression in standard phosphorus tiers is intensifying because French and German construction compounders are consolidating purchase volumes. Mid-size wire and cable producers exhibit the highest price sensitivity, while tier-1 automotive OEMs prioritize formulation support over unit cost.
Supply Chain Analysis
Strategic stockpiling of phosphorus intermediates prevails among German automotive suppliers confronting ECHA restriction uncertainty, while just-in-time mineral filler delivery suffices for construction sector compounders with predictable demand profiles. Supply concentrates in Germany, France, and Belgium for phosphorus compounds, with brominated specialties drawing from Asian manufacturing. Raw material dependencies center on phosphate rock, elemental phosphorus, and alumina trihydrate feedstocks. Single-source vulnerability runs through specialized phosphorus intermediate production clusters. Distribution runs through direct technical sales for OEM accounts and regional chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation services and regulatory compliance consulting attach to base chemical sales at expansion rates exceeding mineral filler volumes, as OEM material qualification protocols demand expanded toxicological documentation and joint development programs.
For Market Incumbents: Shield phosphorus intermediate supply positions through captive production or exclusive offtake agreements with Dutch and Belgian producers, as ECHA-driven substitution timelines tighten input availability. Deepen masterbatch processing capacity in Germany's industrial corridor to capture compounding efficiency premiums and reduce customer switching. Certification investment in MDR-aligned material safety dossiers defends against emerging specialty compounders from Asia. For New Entrants and Emerging Players: Technical service gaps in phosphorus-nitrogen intumescent system optimization present entry points where incumbent chemical conglomerates under-serve mid-size French construction compounders. Target Polish and Czech manufacturing zones absorbing EU cohesion fund infrastructure investments with standard-grade mineral filler distribution partnerships. Lead with formulation support bundled to base chemical supply as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because REACH restriction windows and EU Green Deal chemical sustainability frameworks create durable demand for substitution-enabling technologies. Acquisition targets include mid-scale phosphorus compound specialists with established ECHA registration dossiers and masterbatch processing capabilities. Watch ECHA substance restriction proposal advancement rates as the inflection signal indicating substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Intermediates | Secures supply continuity for German automotive OEMs facing ECHA restriction uncertainty. |
| Masterbatch Processing Capacity Expansion | Captures compounding efficiency premiums from Bavarian automotive cluster demand. |
| Green Manufacturing Transition | Aligns production with EU Green Deal chemical sustainability framework requirements. |
| Long-term Supply Agreement | Locks in mineral filler offtake from Rhineland construction retrofit activity. |
| Joint Venture | Combines phosphorus formulation expertise with French intumescent coating application knowledge. |
Research Methodology
A standing panel of polymer compounding plant managers, procurement leads at German automotive OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance restriction proposals, Cefic industry statistics, customs trade data, and SEC filings of listed chemical conglomerates. Bottom-up volume builds across product chemistry and end-use segments triangulated against top-down market sizing from production capacity analysis.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation by product chemistry tier, end-use industry, physical form, and regional production hub. CAGRs derived from regression analysis of historical consumption patterns applied to projected construction and automotive output. Industry-specific forecast inputs included ECHA regulatory timeline assumptions and OEM material qualification protocol diffusion rates.
Underlying assumptions cover REACH restriction enforcement schedules and EU Green Deal implementation pace, with deviation risk concentrated in accelerated ECHA substance evaluation timelines. Forecasts reflect these documented conditions. Revision becomes warranted when automotive OEM flammability protocol stringency crosses thresholds that displace current formulation approaches.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Canada Methanol Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Fluorochemicals Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
1-Methylimidazole Market
Chemicals
Tin Chemicals Market
Chemicals
Maleic Acid Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Aerosol Insecticides Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Trimethylamine Market
Chemicals
Global Diphenylmethane Diisocyanate Market