
 Asia-Pacific Construction Chemicals Market | 2026-2036
Asia-Pacific Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Construction Chemicals Market Outlook
Market Context
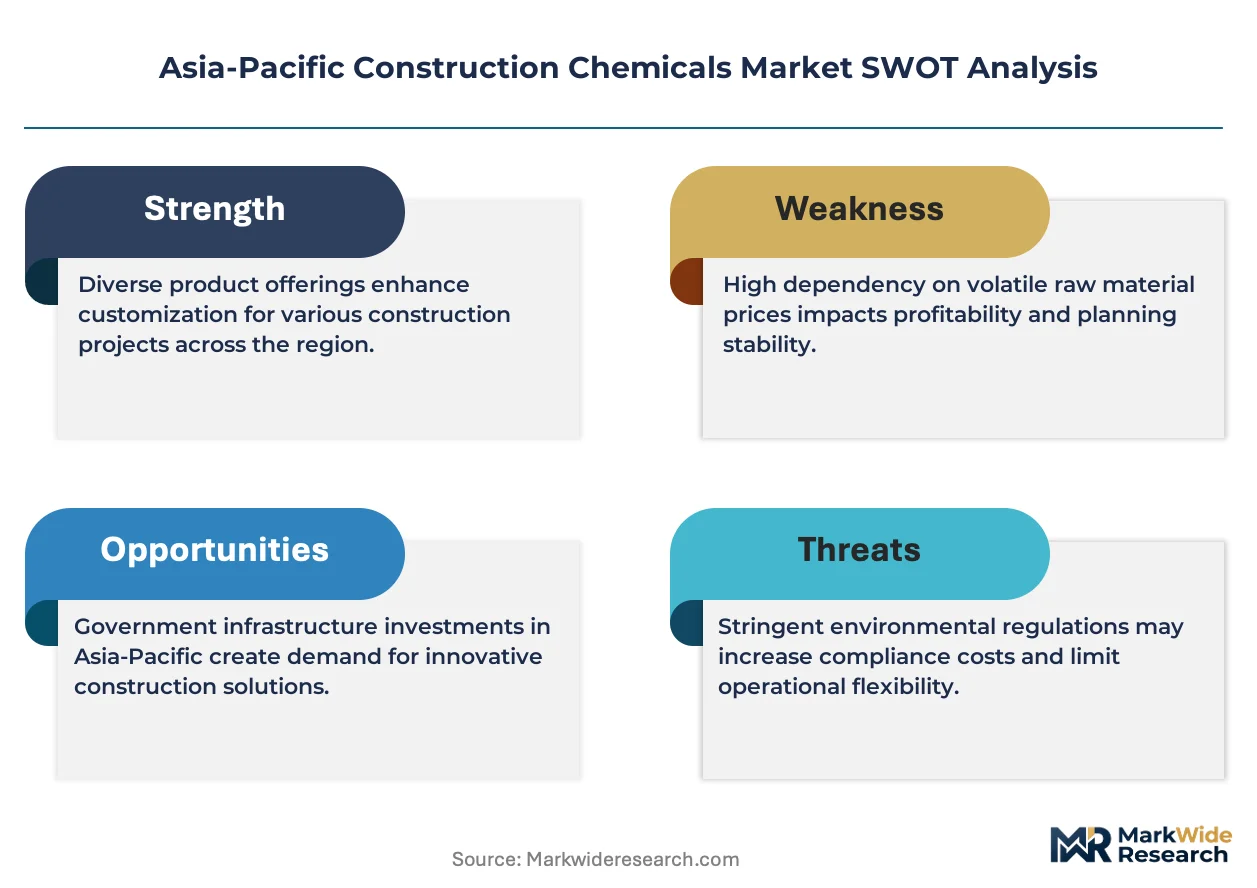
Buyer concentration among tier-one contractors across Southeast Asia is recalibrating procurement standards for construction chemicals. Sika AG leverages its waterproofing specialization to dominate high-specification infrastructure bids. MAPEI S.p.A. sustains competitive positioning through deep distribution networks across ASEAN markets. BASF SE anchors regional supply security with localized manufacturing complexes in China and India.
Technical Definition and Segment Structure
Construction chemicals encompass formulated admixtures, sealants, adhesives, and protective coatings engineered to modify concrete rheology, durability, and curing performance through polymer or cement-based chemistries. These formulations serve primarily to extend structural service life and enable aggressive architectural designs in corrosive or seismic environments. Admixtures command the largest value pool as masterbatch concentrates justify premium pricing against commodity cement. Polymer-based technology segments attract disproportionate R&D allocation due to performance advantages in tropical humidity cycles. Cement-based systems retain volume leadership across cost-sensitive residential applications where specification authority fragments among local contractors.
Regulatory Framework
China's MEE enforces escalating carbon intensity thresholds that compel reformulation away from ordinary Portland cement binders toward geopolymers and supplementary cementitious materials. India's BIS certification mandates for concrete admixtures create compliance barriers for uncertified imports while elevating quality baselines across public infrastructure tenders. Australia's TGA-aligned state building codes impose strict volatile organic compound limits on interior-grade sealants and coatings. Stakeholders must monitor divergence between national green building rating tools and harmonized ASEAN standards to anticipate specification fragmentation.
Market Dynamics
China's dual carbon goals from MEE are forcing wholesale reformulation of cementitious binders across the Asia-Pacific construction chemicals value chain, compressing timelines for geopolymer commercialization while elevating procurement scrutiny on embodied carbon metrics.
Growth Catalysts
- MEE Carbon Intensity Thresholds:China's escalating emissions standards are mandating supplementary cementitious materials in all provincial infrastructure tenders above designated scale thresholds, creating guaranteed offtake for low-carbon admixture suppliers.
- Seismic Retrofitting Mandates:Japan's METI building resilience codes are accelerating specification of high-ductility polymer modifiers for existing commercial stock across Tokyo and Osaka metropolitan zones.
- India's Smart Cities Mission:Urban infrastructure densification from Mumbai to Delhi is concentrating demand for self-compacting concrete technologies that reduce labor intensity in constrained construction corridors.
Market Restraints
- Alumina-Silicate Supply Concentration:Geopolymer feedstock availability clusters around specific fly ash and slag processing regions, exposing formulators to rail freight bottlenecks and regional monopoly pricing from dominant waste processors.
- BIS Certification Friction:India's mandatory BIS admixture certification imposes 18-24 month validation timelines that exclude uncertified imports from public sector tenders, constraining supply elasticity during demand spikes.
- Epoxy Resin Import Dependency:Protective coatings manufacturers remain tethered to Northeast Asian petrochemical supply for specialty hardeners, translating crude volatility directly into margin compression.
Strategic Opportunities
- Vietnam Infrastructure Pipeline:The North-South Expressway and Long Thanh International Airport are creating first-mover advantages for admixture suppliers establishing technical service presence ahead of specification lock-in.
- Digital Procurement Platforms:Tier-one contractors across ASEAN are consolidating chemical purchasing through integrated supply chain platforms that favor certified suppliers with real-time batch documentation capabilities.
- Indonesia's New Capital Relocation:Nusantara construction is mandating green building certification compliance that rewards low-carbon concrete technologies with preferential tender scoring.
Industry Challenges
- Geopolymer Application Engineering:Contractor familiarity gaps with alkali-activated binder handling are generating field performance inconsistencies that damage technology credibility and trigger warranty disputes.
- Cross-Border Formulation Registration:Divergent national standards across ASEAN member states force redundant testing protocols that extend product launch timelines and inflate regulatory compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Construction Chemicals Market |
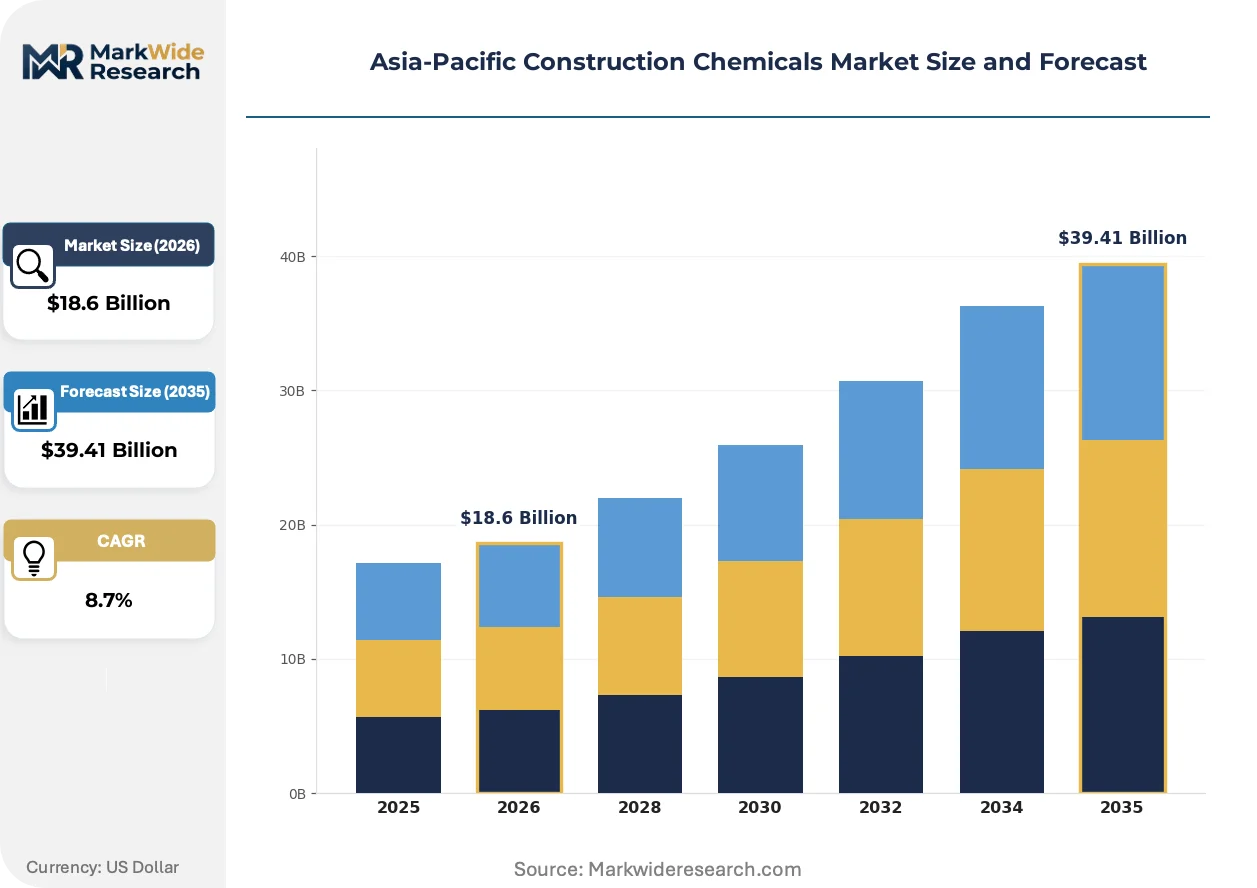
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Engineers, Architects, Project Owners Technology: Polymer-based, Cement-based, Geopolymer, Others |
| Companies Covered | Saint-Gobain, MAPEI S.p.A., Sika AG, Pidilite Industries Limited, Fosroc Inc., Beijing Oriental Yuhong Waterproof Technology Co., Ltd., RPM International Inc., Jiangsu Subote New Materials Co., Ltd., BASF SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Construction Chemicals Market Strategic Shifts
Formulation chemistry, compliance architecture, and procurement mechanics are simultaneously transforming across the Asia-Pacific construction chemicals market, compressing product lifecycles and elevating technical service intensity.
Alkali-activated binders are rewriting competitive positioning in high-specification infrastructure segments. State-owned contractors in China and Vietnam are specifying geopolymers for marine and aggressive soil applications where sulfate resistance dominates performance criteria. This chemistry shift is compressing ordinary Portland cement volumes in premium tender categories while fragmenting specification authority between materials engineers and sustainability officers.
MEE enforcement protocols are tightening disclosure requirements for embodied carbon in all public infrastructure above designated contract values. Manufacturers must now submit verified Environmental Product Declarations to qualify for provincial tender shortlists, with non-compliant formulations facing automatic disqualification regardless of technical performance. India's BIS is harmonizing with this trajectory through draft standards on admixture carbon footprint labeling anticipated for mandatory implementation.
Consolidated procurement by tier-one EPC contractors is displacing fragmented purchasing across project sites. Sika AG and MAPEI S.p.A. are embedding technical service teams directly within contractor engineering departments to secure multi-year supply agreements with performance guarantees. This relationship model concentrates volume with integrated suppliers while marginalizing distributors lacking application engineering capabilities, with the pattern most visible across Southeast Asian mega-project clusters.
Asia-Pacific Construction Chemicals Market Segmentation
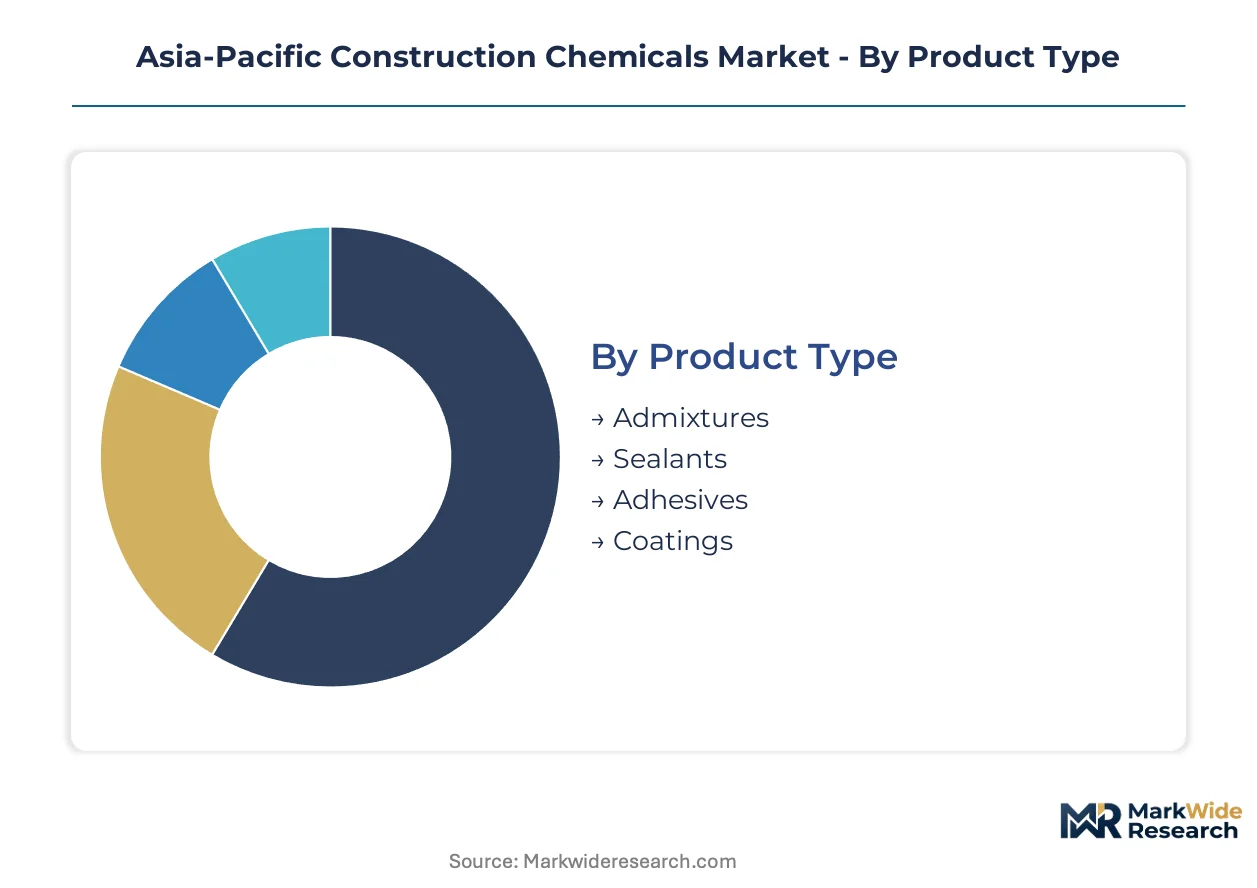
Construction chemicals serve distinct performance requirements across project scales and environmental exposures. Segment boundaries align with specification authority, procurement budgets, and compliance thresholds rather than interchangeable commodity logic.
Product Type:
Upgrade cycles vary dramatically across chemical categories, with infrastructure-grade admixtures demanding reformulation every 3-5 years versus decorative coatings extending to 8-10 year replacement horizons.
- Admixtures:Masterbatch concentrates modify concrete rheology, accelerate curing, and enhance sulfate resistance through polycarboxylate ether or naphthalene sulfonate chemistries. China's MEE carbon intensity thresholds are forcing rapid displacement of conventional superplasticizers with low-embodied-carbon alternatives across provincial infrastructure tenders.
- Sealants:Polyurethane and silicone formulations create watertight joints in expansion gaps and façade connections. Australia's TGA-aligned state codes on volatile organic compound limits are concentrating specification toward low-VOC hybrid polymers in Sydney and Melbourne commercial developments.
- Adhesives:Epoxy, acrylic, and cementitious bonding agents anchor tiles, structural rebars, and prefabricated elements. Tile-setting applications dominate volume across India's residential corridor from Mumbai to Delhi.
- Coatings:Protective layers shield concrete and steel from carbonation, chloride ingress, and chemical attack. Marine infrastructure specifications in Vietnam and Indonesia drive premium epoxy and polyurethane system adoption.
Admixtures sit at the top of the volume ranking, with geopolymer-enabled formulations climbing the fastest.
Application:
Cost tier stratification separates specification-grade infrastructure chemicals from commodity residential products, with tender thresholds determining admixture performance grades.
- Residential:Cost-sensitive single-family and multi-family housing drives cement-based adhesive and basic waterproofing consumption. India's affordable housing push concentrates demand in tier-2 and tier-3 cities across Maharashtra and Uttar Pradesh.
- Commercial:High-rise offices, retail complexes, and hospitality projects specify self-compacting concrete and advanced curing compounds. Japan's METI seismic retrofitting mandates accelerate polymer-modified mortar specification across Tokyo's aging commercial stock.
- Infrastructure:Bridges, tunnels, dams, and transportation corridors command premium admixture grades with extended durability guarantees. Vietnam's North-South Expressway and Long Thanh International Airport anchor regional demand for sulfate-resistant and corrosion-inhibiting formulations.
- Industrial:Manufacturing facilities, power plants, and process industries require chemical-resistant flooring and heavy-duty protective coatings. Indonesia's Nusantara new capital construction mandates green-certified industrial buildings with low-carbon concrete specifications.
Infrastructure commands the highest value per ton, with commercial applications expanding most quickly across Southeast Asian urban densification zones.
End User:
Customer type determines procurement channel access, with tier-one contractors consolidating chemical purchasing through integrated supply chain platforms that marginalize fragmented distributor networks.
- Contractors:Direct procurement of admixtures, sealants, and site-applied coatings dominates volume. Tier-one EPC firms across ASEAN are embedding technical service teams within engineering departments to secure multi-year supply agreements.
- Engineers:Specification authority over mix designs and durability requirements shapes long-term chemical selection. Materials engineers in China and Vietnam increasingly share authority with sustainability officers on geopolymer tender qualifications.
- Architects:Aesthetic and performance criteria for exposed concrete and interior finishes influence coating and sealant selection. Green building rating tool compliance requirements elevate low-VOC and low-carbon product preference.
- Project Owners:Lifecycle cost and warranty risk transfer considerations drive premium chemical adoption on design-build and public-private partnership structures. State-owned contractors in China mandate Environmental Product Declaration submission for provincial tender qualification.
Contractors represent the dominant procurement volume, with engineers gaining specification influence fastest through sustainability-integrated design protocols.
Technology:
Supply concentration for alkali-activated feedstocks clusters around specific fly ash and slag processing regions, exposing formulators to rail freight bottlenecks and regional monopoly pricing.
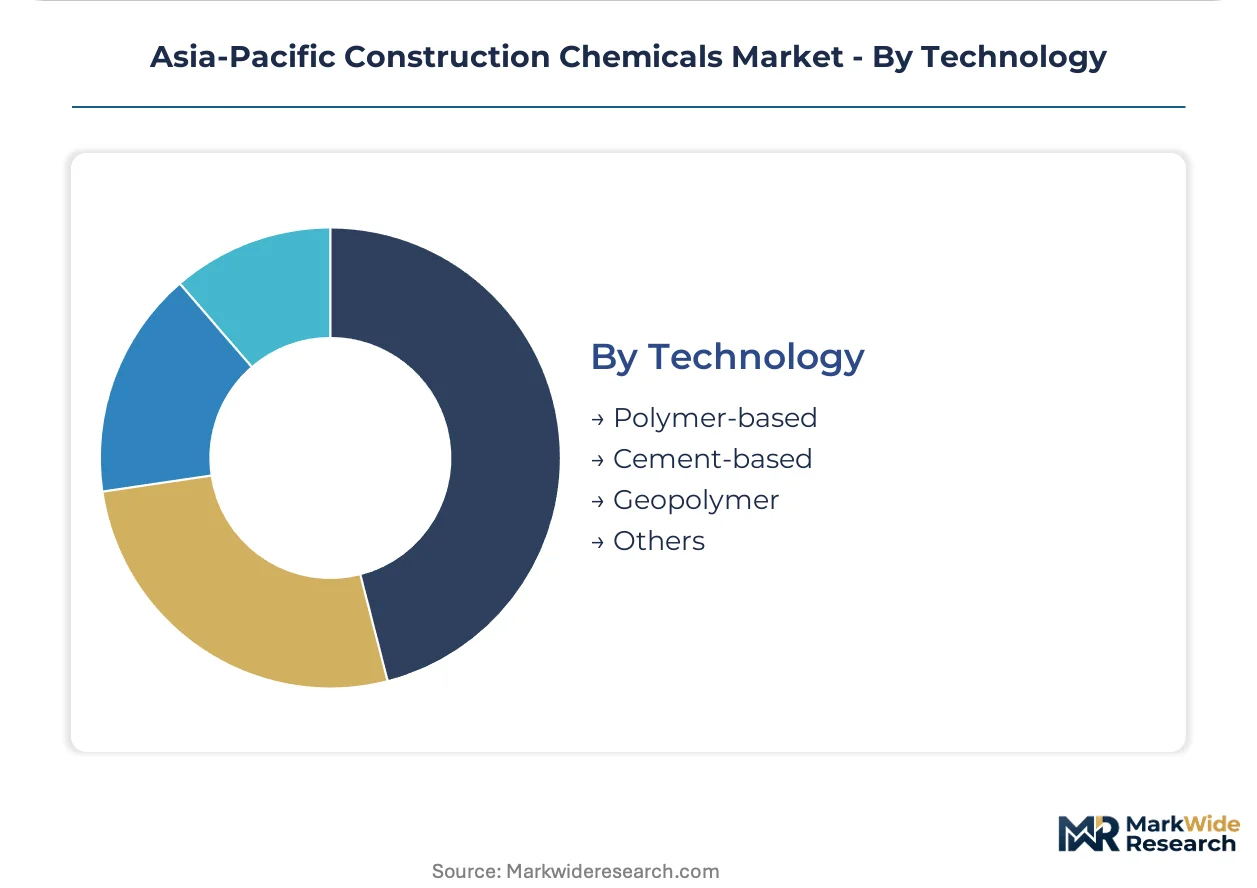
- Polymer-based:Acrylic, epoxy, and polyurethane chemistries deliver superior adhesion, flexibility, and chemical resistance. Tropical humidity cycling across Southeast Asia accelerates R&D allocation toward moisture-curing and hybrid polymer systems.
- Cement-based:Ordinary Portland cement binders blended with polymers retain cost leadership across price-sensitive applications. India's BIS certification mandates for concrete admixtures elevate quality baselines while constraining uncertified import supply elasticity.
- Geopolymer:Alkali-activated alumina-silicate binders eliminate Portland cement content and slash embodied carbon. China's MEE enforcement protocols mandate disclosure requirements that compress commercialization timelines for geopolymer suppliers.
- Others:Emerging bio-based and nano-engineered formulations occupy early-stage commercialization. Research partnerships between Japanese universities and construction chemical manufacturers target self-healing concrete technologies.
Cement-based systems hold volume leadership, with geopolymer technology gaining share fastest under escalating carbon intensity regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and application engineers concentrate heavily across East Asian manufacturing corridors and Indian industrial belts, anchoring technical service capabilities for high-performance admixture development.
China
Provincial infrastructure tenders above designated scale thresholds now mandate supplementary cementitious materials under MEE carbon intensity protocols, guaranteeing offtake for low-carbon admixture suppliers. The Yangtze River Delta manufacturing cluster houses the densest concentration of geopolymer R&D facilities, with Shanghai-based technical centers driving rapid commercialization timelines.
India
The urban corridor stretching from Mumbai to Delhi concentrates demand for self-compacting concrete technologies as Smart Cities Mission densification accelerates. BIS certification mandates for concrete admixtures create compliance barriers that elevate quality baselines across public infrastructure tenders. Maharashtra and Gujarat industrial zones host the primary formulation plants serving western Indian construction markets.
Vietnam
The North-South Expressway and Long Thanh International Airport anchor regional demand for sulfate-resistant and corrosion-inhibiting formulations. State-owned contractors increasingly specify geopolymer-enabled binders for marine infrastructure exposed to aggressive sulfate environments. Ho Chi Minh City technical service teams from multinational suppliers are embedding directly within EPC engineering departments.
Japan
METI building resilience codes accelerate specification of high-ductility polymer modifiers for seismic retrofitting across Tokyo and Osaka metropolitan zones. Aging commercial stock requires extensive structural reinforcement, concentrating demand for specialized bonding agents and repair mortars. Kanto region technical centers lead development of moisture-curing systems adapted to humid coastal conditions.
Australia
TGA-aligned state building codes impose strict volatile organic compound limits on interior-grade sealants and coatings, concentrating specification toward low-VOC hybrid polymers. Sydney and Melbourne commercial developments drive premium product adoption as green building rating tool compliance tightens. New South Wales infrastructure procurement increasingly requires Environmental Product Declaration submission for tender qualification.
Asia-Pacific Construction Chemicals Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers, creating a bifurcated structure where scale-driven portfolio breadth confronts application-specific technical depth. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with localized manufacturing complexes, regional specialists with deep distribution networks, and domestic champions leveraging regulatory compliance barriers. Competitive intensity manifests through technical service team embedding within contractor engineering departments and multi-year supply agreements with performance guarantees.
Within the multinational tier, Sika AG and BASF SE exemplify divergent strategic positioning—one through waterproofing specialization, the other through supply security anchored in localized production. MAPEI S.p.A. represents the regional specialist archetype with distribution depth across ASEAN markets. Among Asia-Pacific domestic players, Pidilite Industries Limited and Beijing Oriental Yuhong Waterproof Technology Co., Ltd. occupy positions shaped by proximity to high-growth national infrastructure pipelines and regulatory familiarity advantages.
| Leading Market Players |
|---|
| Saint-Gobain |
| MAPEI S.p.A. |
| Sika AG |
| Pidilite Industries Limited |
| Fosroc Inc. |
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| RPM International Inc. |
| Jiangsu Subote New Materials Co., Ltd. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers across China and Vietnam anchor supply security for geopolymer feedstocks, compressing pricing power for independent formulators while elevating procurement discipline among tier-one contractors. State ownership of fly ash processing infrastructure creates asymmetric cost positions that reshape competitive bidding dynamics across provincial infrastructure tenders.
Pricing Analysis
Bundled technical service contracts dominate premium admixture segments, while unbundled commodity sales persist across residential waterproofing and tile adhesive categories. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified infrastructure grades from uncertified imports and local blending operations. Cost compression in epoxy hardener inputs is intensifying because Northeast Asian petrochemical supply volatility translates directly into margin pressure. Residential contractors exhibit highest price sensitivity, whereas state-owned infrastructure developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Alkali-activated binder supply rests on concentrated fly ash and slag processing corridors across China's Henan and Shandong provinces, with secondary clusters in India's Maharashtra and Gujarat industrial belts. Key inputs include processed fly ash, ground granulated blast-furnace slag, and specialty alkali activators. Single-source vulnerability concentrates around dominant waste processors controlling rail freight access to formulation plants. Distribution runs through embedded technical service teams within tier-one EPC contractor engineering departments, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with infrastructure durability mandates across China, India, and Vietnam generating predictable replacement demand for high-performance formulations.
For Market Incumbents: To counter margin erosion from epoxy resin import dependency, secure captive supply arrangements with Northeast Asian petrochemical producers and expand in-house production of alkali activators at existing China manufacturing complexes. Prioritize BIS certification investment to lock out uncertified competitors from India's Smart Cities Mission procurement pipelines. For New Entrants and Emerging Players: Digital procurement platforms offer the most penetrable route, with tier-one ASEAN contractors consolidating chemical purchasing through integrated supply chain systems that favor certified suppliers with real-time batch documentation. Target Vietnam's North-South Expressway and Long Thanh International Airport specifications by establishing technical service presence ahead of geopolymer tender lock-in. For Investors and Strategic Acquirers: Specialty chemical conglomerates with construction adjacencies are the most active acquirer in this space, seeking geopolymer formulation capabilities to complement existing admixture portfolios. Acquisition target archetype: mid-cap regional specialists with deep ASEAN distribution and BIS-certified India manufacturing. Watch MEE enforcement intensity on embodied carbon disclosure as inflection indicator for geopolymer adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali Activator Production | Captive supply of sodium silicate reduces exposure to regional monopoly pricing from dominant waste processors. |
| Green Manufacturing Transition | Low-carbon geopolymer formulations qualify for preferential tender scoring under Indonesia's Nusantara green building mandates. |
| Long-term Supply Agreement | Multi-year performance-guaranteed contracts with tier-one EPC firms embed technical service teams within contractor engineering departments. |
| Joint Venture | Partnerships with Chinese state-owned fly ash processors secure priority feedstock allocation under MEE carbon intensity protocols. |
| Capacity Expansion | Localized manufacturing in Maharashtra and Gujarat industrial zones addresses BIS certification barriers and reduces logistics costs to Delhi-Mumbai corridor projects. |
Study Parameters
Coverage spans China, India, Vietnam, Japan, and Australia, with primary inputs from each market combining structured interviews with plant managers at formulation facilities, procurement leads at tier-one EPC contractors, technical R&D directors at multinational suppliers, and distribution channel partners across ASEAN markets. Secondary validation draws from customs and trade data, BIS certification registries, MEE provincial tender disclosures, and SEC filings of listed construction chemical manufacturers. Bottom-up volume modeling triangulates against top-down market sizing across product categories.
Granularity-level modeling captures admixture, sealant, adhesive, and coating product types; residential, commercial, infrastructure, and industrial applications; polymer-based, cement-based, and geopolymer technology segments; and contractor, engineer, architect, and project owner end-user categories. CAGRs derive from segment-level volume trajectories adjusted for price evolution across the projection horizon. Key inputs include MEE carbon intensity threshold enforcement schedules, BIS certification timeline assumptions, and infrastructure project pipeline data from Vietnam and Indonesia.
The model assumes a particular technology adoption path; alternative pathways for geopolymer commercialization would alter the outlook if contractor familiarity gaps persist or alkali-activated binder field performance inconsistencies trigger warranty dispute waves. Forecasts reflect assumptions on regulatory enforcement intensity, feedstock supply concentration stability, and procurement platform consolidation velocity. A small set of triggers—MEE disclosure mandate expansion, BIS certification harmonization delays, and major geopolymer field failure incidents—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Triethylenediamine Market
Chemicals
Amyl Nitrite Market
Chemicals
Global Pine Chemicals Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Malonic Acid Market
Chemicals
Ferric Fluoride Market
Chemicals
Hydrazine Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Egypt Acidulants Market
Chemicals
Flooring Chemicals Market
Chemicals
Hexamine Market
Chemicals
Hydrazine Hydrate Market