
 North America Tartaric Acid Market | 2026-2036
North America Tartaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tartaric Acid Market Intelligence
Modular blending of tartaric acid derivatives is consolidating buyer choice across North American food and beverage formulators. Wego Chemical Group leverages its coastal distribution network to anchor supply reliability for East Coast pharmaceutical clients. THE CHEMICAL COMPANY competes through specialized grades targeting wine acidity correction, while ATP Group sustains backward integration into grape-sourced raw material streams.
Tartaric acid is a crystalline dicarboxylic acid (C₄H₆O₆) extracted primarily from grape pomace or synthesized from maleic anhydride, functioning as an acidity regulator, chelating agent, and stabilizer across food, pharmaceutical, and cosmetic systems. Natural tartaric acid dominates value contribution due to clean-label premiums and winemaker preference for organic-certified inputs, while synthetic variants occupy cost-sensitive industrial applications where pharmaceutical-grade purity requirements are less stringent. Food and beverages represents the most mature application segment, whereas cosmetics manufacturers are emerging as the fastest-growing end-user cohort driven by antioxidant formulation trends.
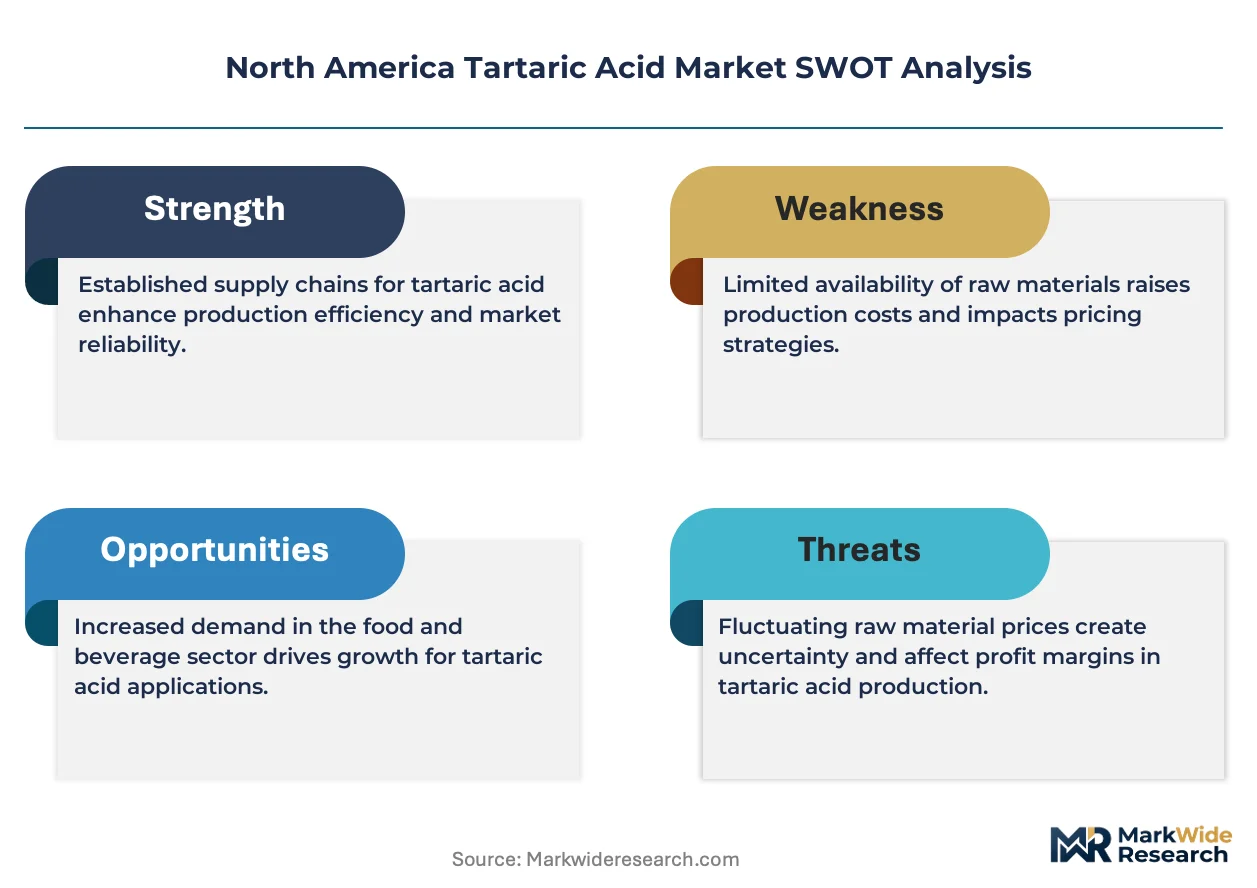
The FDA governs tartaric acid under 21 CFR 184.1099 as a GRAS food additive, while Health Canada and PMRA jointly oversee chemical purity thresholds for cross-border trade. The EPA's evolving framework for chemical processing emissions is forcing tartaric acid producers to retrofit extraction facilities or relocate production to jurisdictions with cleaner energy profiles. Stakeholders must monitor how California's Proposition 65 enforcement patterns and emerging state-level chemical disclosure laws reshape liability exposure for tartaric acid suppliers serving West Coast food manufacturers.
Market Dynamics
California vintners and New York food manufacturers are tightening purity specifications faster than extraction capacity can adapt, compressing margins for suppliers reliant on older grape-sourced processing methods.
Growth Catalysts
- FDA GRAS expansion:The FDA's 21 CFR 184.1099 framework continues validating tartaric acid for novel food applications, opening formulation pathways for plant-based dairy alternatives seeking clean-label acidity regulators.
- Wine pH stabilization demand:California's premium viticulture sector is deepening tartaric acid procurement volumes as heat-stressed harvests require more aggressive acidulation to maintain balance.
- Cosmetic antioxidant surge:Skincare formulators across the United States are integrating tartaric acid derivatives into vitamin C stabilization systems, creating incremental demand beyond traditional food channels.
Market Restraints
- Grape pomace supply volatility:Climate-driven harvest compression in California's Central Valley is constraining natural tartaric acid feedstock availability, forcing price volatility onto extraction-dependent producers.
- Synthetic purity ceiling:Maleic anhydride-derived tartaric acid cannot achieve pharmaceutical-grade specifications required by USP-NF monographs, locking synthetic producers out of high-margin pharmaceutical compounding segments.
- EPA emission retrofit costs:The EPA's evolving chemical processing emission standards are forcing tartaric acid facilities to absorb six-figure scrubber installations or face production curtailment.
Strategic Opportunities
- Canadian cross-border expansion:Health Canada's aligned food additive standards with the FDA create low-friction export pathways for US tartaric acid producers seeking to serve Toronto and Montreal food manufacturing clusters.
- Biotechnology extraction convergence:Enzymatic bioprocessing methods paired with membrane filtration are enabling higher-yield natural extraction from alternative feedstocks including sugar beet waste.
- State-level chemical disclosure tailwinds:California Proposition 65 enforcement patterns are accelerating demand for certified-organic tartaric acid grades that preempt liability exposure for West Coast food brands.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP-NF compliance validation requires 18-24 month stability testing protocols that delay market entry for new tartaric acid purification investments.
- Legacy equipment integration friction:Continuous processing upgrades for tartaric acid crystallization are proving incompatible with batch-oriented quality control systems still prevalent in mid-scale extraction facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tartaric Acid Market |
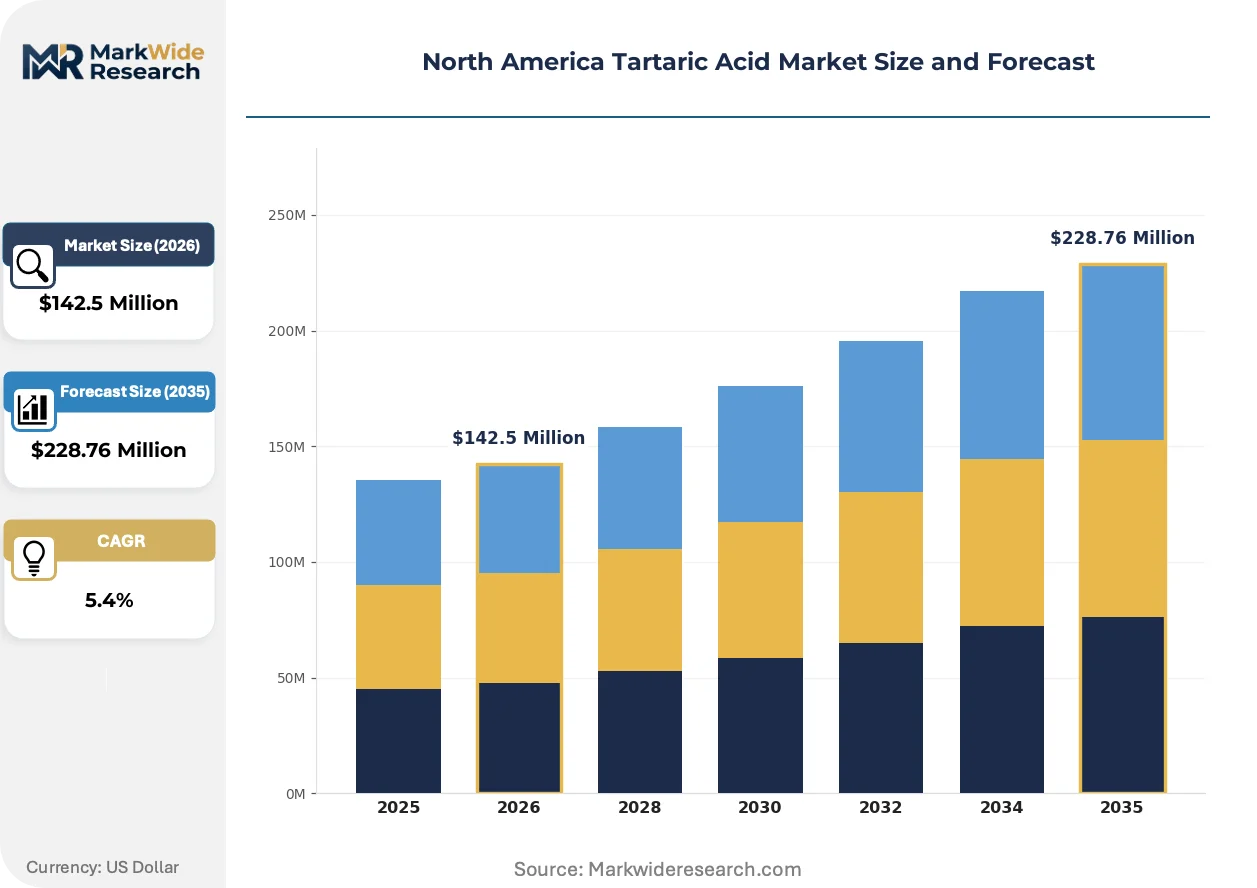
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Tartaric Acid, Synthetic Tartaric Acid, Cream of Tartar, Stabilized Tartaric Acid Application: Food & Beverages, Pharmaceuticals, Cosmetics, Winemaking End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Cosmetics Manufacturers Sales Channel: Online Retailers, Distributors, Specialty Stores, Supermarkets |
| Companies Covered | Wego Chemical Group, THE CHEMICAL COMPANY, ATP Group, Tarac Technologies, Caviro Group, Hawkins Inc, Rochem International, Alvinesa, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tartaric Acid Market Strategic Shifts & Innovations
Membrane filtration and enzymatic processing are displacing conventional solvent-based extraction, while regulatory pressure on residual chemical footprints accelerates capital rotation toward closed-loop production architectures.
Chromatographic purification technology is consolidating quality differentiation in pharmaceutical-grade tartaric acid production. US and Canadian pharmaceutical compounders are adopting this technology at accelerating pace to meet USP-NF monograph specifications. The structural consequence is compressing the supplier base toward integrated producers capable of in-house high-purity finishing, marginalizing toll processors without captive chromatography capacity.
The EPA's evolving framework for chemical processing emissions is tightening operational constraints on tartaric acid extraction facilities. Industrial consequence manifests as forced capital deployment into scrubber systems and process water recycling infrastructure. California-based producers face the most acute compliance pressure, with several facilities evaluating relocation to jurisdictions with cleaner grid profiles to preempt emission threshold violations.
Buyer concentration among multinational food manufacturers is compressing procurement cycles and demanding vendor-managed inventory arrangements. Direct supplier-to-manufacturer contracts are displacing traditional distributor intermediaries in high-volume tartaric acid procurement. This pattern is most visible in the Midwest and Northeast, where CPG giants are consolidating acidulant sourcing through single-source qualification programs.
North America Tartaric Acid Market Segmentation
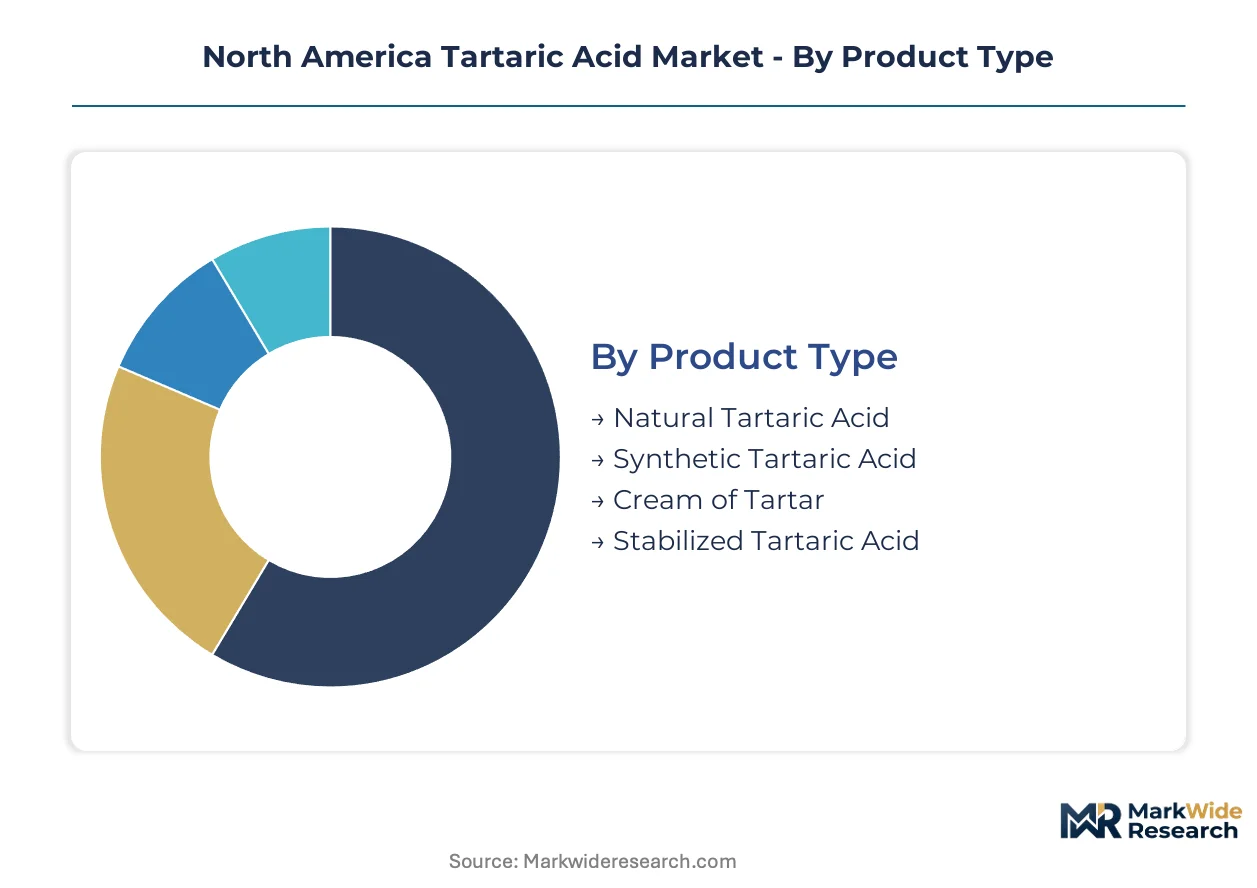
Segmentation in the North America tartaric acid market reveals how capital deployment and regulatory compliance create divergent profit pools across product grades and application channels. Understanding these fault lines enables suppliers to align purification investments with buyer willingness to pay for certified quality tiers.
Product Type:
Capital intensity varies sharply across extraction and synthesis pathways, with natural processing requiring substantially higher upfront filtration infrastructure than maleic anhydride routes.
- Natural Tartaric Acid:Extracted from grape pomace through multi-stage crystallization and membrane filtration, this grade commands premium positioning in California winemaking and organic-certified food systems where FDA GRAS status intersects with clean-label procurement mandates. Heat-stressed harvests in the Central Valley are compressing feedstock availability, forcing extraction facilities to absorb volatile pomace pricing or invest in alternative biomass preprocessing.
- Synthetic Tartaric Acid:Manufactured from maleic anhydride via catalytic oxidation, this segment serves cost-sensitive industrial applications where pharmaceutical-grade USP-NF specifications are not required. EPA emission standards targeting chemical processing facilities are elevating scrubber capital requirements for synthetic producers, eroding the traditional cost advantage over natural extraction.
- Cream of Tartar:A partially neutralized potassium salt of tartaric acid used primarily in baking powder formulations and household culinary applications.
- Stabilized Tartaric Acid:Chemically modified derivatives engineered for extended shelf stability in processed food systems and cosmetic antioxidant formulations.
Natural tartaric acid absorbs the bulk of installed capacity; stabilized derivatives are expanding most quickly.
Application:
Application segmentation tracks how pH regulation requirements diverge across end-use systems with distinct purity thresholds and certification protocols.
- Food & Beverages:The most mature application channel, spanning acidulant deployment in processed foods, soft drinks, and confectionery systems where FDA 21 CFR 184.1099 compliance is baseline. Midwest and Northeast CPG manufacturers are consolidating procurement through single-source qualification programs, compressing supplier margins while demanding vendor-managed inventory arrangements.
- Winemaking:California's premium viticulture sector drives concentrated demand for tartaric acid in acidulation protocols addressing heat-stressed harvest chemistry. New York Finger Lakes vintners are deepening procurement volumes as regional warming patterns disrupt traditional grape acidity profiles.
- Pharmaceuticals:USP-NF monograph compliance requires 18-24 month stability validation protocols, creating steep barriers to entry for new purification investments. Chromatographic finishing capability is concentrating supply among integrated producers with captive high-purity infrastructure.
- Cosmetics:Skincare formulators are integrating tartaric acid derivatives into vitamin C stabilization systems, generating incremental demand beyond traditional food channels as antioxidant positioning gains formulation priority.
Food and beverage applications anchor current volume; cosmetics is climbing the fastest as antioxidant formulation trends accelerate.
End User:
End user segmentation reflects how buyer scale and quality certification requirements reshape procurement channel economics and supplier relationship structures.
- Food Manufacturers:Large-scale CPG operations in the Midwest and Northeast are displacing distributor intermediaries through direct supplier contracts and single-source qualification programs that demand extensive documentation of FDA compliance.
- Beverage Producers:Carbonated soft drink and ready-to-drink tea formulators represent high-volume, price-sensitive procurement with standardized acidulant specifications and limited premium tolerance.
- Pharmaceutical Companies:Compounding operations and generic drug manufacturers require USP-NF certified grades with validated stability data, concentrating supply relationships among producers with demonstrated chromatographic purification capability.
- Cosmetics Manufacturers:Mid-scale skincare and personal care formulators are emerging as a growth cohort, prioritizing antioxidant functionality claims and clean-label positioning over commodity pricing.
Food manufacturers command the largest share of procurement volume; cosmetics manufacturers are gaining share fastest.
Sales Channel:
Sales channel segmentation tracks how buyer concentration and order scale reshape distribution economics across digital and physical pathways.
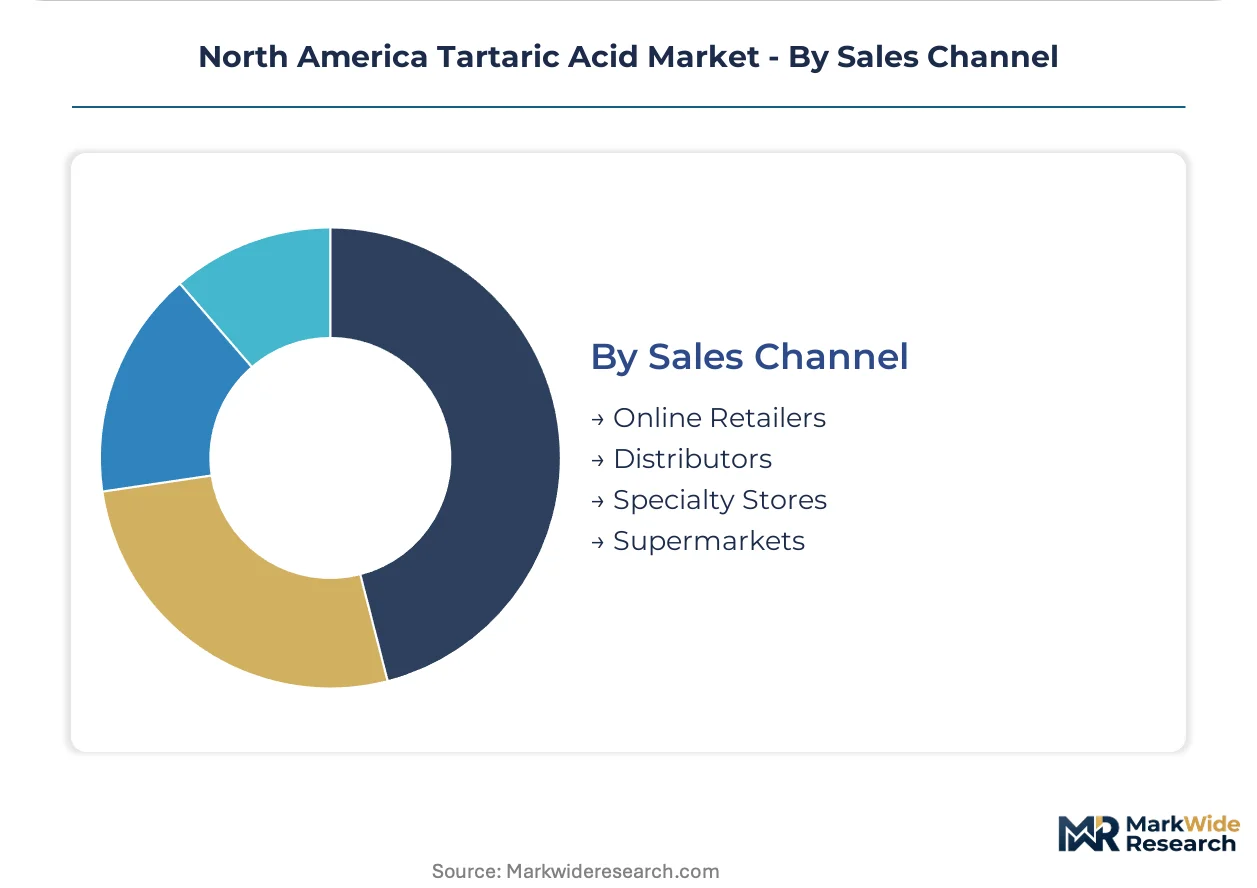
- Distributors:Traditional chemical distributors maintain relevance in mid-scale procurement where technical service and just-in-time delivery offset modest price premiums, particularly for East Coast pharmaceutical clients served by coastal logistics networks.
- Online Retailers:E-commerce platforms are capturing household and small-scale commercial demand for cream of tartar and food-grade tartaric acid, though bulk industrial procurement remains channel-resistant.
- Specialty Stores:Restaurant supply and professional culinary retailers serve artisan food producers and premium winemaking operations requiring technical consultation alongside product delivery.
- Supermarkets:Mass retail channels handle consumer-packaged cream of tartar and baking applications with minimal technical content, competing primarily on price positioning and shelf placement.
Distributors retain the largest installed channel capacity; online retailers are expanding most quickly as small-scale procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American tartaric acid production concentrates in California and New York extraction facilities, while consumption spreads across Midwest food manufacturing and Atlantic Coast pharmaceutical compounding. Canada imports substantial volumes to serve Toronto and Montreal food processing clusters.
United States
California vintners and New York food manufacturers drive concentrated demand for natural tartaric acid in wine acidulation and processed food systems. The FDA's 21 CFR 184.1099 GRAS framework governs food additive deployment, while the EPA enforces emission standards on extraction facilities. The Central Valley hosts grape pomace processing infrastructure where heat-stressed harvests are compressing feedstock availability and elevating raw material costs.
Canada
Toronto and Montreal food manufacturing clusters anchor Canadian tartaric acid procurement for bakery and confectionery applications. Health Canada and the PMRA jointly oversee chemical purity thresholds for cross-border trade alignment with US standards. Ontario-based distributors serve as logistical intermediaries for US producers seeking low-friction export pathways into Canadian CPG supply chains.
Mexico
Baja California and Querétaro beverage producers represent emerging tartaric acid demand as carbonated soft drink formulation expands. Mexico's national food safety regulator, COFEPRIS, maintains additive standards that facilitate North American supply chain integration. Guadalajara's growing food processing sector is deepening acidulant procurement volumes for regional snack and sauce manufacturing.
North America Tartaric Acid Market Key Industry Players
The competitive structure tilts toward integrated extraction specialists with captive grape pomace supply chains. Mid-scale distributors and toll processors occupy secondary positions, while synthetic producers compete on cost for industrial-grade applications. Three archetypes dominate: backward-integrated natural extractors, coastal logistics-anchored distributors, and pharmaceutical-grade purification specialists. Capacity consolidation and certification-driven supplier qualification are the dominant competitive moves reshaping procurement relationships.
Among North American distributors, Wego Chemical Group occupies a position exemplifying coastal logistics networks serving East Coast pharmaceutical clients. THE CHEMICAL COMPANY and ATP Group represent contrasting archetypes—the former specializing in wine-industry acidity correction grades, the latter sustaining upstream control over grape-sourced raw material streams through integrated extraction infrastructure.
| Leading Market Players |
|---|
| Wego Chemical Group |
| THE CHEMICAL COMPANY |
| ATP Group |
| Tarac Technologies |
| Caviro Group |
| Hawkins Inc |
| Rochem International |
| Alvinesa |
| Merck |
| Others |
Cost & Logistics Intelligence
Enzymatic bioprocessing paired with membrane filtration is compressing cost differentials between natural and synthetic tartaric acid grades while concentrating production among facilities capable of high-yield extraction from alternative feedstocks. This technological shift simultaneously elevates capital barriers for new entrants and reshapes procurement power toward buyers with volume scale to justify dedicated supply arrangements.
Pricing Analysis
Margin tightening in pharmaceutical-grade segments reflects USP-NF certification timelines stretching 18-24 months and chromatographic purification infrastructure costs. Three-tier pricing structure across premium, standard, and economy levels separates USP-NF certified natural grades from food-grade natural and maleic anhydride-derived synthetic variants. Cost-down pressure on synthetic grades accelerates because EPA scrubber retrofit requirements erode traditional cost advantages. Beverage producers exhibit highest price sensitivity; pharmaceutical compounders accept premium positioning for validated stability data.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume procurement from Midwest and Northeast CPG giants, displacing traditional distributor intermediaries. Supply concentrates in California extraction facilities processing Central Valley grape pomace, with secondary production in New York and Ontario. Raw material flows draw from grape pomace, sugar beet waste preprocessing, and maleic anhydride catalytic oxidation. Single-source vulnerability in California feedstock supply creates structural exposure to climate-driven harvest compression. Distribution runs through coastal logistics networks for East Coast pharmaceutical clients and direct rail links for Midwest food manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American tartaric acid supply operates under pronounced feedstock constraints, with Central Valley grape pomace availability compressing faster than alternative biomass preprocessing capacity can expand. This bottleneck sustains pricing power for integrated extractors while forcing cost absorption onto synthetic producers facing emission compliance investments.
For Market Incumbents: Hedge against grape pomace volatility by securing alternative biomass supply contracts from sugar beet processing cooperatives in the Upper Midwest. Expand chromatographic finishing capacity to capture pharmaceutical-grade margin premiums before USP-NF validation timelines lengthen further. Defensive consolidation through toll processor acquisition eliminates competitor access to captive extraction infrastructure. For New Entrants and Emerging Players: Launch via enzymatic bioprocessing technology licensing to bypass capital-intensive crystallization infrastructure and target cosmetics manufacturers seeking antioxidant-grade tartaric acid derivatives. White-space concentration exists in certified-organic tartaric acid for California Proposition 65-compliant food brands. Go-to-market leverage rests on clean-label certification rather than commodity price positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational food ingredient conglomerates seeking North American acidulant supply security. Long-term viability favors integrated producers with captive grape pomace streams and demonstrated USP-NF compliance histories over toll-dependent processors. Monitor EPA emission standard enforcement patterns in California as inflection indicator for production relocation decisions and associated asset revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grape Pomace Supply | Captive feedstock secures margin protection against climate-driven harvest volatility in California's Central Valley. |
| Chromatographic Purification Capacity Expansion | USP-NF grade certification opens pharmaceutical compounding relationships with 18-24 month validation barriers. |
| Enzymatic Bioprocessing Technology Licensing | Alternative feedstock utilization from sugar beet waste reduces dependency on grape pomace availability constraints. |
| Cross-Border Canadian Distribution Network | Health Canada alignment with FDA standards creates low-friction export pathway for Toronto and Montreal food clusters. |
| Certified-Organic Grade Production | California Proposition 65 compliance positioning captures liability-averse West Coast food manufacturer procurement. |
Research Approach
Document review covered FDA GRAS filings, EPA emission compliance records, Health Canada food additive standards, and USP-NF monograph specifications, complemented by interviews with extraction facility plant managers, pharmaceutical compounding procurement leads, California vintner technical directors, and Midwest CPG supply chain planners. Secondary validation drew from customs trade data, American Chemistry Council reports, and SEC 10-K disclosures from publicly traded ingredient suppliers. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-referenced primary intelligence.
Volume and value trajectories across the analysis window were generated through multi-dimensional segmentation incorporating grade tier, end-use application, and regional production hub. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and projected capacity expansion timelines. Key forecast inputs included grape pomace yield assumptions under climate stress scenarios and enzymatic processing adoption rates for alternative feedstock utilization.
The model assumes a particular technology adoption path; alternative pathways for membrane filtration and bioprocessing convergence would alter the outlook if capital costs decline faster than projected. Forecasts reflect assumptions about regulatory stability in FDA GRAS frameworks and EPA emission enforcement intensity. Practitioners should monitor Central Valley harvest compression indicators and California Proposition 65 enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Trimethylamine Market
Chemicals
N-Propanol Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Stimulation Materials Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Caustic Soda Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Scouring Agents Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Laboratory Chemicals Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
South America Construction Chemicals Market