
 Benzoyl Alcohol Market | 2026-2036
Benzoyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Benzoyl Alcohol Market Outlook
Specialty chemical distribution networks serving personal care formulators is reconfiguring around regional compliance hubs and just-in-time inventory models. LANXESS leverages its European manufacturing base to sustain pharmaceutical-grade supply continuity for parenteral applications. Merck KGaA anchors high-purity benzoyl alcohol production through stringent quality protocols that differentiate its offerings in regulated markets. INEOS competes on industrial solvent volume, extending its reach through bulk supply agreements with agrochemical manufacturers.
Benzoyl alcohol is an aromatic alcohol with the chemical formula C₇H₈O, typically manufactured through the hydrolysis of benzyl chloride or catalytic hydrogenation of benzaldehyde, and functions primarily as a preservative, solvent, and viscosity-reducing agent across pharmaceutical and cosmetic formulations. The cosmetics product type segment dominates current volume, supported by preservative demand in premium skincare and hair care formulations. The pharmaceuticals application segment leads margin pools due to injectable-grade certification requirements and parenteral drug compatibility testing. The personal care end user category occupies the broadest channel footprint, spanning both direct sales to multinational formulators and distributor networks serving mid-tier regional brands.
EPA regulations governing volatile organic compound emissions from industrial solvent applications constrain formulation choices in United States manufacturing, while REACH registration requirements in Europe mandate comprehensive toxicity documentation for cosmetic and pharmaceutical grades. China's NMPA and GB standards impose parallel purity specifications on imported and domestically produced benzoyl alcohol for drug applications, creating a multi-jurisdictional compliance burden for suppliers. Stakeholders must monitor evolving pharmaceutical monograph revisions and solvent emission thresholds to align certification investments with shifting regional enforcement priorities.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating volume among producers capable of sustaining injectable-grade compliance across multiple regulatory jurisdictions.
Growth Catalysts
- Biologic stabilizer substitution:Parenteral drug manufacturers are replacing benzyl alcohol alternatives in protein formulations, pulling demand toward higher-purity grades.
- REACH registration:European chemical compliance mandates comprehensive toxicity documentation, advantaging incumbent suppliers with established dossiers.
- China API expansion:Domestic pharmaceutical active ingredient production is scaling capacity, creating concentrated regional demand for excipient-grade supply.
Market Restraints
- Toluene feedstock volatility:Aromatic hydrocarbon price swings transmit directly to benzaldehyde hydrogenation economics, squeezing producer margins.
- Substitution by phenoxyethanol:Cosmetic formulators in preservative-sensitive applications are pivoting toward alternative antimicrobial agents.
- EPA VOC thresholds:Stricter industrial solvent emission limits in United States manufacturing constrain high-volume solvent applications.
Strategic Opportunities
- India CDSCO pathway:Underpenetrated pharmaceutical formulation sector offers whitespace for injectable-grade certification investments.
- Continuous flow hydrogenation:Process intensification technology convergence with catalytic reactor design is compressing batch cycle times.
- Direct-to-formulator e-procurement:Digital platform distribution models are disintermediating traditional chemical distributor networks.
Industry Challenges
- Pharmacopeial harmonization timelines:USP, EP, and JP monograph alignment delays create multi-jurisdiction certification bottlenecks.
- Analytical chemist scarcity:Specialized talent for impurity profiling and stability testing functions constrains quality control throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzoyl Alcohol Market |
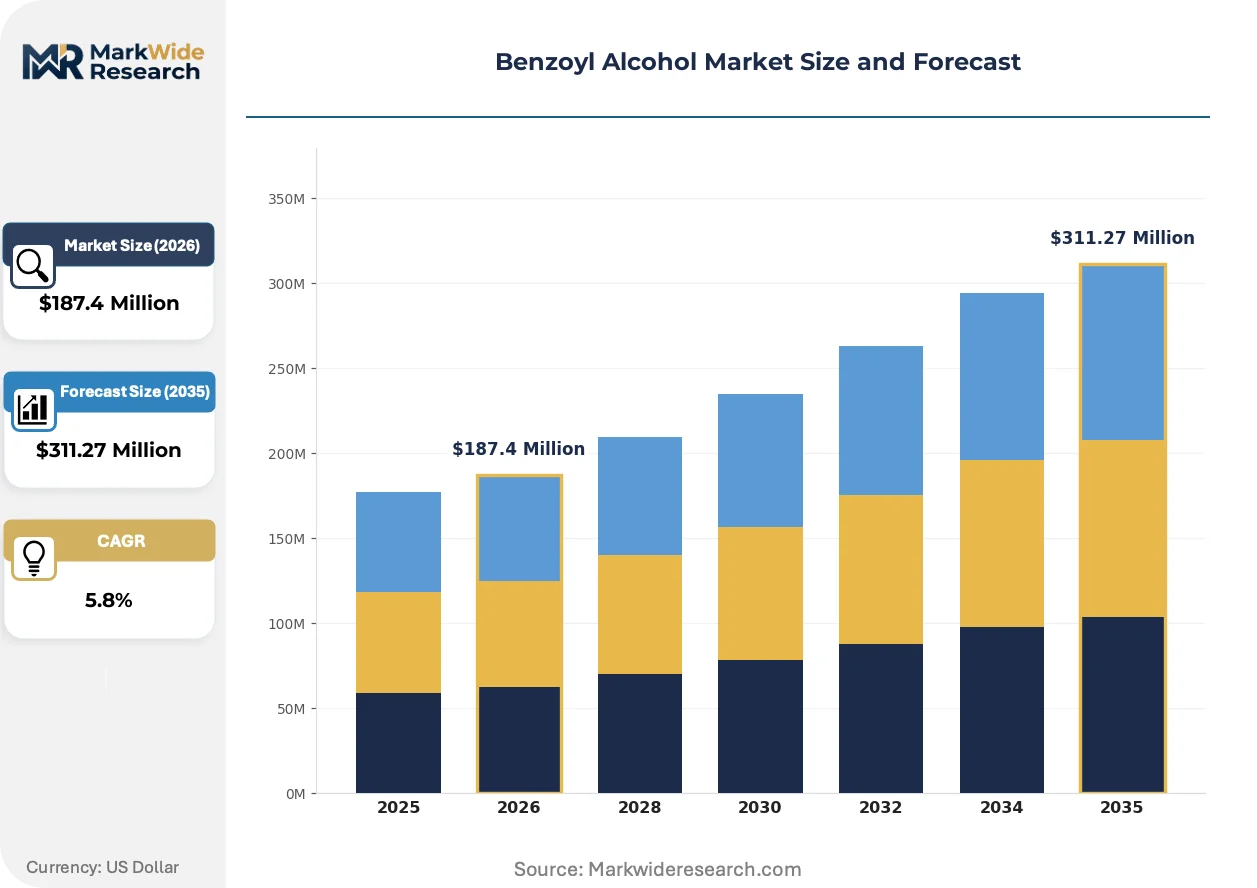
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Agrochemicals, Industrial Solvents Application: Preservatives, Fragrance Ingredients, Solvents, Chemical Intermediates End User: Personal Care, Healthcare, Agriculture, Manufacturing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | LANXESS, Merck KGaA, INEOS, Emerald Performance Materials, Elan Chemical, Gujarat Alkalies and Chemicals Ltd., Greenfield Global Inc., Hubei Greenhome Materials Technology, Valtris Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzoyl Alcohol Market Strategic Shifts
Process analytical technology and regulatory data harmonization are compressing batch release timelines while enabling real-time quality verification across distributed manufacturing networks.
Continuous manufacturing platforms are digitizing quality assurance workflows in benzoyl alcohol production. Pharmaceutical-grade suppliers adopting PAT-enabled reactor systems are reducing batch-to-batch variability. This technology is digitizing documentation trails for regulatory submissions, compressing audit preparation cycles.
REACH authorization procedures are tightening substance-of-very-high-concern scrutiny on residual benzaldehyde impurities. European formulators face reformulation pressures as candidate list expansions trigger downstream notification obligations. Cosmetic and pharmaceutical grades destined for EU markets are responding with enhanced purification investments.
Formulator procurement teams are consolidating vendor panels around dual-source pharmaceutical-grade suppliers capable of spanning multiple pharmacopeias. Regional mid-tier personal care brands are being displaced from preferred supplier lists as multinational buyers compress their approved vendor bases. This concentration is most visible in North American and Western European direct sales channels.
Benzoyl Alcohol Market Segmentation
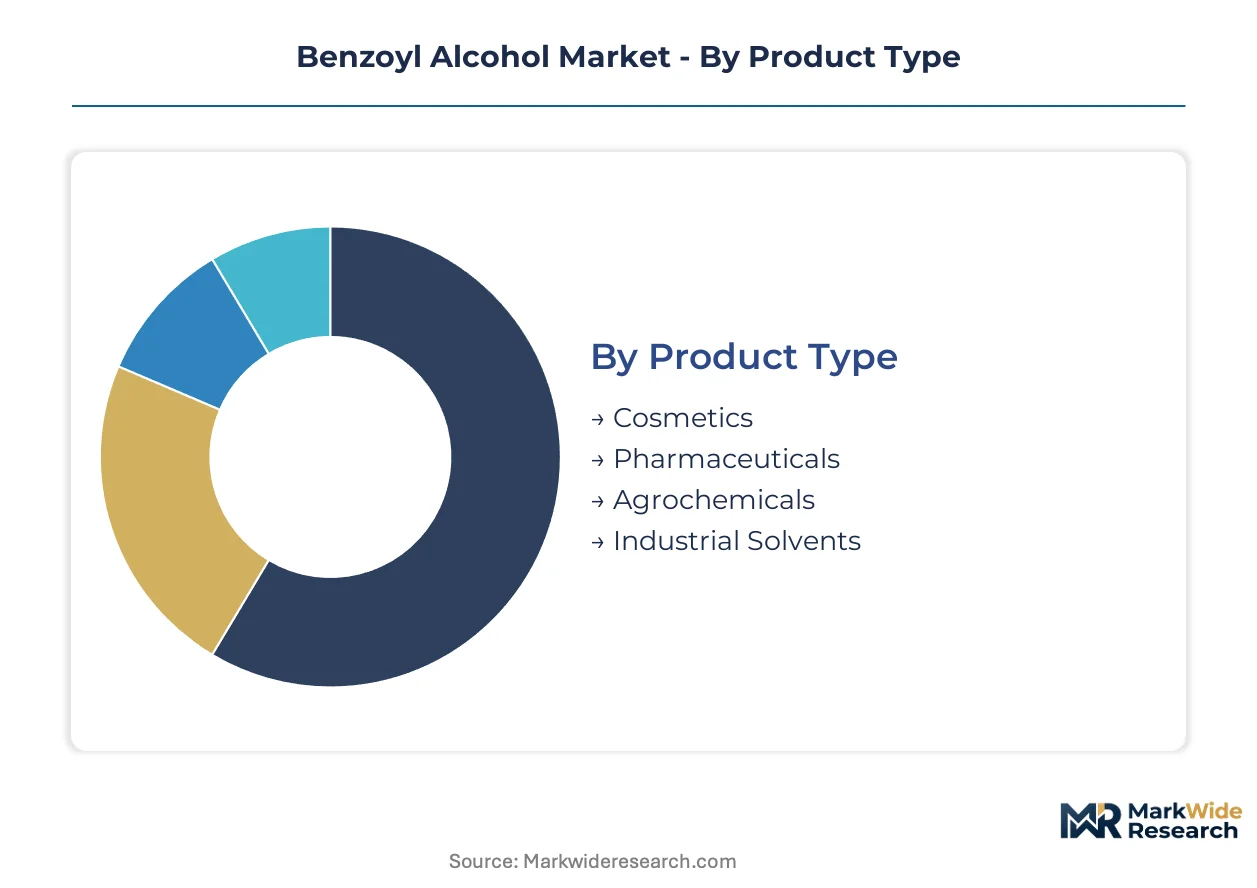
Benzoyl alcohol purity grades stratify sharply across end-use requirements, with pharmaceutical certification commanding premium positioning while industrial volumes compete on feedstock efficiency. Segment boundaries are hardening as multi-jurisdictional compliance burdens force specialization.
Product Type:
Cosmetics and pharmaceutical grades anchor mature demand pools with established certification protocols, while agrochemical and industrial applications are emerging segments with evolving purity specifications.
- Cosmetics:Technical specifications center on low-odor, colorless grades meeting international cosmetic safety standards for preservative applications in skincare and hair care formulations. Demand concentrates in premium personal care manufacturing clusters across China and Western Europe, driven by preservative system reformulations responding to ECHA candidate list expansions.
- Pharmaceuticals:Injectable-grade material requires USP, EP, and JP pharmacopeial compliance with stringent residual benzaldehyde limits below 0.05% and comprehensive endotoxin testing. Parenteral drug manufacturers in the United States and Germany are pulling volume toward higher-purity grades as biologic stabilizer substitution accelerates.
- Agrochemicals:Technical-grade supply serves pesticide formulation and crop protection manufacturing with moderate purity requirements.
- Industrial Solvents:Volume applications in coatings and adhesives face EPA VOC emission constraints in United States manufacturing.
Cosmetics handles the majority of throughput; pharmaceuticals is the fastest mover on share.
Application:
Cost tier differentiation separates commodity solvent applications from premium preservative and fragrance ingredient markets.
- Preservatives:Antimicrobial functionality at 0.5-1.0% concentration levels in aqueous cosmetic and pharmaceutical formulations requires USP-grade certification for injectable compatibility. Demand clusters with multinational personal care formulators consolidating vendor panels around dual-source pharmaceutical-grade suppliers capable of spanning multiple pharmacopeias.
- Fragrance Ingredients:High-purity benzoyl alcohol functions as a fixative and solvent in fine fragrance compounding, with odor profile specifications stricter than industrial grades. European fragrance houses in France and Switzerland are concentrating procurement around REACH-registered suppliers with established toxicity dossiers.
- Solvents:Industrial dissolution applications in coatings and inks face substitution pressure from lower-VOC alternatives.
- Chemical Intermediates:Benzyl ester synthesis and derivative manufacturing feed pharmaceutical and agrochemical value chains.
Preservatives commands the largest volume position; fragrance ingredients is expanding most quickly on premium positioning.
End User:
Customer type fragmentation creates distinct procurement patterns across regulated healthcare and price-sensitive manufacturing segments.
- Personal Care:Multinational formulators and mid-tier regional brands drive preservative demand across skincare, hair care, and color cosmetic applications with diverging certification requirements. Direct sales channels to large manufacturers are consolidating while distributor networks serve fragmented regional brands.
- Healthcare:Hospital pharmacies, compounding facilities, and parenteral drug manufacturers require injectable-grade supply with batch-specific CoA documentation and stability testing. CDSCO registration requirements in India are creating new compliance entry barriers for suppliers targeting this underpenetrated formulation sector.
- Agriculture:Crop protection manufacturers utilize technical-grade material in pesticide emulsion systems.
- Manufacturing:Industrial coatings, adhesives, and specialty chemical production consume solvent-grade volumes.
Personal care absorbs the dominant share of volume; healthcare is climbing the fastest on margin expansion.
Distribution Channel:
Geography of demand shapes channel configuration, with regional compliance hubs driving consolidation around specialized distributors.
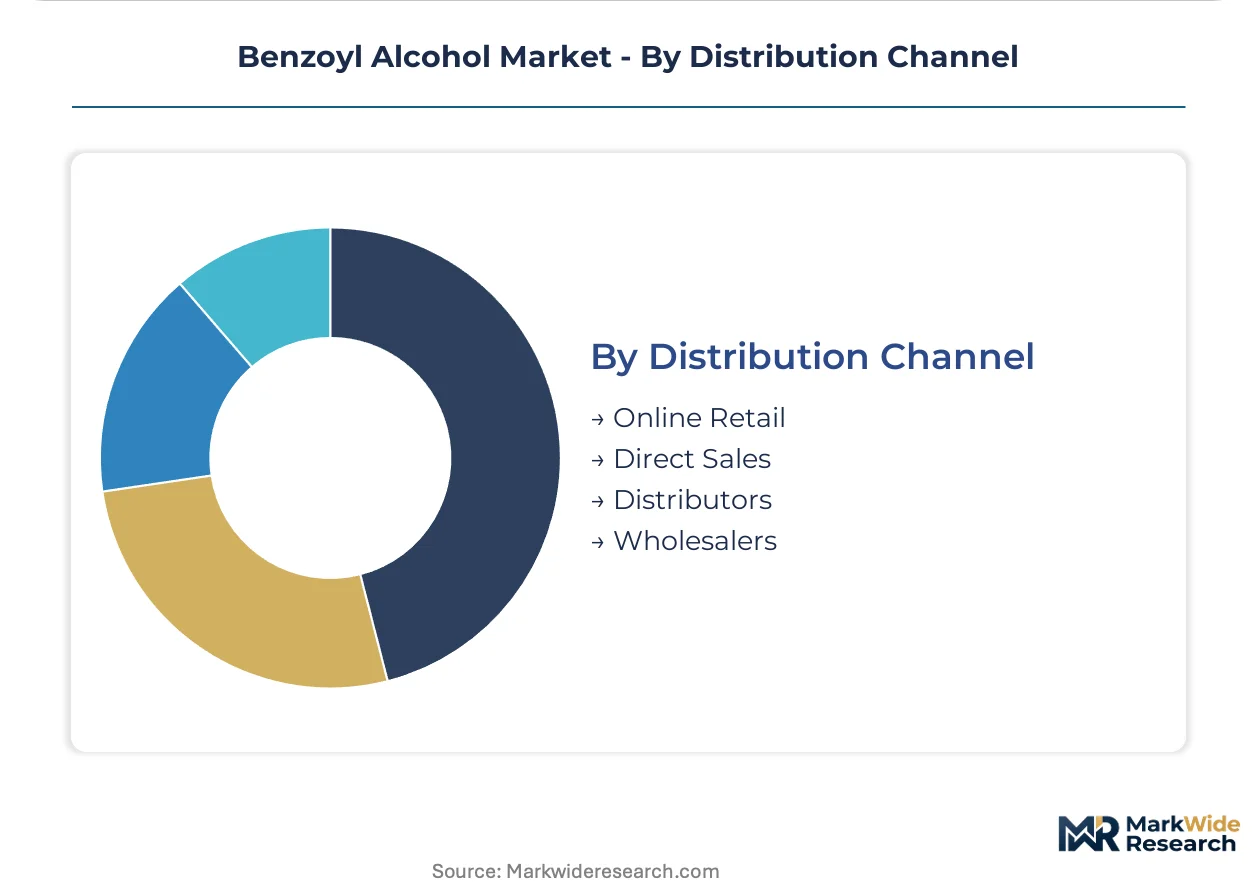
- Direct Sales:Pharmaceutical-grade supply to multinational formulators and parenteral drug manufacturers operates through long-term supply agreements with audit rights and dedicated inventory buffers. LANXESS and Merck KGaA anchor this channel through European manufacturing bases sustaining pharmaceutical-grade continuity.
- Distributors:Regional chemical distributors serving mid-tier personal care and agrochemical manufacturers are reconfiguring around just-in-time inventory models and compliance documentation support. Specialty chemical distribution networks in Germany and the Netherlands are consolidating as REACH authorization procedures tighten.
- Online Retail:Small-volume cosmetic ingredient procurement by independent formulators and regional brands is migrating to digital platforms.
- Wholesalers:Bulk industrial solvent volumes flow through traditional chemical wholesale networks with limited value-added services.
Direct sales manages the highest-value throughput; online retail is gaining share fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's purity specifications for pharmaceutical excipients are concentrating benzoyl alcohol procurement around certified Chinese manufacturers. Domestic API production expansion and personal care manufacturing scaling are reshaping regional supply patterns across multiple jurisdictions.
China
Pharmaceutical-grade demand concentrates in Jiangsu and Zhejiang provinces where domestic API manufacturers are scaling parenteral drug production. NMPA's GB standards impose parallel purity specifications on imported and domestically produced material, creating compliance convergence. Shanghai and Suzhou manufacturing clusters are absorbing expanded excipient-grade capacity as biologic stabilizer substitution accelerates.
United States
Injectable-grade certification requirements are compressing supplier margins while concentrating volume among multi-pharmacopeia compliant producers. EPA solvent emission rules constrain industrial applications in coatings and adhesives manufacturing. New Jersey and Pennsylvania chemical manufacturing corridors sustain pharmaceutical-grade supply continuity for parenteral drug formulators.
Germany
REACH registration mandates comprehensive toxicity documentation for cosmetic and pharmaceutical grades. Lanxess anchors European pharmaceutical-grade production from its manufacturing base, sustaining supply continuity for parenteral applications. The Rhine-Ruhr industrial cluster maintains specialty chemical distribution networks serving personal care formulators with just-in-time inventory models.
India
CDSCO registration requirements are creating new compliance entry barriers for injectable-grade suppliers targeting the underpenetrated pharmaceutical formulation sector. Gujarat Alkalies and Chemicals Ltd. represents domestic capacity expansion in technical-grade production. Maharashtra and Gujarat pharmaceutical manufacturing zones are pulling demand toward certified excipient supply as domestic drug formulation scales.
Switzerland
Fine fragrance compounding drives high-purity demand for fixative applications with odor profile specifications stricter than industrial grades. Swissmedic's pharmaceutical regulations align with EU REACH frameworks, creating regulatory coherence for cross-border supply. Basel's fragrance and specialty chemical cluster concentrates procurement around REACH-registered suppliers with established toxicity dossiers.
Benzoyl Alcohol Market Competitive Environment
Pharmaceutical-grade specialists and industrial solvent volume producers split the market along purity-grade lines. Supplier consolidation is accelerating as multi-jurisdictional compliance burdens force specialization around certified production. Three archetypes dominate: European pharmaceutical-grade incumbents with established pharmacopeia dossiers, Asian technical-grade volume producers serving agrochemical and industrial applications, and specialty chemical distributors reconfiguring around regional compliance hubs. Capacity expansion and strategic partnerships represent the dominant competitive moves as players defend positioning across diverging margin pools.
Among European pharmaceutical-grade incumbents, LANXESS and Merck KGaA occupy positions exemplifying regulatory compliance anchoring. LANXESS leverages its manufacturing base to sustain supply continuity for parenteral applications. Merck KGaA represents high-purity production through stringent quality protocols. INEOS sits within the industrial solvent volume tier, competing through bulk supply agreements. These three companies illustrate the strategic divergence between premium-grade certification investments and commodity-scale efficiency.
| Leading Market Players |
|---|
| LANXESS |
| Merck KGaA |
| INEOS |
| Emerald Performance Materials |
| Elan Chemical |
| Gujarat Alkalies and Chemicals Ltd. |
| Greenfield Global Inc. |
| Hubei Greenhome Materials Technology |
| Valtris Specialty Chemicals |
| Others |
Value Chain & Pricing Dynamics
Toluene feedstock volatility compresses margin structures across all three purity tiers while simultaneously forcing geographic reconfiguration of manufacturing assets toward integrated petrochemical corridors. This dual pressure mechanism widens spreads between pharmaceutical-grade and industrial-grade quotations while rewarding producers with captive benzene supply.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical grades from standard technical-grade volumes. Contract-based long-term offtake dominates high-purity supply to parenteral drug manufacturers, with price differentiation anchored in USP/EP/JP certification status and residual benzaldehyde testing depth. Cost compression in industrial solvent tiers intensifies as EPA VOC thresholds constrain formulation demand. Personal care multinationals exhibit lowest price sensitivity due to reformulation switching costs, while agrochemical blenders drive hardest bargain negotiations on technical-grade spot purchases.
Supply Chain Analysis
Contract-manufacturing concentration in benzoyl alcohol rests on LANXESS and Merck KGaA anchoring European pharmaceutical-grade capacity alongside Gujarat Alkalies and Hubei Greenhome in Asian technical-grade production. Raw material dependencies draw from toluene oxidation streams, benzaldehyde hydrogenation catalysts, and specialty packaging for injectable-grade containment. Single-source vulnerability concentrates in Jiangsu and Zhejiang provinces where domestic API expansion concentrates excipient demand. Distribution runs through direct sales agreements for pharmaceutical grades and specialty chemical distributors serving regional personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward multinational personal care formulators consolidating vendor panels around dual-source pharmaceutical-grade suppliers, fragmenting mid-tier regional brands into distributor-dependent procurement.
For Market Incumbents: Pre-empt phenoxyethanol substitution in cosmetic preservative applications by accelerating REACH-registered toxicity dossier expansions into fragrance-grade applications. Deepen backward integration into toluene supply through offtake agreements with European refinery operators, securing feedstock cost stability against aromatic hydrocarbon volatility. Anchor multi-pharmacopeia certification investments to defend margin pools from emerging Indian CDSCO-registered competitors.
For New Entrants and Emerging Players: Build out injectable-grade capacity targeting India's underpenetrated pharmaceutical formulation sector where CDSCO registration creates compliance entry barriers for established suppliers. Prioritize continuous flow hydrogenation technology adoption to compress batch cycle times and offset incumbent scale advantages. Pursue direct-to-formulator e-procurement channels disintermediating traditional chemical distributor networks serving mid-tier regional personal care brands.
For Investors and Strategic Acquirers: REACH authorization timeline reshapes the acquisition landscape toward targets with established SVHC compliance dossiers and residual impurity control capabilities. Long-term viability favors pharmaceutical-grade specialists with demonstrated parenteral drug compatibility testing infrastructure over industrial solvent volume producers facing EPA emission constraints. Monitor ECHA candidate list expansion velocity as inflection signal for downstream reformulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Supply | Captive feedstock access insulates LANXESS from aromatic hydrocarbon price swings. |
| Continuous Flow Hydrogenation Adoption | Process intensification compresses batch release timelines for Merck KGaA's pharmaceutical grades. |
| Multi-Pharmacopeia Certification Investment | USP/EP/JP alignment unlocks parenteral drug manufacturer procurement consolidation. |
| Direct-to-Formulator E-Procurement Platform | Digital distribution disintermediates specialty chemical networks serving mid-tier brands. |
| CDSCO Registration Pathway Development | Indian regulatory compliance creates whitespace for injectable-grade market entry. |
Study Parameters
A spread of perspectives from pharmaceutical procurement managers, cosmetic formulator R&D directors, specialty chemical distributors, and regulatory affairs specialists converged on the working assumptions underpinning demand trajectories. Primary fieldwork combined structured interviews with downstream end-users and upstream production planners, validated against customs trade data, ECHA registration databases, SEC chemical sector filings, and pharmacopeial monograph revision notices. Bottom-up volume builds across grade tiers and application segments were triangulated with top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling consumption intensity by pharmaceutical formulation expansion, personal care manufacturing scaling, and agrochemical emulsion system requirements. Segmentation dimensions included purity grade tier, end-use industry vertical, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted growth coefficients applied to baseline consumption estimates, with feedstock cost pass-through assumptions and certification investment cycles incorporated as industry-specific forecast inputs.
Stress conditions across toluene price volatility bands, REACH authorization timeline delays, and EPA VOC threshold stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding biologic stabilizer substitution velocity and pharmacopeial harmonization progress. Quarterly review of ECHA candidate list expansions, NMPA GB standard revisions, and CDSCO registration approval rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
United States Construction Chemicals Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Triethylenediamine Market
Chemicals
Spirodiclofen Market
Chemicals
White Phosphorus Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Stimulation Materials Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Global N-Butanol Market
Chemicals
Acetic Ether Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Superplasticizer Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Glyoxal Market