
 Phenylethyl Market | 2026-2036
Phenylethyl Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylethyl Market Outlook
Natural-derived phenylethyl alcohol is repositioning synthetic benzene-based production economics across fragrance and cosmetic supply chains. Evonik Industries AG leverages biotechnology platforms to produce high-purity phenylethyl alcohol through fermentation, reducing petrochemical dependency. Kunshan Odowell anchors Asia-Pacific supply with integrated aroma chemical manufacturing. Koninklijke DSM NV competes through specialized yeast-strain R&D that improves conversion yields.
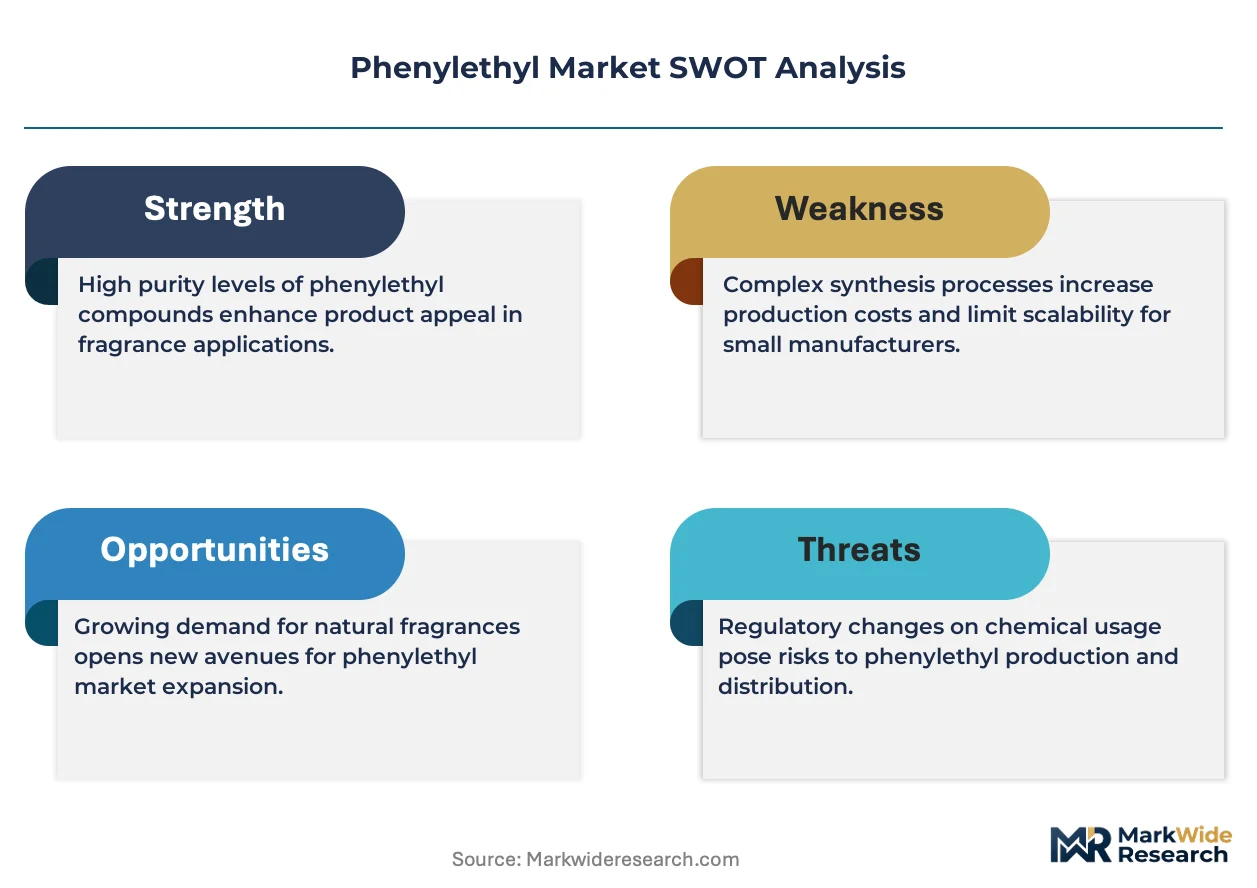
Phenylethyl compounds encompass alcohols, acetates, amines, and malonates derived from benzene or biotechnological pathways, typically specified at purity levels exceeding 99% for cosmetic and pharmaceutical applications. These molecules serve as rose-scent precursors, flavoring agents, and active pharmaceutical intermediates. Phenylethyl alcohol dominates volume through its established fragrance application base, while phenylethyl amine captures expanding pharmaceutical-grade demand for central nervous system research compounds. Food-grade phenylethyl acetate generates concentrated margin pools from artisanal chocolate and beverage flavoring segments where natural-label positioning commands premium positioning.
REACH in Europe, FDA food additive regulations in the United States, and China's GB standards for cosmetic raw materials collectively shape purity benchmarks, labeling requirements, and market access conditions for phenylethyl producers. Compliance costs favor manufacturers with in-house analytical capabilities and documented supply chain transparency. Stakeholders must monitor regulatory divergence between biotech-derived and petrochemical-derived phenylethyl classification frameworks, as this distinction increasingly determines qualification for natural-label product segments.
Market Dynamics
Biotechnology-based phenylethyl production is compressing synthetic benzene economics while REACH purity mandates in Europe force reformulation across fragrance supply chains. This structural shift favors producers with fermentation platforms and documented supply chain transparency.
Growth Catalysts
- Fermentation Technology Maturation:Biotech-derived phenylethyl alcohol achieves cosmetic-grade purity exceeding 99% without petrochemical feedstocks. Fragrance houses in France and Germany are qualifying these sources for natural-label positioning.
- REACH Compliance Thresholds:ECHA's tightening specifications for cosmetic-grade phenylethyl compounds are disqualifying low-purity imports. European formulators are consolidating supplier relationships around certified producers with in-house analytical capabilities.
- China's Fermentation Scale-Up:Domestic producers in Jiangsu and Zhejiang provinces are expanding bioreactor capacity for phenylethyl alcohol. This supply concentration is reducing import dependency for Asia-Pacific fragrance manufacturing.
Market Restraints
- Benzene Feedstock Volatility:Synthetic phenylethyl production remains exposed to benzene price fluctuations from petrochemical complexes. This input cost instability compresses margins for traditional manufacturers without biotech alternatives.
- China Supply Concentration:Fermentation-based phenylethyl capacity clusters among domestic producers in eastern provinces. Geographic supply density creates vulnerability to regional energy policy shifts or environmental enforcement actions.
- Technical Purity Ceiling:Food-grade phenylethyl acetate requires impurity profiles below 0.1% for artisanal chocolate applications. Conventional synthetic routes struggle to meet this specification without prohibitively expensive distillation sequences.
Strategic Opportunities
- India Flavor Expansion:FSSAI's evolving standards for natural-identical flavor compounds create qualification pathways for biotech-derived phenylethyl acetate. Domestic confectionery and beverage producers are seeking compliant suppliers for premium product lines.
- Pharmaceutical-Grade Amines:Phenylethyl amine derivatives for central nervous system research command purity premiums above fragrance applications. Contract manufacturers with cGMP fermentation capabilities can access this specialized demand pool.
- EU Green Deal Alignment:Biotech-derived phenylethyl qualifies for sustainability-linked procurement criteria under CSRD disclosure requirements. Cosmetic brands with net-zero commitments are prioritizing these supply sources in vendor selection.
Industry Challenges
- Fermentation Scale-Up Expertise:Industrial biotech talent capable of optimizing yeast strain conversion yields remains concentrated among specialized research institutions. Manufacturers face recruitment competition from broader synthetic biology sectors.
- Dual Certification Timelines:Producers seeking both REACH registration and FDA food additive status must navigate sequential review processes. Documentation requirements for biotech-derived versus synthetic origin create additional analytical burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylethyl Market |
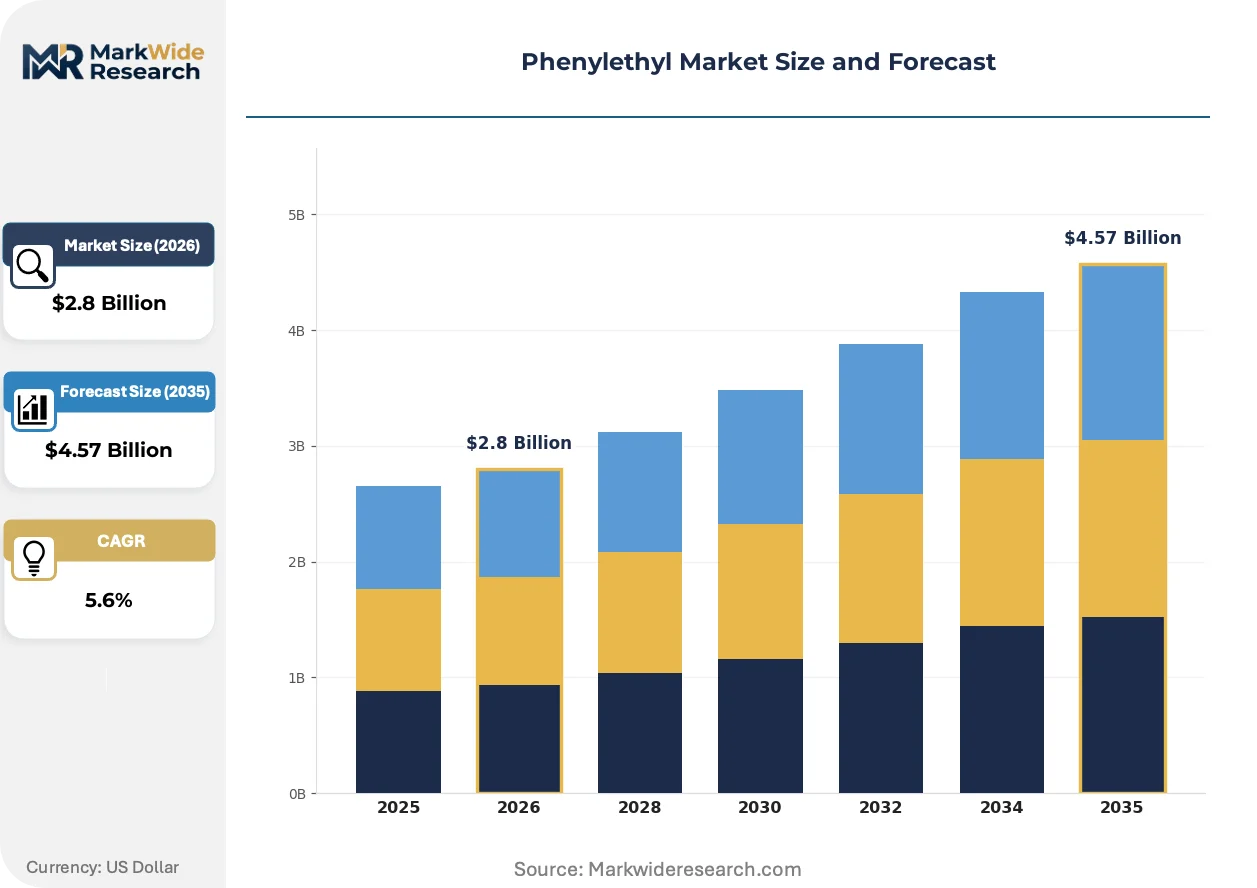
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenylethyl Alcohol, Phenylethyl Acetate, Phenylethyl Amine, Phenylethyl Malonate End Use Industry: Cosmetics, Food & Beverages, Pharmaceutical, Fragrance Grade: Food Grade, Cosmetic Grade, Industrial Grade, Pharmaceutical Grade Packaging Type: Drums, Bottles, Totes, Bulk Containers |
| Companies Covered | Harmony Organics Private Ltd, Kunshan Odowell, Evonik Industries AG, Becton, Dickinson and Company, Actylis, Koninklijke DSM NV, KDAC Pvt. Ltd, Penta Manufacturing Company, Yinghai (Cangzhou) Aroma Chemical Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylethyl Market Strategic Shifts
Continuous processing technology is displacing batch fermentation in phenylethyl manufacturing, while regulatory frameworks increasingly differentiate biotech-derived from petrochemical-origin classifications. These forces are compressing traditional supplier economics.
Continuous fermentation systems with integrated membrane separation are unifying upstream production and downstream purification into single-unit operations. Mid-scale aroma chemical manufacturers in Germany and the Netherlands are retrofitting existing facilities with these configurations. This technology convergence is reducing capital intensity per kilogram of phenylethyl alcohol while improving batch-to-batch consistency for cosmetic-grade specifications.
REACH's 2023 updates to cosmetic ingredient dossier requirements are mandating enhanced impurity profiling for phenylethyl compounds across all purity grades. European fragrance compounders are demanding comprehensive substance identity data from suppliers. Small-scale importers without analytical infrastructure are exiting the market, consolidating volume around integrated producers with in-house GC-MS and NMR capabilities.
Artisanal chocolate and craft beverage producers are specifying natural-label phenylethyl acetate in direct procurement contracts with fermentation specialists. Traditional distribution through commodity chemical brokers is fragmenting as end-users seek supply chain transparency for consumer-facing sustainability claims. This channel disintermediation is most visible in France, Belgium, and Switzerland where premium food manufacturers maintain direct supplier relationships.
Phenylethyl Market Segmentation
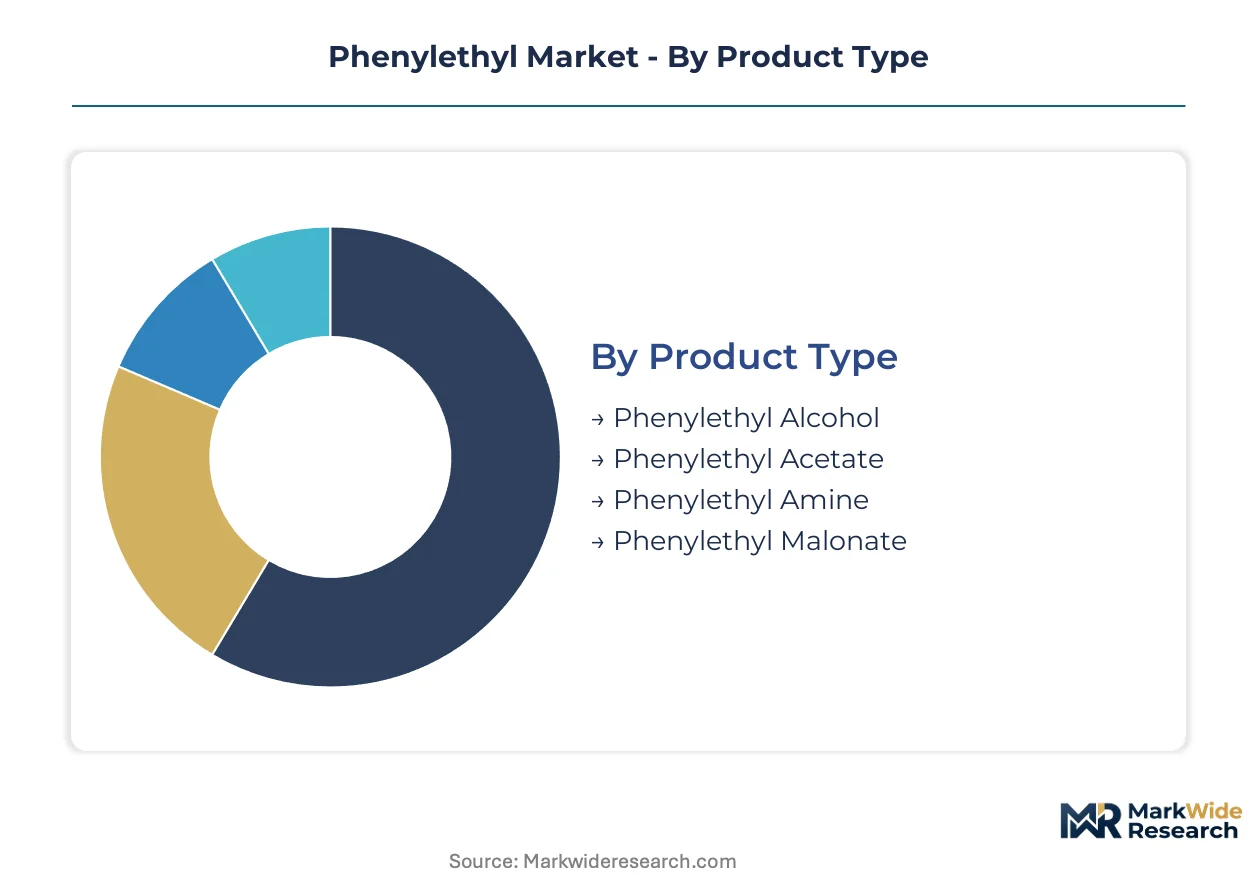
Phenylethyl market segmentation reveals divergent value capture across standalone fragrance precursors versus embedded pharmaceutical intermediates. Grade and packaging specifications determine qualification pathways for REACH-compliant cosmetics versus FDA-regulated food applications.
Product Type:
Standalone phenylethyl alcohol dominates fragrance formulation as a finished ingredient, while phenylethyl amine embeds into multi-step pharmaceutical synthesis with distinct purity requirements.
- Phenylethyl Alcohol:Rose-scent precursor specified above 99% purity for cosmetic applications. Demand concentrates in France and Germany where fragrance houses qualify fermentation-derived sources for natural-label positioning under REACH cosmetic dossier requirements.
- Phenylethyl Acetate:Flavoring agent with honey-rose notes for artisanal chocolate and beverage segments. Swiss and Belgian premium food manufacturers specify natural-label grades in direct procurement contracts, bypassing traditional chemical distribution channels.
- Phenylethyl Amine:Central nervous system research intermediate requiring pharmaceutical-grade documentation.
- Phenylethyl Malonate:Specialty ester for fine fragrance compounding with extended volatility profiles.
Phenylethyl alcohol leads volumes today; phenylethyl amine is gaining share fastest.
End Use Industry:
Cost tier differentiation separates commodity fragrance volume from premium pharmaceutical margin pools, with food-grade applications commanding intermediate positioning through natural-label premiums.
- Cosmetics:Skin care and personal care formulations requiring REACH-registered phenylethyl alcohol with comprehensive impurity profiling. European formulators consolidate supplier relationships around certified producers with in-house GC-MS and NMR capabilities.
- Fragrance:Fine perfume manufacturing in Grasse, France and Geneva, Switzerland drives specification-grade demand. Biotech-derived sources qualify for sustainability-linked procurement under EU Green Deal alignment criteria.
- Food & Beverages:Artisanal chocolate and craft beverage segments with FSSAI-evolving standards in India creating new qualification pathways.
- Pharmaceutical:cGMP fermentation requirements for central nervous system research compounds with purity premiums above fragrance applications.
Fragrance captures the largest volume share; pharmaceutical applications deliver the steepest expansion trajectory.
Grade:
Application maturity determines grade specification intensity, with cosmetic and pharmaceutical segments demanding documented supply chain transparency absent from industrial applications.
- Cosmetic Grade:Phenylethyl alcohol exceeding 99% purity with enhanced impurity profiling mandated by ECHA's updated cosmetic ingredient dossier requirements. Small-scale importers without analytical infrastructure are exiting the European market.
- Pharmaceutical Grade:cGMP documentation for phenylethyl amine derivatives with batch-to-batch consistency requirements. Contract manufacturers with fermentation capabilities access specialized demand pools for central nervous system research.
- Food Grade:Phenylethyl acetate requiring impurity profiles below 0.1% for artisanal chocolate applications.
- Industrial Grade:Lower-specification material for non-consumer chemical synthesis.
Cosmetic grade leads current volumes; pharmaceutical grade is climbing the fastest.
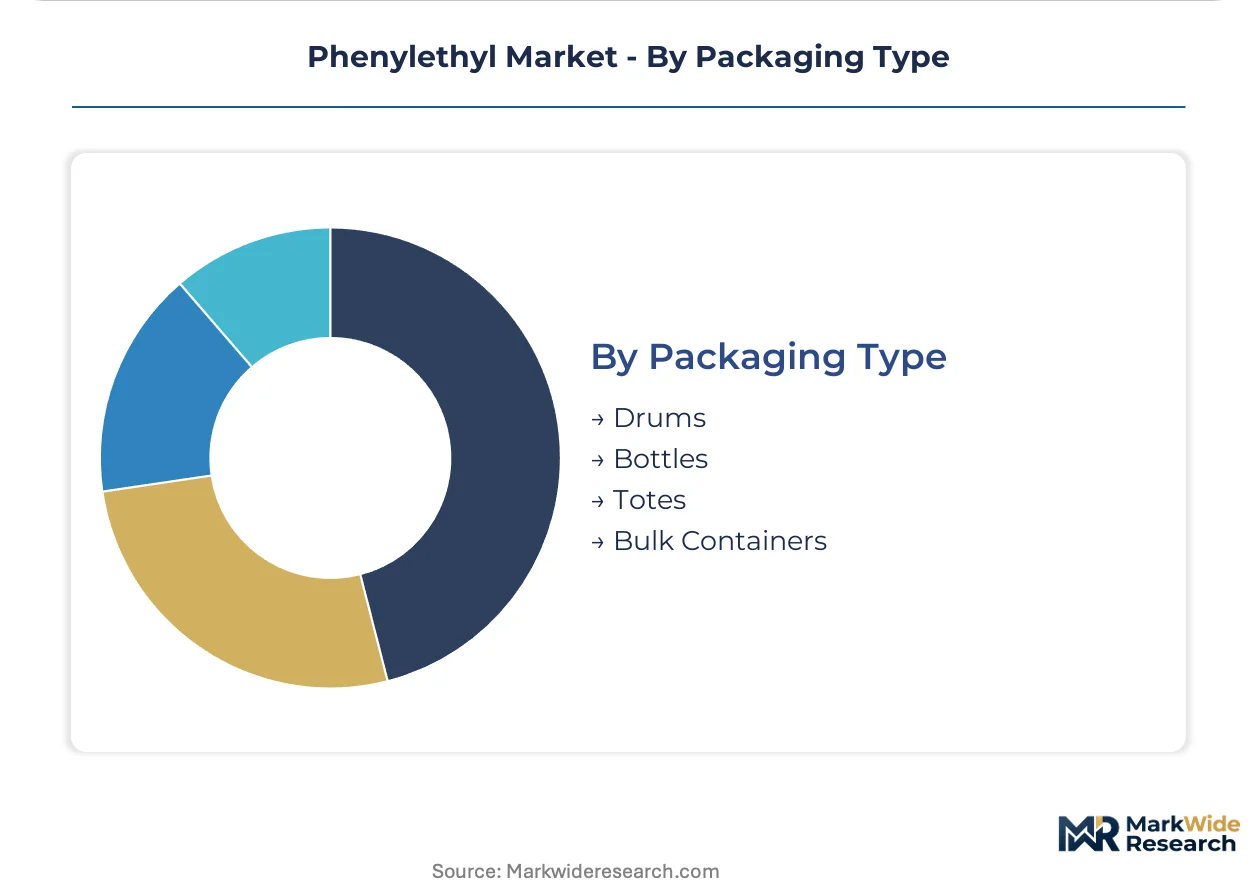
Packaging Type:
Supply concentration in China's Jiangsu and Zhejiang provinces shapes bulk container economics, while artisanal end-users fragment demand toward smaller-format packaging with traceability documentation.
- Drums:Standard 200-liter format for mid-scale fragrance compounders in Germany and the Netherlands. Continuous fermentation retrofits reduce per-kilogram handling costs while maintaining batch consistency.
- Bulk Containers:ISO tank configurations for integrated aroma chemical manufacturers with direct pipeline connections to downstream formulation facilities. China's domestic producers scale fermentation capacity for regional Asia-Pacific supply.
- Bottles:Small-format packaging for laboratory and sampling quantities.
- Totes:Intermediate bulk containers for specialty chemical distributors.
Bulk containers dominate volume throughput; bottles are expanding most quickly in premium direct-procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse, France anchors fragrance-grade phenylethyl demand through its historic perfume compounder concentration. Jiangsu and Zhejiang provinces in China dominate fermentation-based supply expansion. Switzerland and Germany maintain specification leadership through REACH-aligned cosmetic manufacturing.
China
Domestic producers in Jiangsu and Zhejiang provinces scale bioreactor capacity for phenylethyl alcohol to reduce import dependency. GB standards for cosmetic raw materials enforce purity documentation that favors integrated manufacturers with captive analytical laboratories. Yinghai and other fermentation specialists concentrate production in Cangzhou and surrounding industrial zones to serve Asia-Pacific fragrance formulators.
France
Fine perfume manufacturing in Grasse drives specification-grade phenylethyl alcohol demand for natural-label positioning. ECHA's REACH cosmetic dossier requirements mandate comprehensive impurity profiling that disqualifies uncertified imports. Fragrance houses consolidate supplier relationships around producers with documented fermentation-derived supply chains and in-house GC-MS capabilities.
Germany
Mid-scale aroma chemical manufacturers in the Rhineland retrofit facilities with continuous fermentation systems integrating membrane separation. The EU Green Deal's sustainability-linked procurement criteria under CSRD disclosure requirements prioritize biotech-derived phenylethyl for cosmetic brands with net-zero commitments. Evonik Industries anchors biotechnology platform development through specialized yeast-strain optimization.
Switzerland
Premium food manufacturers in Geneva and Basel specify natural-label phenylethyl acetate through direct procurement contracts bypassing commodity brokers. Swissmedic-aligned pharmaceutical documentation requirements create qualification pathways for cGMP-grade phenylethyl amine derivatives. Artisanal chocolate and craft beverage segments command impurity profiles below 0.1% that strain conventional synthetic economics.
India
FSSAI's evolving standards for natural-identical flavor compounds open qualification pathways for biotech-derived phenylethyl acetate in domestic confectionery and beverage production. Maharashtra and Gujarat-based fragrance compounders seek compliant suppliers for premium product lines serving urban consumer markets. Import substitution policies accelerate local fermentation capacity planning among specialty chemical distributors.
Phenylethyl Market Competitive Environment
Global majors compete with regional champions across technology platforms and regulatory certification depth. Market structure tilts toward integrated producers with simultaneous REACH registration and FDA food additive status, compressing margins for single-certification competitors. Three archetypes dominate: biotechnology platform operators, integrated aroma chemical manufacturers with backward feedstock control, and specialized fermentation contractors serving pharmaceutical-grade demand. Capacity expansion and dual-certification timeline acceleration represent the dominant competitive moves as small-scale importers exit under ECHA's tightened purity mandates.
Among biotechnology-focused operators, Evonik Industries AG and Koninklijke DSM NV exemplify platform-scale fermentation capabilities. Kunshan Odowell anchors Asia-Pacific supply integration. Harmony Organics Private Ltd occupies a position within India-based specialty chemical manufacturing. These named entities represent archetype concentration rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Harmony Organics Private Ltd |
| Kunshan Odowell |
| Evonik Industries AG |
| Becton, Dickinson and Company |
| Actylis |
| Koninklijke DSM NV |
| KDAC Pvt. Ltd |
| Penta Manufacturing Company |
| Yinghai (Cangzhou) Aroma Chemical Company Ltd |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-registered cosmetic phenylethyl and uncertified industrial material manifests simultaneously in three-tier pricing stratification and supplier consolidation around integrated manufacturers with captive analytical laboratories. Fermentation-derived natural-label grades command premium positioning through documented supply chain transparency, while synthetic benzene-based material faces margin compression from volatile petrochemical feedstock costs.
Pricing Analysis
Input-cost pass-through from benzene volatility disproportionately burdens synthetic phenylethyl manufacturers without biotech alternatives, compressing margins in commodity fragrance applications. Pricing stratifies across premium fermentation-derived cosmetic grades, mid-tier standard industrial material, and economy synthetic benzene-based supply. Downward pricing pressure intensifies in synthetic routes as China's domestic fermentation scale-up reduces import dependency for Asia-Pacific formulators. Small-scale fragrance compounders in Germany and the Netherlands exhibit highest price sensitivity, while Swiss pharmaceutical contractors absorb premiums for cGMP-certified phenylethyl amine derivatives.
Supply Chain Analysis
REACH and FDA dual-certification gating consolidates viable supplier pools around integrated producers with simultaneous ECHA registration and food additive status, excluding small-scale importers lacking analytical infrastructure. Supply concentrates in China's Jiangsu and Zhejiang provinces, with secondary fermentation capacity emerging in India's Maharashtra and Gujarat states. Raw material dependencies include glucose feedstocks for yeast-strain fermentation, specialized membrane separation equipment, and pharmaceutical-grade packaging materials. Single-source vulnerability intensifies around China's eastern province cluster given regional energy policy exposure. Distribution runs through direct procurement contracts with premium food manufacturers in Switzerland and Belgium, bypassing traditional commodity chemical brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenylethyl demand is maturing toward quality-tier bifurcation as fragrance houses and pharmaceutical contractors consolidate procurement around certified fermentation-derived supply with comprehensive impurity documentation.
For Market Incumbents: To counter margin erosion from China's domestic fermentation scale-up, accelerate backward integration into yeast-strain R&D capabilities and secure dual REACH-FDA certification timelines ahead of ECHA's tightening cosmetic dossier requirements. Prioritize capacity expansion in India's emerging qualification pathways under FSSAI's evolving natural-identical flavor standards. For New Entrants and Emerging Players: Begin with India's artisanal chocolate and craft beverage segments where FSSAI standards create qualification white-space for biotech-derived phenylethyl acetate. Target Maharashtra-based confectionery producers seeking import substitution for premium product lines. Establish direct procurement relationships bypassing commodity distribution channels to capture natural-label premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where small-scale importers exit under REACH purity mandates, creating acquisition opportunities for mid-cap fermentation specialists with existing analytical infrastructure. Long-term viability favors platform-scale biotech operators with simultaneous cosmetic and pharmaceutical-grade capabilities. Watch for inflection in ECHA enforcement intensity against uncertified imports as the signal for accelerated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Yeast-Strain Optimization Investment | Evonik and DSM compete through specialized R&D improving fermentation conversion yields for cosmetic-grade purity. |
| Continuous Fermentation Retrofit | German and Dutch manufacturers reduce capital intensity per kilogram while improving batch-to-batch consistency. |
| Dual-Certification Acceleration | Producers navigate sequential ECHA and FDA review processes to access natural-label and pharmaceutical demand pools. |
| Direct Procurement Channel Development | Swiss and Belgian premium food manufacturers bypass commodity brokers for supply chain transparency. |
| India Fermentation Capacity Planning | Maharashtra and Gujarat distributors respond to import substitution policies and FSSAI qualification pathways. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fragrance compounders, pharmaceutical contract manufacturers, fermentation plant managers, and specialty chemical procurement leads with secondary validation from ECHA cosmetic dossier filings, FDA food additive registrations, customs trade data, and SEC disclosures from listed aroma chemical producers. Bottom-up volume modeling across grade tiers and end-use segments triangulated against top-down market sizing from production capacity assessments.
Segment-weighting approaches distributed value and volume across product type, grade specification, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from growth rate convergence modeling across these segments throughout the forecast period. Industry-specific forecast inputs included yeast-strain conversion yield improvements, REACH compliance timeline assumptions, and China's domestic fermentation capacity expansion trajectories.
Several conditions sit outside the modeled scope, including abrupt ECHA enforcement actions against uncertified imports, regional energy policy disruptions affecting China's Jiangsu and Zhejiang production clusters, and breakthrough synthetic biology platforms displacing conventional fermentation economics. A model refresh is warranted upon material change in dual-certification timeline completion rates or FSSAI finalization of natural-identical flavor compound standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Fluoroboric Acid Market
Chemicals
Chlorosilane Market
Chemicals
Global Glycol Ether Market
Chemicals
Malic Acid Market
Chemicals
Acetophenone Market
Chemicals
Trimethylamine Market
Chemicals
Global Thiophene Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Methanol Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Hydrogenated Dimer Acid Market