
 Calcium Carbide Market | 2026-2036
Calcium Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Carbide Market Intelligence
Steel mill procurement is pivoting toward fewer, larger acetylene suppliers with captive carbide sources. SA Calcium Carbide leverages its integrated lime-carbide operations to secure long-term metallurgy contracts. Xinjiang Zhongtai Chemical Co., Ltd. dominates western Chinese supply through coal-field proximity. Alzchem Group AG differentiates via reagent-grade purity for European chemical synthesis.
Calcium carbide is an inorganic compound produced by electrothermal reduction of lime and coke in arc furnaces at approximately 2200°C, yielding a grey-black crystalline material containing 75–80% CaC₂ by weight. Its primary commercial purpose is acetylene generation through hydrolysis, serving as a feedstock for metal cutting, chemical synthesis, and PVC precursor routes. Chemical grade material commands premium positioning due to stringent purity thresholds for acetylene-derived solvents. Standard grade occupies volume leadership in steel desulfurization where cost efficiency outweighs specification stringency. Granule form is gaining preference over lump in automated acetylene generator systems across metallurgy sector customers.
EPA emissions guidelines for carbide furnace operations shape US plant upgrade cycles and capital allocation. REACH registration requirements in Europe constrain small-volume importers while favoring established producers with dossier completion. China's MEE enforcement of dual carbon goals is pressuring coal-dependent carbide clusters toward energy-efficiency retrofits. Stakeholders must monitor regulatory divergence between EU carbon border adjustments and developing-market enforcement gaps to align capacity investments with compliant demand nodes.
Market Dynamics
Steel mill consolidation into fewer, larger oxy-acetylene operators is compressing supplier tiers and rewarding carbide producers with captive lime kilns and generator integration. This buyer-side concentration is reshaping contract structures toward decade-long offtake agreements with embedded price corridors.
Growth Catalysts
- China's MEE dual carbon enforcement:Energy-efficiency mandates are accelerating furnace retrofits in Ningxia and Inner Mongolia, tightening supply and lifting margins for compliant producers.
- Acetylene-to-solvent chemical synthesis:Pharmaceutical and agrochemical manufacturers are expanding acetylene-derived intermediate procurement for high-purity reagent applications.
- US IRA clean manufacturing credits:Domestic carbide producers qualifying for Section 45X credits are reinvesting in arc furnace modernization to capture incentive value.
Market Restraints
- Coke and anthracite input volatility:Carbon electrode and reducing agent costs swing with coking coal futures, compressing margin visibility for non-integrated operators.
- Ningxia supply cluster concentration:Over half of Chinese export volume originates from coal-carbide integrated complexes vulnerable to coordinated environmental shutdowns.
- Acetylene substitution by propane in metal cutting:Propane-oxygen systems are displacing acetylene in lower-precision steel fabrication, eroding standard-grade carbide demand.
Strategic Opportunities
- Southeast Asia steel capacity expansion:Vietnamese and Indonesian greenfield mills lack captive carbide supply, creating import-dependent demand pockets for integrated exporters.
- Granule form automation compatibility:Automated acetylene generator systems favor consistent-size granules over lump material, enabling premium positioning for sizing-capable producers.
- EU CBAM carbon border adjustment:Embedded emissions accounting favors carbide from low-carbon power grids, advantaging producers with hydroelectric or nuclear furnace energy.
Industry Challenges
- GB standard certification timelines:China's tightening purity specifications require third-party laboratory verification cycles that delay export clearance by 6-12 weeks.
- Arc furnace electrode replacement capex:Soderberg electrode rebuilds and pre-baked anode upgrades demand capital commitments exceeding $15 million per furnace line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Carbide Market |
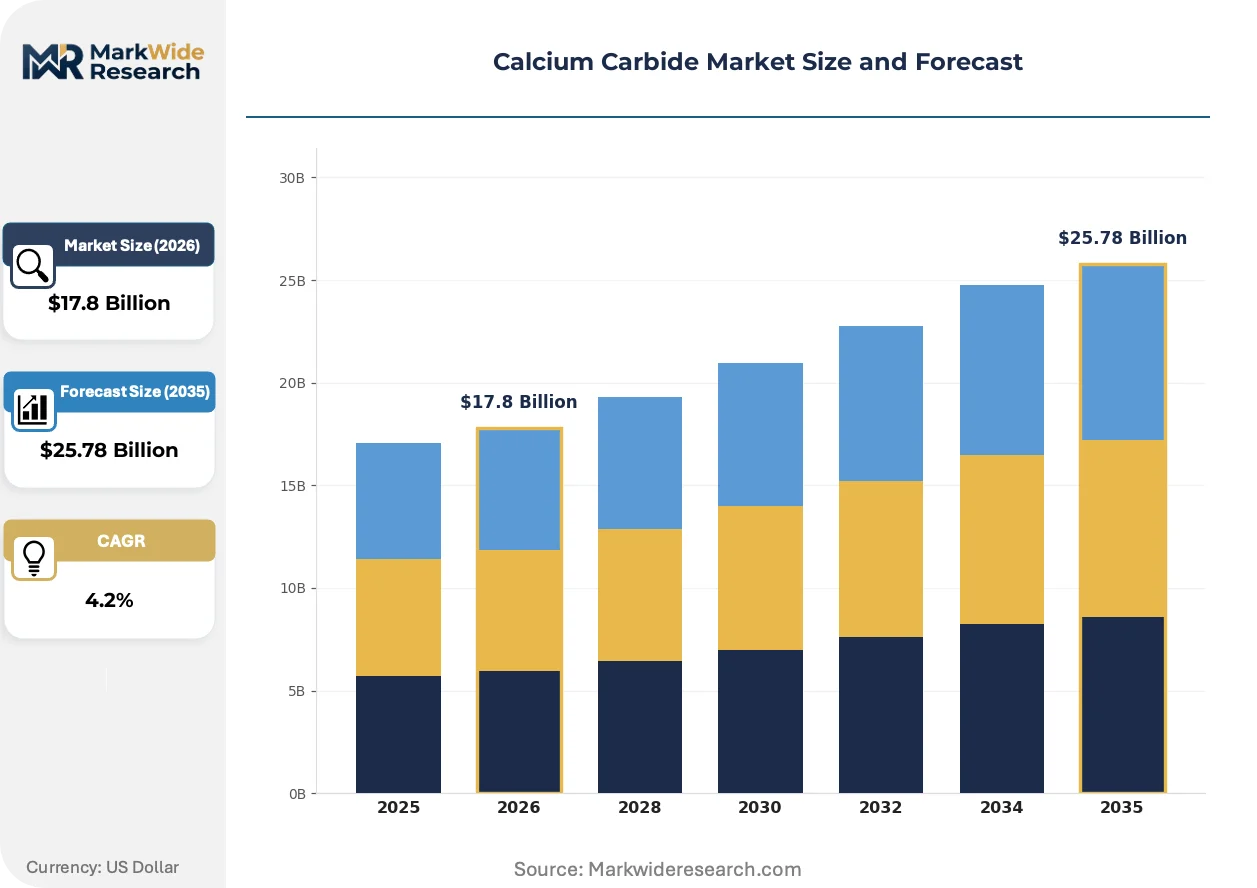
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $25.78 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Chemical Grade, Technical Grade, Reagent Grade, Food Grade Application: Acetylene Production, Steel Manufacturing, Desulfurization, Calcium Cyanamide Production, Soil Amendment End User Industry: Metallurgy Sector, Agriculture Sector, Chemical Industry, Construction Materials, Fertilizer Production Form: Granules, Lump, Powder, Pellets, Compact Form |
| Companies Covered | Linde AG, SA Calcium Carbide, Carbide Industries LLC, Xinjiang Zhongtai Chemical Co., Ltd., Ningxia Jinyuyuan Chemical Group Co., Ltd., Inner Mongolia Baiyanhu Chemical Co Ltd, The Dow Chemical Company, DCM Shriram Ltd., Alzchem Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Carbide Market Strategic Shifts & Innovations
Automation in acetylene generation and carbon accounting transparency are compressing traditional supply arrangements. Producers are racing to digitize furnace operations and secure low-carbon power purchase agreements ahead of regulatory phase-ins.
Closed-loop carbide slag recycling systems are consolidating waste management economics for integrated lime-carbide operations. Steel mills with captive acetylene plants are adopting these systems fastest, locking in zero-landfill certifications that satisfy ESG-linked lending covenants. The technology is consolidating supplier-customer relationships into sole-source arrangements with embedded service contracts.
REACH registration dossier requirements are tightening chemical-grade purity documentation for European acetylene derivative manufacturers. ECHA enforcement of updated substance identity protocols is forcing importers to commission full analytical characterization of carbide lots. Specialty chemical end-uses in Germany and the Netherlands are absorbing these compliance costs through indexed contract adjustments.
Steel service centers are unbundling acetylene cylinder maintenance from carbide supply agreements, shifting toward direct generator ownership. Large fabrication shops in Texas and Ohio are installing automated carbide-to-acetylene systems that bypass traditional gas distributor markups. This behavior is most visible in North American heavy equipment repair chains seeking to control cutting gas unit economics.
Calcium Carbide Market Segmentation
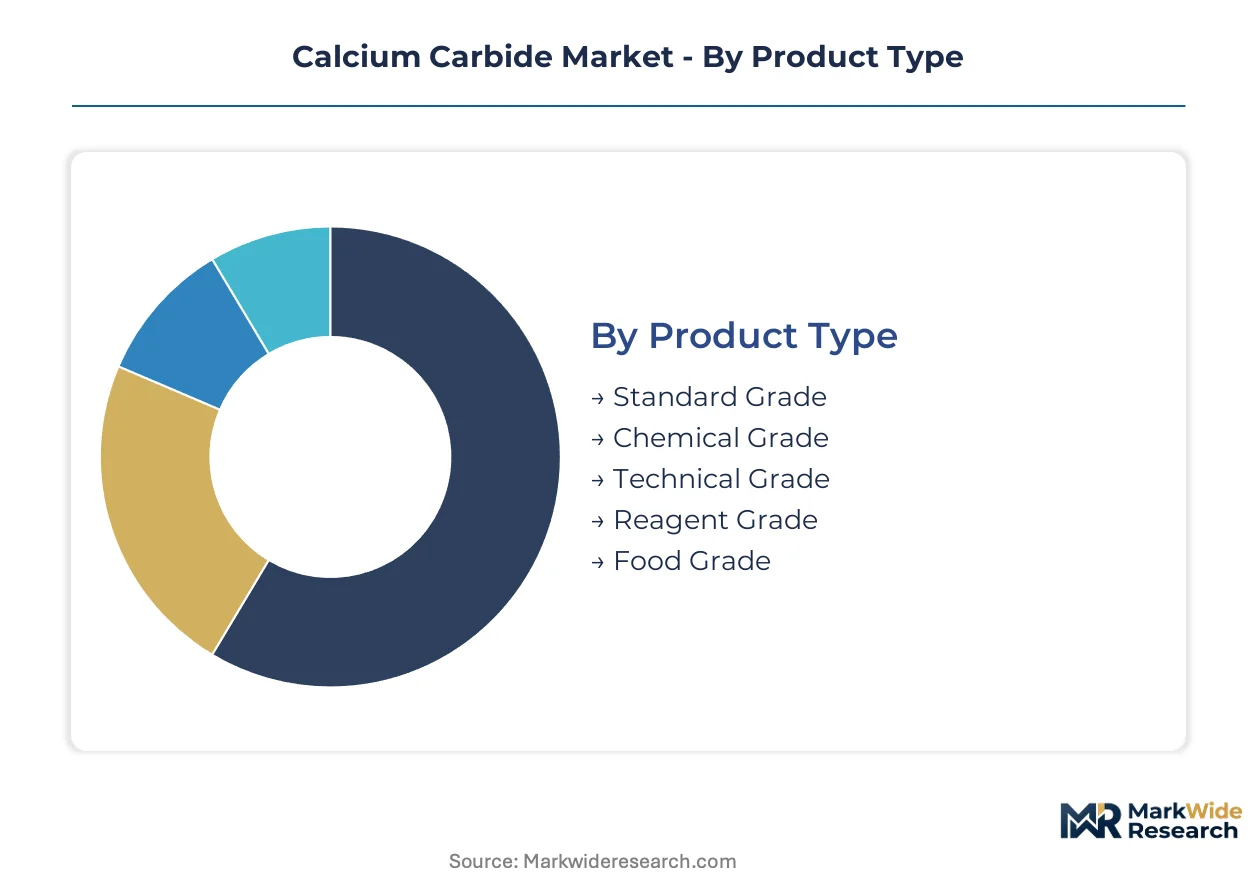
Calcium carbide segmentation reflects divergent capital requirements across purity tiers and form factors. Furnace economics and end-use specifications create distinct investment profiles that shape producer positioning and capacity allocation decisions.
Product Type:
Standard grade demands the heaviest furnace infrastructure with lower purity tolerance, while reagent grade requires analytical instrumentation and clean-room packaging investments.
- Standard Grade:Contains 75-80% CaC₂ by weight with controlled sulfur and phosphorus limits. Steel desulfurization operations in Ningxia and Inner Mongolia absorb volume through long-term metallurgy contracts where cost efficiency dominates procurement criteria.
- Chemical Grade:Stringent purity thresholds above 80% CaC₂ with trace metal specifications for acetylene-derived solvent synthesis. Pharmaceutical and agrochemical manufacturers in Germany and the Netherlands pay premiums for REACH-compliant documentation and lot-specific analytical certificates.
- Technical Grade:Intermediate specification for industrial acetylene generation without reagent-grade documentation burden.
- Reagent Grade:Ultra-high purity for laboratory and analytical applications requiring sub-ppm impurity controls.
- Food Grade:Specialized purification for residual acetylene applications in food processing equipment sterilization.
Most installed capacity flows through Standard Grade. Expansion is steepest in Chemical Grade.
Application:
Volume concentration varies by customer scale, with integrated steel mills driving batch sizes and contract structures.
- Acetylene Production:Hydrolysis reaction yields fuel gas for metal cutting and chemical feedstock. Automated generator systems at Texas and Ohio fabrication shops favor consistent granule supply with direct carbide-to-acetylene integration bypassing distributor markups.
- Steel Manufacturing:Oxy-acetylene cutting applications demand reliable thermal performance. Vietnamese and Indonesian greenfield mills without captive carbide supply create import-dependent demand pockets for exporters with generator integration capabilities.
- Desulfurization:Molten iron sulfur reduction in blast furnace operations.
- Calcium Cyanamide Production:Nitrogen fixation precursor for fertilizer manufacturing.
- Soil Amendment:Agricultural pH correction and calcium supplementation in acidic soils.
Steel Manufacturing commands the largest contract volumes. Acetylene Production is gaining share fastest.
End User Industry:
Margin structure follows certification burden, with regulated industries absorbing compliance costs through indexed pricing.
- Metallurgy Sector:Integrated steel mills and service centers with captive acetylene plants. Closed-loop carbide slag recycling systems lock in zero-landfill certifications that satisfy ESG-linked lending covenants at North American heavy equipment repair chains.
- Chemical Industry:Acetylene derivative manufacturers requiring full REACH dossier completion. ECHA enforcement of updated substance identity protocols forces importers to commission analytical characterization, consolidating supply toward established producers with laboratory infrastructure.
- Agriculture Sector:Calcium cyanamide and soil amendment distributors.
- Construction Materials:Carbide slag utilization in cement and aggregate applications.
- Fertilizer Production:Nitrogen compound manufacturing with regional formulation requirements.
Metallurgy Sector anchors current revenue. Chemical Industry shows the steepest expansion trajectory.
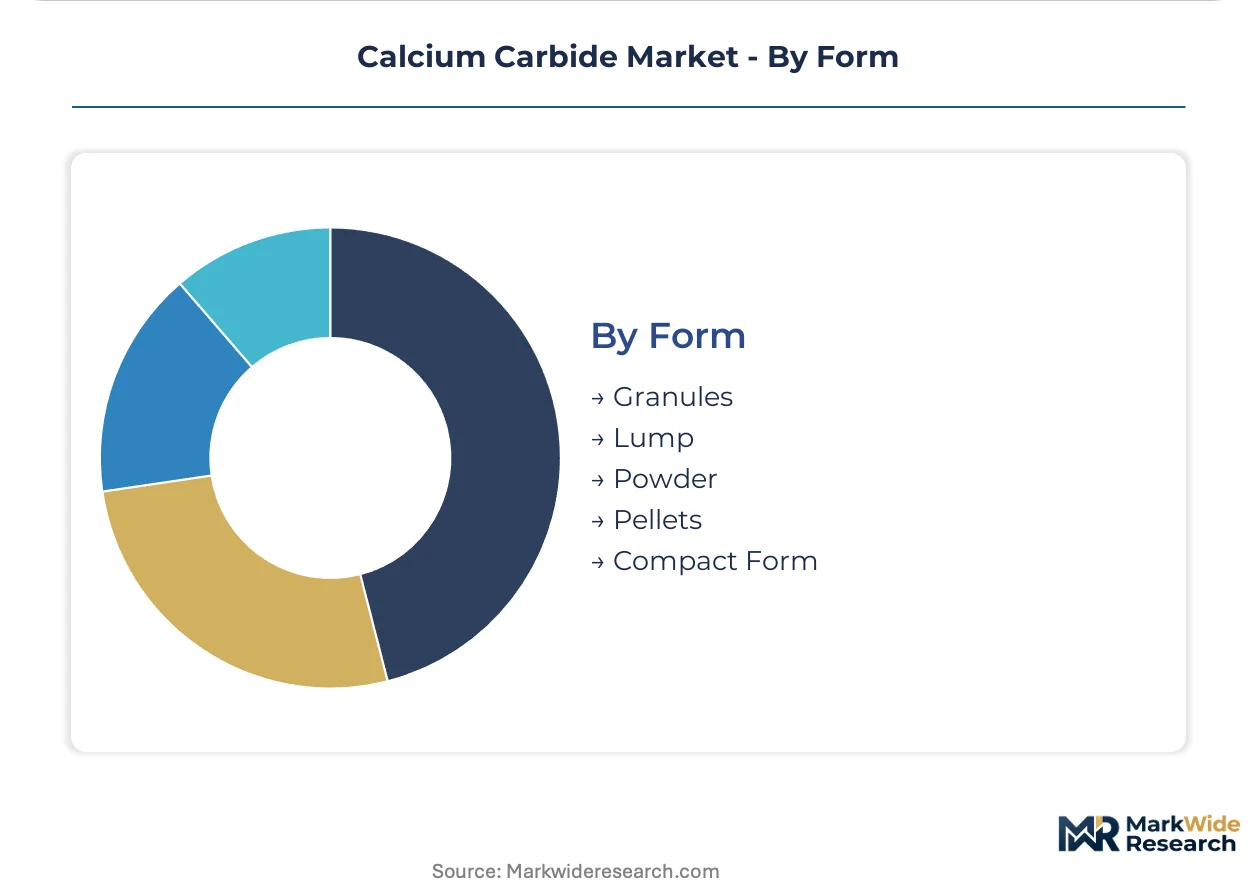
Form:
Automation compatibility is reshaping physical specification requirements across customer segments.
- Granules:Consistent sizing for automated acetylene generator systems. Steel service centers in Texas and Ohio installing direct generator ownership prefer granule feedstock for reliable flow characteristics and reduced handling labor.
- Lump:Traditional form for manual generator loading and legacy equipment.
- Powder:Fine particle size for chemical synthesis reactions requiring rapid hydrolysis kinetics.
- Pellets:Compressed form for controlled dissolution rate applications.
- Compact Form:High-density briquettes for specialized transport and storage efficiency.
Lump form retains the largest installed equipment base. Granules are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningxia province dominates export volumes while the United States pursues furnace modernization through IRA incentives, creating divergent capital deployment trajectories across major producing regions.
China
Ningxia and Inner Mongolia host coal-calcium carbide integration clusters supplying over half of global export volume. MEE enforcement of dual carbon goals is pressuring these facilities toward energy-efficiency retrofits. Ningxia Jinyuyuan Chemical Group operates within this concentrated supply base where environmental compliance timelines now dictate operational continuity.
United States
Steel service centers in Texas and Ohio are installing automated acetylene generator systems that bypass traditional gas distributor markups. EPA emissions guidelines for carbide furnace operations shape plant upgrade cycles and capital allocation decisions. Carbide Industries LLC maintains operations within this regulatory framework where Section 45X clean manufacturing credits incentivize arc furnace modernization.
Germany
REACH registration requirements constrain small-volume importers while favoring established producers with dossier completion. ECHA enforcement of updated substance identity protocols forces analytical characterization of carbide lots. Alzchem Group AG anchors European supply from this regulatory environment where reagent-grade purity commands premium positioning.
South Africa
SA Calcium Carbide leverages integrated lime-carbide operations to secure long-term metallurgy contracts across sub-Saharan steel markets. The country's national environmental regulator shapes emission control standards for electrothermal reduction facilities. Operations concentrate in industrial zones serving mining sector oxy-acetylene cutting demand.
India
DCM Shriram Ltd. participates in a market where steel desulfurization applications absorb standard-grade volume through cost-sensitive procurement. BIS standards for industrial chemical purity are tightening product specifications across domestic and export markets. Capacity clusters in western and northern states supply regional metallurgy and chemical synthesis end-uses.
Calcium Carbide Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated coal-carbide operators with captive energy inputs, lime-carbide specialists with slag recycling capabilities, and chemical-grade purifiers with analytical laboratory infrastructure. Capacity expansion and furnace modernization represent the dominant competitive moves as producers position for carbon-accounting transparency.
Within the integrated operator tier, Xinjiang Zhongtai Chemical Co., Ltd. and Ningxia Jinyuyuan Chemical Group Co., Ltd. exemplify the coal-field proximity model that dominates Chinese supply. SA Calcium Carbide occupies a position among lime-carbide specialists with captive raw material integration. These three entities represent distinct geographic and structural archetypes without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Linde AG |
| SA Calcium Carbide |
| Carbide Industries LLC |
| Xinjiang Zhongtai Chemical Co., Ltd. |
| Ningxia Jinyuyuan Chemical Group Co., Ltd. |
| Inner Mongolia Baiyanhu Chemical Co Ltd |
| The Dow Chemical Company |
| DCM Shriram Ltd. |
| Alzchem Group AG |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in Ningxia province anchor supply discipline through coal-field integration, translating captive energy inputs into pricing power that resists standard-grade commoditization. This ownership pattern compresses margin volatility for integrated operators while forcing non-integrated competitors toward chemical-grade premiums or granule form automation investments.
Pricing Analysis
Capacity additions in Inner Mongolia are reshaping price floors for standard-grade material bound for steel desulfurization. Pricing stratifies across reagent-grade, chemical-grade, and standard tiers based on purity certification and lot-specific analytical documentation. Cost compression in standard-grade runs through coke and anthracite input volatility, with Vietnamese greenfield mills exhibiting highest price sensitivity and German pharmaceutical manufacturers showing least sensitivity due to REACH compliance pass-through.
Supply Chain Analysis
REACH registration and GB standard certification gating constrain importer participation while consolidating supply toward dossier-complete producers with laboratory infrastructure. Manufacturing concentrates in China, South Africa, and Germany, with raw material dependencies spanning metallurgical coke, high-calcium lime, and carbon electrodes. Single-source vulnerability concentrates in Ningxia coal-carbide clusters vulnerable to coordinated MEE enforcement actions. Distribution runs through long-term offtake agreements with embedded price corridors rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
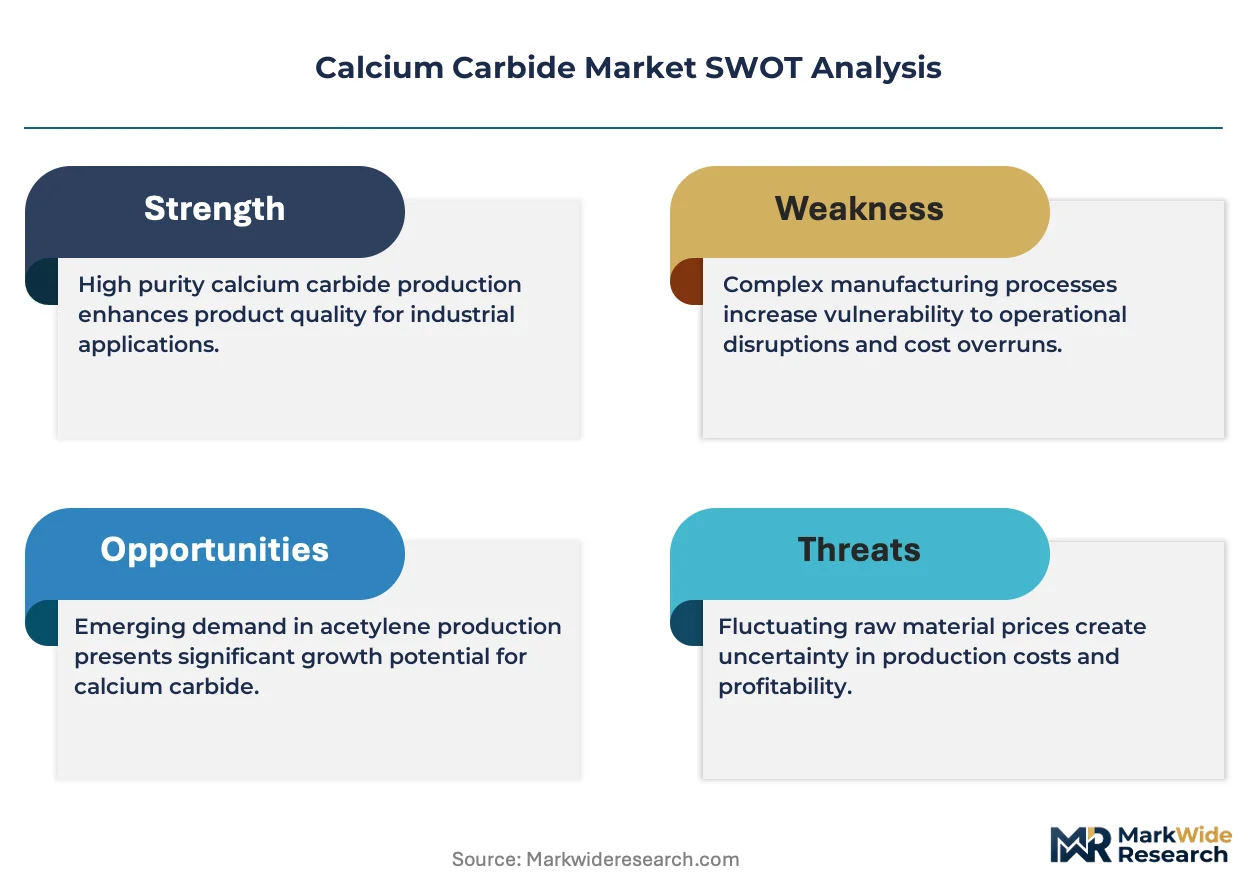
This market reads as a geographic-arbitrage play between EU carbon border adjustment exposure and developing-market enforcement gaps, with embedded emissions accounting advantaging producers on low-carbon power grids.
For Market Incumbents: Deploy furnace modernization credits to capture Section 45X value ahead of competitor retrofit cycles. Secure decade-long metallurgy contracts with captive lime kiln integration to defend against propane-oxygen substitution in lower-precision steel fabrication. Accelerate closed-loop carbide slag recycling certifications to satisfy ESG-linked lending covenants at North American heavy equipment repair chains. For New Entrants and Emerging Players: Launch via automated granule supply partnerships with Vietnamese and Indonesian greenfield mills lacking captive carbide infrastructure. Target chemical-grade purity segments where REACH dossier completion barriers limit importer competition. Penetrate through direct generator ownership models that bypass traditional gas distributor markups at Texas and Ohio fabrication shops. For Investors and Strategic Acquirers: Valuations sit cheapest among lime-carbide specialists with slag recycling capabilities and sub-Saharan market access. Long-term viability hinges on carbon-accounting transparency and low-carbon power purchase agreements ahead of EU CBAM phase-ins. Watch for MEE enforcement intensity in Ningxia as inflection indicator for Chinese export volume availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Lime Supply | SA Calcium Carbide secures metallurgy contract renewals through slag recycling economics. |
| Granule Form Capacity Expansion | Automated generator compatibility commands premium positioning at Ohio steel service centers. |
| REACH Dossier Completion Investment | Alzchem Group AG locks in pharmaceutical manufacturer loyalty through analytical certification. |
| Long-term Supply Agreement with Greenfield Mills | Vietnamese steel capacity expansion creates import-dependent demand pockets for integrated exporters. |
| Joint Venture for Low-carbon Power Procurement | EU CBAM embedded emissions accounting favors hydroelectric or nuclear furnace energy sourcing. |
Research Approach
Direct dialogue with carbide plant managers, steel procurement leads at integrated mills, acetylene generator system engineers, and REACH compliance consultants grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, MEE enforcement bulletins, ECHA substance identity protocols, and SEC filings of publicly traded chemical conglomerates. Bottom-up capacity modeling and top-down demand segmentation were triangulated against import-export flow analysis.
Top-down macroeconomic drivers were reconciled with bottom-up furnace-level production estimates across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, form factor, and regional production hub. CAGRs were derived from weighted capacity expansion schedules and demand elasticity coefficients. Forecast inputs incorporated MEE dual carbon enforcement timelines and IRA Section 45X credit qualification thresholds.
Several conditions sit outside the modeled scope, including unannounced environmental shutdowns in Ningxia clusters and abrupt acetylene substitution acceleration by propane-oxygen systems. Forecasts reflect assumptions about regulatory enforcement consistency and raw material input cost stability. A model refresh is warranted upon material change in EU CBAM implementation timelines or MEE inspection intensity in coal-carbide integrated regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Menadione Market
Chemicals
Scouring Agents Market
Chemicals
Selenium Sulfide Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
5 Dinitroaniline Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Sodium Hydride Market
Chemicals
Periodic Acid Market
Chemicals
Power Plant Chemicals Market
Chemicals
Pyrogallol Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Laboratory Chemicals Market
Chemicals
Glyoxylic Acid Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Calcium Methoxide Market